
 India Automotive Parts Magnesium Die Casting Market | 2026-2036
India Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Parts Magnesium Die Casting Market Foresight
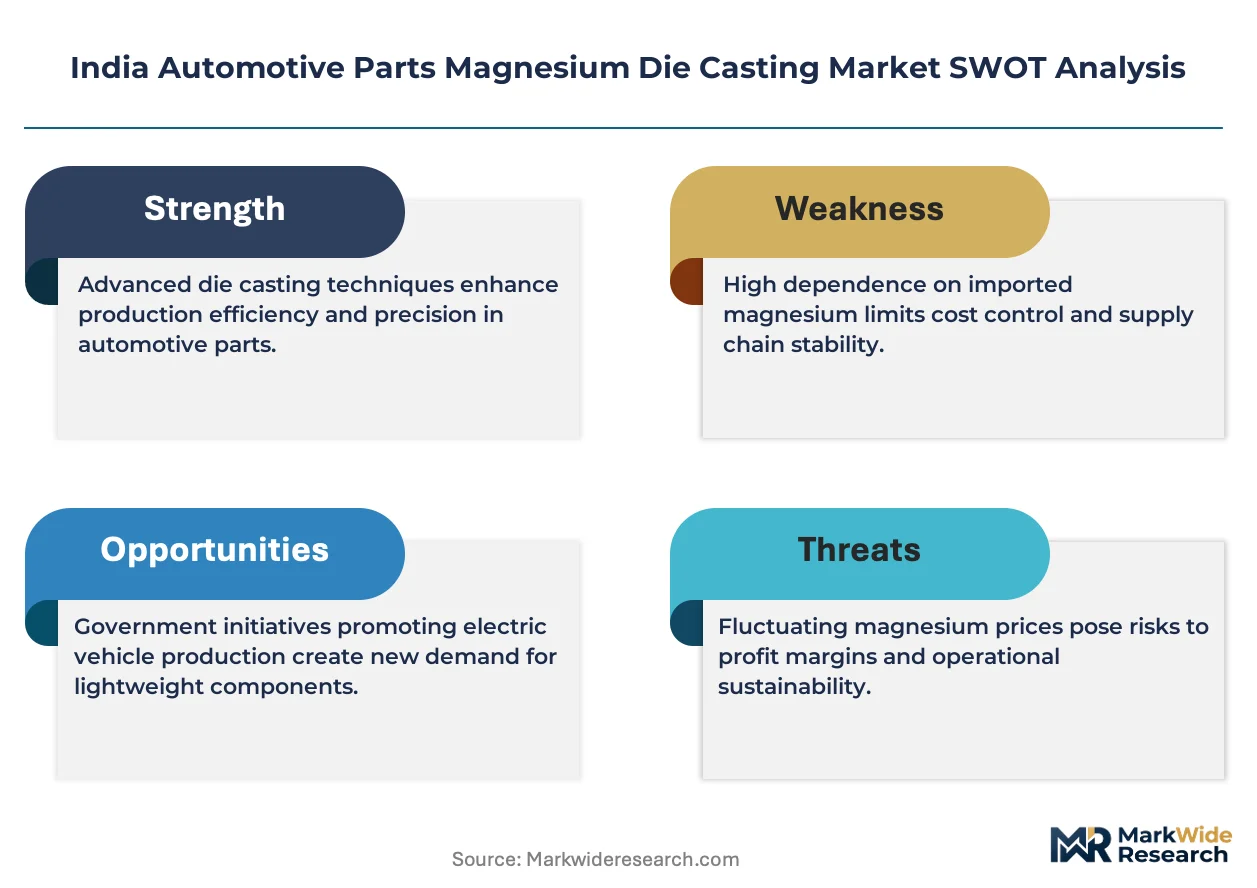
Asset-light leasing models for die-casting cells are rewriting competitive entry dynamics for mid-tier suppliers in India. Shiloh Industries Inc leverages its North American tooling expertise to serve transplanted OEM programs near Pune. Sandhar Group anchors its position through captive machining and assembly operations tied to two-wheeler OEMs. Sundaram Clayton Ltd dominates southern India with high-volume transmission case production for domestic passenger vehicle platforms.
Automotive parts magnesium die casting is a net-shape manufacturing process where molten magnesium alloys, typically AZ91D or AM60B, are injected into hardened steel dies under pressures exceeding 1,000 bar to produce lightweight structural components. The primary purpose is mass reduction in vehicle assemblies, with magnesium offering a density one-quarter that of steel and superior damping characteristics for noise-vibration-harshness management. Engine components and transmission parts command the deepest margin pools due to tolerance-critical geometries and thermal loading requirements that limit supplier qualification. Electric vehicle applications represent the fastest-expanding segment as manufacturers pursue battery tray and motor housing designs that offset lithium-ion pack mass.
BIS certification under IS 15947 and ARAI homologation protocols govern material grades, dimensional stability, and corrosion resistance for magnesium castings sold into Indian vehicle programs. The Ministry of Heavy Industries' PLI scheme for automotive and auto components is channeling capital toward advanced die-casting capacity that meets these standards. Stakeholders must monitor how BIS alignment with UN ECE regulations on magnesium flammability reshapes product liability and export qualification timelines.
Market Dynamics
India's automotive parts magnesium die casting market is being fundamentally restructured by the Ministry of Heavy Industries' PLI scheme, which channels capital toward advanced die-casting capacity that meets BIS crashworthiness and recyclability standards for electric vehicle battery housings.
Growth Catalysts
- PLI scheme capital allocation:The Ministry of Heavy Industries' production-linked incentive scheme is directing investment toward high-pressure die-casting cells capable of producing BIS-certified AZ91D and AM60B alloy components for OEM battery tray programs.
- Tamil Nadu industrial corridor concentration:The Chennai-Aurangabad manufacturing belt hosts dense clustering of transplanted OEM assembly plants and captive tier-1 networks, creating localized demand pull for magnesium structural castings.
- Electric vehicle platform expansion:Domestic and multinational automakers are scaling battery electric vehicle architectures that require lightweight motor housings and transmission cases to offset lithium-ion pack mass penalties.
Market Restraints
- Magnesium ingot price volatility:Primary magnesium supply concentration in Shanxi and Ningxia provinces of China exposes Indian die-casters to raw material cost swings and currency fluctuation risks.
- BIS-ARAI dual certification friction:The Bureau of Indian Standards' IS 15947 dimensional stability requirements and Automotive Research Association of India homologation protocols create extended qualification timelines for new supplier entry.
- Aluminum alloy substitution pressure:A380 and AlSi10Mg aluminum die-casting grades compete for transmission case and engine bracket applications where corrosion resistance and established recycling infrastructure outweigh magnesium's density advantage.
Strategic Opportunities
- Gujarat-Sanand corridor expansion:The western India automotive manufacturing belt remains underpenetrated by qualified magnesium die-casting suppliers despite hosting major passenger vehicle and two-wheeler OEM facilities.
- Thixomolding technology convergence:Semi-solid metal processing combined with in-situ melting feedstock systems enables thinner-wall casting designs for electric vehicle motor housings with reduced porosity defects.
- Asset-light leasing channel innovation:Die-casting cell leasing models allow mid-tier suppliers to access high-pressure equipment without full capital ownership, lowering barrier to entry for BIS-certified production.
Industry Challenges
- High-pressure die-casting process engineering talent scarcity:Qualified technicians capable of managing 1,000+ bar injection pressures and real-time porosity control remain concentrated among incumbent tier-1 suppliers.
- UN ECE magnesium flammability alignment complexity:BIS consideration of United Nations Economic Commission for Europe fire-safety standards for magnesium components creates unresolved product liability exposure and export qualification uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Parts Magnesium Die Casting Market |
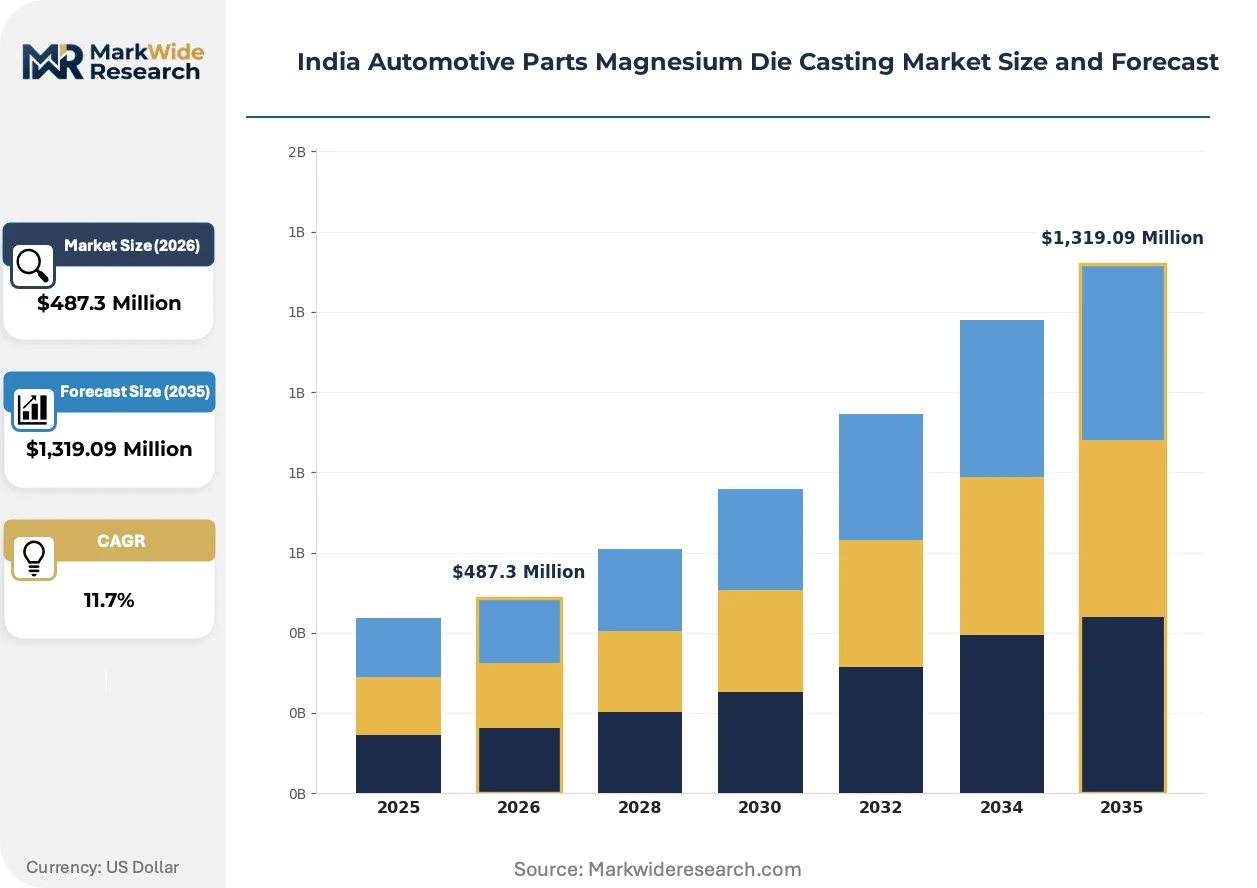
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Chassis Parts, Body Parts Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Two-Wheelers End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Technology: High-Pressure Die Casting, Vacuum Die Casting, Gravity Die Casting, Squeeze Casting |
| Companies Covered | Magic Precision, Shiloh Industries Inc, Ryobi Die Casting, JPM Group, George Fischer Ltd, Pace Industries, Dynacast International, Sandhar Group, Sundaram Clayton Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Parts Magnesium Die Casting Market Shifts & Advancements
Digital process control systems and alloy formulation advances are compressing development cycles for magnesium structural components while regulatory pressure on vehicle mass reduction intensifies specification requirements across Indian OEM platforms.
Thixomolding semi-solid metal processing is virtualizing traditional high-pressure die-casting workflows for electric vehicle motor housing production. Maruti Suzuki and Tata Motors procurement teams are qualifying thixomolded AZ91D components for 2025 platform launches. This technology is virtualizing conventional molten-metal injection sequences by enabling lower-temperature processing with reduced solidification shrinkage and extended die life.
BIS alignment with UN ECE R100 electric vehicle safety regulations is tightening material traceability and flammability testing protocols for magnesium battery tray castings. The Automotive Research Association of India is mandating batch-level chemical certification and thermal runaway propagation resistance documentation. Tier-1 suppliers serving Mahindra Electric and Ather Energy programs face compressed homologation timelines to meet these dual-standard requirements.
Buyer consolidation among domestic OEMs is compressing supplier qualification cycles and favoring vertically integrated die-casting-to-machining operations. Mahindra & Mahindra and Bajaj Auto are consolidating magnesium component awards to suppliers with captive CNC finishing and leak-testing capabilities. This pattern is most visible in Tamil Nadu, where Sundaram Clayton and Sandhar Group anchor southern India supply relationships through integrated transmission case production.
India Automotive Parts Magnesium Die Casting Market Segmentation
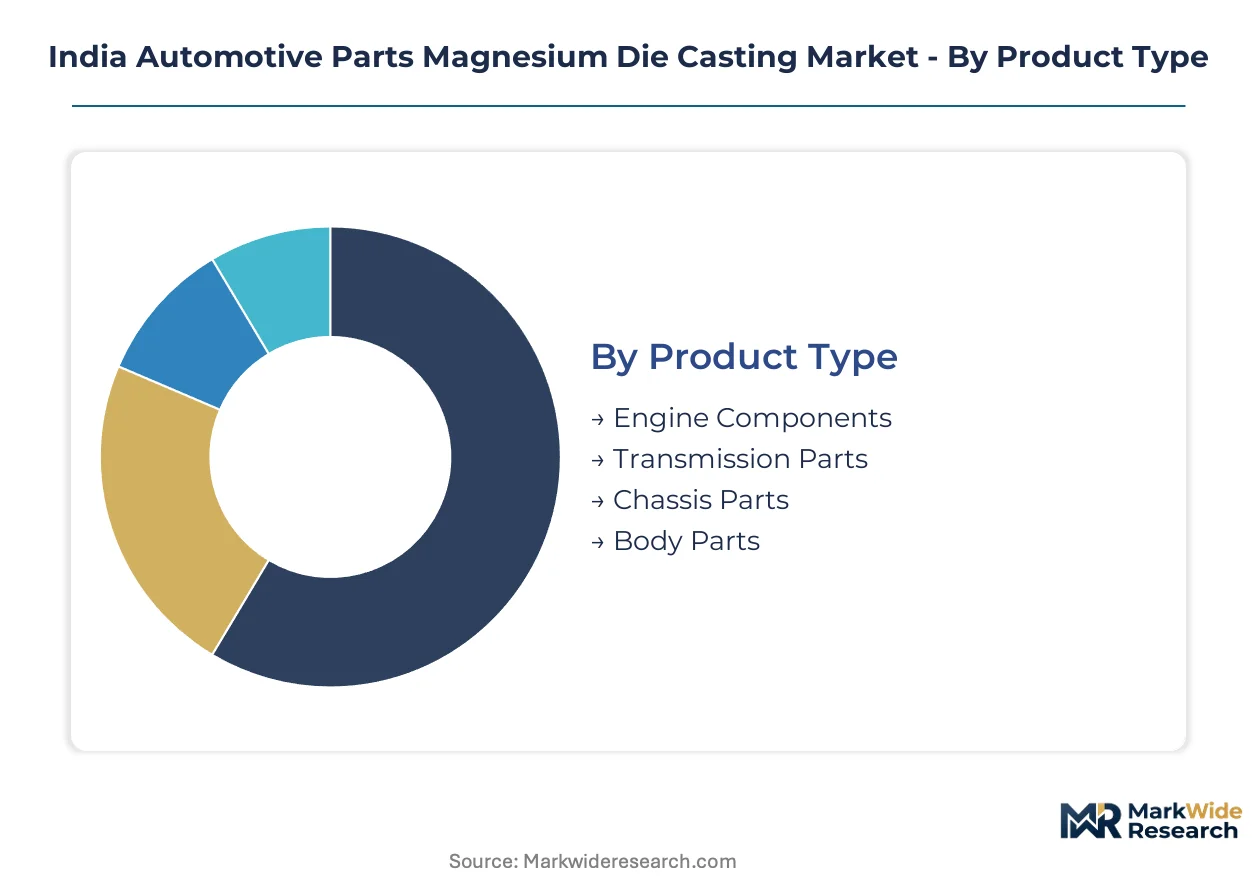
Magnesium die casting suppliers in India configure production cells around distinct technical specifications and buyer requirements. Segment boundaries determine alloy selection, tooling investment, and certification pathways for BIS-ARAI compliance.
Product Type:
Cost tier differentiation across product categories reflects tolerance complexity and thermal loading demands on magnesium alloys.
- Engine Components:Piston housings, valve covers, and oil pans require AZ91D alloy grades with high creep resistance under combustion temperatures. Maruti Suzuki and Tata Motors source these from Tamil Nadu-based suppliers for domestic passenger vehicle platforms, with BIS IS 15947 dimensional stability certification extending qualification cycles.
- Transmission Parts:Clutch housings and gearbox casings dominate volume throughput due to standardized geometries across multiple OEM programs. Sundaram Clayton anchors southern India supply relationships through integrated high-pressure die casting and CNC finishing operations for these components.
- Chassis Parts:Steering column brackets and suspension mounts utilize AM60B alloys for improved ductility under impact loading.
- Body Parts:Door inner panels and roof frames remain niche applications limited by surface finish requirements and corrosion protection costs.
Transmission parts hold installed capacity. Engine components are rotating up the share rankings.
Application:
End-use vehicle categories impose divergent mass reduction priorities and volume scale requirements on magnesium casting programs.
- Electric Vehicles:Battery tray castings and motor housings represent the steepest expansion trajectory as manufacturers offset lithium-ion pack mass penalties. BIS alignment with UN ECE R100 flammability protocols is compressing homologation timelines for suppliers serving Mahindra Electric and Ather Energy.
- Passenger Vehicles:Transmission cases and engine brackets command the deepest margin pools due to tolerance-critical geometries and established recycling infrastructure. The Chennai-Aurangabad corridor concentrates demand from transplanted OEM assembly plants and captive tier-1 networks.
- Commercial Vehicles:Cab structures and seat frames utilize magnesium for driver ergonomics and payload optimization.
- Two-Wheelers:Crankcases and wheel hubs drive high-volume production for cost-sensitive domestic programs.
Passenger vehicles anchor current revenue. Electric vehicles are climbing the fastest.
End User:
Customer type determines technical interface depth and capital commitment levels across the supply chain.
- OEMs:Direct procurement of battery housings and structural castings requires integrated design collaboration and crashworthiness validation. The Ministry of Heavy Industries' PLI scheme channels capital toward die-casting cells capable of meeting these direct specifications.
- Tier-1 Suppliers:Sandhar Group and similar intermediaries consolidate machining and assembly operations to serve two-wheeler OEMs with finished transmission components.
- Aftermarket Providers:Replacement engine covers and decorative trim pieces operate outside BIS homologation pathways.
- Vehicle Assemblers:Knockdown kit producers in Gujarat-Sanand corridor represent underpenetrated demand for qualified magnesium suppliers.
Tier-1 suppliers hold installed capacity. OEMs are rotating up the share rankings.
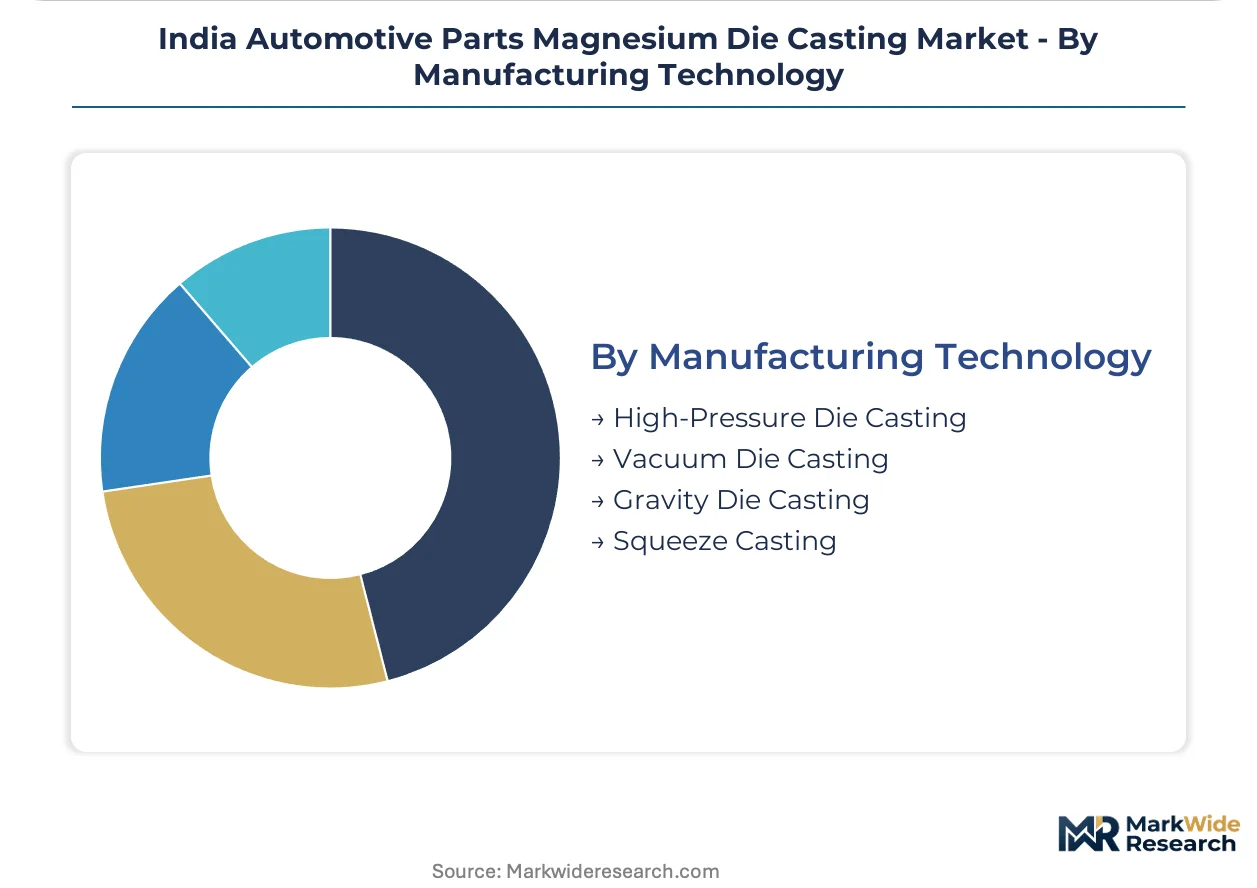
Manufacturing Technology:
Process selection governs porosity control, wall thickness capability, and equipment capital intensity for magnesium alloy processing.
- High-Pressure Die Casting:Injection pressures exceeding 1,000 bar enable thin-wall designs for transmission cases with cycle times under 60 seconds. Qualified technicians capable of real-time porosity management remain concentrated among incumbent tier-1 suppliers in Tamil Nadu.
- Vacuum Die Casting:Reduced gas entrapment supports heat-treatable AZ91D grades for safety-critical structural applications.
- Gravity Die Casting:Lower capital requirements suit prototype development and low-volume chassis brackets.
- Squeeze Casting:Solidification under mechanical pressure yields pore-free microstructures for high-integrity motor housings.
High-pressure die casting holds installed capacity. Vacuum die casting is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Heavy Industries' PLI scheme is channeling capital toward die-casting capacity in states with established automotive ecosystems. Tamil Nadu, Maharashtra, Gujarat, Karnataka, and Haryana concentrate qualified supplier networks and OEM assembly infrastructure.
Tamil Nadu
The Chennai-Aurangabad corridor hosts dense clustering of transplanted OEM plants and captive tier-1 networks. BIS certification under IS 15947 governs material grades for local production. Sundaram Clayton anchors southern supply relationships through integrated transmission case manufacturing in this belt.
Maharashtra
Pune-based OEM procurement teams are scaling magnesium adoption for battery housings and structural components. The state's industrial policy complements central PLI incentives for advanced die-casting cells. Shiloh Industries leverages North American tooling expertise to serve transplanted programs near this manufacturing hub.
Gujarat
The Sanand-Vadodara automotive belt remains underpenetrated by qualified magnesium suppliers despite hosting major passenger vehicle facilities. State-level infrastructure incentives target component vendor migration from established corridors. Die-casting cell leasing models are lowering entry barriers for mid-tier suppliers in this western expansion zone.
Karnataka
Bengaluru-centered EV startups and two-wheeler OEMs are generating demand for lightweight motor housings. The state's electronics manufacturing ecosystem supports digital process control system integration. Local suppliers face compressed homologation timelines under ARAI protocols for electric vehicle safety compliance.
Haryana
The Manesar-Bawal industrial zone concentrates two-wheeler and commercial vehicle component demand. Sandhar Group maintains captive machining and assembly operations tied to OEM programs in this northern belt. BIS-ARAI dual certification requirements extend supplier qualification cycles for new market entrants.
India Automotive Parts Magnesium Die Casting Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated tier-1 specialists and transplanted multinational tooling experts. Three archetypes dominate: integrated die-casting-to-machining operators, North American technology licensors, and asset-light regional fabricators. Competitive positioning depends on BIS certification speed and captive finishing capabilities. M&A activity targets qualified technicians and ARAI homologation track records.
Among multinational specialists, Shiloh Industries Inc and George Fischer Ltd exemplify technology-transfer strategies serving transplanted OEM platforms. Sandhar Group and Sundaram Clayton Ltd occupy positions as integrated domestic operators with captive machining networks. Magic Precision represents the precision-focused archetype addressing tolerance-critical geometries.
| Leading Market Players |
|---|
| Magic Precision |
| Shiloh Industries Inc |
| Ryobi Die Casting |
| JPM Group |
| George Fischer Ltd |
| Pace Industries |
| Dynacast International |
| Sandhar Group |
| Sundaram Clayton Ltd |
| Others |
Supply & Pricing Matrix
Magnesium ingot price volatility from Shanxi and Ningxia provinces determines both the spread between premium BIS-certified castings and economy-grade alternatives and the geographic clustering of die-casting capacity around Tamil Nadu's Chennai-Aurangabad corridor.
Pricing Analysis
Certification level under BIS IS 15947 creates the primary spread between qualified suppliers and unverified fabricators. Three-tier pricing structure across ARAI-homologated, BIS-certified, and uncertified grades reflects qualification timeline investments. Cost compression in economy-tier transmission cases is intensifying because aluminum A380 substitution threatens magnesium's density advantage. Two-wheeler OEMs exhibit highest price sensitivity; electric vehicle battery tray buyers prioritize flammability compliance over unit cost.
Supply Chain Analysis
Chinese export-control regimes on primary magnesium smelting technology constrain Indian die-casters' access to advanced ingot refining capabilities. Raw material flows draw from Shanxi province ingot producers, Ningxia alloy refiners, and domestic AZ91D formulators in Maharashtra. Single-source vulnerability concentrates in Chinese primary magnesium supply. Distribution runs through captive tier-1 networks anchored by Sundaram Clayton and Sandhar Group before reaching OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ministry of Heavy Industries' PLI scheme for automotive components accelerates magnesium adoption for electric vehicle battery housings, creating a regulatory-inflected growth window for qualified suppliers.
For Market Incumbents: Build ARAI homologation track records as a certification moat against transplanted multinational entrants. Deepen backward integration into captive CNC machining and leak-testing operations to defend margin position against aluminum substitution. Prioritize thixomolding capacity additions in Tamil Nadu to capture electric vehicle motor housing demand from Mahindra Electric and Ather Energy. For New Entrants and Emerging Players: The Gujarat-Sanand corridor's underpenetrated passenger vehicle facilities represent the most penetrable entry point for qualified magnesium suppliers. Asset-light die-casting cell leasing models lower capital barriers for BIS-certified production entry. Target two-wheeler crankcase programs through tier-1 relationships with Sandhar Group's machining networks. For Investors and Strategic Acquirers: BIS alignment with UN ECE R100 flammability protocols reshapes the acquisition landscape toward suppliers with batch-level chemical certification capabilities. Five-to-ten-year viability favors vertically integrated die-casting-to-machining operators with captive technician pools. Monitor ARAI homologation timeline compression as the signal indicating qualification bottleneck relaxation.| Strategic Initiative | Industry Significance |
|---|---|
| Thixomolding Technology Adoption | Maruti Suzuki and Tata Motors procurement teams qualify semi-solid AZ91D components for platform launches. |
| Backward Integration into Machining | Mahindra and Mahindra consolidates awards to suppliers with captive CNC finishing and leak-testing capabilities. |
| PLI Scheme Capacity Expansion | Ministry of Heavy Industries channels capital toward high-pressure die-casting cells meeting BIS crashworthiness standards. |
| Asset-Light Leasing Models | Mid-tier suppliers access 1,000+ bar injection equipment without full capital ownership in Gujarat-Sanand corridor. |
| ARAI-BIS Dual Certification Investment | Tier-1 suppliers serving electric vehicle programs face compressed homologation timelines under dual-standard requirements. |
Research Methodology
The analysis maps high-pressure die casting, vacuum die casting, gravity die casting, and squeeze casting sub-sectors, each validated through OEM platform engineers, tier-1 supplier procurement leads, ARAI certification officers, and die-casting cell equipment vendors. Primary interviews combined with secondary validation from BIS standards documentation, Ministry of Heavy Industries PLI scheme filings, vehicle production databases, and customs trade records. Bottom-up capacity assessments and top-down OEM procurement projections were triangulated.
Assumptions held fixed include BIS-ARAI dual certification requirements and PLI scheme capital allocation rates; variables tested included magnesium-aluminum price spreads and electric vehicle platform launch timing across the projection horizon. Segmentation dimensions modeled encompass product type, application vehicle class, manufacturing technology, and regional production cluster. CAGRs derived from installed capacity expansion rates and content-per-vehicle penetration curves. Forecast inputs incorporated thixomolding adoption rates and UN ECE flammability alignment timelines.
Practitioners should monitor magnesium ingot price volatility from Chinese provinces and BIS regulatory alignment with UN ECE standards for early signals of forecast deviation. Material shifts in PLI scheme funding allocation or primary magnesium supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Tow Bar Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
China Passenger Vehicles Lubricants Market