
 Timing Gear Market | 2026-2036
Timing Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Timing Gear Market Analysis
Powertrain electrification is fragmenting traditional timing gear architectures as hybrid engines require dual-mode synchronization systems. Gates Corporation leverages its polymer composite expertise to supply belt-driven solutions for downsized turbocharged engines. GKN PLC anchors its position through powder metallurgy capabilities that reduce component weight in high-RPM applications. The Timken Company differentiates via integrated bearing-gear assemblies that cut assembly steps for powertrain manufacturers.
Timing gears are precision-machined or sintered mechanical components that synchronize crankshaft and camshaft rotation through exact tooth profiles, typically manufactured to AGMA or DIN quality classes with surface hardness exceeding 58 HRC for wear resistance. Their primary purpose is maintaining valve timing accuracy across varying engine speeds and thermal loads. Chain drive systems dominate heavy-duty and high-performance applications where load capacity outweighs noise considerations, while belt systems occupy cost-sensitive passenger vehicle segments where acoustic refinement and packaging efficiency command priority. Composite materials represent the fastest-expanding material category as OEMs pursue mass reduction targets without sacrificing fatigue life.
EPA Corporate Average Fuel Economy standards and NHTSA safety regulations in the United States mandate lighter powertrain components that preserve structural integrity under crash loads. EMA and REACH frameworks in Europe restrict certain alloy additives while demanding full material traceability through supply chains. Stakeholders must monitor how dual regulatory pressures on emissions and material composition reshape supplier qualification timelines and tooling investments.
Market Dynamics
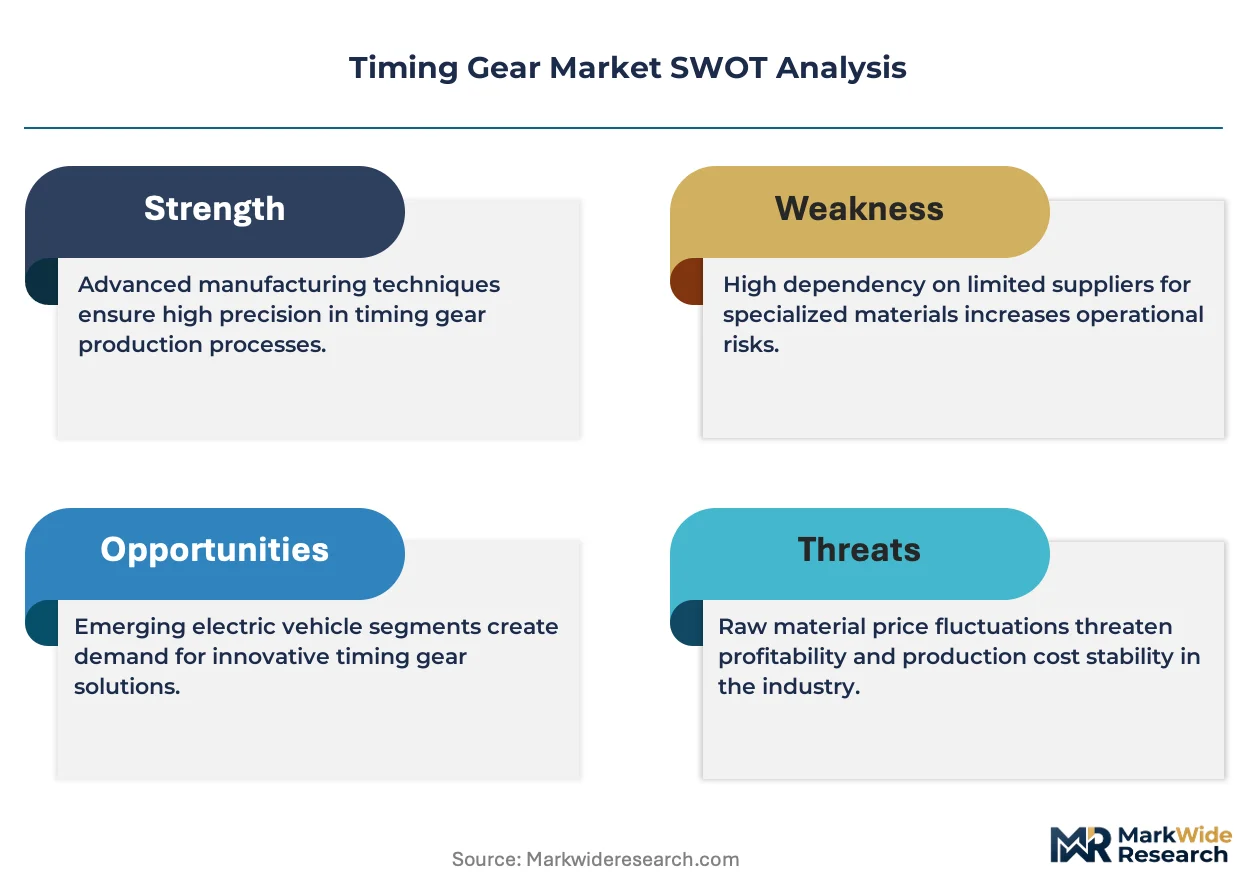
Powertrain electrification is fragmenting traditional timing gear architectures as hybrid engines require dual-mode synchronization systems that bridge mechanical and electric motor control. This structural shift is reshaping supplier qualification timelines and tooling investments across the value chain.
Growth Catalysts
- EPA emissions standards:United States automotive OEM procurement of lightweight timing drive systems accelerates as Corporate Average Fuel Economy mandates tighten. Powder metallurgy and polymer composite solutions gain traction.
- Precision engineering clusters:Germany's corridor around Stuttgart and Munich concentrates demand for high-RPM capable components with AGMA quality-class tooth profiles.
- Composite material innovation:Sintered metal and advanced polymer formulations enable mass reduction targets without sacrificing surface hardness exceeding 58 HRC for wear resistance.
Market Restraints
- Alloy additive restrictions:EMA and REACH frameworks in Europe limit certain material compositions while demanding full supply chain traceability, extending qualification cycles.
- Input cost volatility:Specialty steel and rare earth alloying elements face price instability tied to concentrated mining operations in select geographies.
- Technical load-capacity tradeoffs:Belt systems cannot match chain drive load capacity in heavy-duty applications, segmenting addressable markets by performance tier.
Strategic Opportunities
- Dual-mode synchronization systems:Hybrid powertrain architectures create white space for suppliers bridging mechanical timing gears with electric motor control interfaces.
- Integrated bearing-gear assemblies:Convergence of powder metallurgy gear production with precision bearing manufacturing cuts assembly steps for powertrain manufacturers.
- Aftermarket service networks:Channel innovation through certified rebuild programs for high-mileage commercial vehicle timing systems extends component lifecycle revenue.
Industry Challenges
- AGMA and DIN certification timelines:Quality-class verification for precision-machined tooth profiles requires extended testing protocols that delay new product introduction.
- Cross-functional engineering talent:Scarce expertise combining mechanical gearing knowledge with electric powertrain control systems constrains development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timing Gear Market |
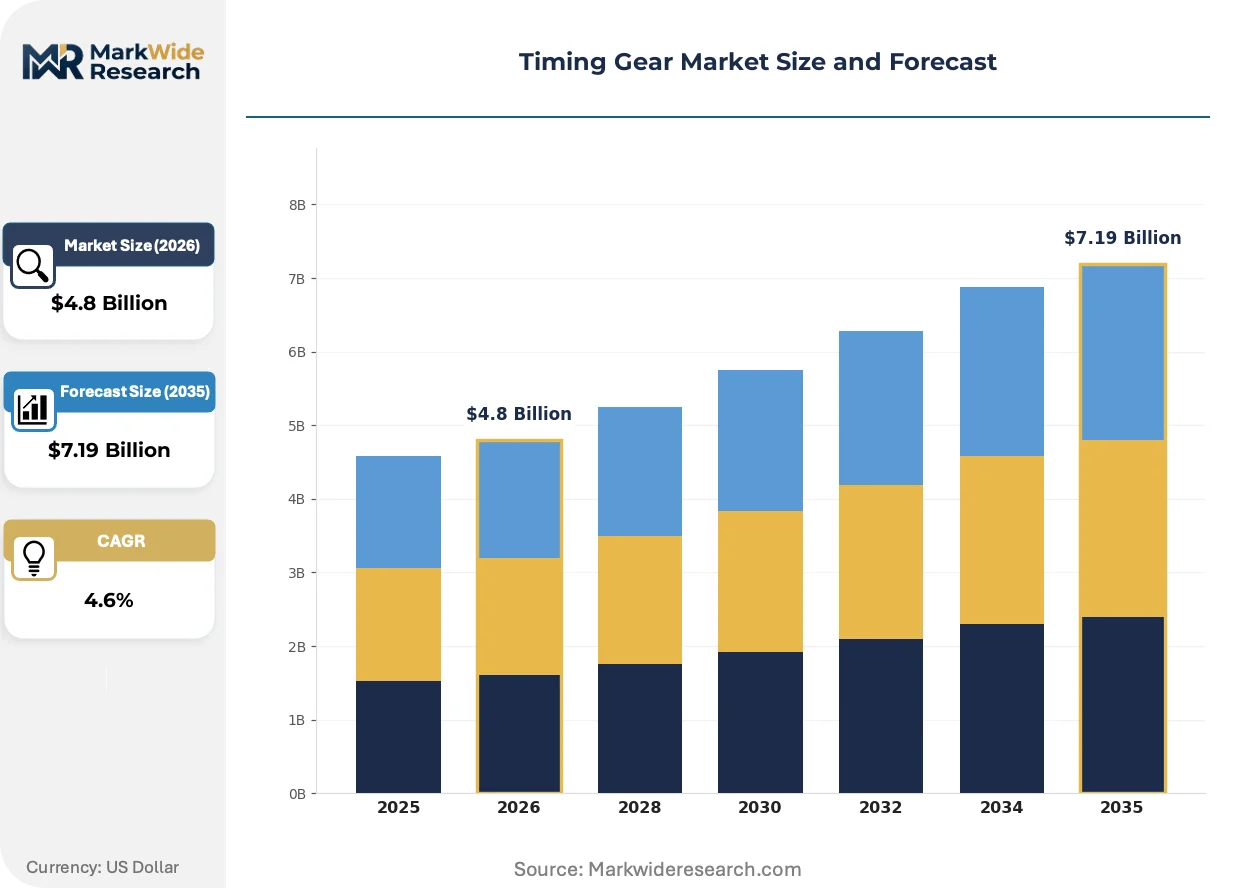
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chain, Belt, Sprocket, Pulley Material: Steel, Aluminum, Composite, Plastic End User: Automotive, Aerospace, Industrial Equipment, Marine Application: Engine Timing, Gear Reduction, Speed Control, Camshaft Operation |
| Companies Covered | Gates Corporation, GKN PLC, The Timken Company, ACDelco, American Axle & Manufacturing Inc., ContiTech, J.K. Fenner Limited, The Carlstar Group, Dayco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timing Gear Market Emerging Trajectories
Digital simulation tools are compressing product development cycles while material science breakthroughs enable lighter-duty applications. These forces are converging to redefine competitive positioning across the timing gear supply base.
Polymer composite belt systems are virtualizing traditional metal gear architectures in downsized turbocharged passenger vehicle engines. Tier 1 suppliers with captive polymer formulation capabilities capture specification authority from conventional metal gear producers. This technology is virtualizing the boundary between belt and chain drive segments, collapsing historical performance-category distinctions.
REACH material traceability mandates in Europe are forcing systemic documentation upgrades across multi-tier supply chains. Component suppliers must implement serialized batch tracking from raw material through finished gear hardening. German precision engineering corridors face the steepest compliance costs due to their concentration of high-specification automotive OEM relationships.
Consolidated procurement desks at major powertrain manufacturers are compressing supplier bases and extending payment terms. Tier 2 and Tier 3 gear producers face margin pressure as buying power concentrates among fewer integrated system suppliers. This pattern is most visible in United States automotive OEM sourcing, where EPA-driven lightweighting mandates intensify price competition for qualifying components.
Timing Gear Market Segmentation
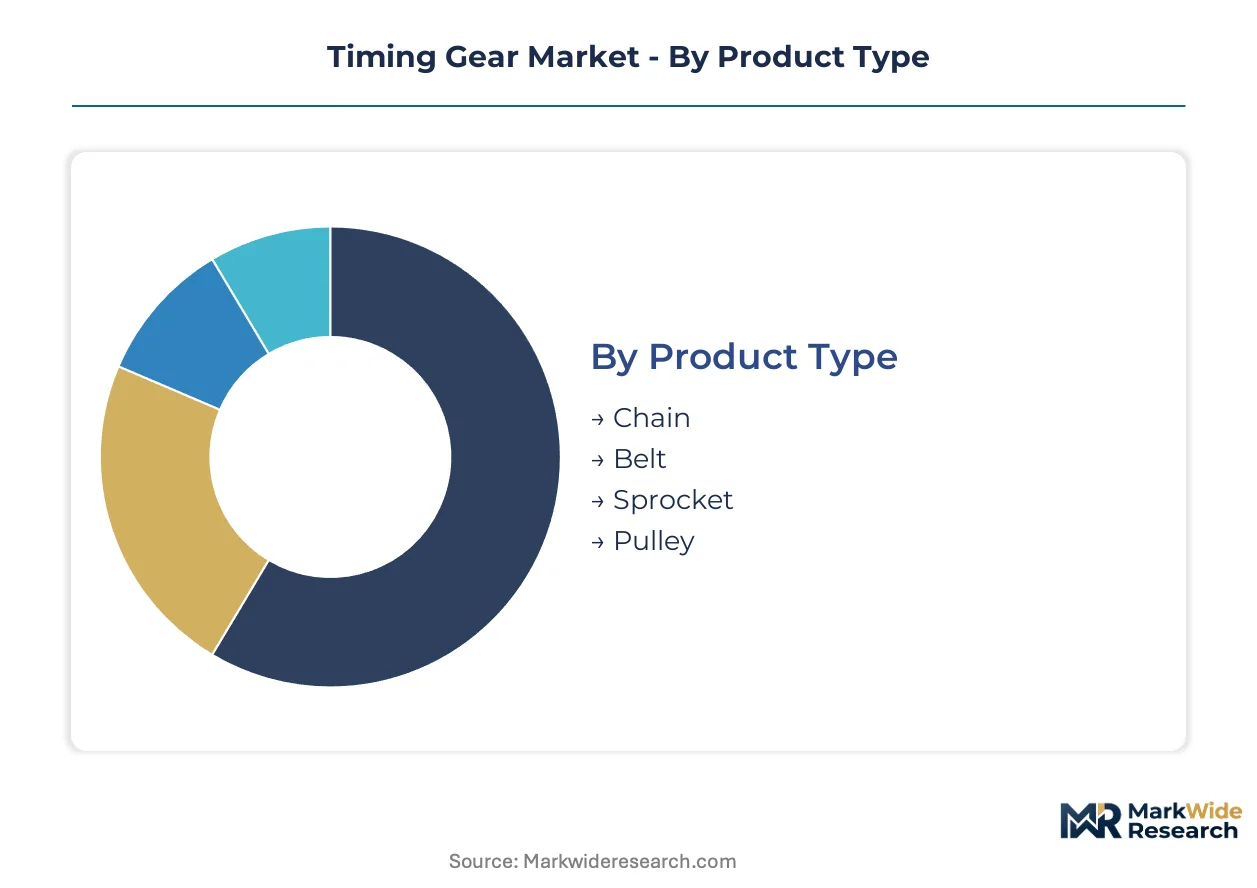
Timing gear procurement cycles vary dramatically by product category and end-use intensity. Automotive OEMs refresh engine architectures every 5-7 years, while industrial equipment operates on 15-20 year replacement horizons. Understanding these velocity differentials shapes inventory positioning and qualification investment priorities.
Product Type:
Chain systems turn over fastest in heavy-duty commercial vehicle programs, while belt architectures dominate passenger car refresh cycles with shorter design windows.
- Chain:Roller and silent chain configurations handle peak torque loads exceeding 500 Nm in diesel and high-performance gasoline engines. Demand clusters in Stuttgart and Munich precision engineering corridors where AGMA quality-class specifications are mandatory for OEM qualification.
- Belt:Polymer composite and rubber-glass hybrid constructions enable mass reduction targets without sacrificing fatigue life in downsized turbocharged engines. Procurement is accelerating among United States automotive OEMs responding to EPA Corporate Average Fuel Economy mandates.
- Sprocket:Powder metallurgy and machined steel variants provide positive engagement for chain drive systems.
- Pulley:Cast aluminum and stamped steel designs guide belt routing with tensioner integration.
Chain dominates installed base in commercial vehicle and high-RPM applications. Belt is where expansion concentrates as hybrid powertrains demand acoustic refinement and packaging efficiency.
Material:
Steel commands premium positioning for load-critical applications, while composite formulations capture specification authority through mass reduction performance.
- Steel:Case-hardened and through-hardened alloy grades achieve surface hardness exceeding 58 HRC for wear resistance in high-RPM timing applications. German precision engineering corridors concentrate demand for DIN-certified steel formulations with full batch traceability.
- Composite:Glass-fiber reinforced polymers and carbon-fiber hybrids enable 40-60% mass reduction versus metal equivalents. REACH material traceability mandates in Europe force serialized documentation from raw material through finished component hardening.
- Aluminum:Die-cast and machined grades serve pulley and light-load sprocket applications where thermal conductivity aids heat dissipation.
- Plastic:Injection-molded formulations occupy auxiliary drive positions with minimal torque transmission requirements.
Steel maintains specification dominance in heavy-duty and high-performance tiers. Composite is climbing the fastest as OEM lightweighting targets intensify across passenger vehicle segments.
End User:
Automotive volumes dwarf adjacent sectors, yet aerospace and marine command margin premiums through certification complexity and low-volume precision requirements.
- Automotive:Passenger car, light truck, and commercial vehicle powertrain manufacturers constitute the primary demand base. United States EPA emissions standards and NHTSA safety regulations mandate lighter components preserving structural integrity under crash loads.
- Industrial Equipment:Compressor, pump, and generator manufacturers specify timing gears for auxiliary drive systems with extended service intervals.
- Aerospace:Auxiliary power units and propulsion systems require specialized alloys with full material pedigree documentation.
- Marine:Outboard and inboard engine manufacturers prioritize corrosion-resistant coatings for saltwater environments.
Automotive dominates absolute volume and supplier qualification activity. Industrial Equipment represents the steadiest replacement-driven demand with less cyclical volatility.
Application:
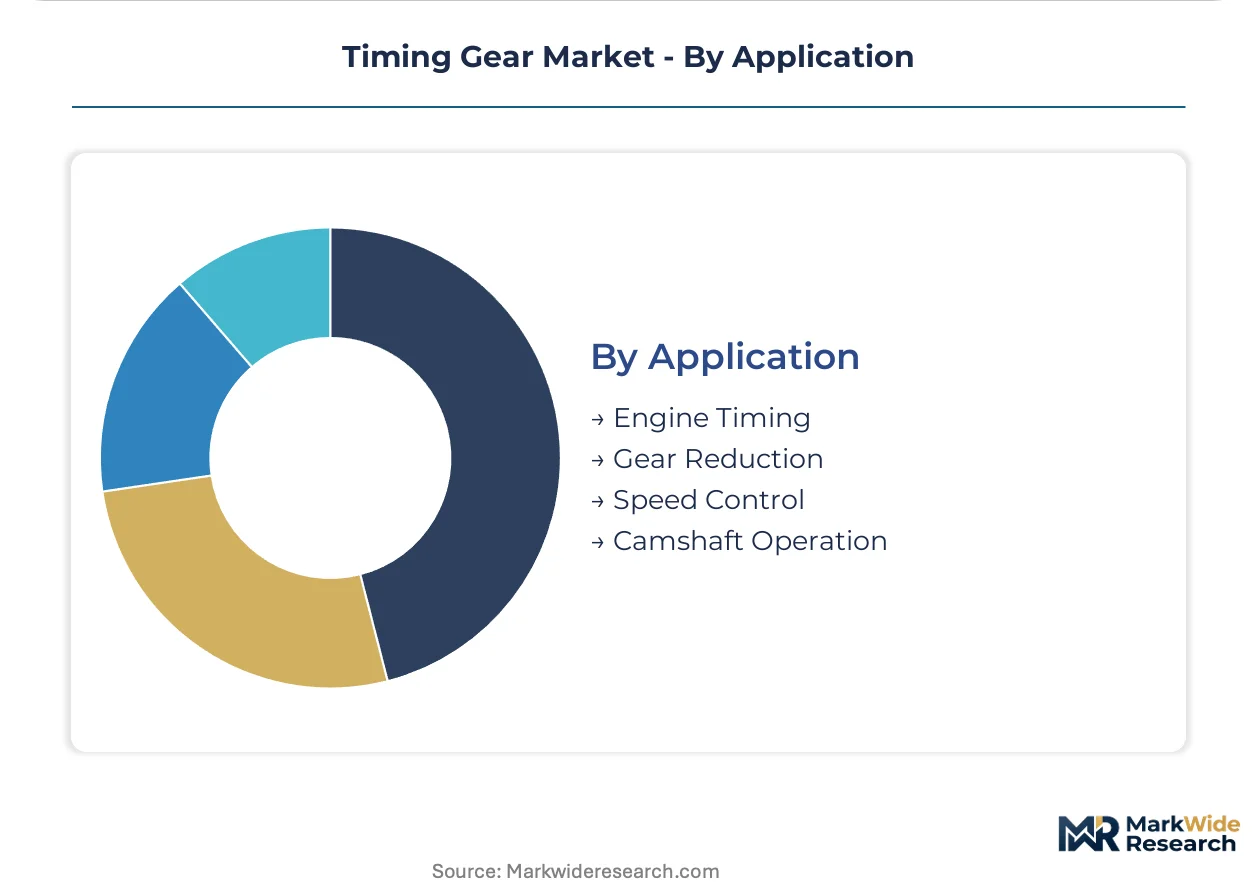
Engine timing absorbs the majority of precision-manufacturing capacity, while gear reduction and speed control applications tolerate broader tolerance bands.
- Engine Timing:Crankshaft-to-camshaft synchronization demands exact tooth profiles maintaining valve timing accuracy across varying engine speeds and thermal loads. Dual-mode hybrid architectures are fragmenting traditional single-mechanism approaches.
- Camshaft Operation:Variable valve timing systems require precision components enabling phase adjustment under oil pressure control.
- Gear Reduction:Step-down ratios for accessory drives operate at lower precision requirements than primary timing functions.
- Speed Control:Governor and limiter mechanisms manage maximum rotational velocity in industrial powertrains.
Engine Timing commands the tightest manufacturing tolerances and longest qualification cycles. Camshaft Operation is gaining specification complexity as variable valve timing penetrates mainstream powertrain architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement desks concentrate demand in precision engineering corridors where EPA and REACH compliance intersect with high-RPM component manufacturing. Supplier qualification timelines extend longest in markets with dual regulatory pressure on emissions and material traceability.
United States
EPA Corporate Average Fuel Economy mandates accelerate lightweight timing drive procurement from Detroit and Southeast automotive clusters. NHTSA crash safety regulations require components preserving structural integrity under impact loads. Powder metallurgy suppliers around Detroit face compressed payment terms as OEM procurement desks consolidate vendor bases.
Germany
Stuttgart and Munich precision engineering corridors concentrate demand for AGMA quality-class timing gears in high-RPM applications. EMA and REACH frameworks restrict certain alloy additives while mandating serialized batch documentation. Baden-Württemberg suppliers bear steepest compliance costs due to concentration of premium automotive OEM relationships.
China
Domestic OEM expansion and export manufacturing sustain demand for both chain and belt architectures across Shanghai and Yangtze River Delta production zones. MIIT fuel consumption standards and GB emissions regulations tighten component specifications for local vehicle production. Jiangsu and Zhejiang provinces host expanding powder metallurgy capacity serving regional powertrain manufacturers.
Japan
Hybrid powertrain leadership from Toyota and Honda generates specification authority for dual-mode synchronization systems in Aichi and Kanto manufacturing belts. METI carbon neutrality roadmaps pressure suppliers toward mass-reduction solutions without sacrificing surface hardness requirements. Nagoya-area precision manufacturers maintain tight tolerance capabilities for variable valve timing applications.
India
Domestic passenger vehicle growth and commercial vehicle renewal cycles drive timing gear demand across Tamil Nadu and Maharashtra automotive corridors. BIS quality certification and PLI scheme incentives reshape supplier qualification pathways for local and export markets. Chennai and Pune clusters concentrate machining capacity for both OEM supply and aftermarket replacement networks.
Timing Gear Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Integrated system suppliers capture specification authority through captive polymer formulation or powder metallurgy capabilities. Three archetypes dominate: belt-drive specialists leveraging composite material science, precision metal fabricators with AGMA-certified hardening processes, and bearing-gear integrators cutting assembly steps for powertrain manufacturers. Consolidation pressure intensifies as Tier 1 procurement desks compress supplier bases and extend payment terms.
Within the integrated-system tier, Gates Corporation and The Timken Company exemplify channel-control strategies through material science and assembly-integration positioning. GKN PLC anchors the precision-metal fabrication archetype with powder metallurgy heritage. ACDelco and Dayco occupy positions spanning aftermarket distribution and OEM supply relationships. ContiTech represents the Continental AG-backed synthetic materials approach to timing drive architectures. American Axle & Manufacturing Inc. and J.K. Fenner Limited illustrate regional-scale specialists competing on qualification speed and geographic proximity to major OEM assembly plants.
| Leading Market Players |
|---|
| Gates Corporation |
| GKN PLC |
| The Timken Company |
| ACDelco |
| American Axle & Manufacturing Inc. |
| ContiTech |
| J.K. Fenner Limited |
| The Carlstar Group |
| Dayco |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor cost dynamics compress margins for powder metallurgy suppliers while amplifying price differentiation between AGMA-certified precision components and commodity-grade alternatives. Supply concentration in Jiangsu and Zhejiang provinces concentrates bargaining power among integrated system suppliers, forcing Tier 2 gear producers to absorb logistics volatility or cede specification authority.
Pricing Analysis
Cost-plus contracts indexed to specialty steel and rare earth alloying element spot prices dominate procurement between German precision engineering suppliers and Stuttgart-area OEMs. Price differentiation separates DIN-certified steel formulations with full batch traceability from standard-grade alternatives, with certification tier and volume scale as primary drivers. Pricing pressure stems from consolidated procurement desks extending payment terms, while aftermarket service networks exhibit the lowest price sensitivity due to lifecycle revenue capture.
Supply Chain Analysis
Export-control restrictions on advanced powder metallurgy sintering equipment limit technology transfer to emerging manufacturing bases, concentrating high-specification capacity in Germany, Japan, and the United States. Raw material flows draw from specialty steel mills in Baden-Württemberg, rare earth processing facilities in China, and polymer formulation centers in the United States. Single-source vulnerability around precision hardening equipment creates systemic exposure. Distribution runs through Tier 1 integrated system suppliers with captive specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification fragments traditional timing gear architectures into multiple synchronization niches, creating entry points for specialists bridging mechanical and electric control interfaces.
For Market Incumbents: Pre-empt specification displacement by hybrid powertrain architectures through captive development of dual-mode synchronization systems. Deepen backward integration into polymer formulation capabilities to defend against belt-drive virtualization of metal gear applications. Prioritize AGMA quality-class certification maintenance as emerging entrants lack hardened process expertise. For New Entrants and Emerging Players: Mid-market commercial vehicle aftermarket rebuild networks in India and Southeast Asia represent the most penetrable entry point, as OEM procurement consolidation leaves service gaps in high-mileage timing system replacement. Target powder metallurgy sprocket supply for industrial equipment auxiliary drives, where qualification cycles run shorter than automotive programs. Pursue direct relationships with fleet maintenance operators as a go-to-market angle bypassing consolidated Tier 1 channels. For Investors and Strategic Acquirers: Precision metal fabricators with captive AGMA-certified hardening processes and established European OEM relationships offer the strongest acquisition profile for long-term viability through the powertrain transition window. Monitor hybrid powertrain platform ramp schedules as the critical inflection signal for timing gear architecture demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Synchronization Development | Captures specification authority in hybrid powertrain architectures bridging mechanical and electric motor control. |
| Backward Integration into Polymer Formulation | Defends against belt-drive virtualization by Gates Corporation and ContiTech composite material science. |
| AGMA Quality-Class Certification Investment | Extends qualification timelines that constrain emerging competitors without hardened precision processes. |
| Aftermarket Service Network Expansion | Generates lifecycle revenue from high-mileage commercial vehicle timing system rebuild programs. |
| Powder Metallurgy Capacity Addition | Reduces component weight for EPA-driven lightweighting mandates in United States automotive OEM supply. |
Methodological Framework
Desk research of customs trade data, SEC filings from bearing and powertrain suppliers, and IHS Markit vehicle production databases preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, powder metallurgy plant managers, and aftermarket distribution channel heads. Primary fieldwork across Stuttgart, Detroit, and Nagoya manufacturing belts combined with secondary validation from EPA regulatory filings and REACH compliance documentation. Bottom-up unit demand estimates triangulated against top-down powertrain production forecasts.
Assumptions held fixed include EPA Corporate Average Fuel Economy trajectory tightening, MIIT fuel consumption standard enforcement in China, and hybrid powertrain penetration rates across passenger vehicle segments. The analytical framework modeled segmentation across chain-belt-sprocket-pulley product types, steel-composite-aluminum-plastic material tiers, and automotive-industrial-aerospace-marine end-use categories. CAGRs derived from regression analysis against powertrain production volumes and content-per-vehicle trends. Industry-specific inputs incorporated powder metallurgy yield rates and polymer composite fatigue testing protocols.
Macroeconomic conditions sit as an overlay; deviation in specialty steel pricing volatility, rare earth supply disruption, or automotive OEM production schedules would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and technology substitution rates. Material shifts in hybrid powertrain architecture standardization or REACH material traceability mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Canada Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Apron Bus Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Canada Automotive Actuators Market
Automotive Parts
Cam Trigger Kits Market