
 VVT Actuators Market | 2026-2036
VVT Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
VVT Actuators Market Analytics
Passenger car electrification is restructuring procurement patterns across the VVT actuator supply base. BorgWarner Inc. leverages its powertrain electronics portfolio to capture electromelectric actuator contracts from European OEMs. Denso Corporation anchors hybrid vehicle programs in Japan through integrated VVT module production. Schaeffler AG differentiates via cam phaser systems that bridge hydraulic legacy and electric architectures.
A VVT actuator is an electromechanical or hydraulic device that modulates camshaft timing relative to crankshaft position, typically operating at oil pressures of 1-5 bar or motor-driven resolutions below 0.5 degrees to optimize valve overlap across engine speed ranges. Hydraulic actuators retain cost advantages in mass-market internal combustion engines, though electromechanical variants are gaining share where millisecond response times enable cylinder deactivation strategies. Continuous variable valve timing technology commands premium positioning as it permits infinite phase adjustment rather than discrete steps, while the OEM end-user channel concentrates volume despite aftermarket growth in aging vehicle parc regions.
EPA Corporate Average Fuel Economy standards and Euro 7 emission limits from the European Commission are tightening allowable NOx and CO2 thresholds, forcing actuator suppliers to validate components across broader temperature and duty-cycle envelopes. China's MIIT administers parallel fuel consumption regulations that phase in stricter limits for domestic vehicle production. Stakeholders must monitor how split-cycle and camless engine prototypes from research consortia could obsolesce conventional cam-phasing architectures before the forecast horizon concludes.
Market Dynamics
Electromechanical actuator architectures are displacing hydraulic systems across passenger car powertrains as Euro 7 and China's MIIT fuel consumption regulations mandate faster valve response times for cylinder deactivation strategies. This technology transition is restructuring supplier qualification timelines and capital allocation across the tier base.
Growth Catalysts
- Emissions architecture:Euro 7 NOx thresholds force OEMs to specify actuators with sub-millisecond response windows, eliminating legacy hydraulic lag in stop-start systems.
- China MIIT Phase IV:Domestic OEM procurement of electromechanical VVT modules accelerates as fleet-average consumption limits tighten for 2026 vehicle certification cycles.
- Hybrid powertrain proliferation:Atkinson-cycle engines in Toyota and Honda hybrid platforms require continuous cam phasing across wider speed ranges than conventional ICE architectures permit.
Market Restraints
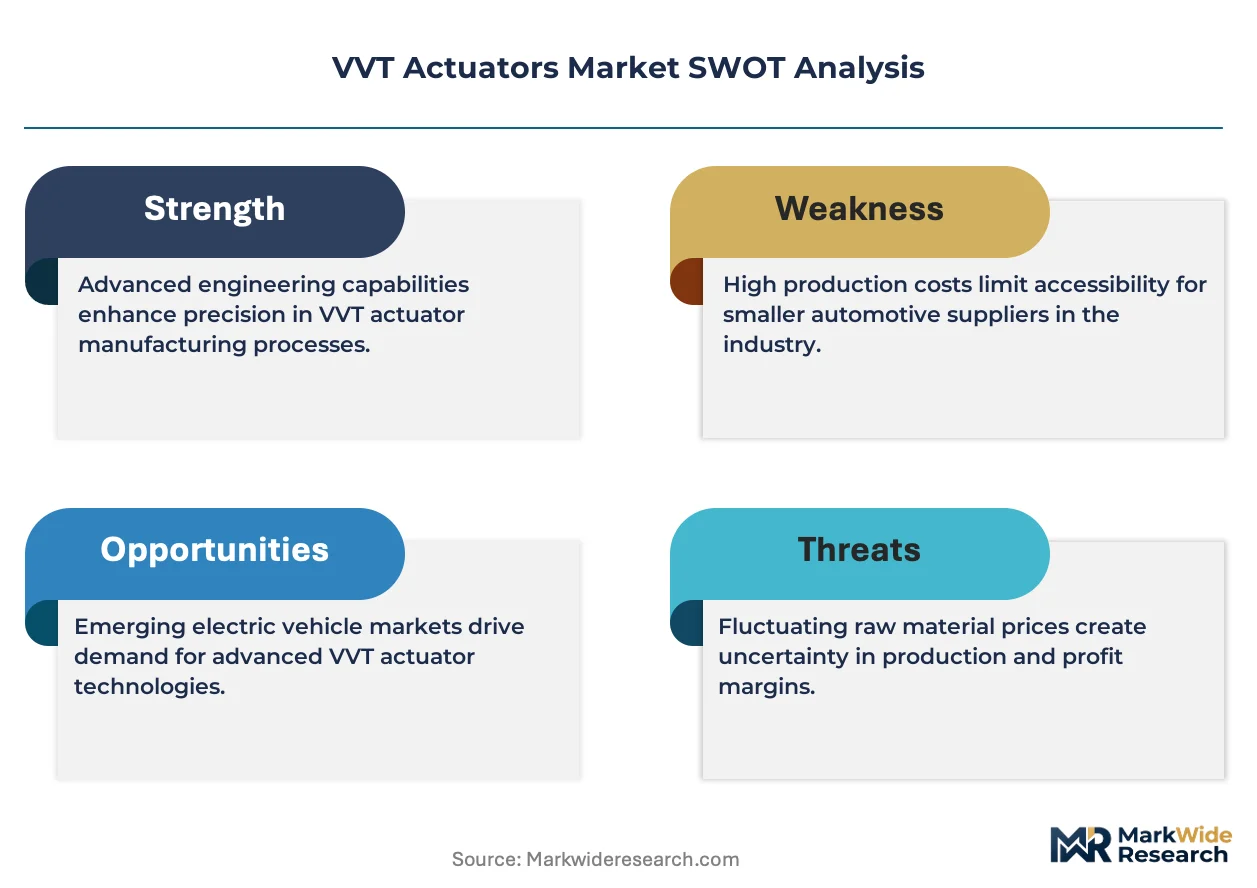
- Rare earth magnet dependency:Neodymium price volatility in Chinese export markets compresses margins for electromechanical actuator producers sourcing permanent magnet motors.
- Supplier concentration:Precision machining of cam phaser housings concentrates in Japan's Aichi and Shizuoka prefectures, exposing procurement pipelines to single-source risk.
- Hydraulic legacy lock-in:Mass-market compact car segments retain cost-optimized hydraulic actuators where electromechanical unit economics fail to amortize across 150,000-unit annual volumes.
Strategic Opportunities
- India BIS adoption:Domestic OEMs sourcing BS6 Phase II-compliant actuators create white space for electromechanical suppliers qualifying under India's automotive component localization mandates.
- Camless engine convergence:Electromagnetic valve actuation prototypes from research consortia could eliminate camshafts entirely, opening module-level supplier positions for actuator specialists with motor control IP.
- Aftermarket channel digitization:E-commerce platforms serving aging European vehicle parc enable direct-to-workshop distribution of replacement phaser units, bypassing traditional tiered distribution.
Industry Challenges
- Embedded software validation:Electromechanical actuators require ASIL-D functional safety certification for motor control algorithms, extending development timelines by 14-18 months.
- Thermal cycling durability:Validation protocols must demonstrate 15-year service life across -40°C to 150°C engine bay temperatures, demanding accelerated test infrastructure investment.
- Legacy powertrain integration:Backward compatibility with existing engine control modules constrains electromechanical actuator signal protocols and connector architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VVT Actuators Market |
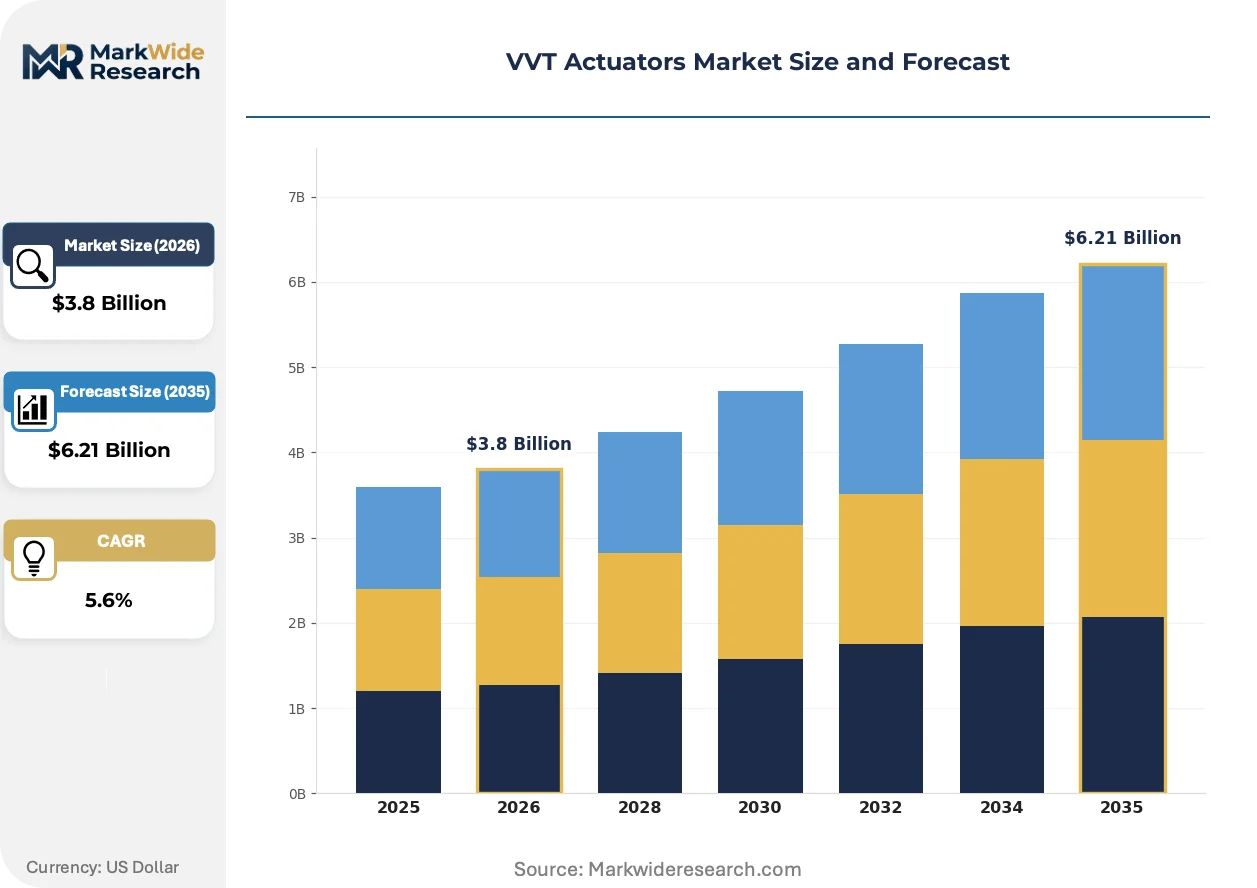
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Pneumatic, Electromechanical Technology: Variable Valve Timing, Continuous Variable Valve Timing, Timing Belt, Timing Chain End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks |
| Companies Covered | BorgWarner Inc., Denso Corporation, Schaeffler AG, Eaton Corporation, Robert Bosch GmbH, Hitachi Astemo, Aisin Seiki Co., Ltd., Continental AG, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VVT Actuators Market Evolving Landscape
Actuator technology is bifurcating between cost-optimized hydraulic legacy and precision electromechanical architectures, with regulatory pressure compressing the transition timeline. Suppliers are reconfiguring production footprints and qualification protocols to serve divergent OEM technology roadmaps.
Brushless DC motor-driven cam phasers are electrifying valve timing control through direct torque delivery eliminating oil pressure dependency. European premium OEMs specify these units for 48V mild-hybrid platforms requiring instantaneous cylinder deactivation. The technology is compressing hydraulic actuator share in segments above 2.0L displacement where fuel economy gains amortize unit cost premiums.
EPA Corporate Average Fuel Economy standards and Euro 7 emission limits are tightening allowable CO2 thresholds across light-duty vehicle fleets. Powertrain engineers must validate VVT components across broader duty-cycle envelopes including extended idle and frequent stop-start events. Electromechanical actuator suppliers in Germany and Japan are expanding thermal test cell capacity to meet compressed homologation timelines.
Fleet procurement of integrated VVT modules is consolidating supplier relationships around powertrain electronics specialists capable of delivering cam phaser, oil control valve, and position sensor as calibrated subsystems. Tier 1 suppliers with in-house motor winding and controller assembly capabilities are displacing discrete component sourcing models. This concentration is most visible in Japan where Denso and Aisin dominate hybrid powertrain actuator procurement through captive hybrid vehicle programs.
VVT Actuators Market Segmentation
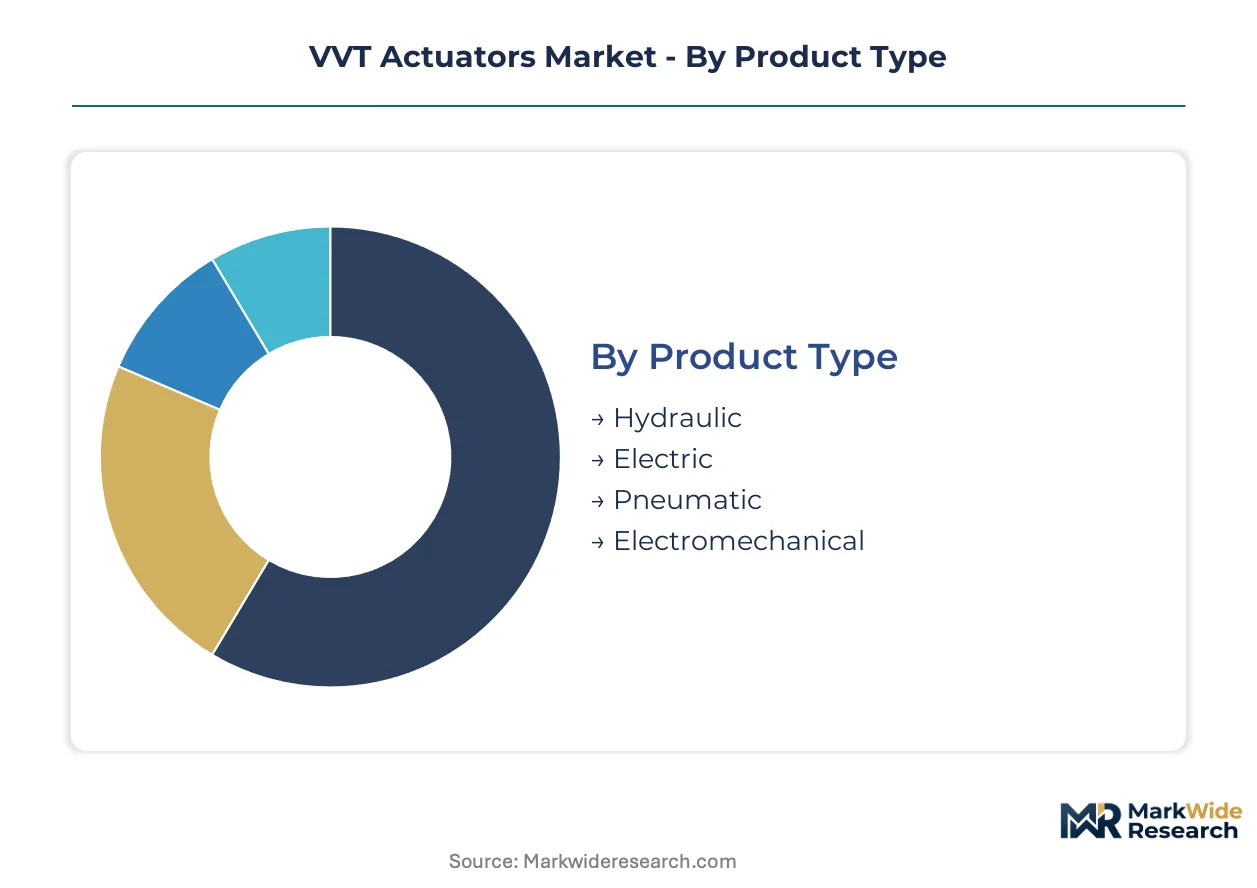
Segmentation in the VVT actuator market reflects divergent technology roadmaps across OEM powertrain strategies. Procurement patterns split between cost-optimized hydraulic legacy and precision electromechanical architectures, with regulatory pressure compressing transition timelines.
Product Type:
Actuator architecture determines response latency, oil dependency, and integration complexity across engine control systems.
- Hydraulic:Oil-pressure-driven cam phasing operates at 1-5 bar with established supply chains in mass-market internal combustion engines. Demand concentrates in compact car segments where unit economics fail to amortize electromechanical premiums below 150,000-unit annual volumes.
- Electromechanical:Brushless DC motor-driven units deliver sub-millisecond response windows enabling cylinder deactivation strategies. Procurement from European premium OEMs accelerates for 48V mild-hybrid platforms requiring instantaneous valve control.
- Electric:Solenoid-based architectures serve auxiliary timing functions in simplified valvetrain designs.
- Pneumatic:Compressed-air systems retain niche deployment in specialized industrial engine applications.
Mature deployment sits with hydraulic actuators. Newer deployment is concentrated in electromechanical variants.
Technology:
Valvetrain control methodology shapes fuel economy certification outcomes and engine mapping flexibility.
- Continuous Variable Valve Timing:Infinite phase adjustment across 0-60 crankshaft degrees permits real-time optimization of valve overlap. Toyota and Honda hybrid programs specify CVVT for Atkinson-cycle engines operating across wider speed ranges than discrete systems permit.
- Variable Valve Timing:Discrete step-wise cam phasing retains cost advantages in conventional ICE architectures where infinite adjustability is not required for compliance.
- Timing Belt:Rubber-toothed drive systems synchronize camshaft rotation in economy vehicle segments.
- Timing Chain:Metal link drives dominate durability-critical applications in commercial vehicle powertrains.
Volume concentration favors discrete VVT. Steepest expansion trajectory belongs to continuous variable architectures.
End User:
Channel structure determines qualification protocols, warranty exposure, and subsystem integration depth.
- OEMs:Direct procurement of calibrated VVT modules from powertrain electronics specialists with in-house motor winding and controller assembly capabilities.
- Tier-1 Suppliers:Intermediate integration of cam phaser, oil control valve, and position sensor as homologated subsystems for vehicle assembler delivery.
- Aftermarket:Replacement phaser unit distribution through e-commerce platforms serving aging European vehicle parc, bypassing traditional tiered distribution.
- Vehicle Assemblers:Final powertrain integration points for actuator subsystems in contract manufacturing arrangements.
Revenue capture concentrates with OEM direct sourcing. Margin expansion is shifting toward aftermarket channel digitization.
Vehicle Type:
Powertrain duty cycles and certification stringency create divergent actuator specification requirements.
- Passenger Cars:Light-duty fleet averaging regulations in China, Europe, and North America drive electromechanical adoption for stop-start and cylinder deactivation compliance.
- Commercial Vehicles:Heavy-duty cycle durability requirements and extended service intervals favor hydraulic actuator retention where thermal cycling demands exceed electromechanical validation envelopes.
- Heavy-Duty Trucks:Long-haul powertrain architectures prioritize reliability over response latency in current procurement specifications.
- Motorcycles:Compact packaging constraints and cost-sensitive segments retain mechanical timing systems in high-volume production.
Technology transition leads in passenger car applications. Commercial vehicle segments maintain hydraulic legacy lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in precision manufacturing corridors across Germany and Japan, while consumption accelerates in China and India as domestic OEMs electrify powertrain portfolios. Regulatory divergence between Euro 7 and MIIT Phase IV standards is fragmenting procurement specifications by geography.
Germany
Stuttgart and Munich engineering clusters supply electromechanical actuators to premium OEMs integrating 48V mild-hybrid architectures. KBA enforces Euro 7 pre-certification protocols that compress supplier validation timelines. Baden-Württemberg's automotive corridor hosts cam phaser R&D facilities bridging hydraulic legacy and electric transition.
China
Domestic OEM procurement of electromechanical VVT modules surges as MIIT Phase IV fleet consumption limits tighten for 2026 certification. Shanghai and Guangzhou assembly plants integrate localized actuator production to meet component localization mandates. Yangtze River Delta suppliers expand motor winding capacity for hybrid powertrain programs.
Japan
Aichi and Shizuoka prefectures concentrate precision machining of cam phaser housings for Toyota and Honda hybrid platforms. METI coordinates supplier qualification for Atkinson-cycle engines requiring continuous cam phasing across wider speed ranges. Nagoya manufacturing clusters dominate integrated VVT module production through captive tier relationships.
United States
Detroit Three OEMs specify electromechanical actuators for light-duty truck cylinder deactivation under EPA CAFE standards. Michigan powertrain engineering centers validate components across extended thermal cycling envelopes. Southeast assembly plants source hybrid-compatible phaser units for stop-start compliance.
India
Maharashtra and Tamil Nadu OEMs procure BS6 Phase II-compliant actuators as BIS adoption accelerates domestic electrification. Pune and Chennai manufacturing zones attract electromechanical suppliers qualifying under automotive component localization mandates. Tier-1 integrators establish motor controller assembly to serve Maruti Suzuki and Hyundai Motor India hybrid programs.
VVT Actuators Market Competitive Landscape
Top-tier vendors anchor powertrain electronics integration, while mid-tier specialists concentrate on discrete component machining and regional qualification services. The supplier base stratifies around three archetypes: full-system integrators with in-house motor control IP, precision machinists of cam phaser housings, and hybrid-focused module assemblers. Consolidation pressure intensifies as OEMs reduce qualified supplier lists. Strategic moves center on backward integration into permanent magnet supply chains and captive hybrid vehicle program partnerships.
Within the full-system integrator tier, BorgWarner Inc. and Denso Corporation exemplify divergent geographic anchoring strategies. BorgWarner's North American and European positioning reflects powertrain electronics consolidation around 48V architectures. Denso's Japanese headquarters proximity to Toyota and Honda hybrid programs illustrates captive tier relationships. Schaeffler AG occupies a bridging position between hydraulic legacy production and electromelectric transition investments. These three entities represent distinct competitive postures without implying specific market share or financial performance claims.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Denso Corporation |
| Schaeffler AG |
| Eaton Corporation |
| Robert Bosch GmbH |
| Hitachi Astemo |
| Aisin Seiki Co., Ltd. |
| Continental AG |
| Mitsubishi Electric Corporation |
| Others |
Value Network & Pricing Analysis
Electromechanical-hydraulic bifurcation between precision motor-driven units and cost-optimized oil-pressure systems generates divergent pricing power across supplier tiers, with Euro 7 compliance timelines compressing procurement premiums for sub-millisecond response capabilities while mass-market compact segments retain hydraulic legacy economics below 150,000-unit annual volumes. This tier divergence manifests in supply chain configurations: premium electromechanical channels anchor in Germany's Baden-Württemberg engineering corridor and Japan's Aichi precision machining clusters, whereas hydraulic commodity flows concentrate in China's Yangtze River Delta component zones serving domestic OEM localization mandates.
Pricing Analysis
Short-lead-time premiums for electromechanical VVT modules with validated ASIL-D motor control algorithms command 15-25% markups over standard qualification timelines, while spot inventory of hydraulic cam phasers trades at discounts in oversupplied compact car segments. Three-tier pricing structure across premium electromechanical, standard hydraulic, and economy remanufactured levels reflects certification grade and volume scale differentiation. Pricing pressure stems from neodymium magnet cost volatility in Chinese export markets compressing margins for permanent-motor producers. Mass-market compact OEMs exhibit highest price sensitivity, whereas European premium brands prioritize response latency over unit cost in 48V mild-hybrid procurement.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese export quotas and Japanese magnet alloy processing capacity, creating input dependency for electromechanical actuator motor windings. Precision cam phaser housing machining draws from Japan's Shizuoka and Aichi prefectures, with secondary capacity in Germany's Stuttgart tooling corridor and China's Guangzhou automotive zone. Single-source vulnerability concentrates in Japanese precision grinding equipment for sub-micron tolerance cam phaser bores. Distribution runs through captive tier relationships for hybrid powertrain programs, with aftermarket e-commerce platforms emerging for European aging vehicle parc replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a consolidation play where ASIL-D functional safety certification requirements and 14-18 month validation timelines force capital-constrained machining specialists toward acquisition or exit. Regulatory compression of homologation windows favors scaled powertrain electronics integrators over discrete component suppliers.
For Market Incumbents: Hedge hydraulic legacy exposure by accelerating electromechanical capacity buildout in Germany and Japan before Euro 7 pre-certification deadlines eliminate lagging suppliers. Secure captive neodymium magnet supply through backward integration or long-term offtake agreements with Chinese rare earth processors to defend margins against export quota volatility. Prioritize motor control algorithm IP development to maintain differentiation as camless engine prototypes threaten cam-phasing architectures.
For New Entrants and Emerging Players: Brushless DC motor controller specialization offers white-space entry through qualification as secondary-source electromechanical supplier to India domestic OEMs under BIS localization mandates. Target BS6 Phase II-compliant actuator procurement for Maruti Suzuki and Hyundai Motor India hybrid programs where established Japanese suppliers face capacity constraints. Deploy direct technical sales to Tier-1 integrators establishing motor winding assembly in Pune and Chennai manufacturing zones.
For Investors and Strategic Acquirers: Re-rating potential sits with precision machining specialists possessing validated cam phaser housing tolerances and established OEM qualification records, given consolidation pressure from electromechanical transition capital requirements. Long-term viability over the 5-10 year horizon requires positioning against camless engine disruption through electromagnetic valve actuation IP or module-level supplier relationships with research consortia. Watch split-cycle engine prototype announcements from major OEM powertrain divisions as inflection indicator for conventional VVT obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Actuator Capacity Expansion | Captures Euro 7 and MIIT Phase IV compliance-driven procurement from European and Chinese OEMs. |
| Backward Integration into Rare Earth Magnet Supply | Insulates margin structure from Chinese export quota volatility and neodymium price spikes. |
| ASIL-D Functional Safety Certification Investment | Extends qualified supplier status for motor control algorithms in 48V mild-hybrid platforms. |
| Camless Engine Module Development Partnership | Positions actuator specialists for electromagnetic valve actuation architectures eliminating camshafts. |
| Aftermarket E-Commerce Channel Establishment | Bypasses traditional tiered distribution to capture aging European vehicle parc replacement demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and powertrain electronics R&D directors. KBA Euro 7 pre-certification protocols, MIIT Phase IV fleet consumption databases, and EPA CAFE compliance filings provided regulatory validation. Vehicle production databases and IHS Markit registration data supplied demand-side calibration. Bottom-up component demand modeling triangulated against top-down OEM powertrain sourcing projections.
Data-stream reconciliation across electromechanical and hydraulic actuator shipment records, rare earth magnet trade flows, and OEM powertrain platform announcements generated volume and value estimates across the projection horizon. Segmentation dimensions modeled include actuator architecture, valvetrain control methodology, end-user channel, and vehicle propulsion class. CAGRs derived from regression analysis of historical procurement patterns against regulatory phase-in schedules. Industry-specific inputs incorporated thermal cycling durability test protocols and ASIL-D certification timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated camless engine commercialization or extended hydraulic legacy retention in emerging market compact segments. Forecasts reflect assumptions regarding MIIT Phase IV enforcement rigor, neodymium export quota stability, and Euro 7 homologation timeline adherence. A small set of triggers—split-cycle engine prototype announcements, Chinese rare earth policy shifts, and Indian BIS localization mandate acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
United States Ceramic Ball Bearings Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Apron Bus Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Global Car Engine Oil Market