
 Morocco Passenger Vehicles Lubricants Market | 2026-2036
Morocco Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Passenger Vehicles Lubricants Market Foresight
Fleet operator consolidation across Morocco's intercity transport and taxi cooperatives is pivoting procurement toward volume-contract supply arrangements. TotalEnergies leverages its coastal blending facility near Mohammedia to secure distribution reach into secondary cities. Afriquia anchors retail throughput through its integrated fuel station network, while OLA Energy competes on price positioning in the independent garage channel.
Passenger vehicles lubricants are formulated hydrocarbon-based fluids engineered to reduce friction, dissipate heat, and prevent wear in internal combustion and transmission systems, with SAE viscosity grades and API service categories defining performance thresholds. Engine oil dominates value capture given higher change frequency and premium synthetic migration, while brake fluid and grease occupy narrower margin pools tied to longer service intervals. Synthetic and semi-synthetic formulations are gaining share as thermal stability requirements intensify under Morocco's hotter operating climates and stop-start urban driving patterns.
Morocco's Ministry of Industry and Trade enforces vehicle emission alignment with European norms, compelling lubricant producers to certify products under ACEA and API standards that the country's national standards body validates. The country's energy transition framework, supervised by the Moroccan Agency for Energy Efficiency, incentivizes lower-friction lubricants as a component of fleet fuel-economy improvement. Stakeholders must monitor how Euro 6-equivalent engine penetration and electric vehicle pilot programs reshape specification demand before the forecast horizon closes.
Market Dynamics
Fleet consolidation across Morocco's taxi cooperatives and intercity bus operators is concentrating purchasing power into volume-contract arrangements, compressing margins for distributors serving fragmented independent garages. The Ministry of Industry and Trade's enforcement of Euro-equivalent emission standards is simultaneously forcing reformulation investments toward lower-viscosity synthetic grades.
Growth Catalysts
- Casablanca-Settat corridor density:Vehicle concentration in Morocco's economic heartland generates concentrated service demand, with lubricant consumption per capita running significantly above national averages due to commercial fleet intensity and urban stop-start driving patterns.
- ACEA/API certification alignment:The Ministry of Industry and Trade's adoption of European emission norms validates premium synthetic formulations, creating technical pull for products meeting C2/C3 and SN/SP service categories that command price premiums over mineral alternatives.
- Energy efficiency framework incentives:The Moroccan Agency for Energy Efficiency's fleet fuel-economy programs treat lower-friction lubricants as eligible interventions, embedding product specification into national carbon reduction planning and institutional procurement criteria.
Market Restraints
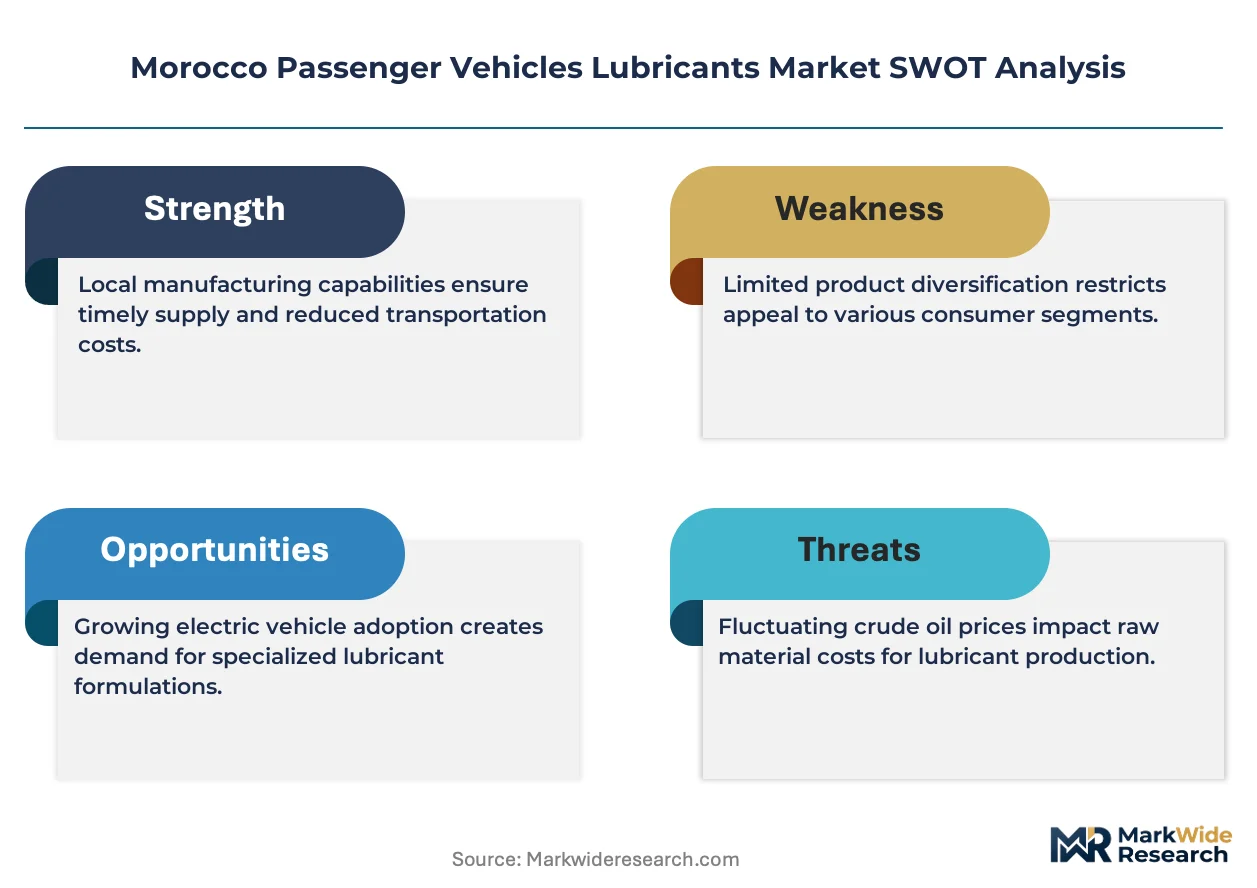
- Base oil import dependency:Morocco lacks domestic Group II/III base oil production, exposing blenders to freight and currency volatility from Middle Eastern and European suppliers that constitute the primary feedstock source.
- Independent garage channel fragmentation:An estimated majority of passenger vehicle maintenance occurs through unaffiliated mechanics lacking technical training or brand loyalty, creating price-driven purchasing that resists premium product migration.
- Extended drain interval technology:Advanced synthetic formulations and OEM fill-for-life transmission fluids reduce per-vehicle lubricant consumption velocity, compressing volume growth potential even as value per liter rises.
Strategic Opportunities
- Marrakech-Safi and Tangier-Tetouan-Al Hoceima expansion:Secondary urban corridors exhibit rising vehicle ownership with underdeveloped service infrastructure, offering first-mover positioning for distributors establishing depot networks ahead of competitor saturation.
- Ride-hailing fleet electrification pilot programs:Hybrid and battery-electric vehicle trials in Casablanca and Rabat create specification white space for thermal management fluids and e-axle lubricants absent legacy product entrenchment.
- Digital fleet management integration:Telematics-enabled oil condition monitoring allows predictive maintenance scheduling, opening subscription-based fluid management contracts that capture lifetime value from commercial operators.
Industry Challenges
- ACEA sequence certification timeline:European testing protocol completion stretches 18-24 months, delaying product launch windows and requiring working capital commitment before revenue recognition.
- Synthetic formulation technical staffing:Advanced additive chemistry and tribology expertise remains concentrated with multinational technical centers, constraining local R&D capability and forcing reliance on licensed formulations.
- Counterfeit product infiltration:Mislabeled mineral oils packaged as synthetic grades erode legitimate brand equity and create liability exposure for distributors whose supply chain controls prove insufficient.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Passenger Vehicles Lubricants Market |
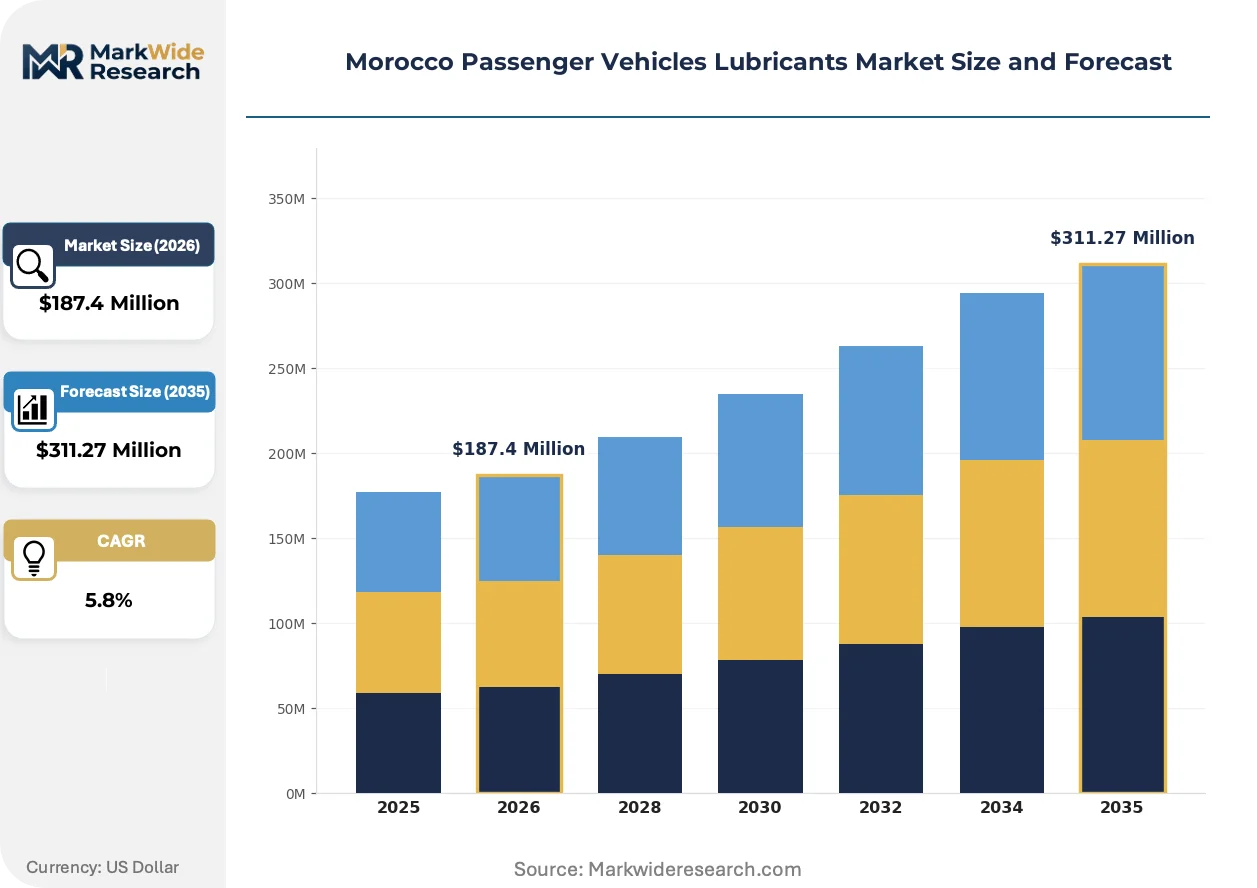
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Formulation: Synthetic, Semi-Synthetic, Mineral, Bio-Based Application: Passenger Cars, SUVs, Motorhomes, Light Trucks Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, Wholesale |
| Companies Covered | Chevron, OLA Energy, TotalEnergies, Fuchs Petrolub, Petrom, Royal Dutch Shell, Afriquia, Lubrilene, BP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Passenger Vehicles Lubricants Market Shifts & Advancements
Synthetic lubricant chemistry is advancing thermal stability thresholds to match Morocco's high-ambient operating conditions and congested urban duty cycles. Three developments are restructuring competitive positioning.
Polyalphaolefin (PAO) and ester-based base stocks are integrating into mainstream passenger vehicle formulations, replacing Group I mineral oils in high-temperature applications. Moroccan fleet operators running extended drain intervals in summer conditions are adopting these chemistries to prevent oxidative thickening. The technology is integrating warranty compliance into service contract structures, compressing price competition around commodity mineral grades.
The Ministry of Industry and Trade's alignment with Euro 6-equivalent emission standards is mandating ACEA C-sequence low-SAPS formulations for gasoline particulate filter and diesel particulate filter protection. Domestic blenders must reformulate existing product lines or surrender OEM fill positions to imported certified alternatives. Passenger diesel vehicles in the Casablanca-Settat corridor, where fleet renewal concentrates, are experiencing the most acute specification pressure.
Volume-contract procurement is consolidating lubricant purchasing decisions from individual garage owners to fleet management platforms and cooperative headquarters. Independent service channels in secondary cities are losing share to authorized workshop networks with captive fluid supply arrangements. This pattern is most visible in intercity transport cooperatives operating between Rabat, Casablanca, and Marrakech, where centralized maintenance budgeting overrides local mechanic preferences.
Morocco Passenger Vehicles Lubricants Market Segmentation
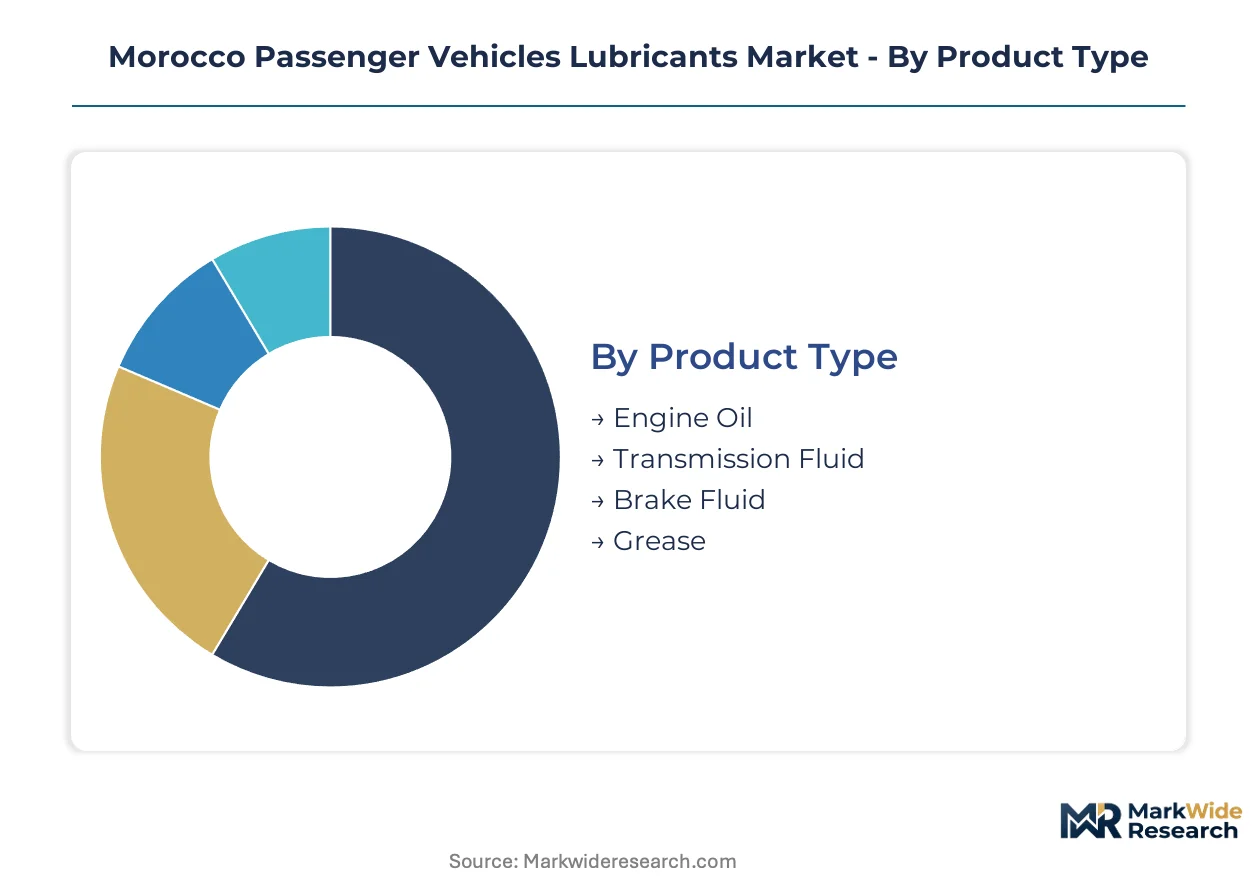
Segmentation in Morocco's passenger vehicle lubricants market reveals how specification requirements fragment across vehicle duty cycles, regulatory compliance tiers, and procurement channel economics. Understanding these divides allows suppliers to align formulation investments with pockets of price acceptance and technical pull.
Product Type:
Standardization dominates high-volume categories where OEM specifications lock in formulation requirements, while specialized applications permit greater customization around operating conditions and fleet maintenance protocols.
- Engine Oil:Hydrocarbon-based fluids formulated to SAE viscosity grades and API SN/SP or ACEA C-sequence specifications, with thermal stability packages engineered for Morocco's high-ambient climates. Demand concentrates in the Casablanca-Settat corridor where commercial fleet intensity and stop-start urban driving accelerate drain interval frequency and premium synthetic uptake.
- Transmission Fluid:Specialized lubricants for automatic, manual, and continuously variable transmissions, formulated with friction modifiers and shear-stable viscosity index improvers. The country's taxi and ride-hailing fleets in Rabat generate concentrated demand as fleet operators negotiate volume contracts specifying OEM-fill compliant chemistries.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT 3, DOT 4, or DOT 5.1 specifications for clutch and brake systems, with hygroscopic degradation driving periodic replacement cycles.
- Grease:Thickened lubricants for chassis, wheel bearings, and suspension components, formulated with lithium or calcium soap bases and extreme-pressure additives for Morocco's mixed urban-intercity duty cycles.
Leading the category by volume: Engine Oil. Growing fastest: Transmission Fluid as CVT penetration rises in urban taxi renewals.
Formulation:
Cost tiers stratify sharply between commodity mineral grades serving price-sensitive independent garages and certified synthetics capturing fleet procurement contracts.
- Synthetic:Polyalphaolefin (PAO) and ester-based formulations delivering oxidative stability for extended drain intervals in high-temperature Moroccan operating conditions. ACEA C2/C3 low-SAPS specifications required for Euro 6-equivalent particulate filter protection command price premiums in the Casablanca-Settat corridor where fleet renewal concentrates.
- Semi-Synthetic:Blended base stocks combining Group II/III oils with mineral fractions, positioned between premium synthetic and commodity mineral tiers for cost-conscious operators seeking moderate drain interval extension.
- Mineral:Group I base oil formulations serving legacy vehicle populations and price-driven independent garage channels, with demand concentrated in secondary cities where technical training and specification awareness lag primary urban centers.
- Bio-Based:Vegetable oil-derived lubricants with biodegradable profiles, positioned for environmentally sensitive applications and pilot fleet trials under the Moroccan Agency for Energy Efficiency's fuel-economy incentive programs.
Volume leadership: Mineral formulations. Steepest expansion trajectory: Synthetic grades as ACEA certification becomes mandatory for OEM warranty compliance.
Application:
Vehicle architecture and usage intensity create divergent lubricant consumption profiles across Morocco's passenger vehicle parc.
- Passenger Cars:Sedans and hatchbacks dominating Morocco's urban mobility, with lubricant demand driven by high annual mileage in taxi and ride-hailing service. Stop-start traffic patterns in Casablanca and Rabat accelerate engine oil degradation and thermal stress on transmission fluids.
- SUVs:Higher-displacement engines and all-wheel-drive systems requiring specialized lubricants for transfer cases and differentials, with demand concentrated in affluent urban households and tourism fleet operators serving Marrakech-Safi corridor.
- Motorhomes:Recreational vehicles with extended storage periods and intermittent use patterns, creating specialized demand for corrosion-inhibited formulations and fuel system stabilizers alongside standard lubricant categories.
- Light Trucks:Commercial utility vehicles operating in intercity transport and last-mile delivery, with higher load factors driving accelerated lubricant consumption and fleet-managed procurement through cooperative headquarters.
Passenger Cars dominate volume. SUVs gain share fastest as urban household upgrading shifts vehicle mix toward higher-margin lubricant applications.
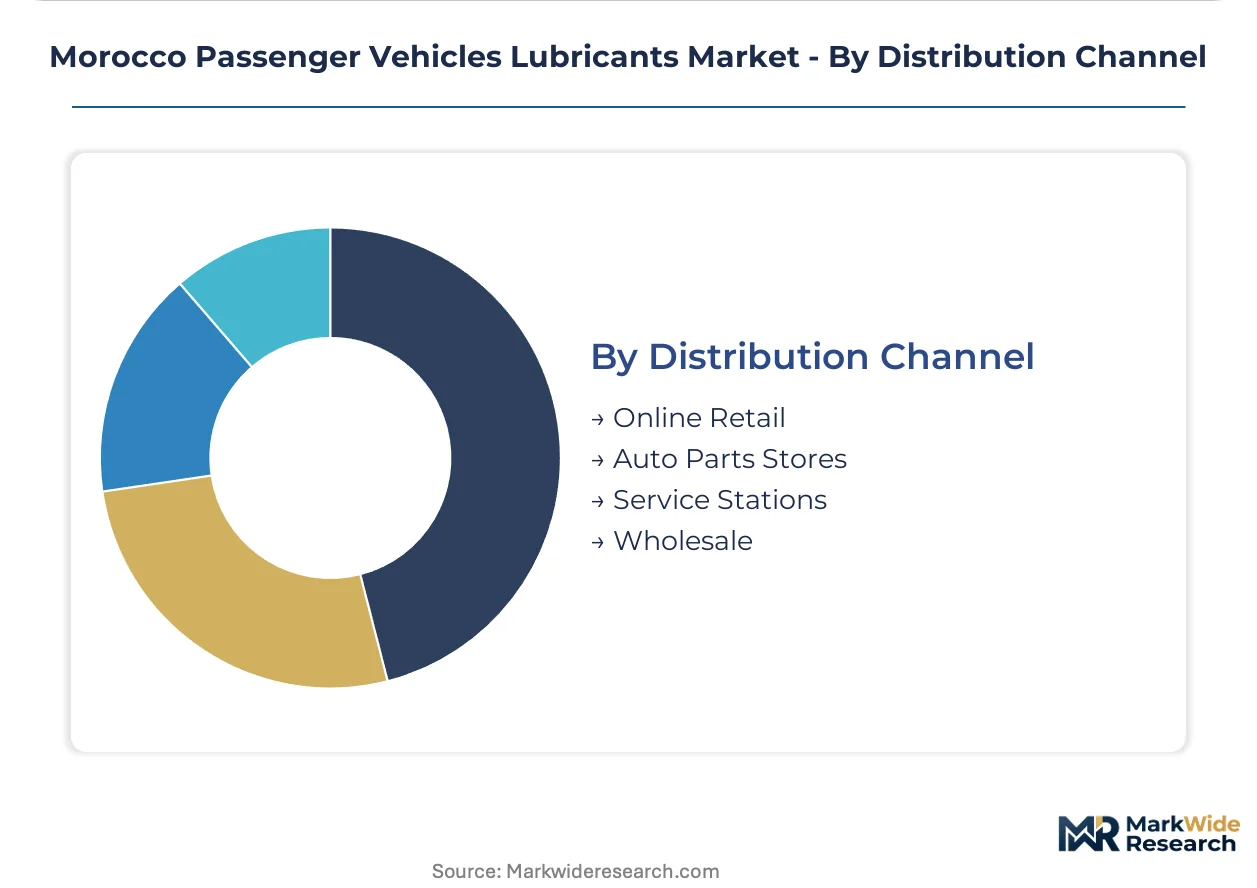
Distribution Channel:
Channel structure reflects the tension between consolidated fleet procurement and fragmented retail service economics.
- Online Retail:E-commerce platforms serving DIY enthusiasts and small garage operators, with growth constrained by counterfeit product risks and the technical complexity of specification matching without physical inspection.
- Auto Parts Stores:Independent and chain-affiliated retailers stocking mid-tier formulations for walk-in mechanic trade, with inventory depth determining competitive positioning in secondary cities.
- Service Stations:Integrated fuel-lubricant retail networks anchoring brand presence through convenience positioning and co-located quick-lube services, with Afriquia's national footprint capturing impulse replacement demand.
- Wholesale:Volume-contract supply to fleet operators, cooperatives, and authorized workshop networks, with multi-year agreements compressing margins while securing predictable offtake from Casablanca-Rabat-Marrakech transport corridors.
Wholesale channels lead by volume through fleet consolidation. Online Retail expands most quickly from low base as digital penetration reaches independent garage procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for passenger vehicle lubricants clusters along Morocco's Atlantic urban corridor, where commercial fleet density and service infrastructure concentrate purchasing power. The Casablanca-Settat region anchors national consumption volumes, while secondary urban centers exhibit diverging specification maturity and channel development.
Casablanca-Settat
Taxi cooperatives and ride-hailing fleets generate concentrated engine oil demand through high-frequency drain intervals. The Ministry of Industry and Trade enforces Euro-equivalent emission standards that mandate ACEA C-sequence low-SAPS formulations for particulate filter protection. Mohammedia's coastal blending infrastructure supplies synthetic grades to authorized workshop networks serving the corridor's fleet operators.
Rabat-Salé-Kénitra
Intercity transport cooperatives operating the Rabat-Casablanca axis negotiate volume-contract lubricant procurement through centralized maintenance platforms. The Moroccan Agency for Energy Efficiency incentivizes lower-friction formulations as fleet fuel-economy interventions. Urban stop-start driving patterns in Rabat accelerate thermal degradation of transmission fluids in taxi renewals.
Marrakech-Safi
Rising private vehicle ownership and tourism fleet expansion drive lubricant consumption growth ahead of service infrastructure development. National standards validation through the country's standards body lags primary urban centers, creating specification awareness gaps among independent mechanics. The Marrakech-Agadir corridor exhibits concentrated SUV demand from affluent households and tourism operators requiring specialized differential lubricants.
Tangier-Tetouan-Al Hoceima
Port logistics activity and cross-border transport generate commercial vehicle lubricant demand distinct from passenger car service patterns. Industrial free zone development attracts fleet operators with centralized procurement capabilities. The Tetouan region's independent garage channel remains fragmented, resisting premium synthetic migration despite coastal humidity conditions favoring corrosion-inhibited formulations.
Fès-Meknès
Legacy vehicle populations and price-sensitive independent maintenance sustain mineral oil demand despite national synthetic transition trends. Regional transport cooperatives serving mountain intercity routes prioritize brake fluid and chassis grease specifications for severe duty cycles. The Fès industrial zone's manufacturing workforce generates commuter vehicle lubricant demand through dispersed retail channels.
Morocco Passenger Vehicles Lubricants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specification differentiation through ACEA certification and fleet contract positioning. The market structures around three archetypes: multinational blenders with coastal manufacturing infrastructure, national fuel retailers leveraging integrated station networks, and independent distributors serving fragmented garage channels. Competitive moves concentrate on volume-contract consolidation with transport cooperatives and synthetic formulation licensing to secure OEM fill positioning.
Among multinational energy majors, TotalEnergies and Royal Dutch Shell exemplify the integrated blender archetype, leveraging technical center resources to certify ACEA sequences for Euro-equivalent compliance. Chevron occupies a position representing North American formulation expertise adapted to high-temperature operating conditions. National champion Afriquia anchors retail throughput through fuel station co-location, while OLA Energy sits within the price-competitive independent channel tier. These named entities represent the competitive spectrum from premium synthetic certification to volume-driven mineral grade distribution.
| Leading Market Players |
|---|
| Chevron |
| OLA Energy |
| TotalEnergies |
| Fuchs Petrolub |
| Petrom |
| Royal Dutch Shell |
| Afriquia |
| Lubrilene |
| BP |
| Others |
Supply & Pricing Matrix
Synthetic base stock migration toward PAO and ester chemistries is simultaneously elevating formulation costs and concentrating supply leverage among blenders with licensed additive packages. Morocco's ACEA C-sequence certification requirements are compressing price competition into certified versus non-certified tiers, with fleet procurement contracts capturing volume discounts that independent garages cannot match.
Pricing Analysis
Volume-contract procurement separates fleet operators negotiating multi-year supply agreements from fragmented independent garages purchasing spot quantities. Price differentiation hinges on ACEA certification tier and volume scale, with C2/C3 low-SAPS formulations commanding premiums over mineral alternatives. Pricing pressure intensifies in the independent channel as counterfeit products erode legitimate brand margins. Fleet cooperatives exhibit lowest price sensitivity due to warranty compliance requirements, while unaffiliated mechanics in secondary cities drive commodity-grade demand.
Supply Chain Analysis
Dual-sourcing requirements from major fleet operators mandate qualification of at least two additive suppliers and base oil feedstock origins. Morocco's blenders draw from Middle Eastern Group II/III producers and European specialty chemical suppliers for advanced additive packages. Single-source vulnerability concentrates in licensed formulation technology controlled by multinational technical centers. Distribution runs through coastal blending facilities at Mohammedia, with secondary logistics nodes serving the Marrakech-Safi and Tangier-Tetouan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's passenger vehicle lubricants market represents a consolidation play as ACEA certification timelines and reformulation investments force subscale blenders toward exit. Fleet procurement centralization accelerates this pressure by concentrating purchasing power among volume-contract winners.
For Market Incumbents: Deepen captive supply relationships with coastal base oil terminals and secure exclusive additive licensing agreements to lock out competitors from C-sequence certification. Expand depot infrastructure into Marrakech-Safi and Tangier-Tetouan ahead of fleet renewal waves. Counterfeit infiltration and extended drain interval technologies threaten volume growth, requiring investment in telematics-enabled fluid monitoring to capture lifetime value. For New Entrants and Emerging Players: E-commerce platforms serving DIY enthusiasts and small garage operators offer lower entry barriers than contested fleet channels. Target specification-aware independent mechanics in secondary cities with semi-synthetic formulations positioned between commodity mineral and premium synthetic tiers. White-space exists in thermal management fluids for hybrid-electric pilot fleets in Casablanca and Rabat, where legacy product entrenchment remains weak. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational blenders seeking coastal manufacturing footprints and established fleet relationships. The five-to-ten year viability window favors targets with ACEA-certified product lines and volume-contract revenue visibility. Monitor electric vehicle pilot program expansion as an inflection signal for thermal fluid specification demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| ACEA C-Sequence Certification Investment | Secures OEM fill positioning and fleet contract eligibility under Morocco's Euro-equivalent emission standards. |
| Coastal Blending Capacity Expansion | Reduces freight exposure from Middle Eastern base oil suppliers and accelerates response to Casablanca-Settat demand. |
| Fleet Telematics Integration | Enables predictive maintenance contracts that capture lifetime lubricant value from transport cooperatives. |
| Secondary City Depot Network Buildout | Establishes first-mover positioning in Marrakech-Safi and Tangier-Tetouan before competitor saturation. |
| Thermal Management Fluid Development | Addresses specification white space in hybrid-electric vehicle trials absent legacy engine oil entrenchment. |
Research Methodology
Document review covered customs and trade flow data, national standards body certifications, and energy agency policy frameworks, complemented by interviews with lubricant blenders, fleet procurement managers at transport cooperatives, and distribution channel operators. Secondary validation drew from industry association reports, SEC filings of multinational energy majors, and vehicle registration databases. Bottom-up demand modeling triangulated against top-down market sizing from supply-side capacity assessments.
Projected value trajectories across the analysis window derived from segmented modeling of formulation grade, vehicle duty cycle, and procurement channel economics. The analytical framework incorporated passenger car versus commercial fleet intensity, synthetic migration rates tied to ACEA enforcement timelines, and regional vehicle density differentials. CAGRs were computed from annualized growth paths adjusted for extended drain interval technology impacts and electric vehicle pilot program penetration.
The model holds under sustained ACEA certification enforcement and stable base oil import flows; deviation in regulatory alignment timing or currency volatility affecting Middle Eastern feedstock costs would shift the outlook materially. Forecasts assume fleet consolidation continues concentrating purchasing power into volume-contract arrangements. Deviation in counterfeit product enforcement or electric vehicle adoption acceleration would revise synthetic grade demand projections significantly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
North America Automotive Airfilters Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Global Motorcycle Carbon Ceramic Brake Rotors Market
Automotive Parts
Industrial Brakes Market