
 Global Car Engine Oil Market | 2026-2036
Global Car Engine Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Car Engine Oil Market Analysis
Aftermarket service revenue is narrowing as original equipment manufacturers extend drain intervals and bundle lubricants with warranty programs. ExxonMobil leverages its synthetic oil technology leadership to capture premium positioning in OEM fill contracts. Shell anchors its position through backward integration into base oil refining and additive chemistry. BP competes via Castrol's motorsport-derived brand equity and specialized high-performance formulations.
Car engine oil comprises base oils blended with performance additives to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines, with modern formulations typically ranging from 0W-16 to 10W-40 viscosity grades depending on operating temperature and engine architecture. Synthetic oil commands the dominant margin pool as automakers specify Group III and PAO-based formulations to meet fuel economy mandates, while conventional oil retains volume leadership in emerging markets with older vehicle parc. Passenger vehicles drive the largest application segment, though commercial vehicles generate higher per-unit lubricant consumption and more frequent service intervals.
The EPA in the United States regulates lubricant environmental claims and fuel economy impacts through corporate average fuel economy standards, while REACH in the European Union restricts certain additive chemistries and mandates chemical safety documentation throughout the supply chain. China's MEE enforces national emission standards that cascade into lubricant viscosity and ash content requirements for domestic vehicle production. Stakeholders must monitor how electrification trends and hybrid powertrain proliferation reshape lubricant demand profiles and service frequency assumptions.
Market Dynamics
Extended drain intervals engineered by OEMs are compressing aftermarket service revenue pools while simultaneously elevating lubricant performance specifications toward synthetic formulations.
Growth Catalysts
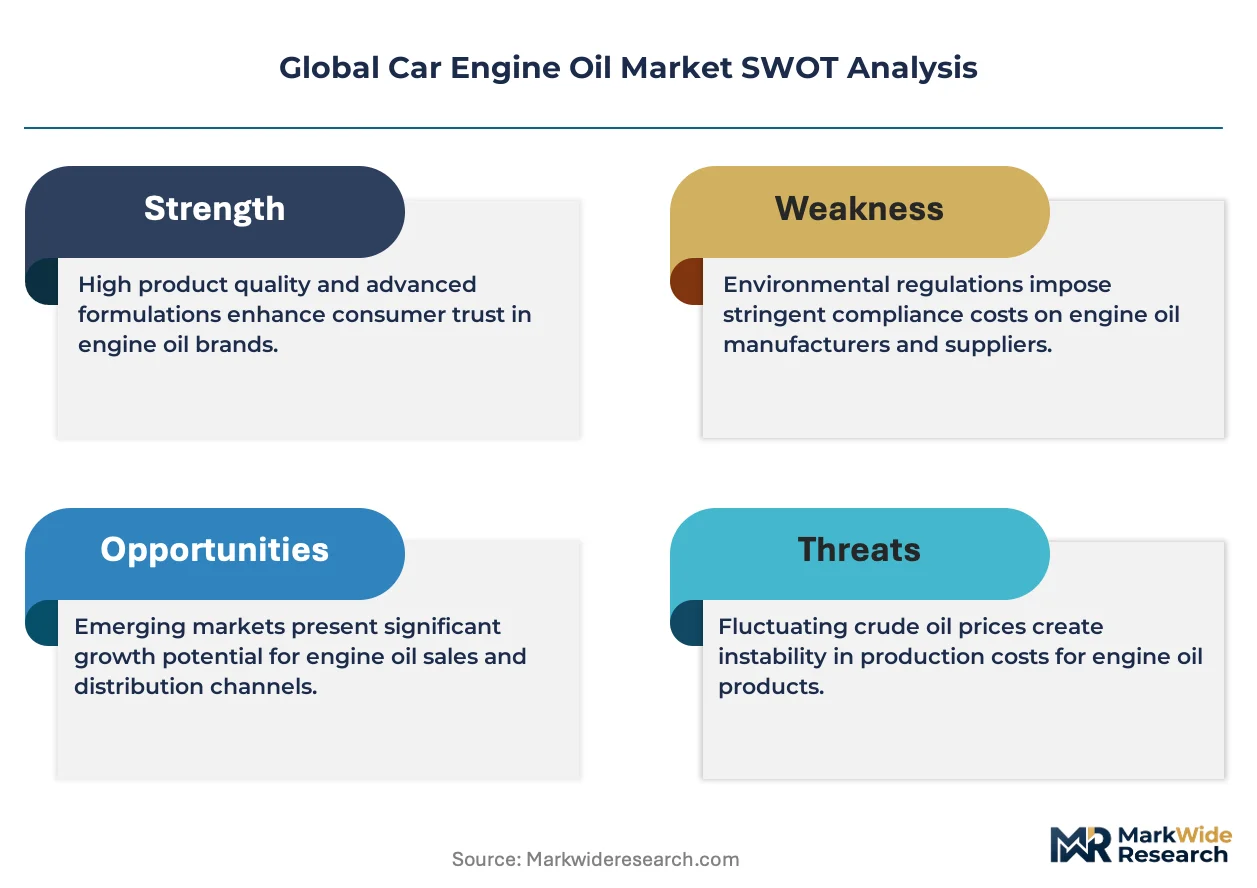
- EU Emissions Standards:Tightening CO2 mandates under the EU Green Deal are forcing automakers to specify lower viscosity grades, directly expanding demand for advanced synthetic formulations in European vehicle production.
- China Vehicle Parc:The world's largest operating passenger vehicle fleet generates sustained volume demand, with domestic OEMs accelerating adoption of Group III base oils to align with MEE national emission requirements.
- Hybrid Powertrain Proliferation:Stop-start engine cycles and thermal management complexity in hybrid architectures are creating specialized lubricant requirements distinct from conventional internal combustion applications.
Market Restraints
- Base Oil Supply Concentration:Group II and Group III base oil production clusters in the US Gulf Coast and Northeast Asia, exposing formulators to geographic concentration risk and freight cost volatility.
- Additive Chemistry Restrictions:REACH regulations in the European Union are constraining zinc dialkyldithiophosphate and other traditional anti-wear chemistries, forcing costly reformulation cycles.
- Electrification Substitution:Battery electric vehicles eliminate engine oil consumption entirely, with BEV sales penetration in Norway and California already compressing addressable market assumptions in those jurisdictions.
Strategic Opportunities
- India Aftermarket Expansion:Underpenetrated synthetic adoption in India's aging vehicle parc creates white space for premium formulation conversion as BS6 emission standards mature.
- Renewable Base Oils:Bio-based and re-refined base oil technologies are converging with circular economy mandates, positioning early movers for EU taxonomy-aligned procurement preferences.
- Direct-to-Workshop Digital Channels:E-commerce platforms and fleet management software are disintermediating traditional distributor networks, enabling margin capture in commercial vehicle service segments.
Industry Challenges
- OEM Approval Timelines:Securing Volkswagen, Mercedes-Benz, and BMW factory-fill certifications requires 18-36 month validation cycles, locking out smaller blenders from premium contract pools.
- Formulation Talent Scarcity:Specialized tribology and additive chemistry expertise is concentrating among legacy suppliers, constraining new entrant R&D capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Car Engine Oil Market |
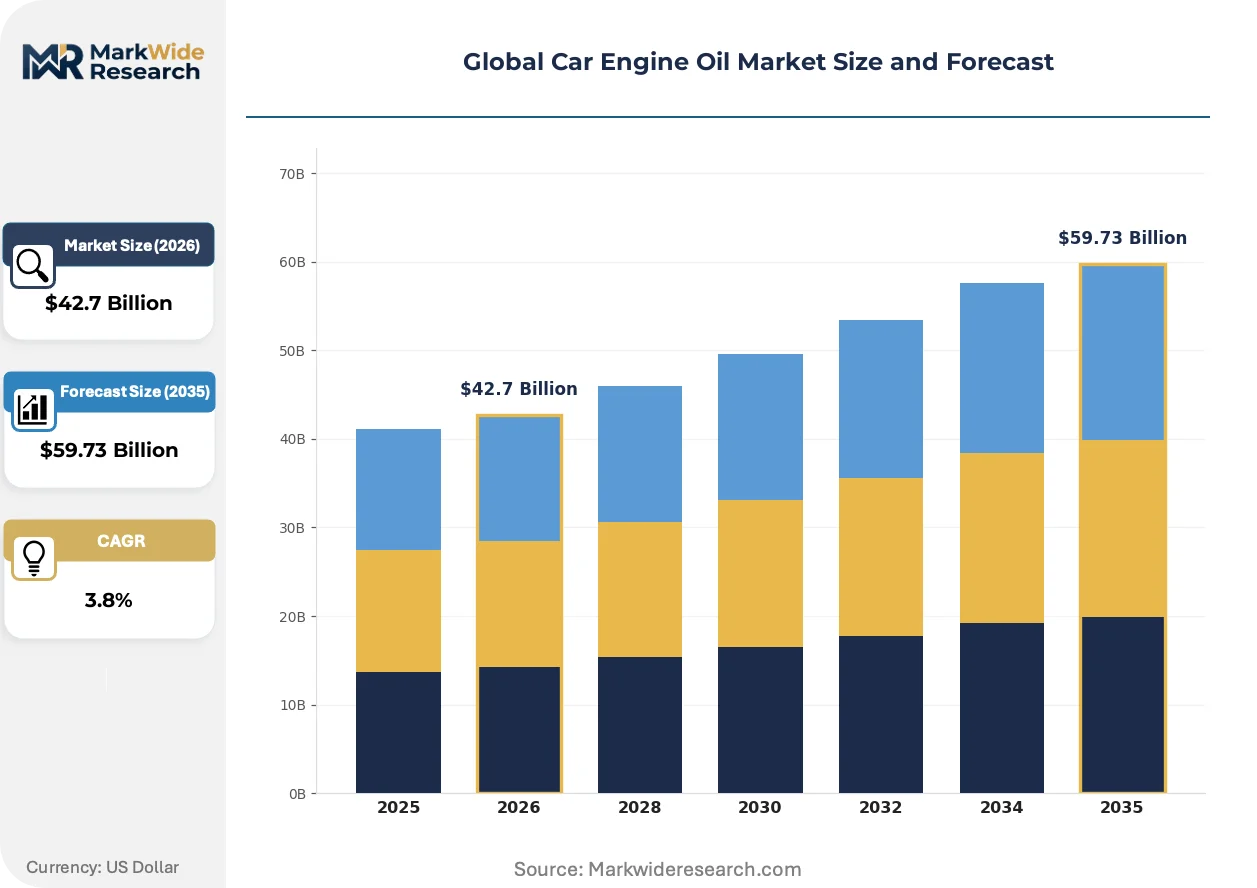
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $59.73 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oil, Conventional Oil, Blended Oil, High Mileage Oil Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy Machinery Service Type: Oil Change, Maintenance Service, Oil Analysis, Lubrication Service Distribution Channel: Retail Stores, Online Platforms, Service Stations, Auto Parts Stores |
| Companies Covered | ExxonMobil, Shell, BP, Chevron Corporation, TotalEnergies, Castrol, Valvoline, Lukoil, Fuchs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Car Engine Oil Market Emerging Trajectories
Formulation science is pivoting toward friction reduction chemistry as fuel economy regulations harden, while digital service models are rewiring how lubricants reach end-users.
Lower viscosity grades are migrating from niche Japanese OEM specifications toward mainstream European and North American factory fill. SAE 0W-16 and 0W-20 formulations reduce hydrodynamic friction losses, enabling automakers to meet corporate average fuel economy targets. The technology is migrating from Toyota and Honda powertrains into Ford and GM light truck engines, compressing historical viscosity grade stratification across vehicle segments.
REACH authorization requirements are restricting boron-containing friction modifiers and certain detergent chemistries across the European supply chain. Formulators must submit comprehensive safety dossiers for additive packages, extending product development timelines by 12-18 months. Passenger vehicle OEMs are responding by consolidating approved supplier lists and demanding pre-certified additive systems from major chemical companies.
Fleet operators are unbundling lubricant procurement from full-service maintenance contracts, creating direct purchasing relationships with blenders and distributors. Large logistics companies in Germany and the United States are negotiating volume commitments separate from workshop labor services, shifting margin allocation toward product suppliers. This pattern is most visible in long-haul trucking segments where telematics-enabled oil analysis supports extended drain interval optimization.
Global Car Engine Oil Market Segmentation
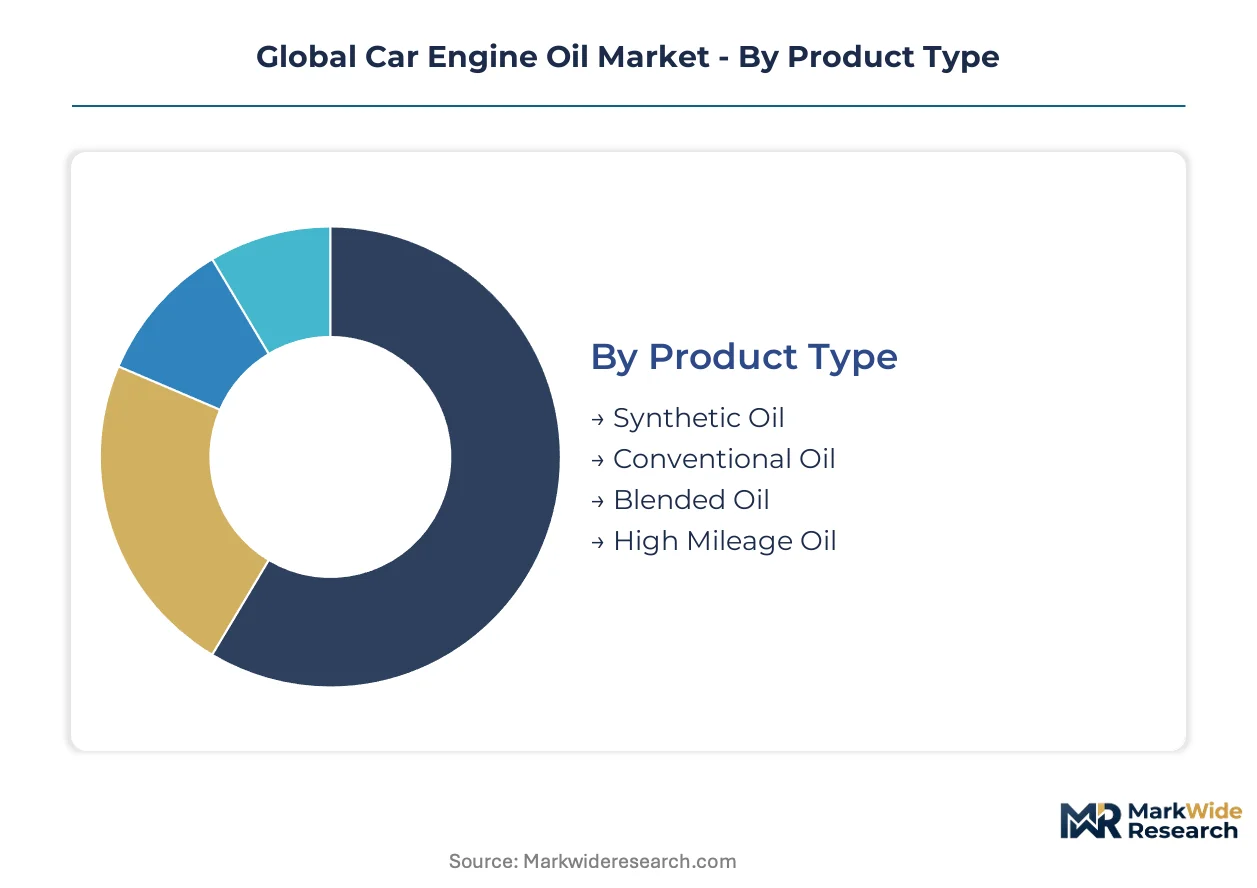
Segmentation in the car engine oil market reveals distinct consumption rhythms across product formulations and service touchpoints. Understanding where volume concentrates versus where margins expand allows suppliers to align R&D investment with profit pool migration.
Product Type:
Cycle times vary dramatically across lubricant chemistries, with synthetic formulations commanding extended drain intervals that compress replacement frequency while elevating per-unit value.
- Synthetic Oil:Group III and PAO-based formulations engineered for thermal stability and low-temperature flow. European OEM factory-fill specifications and China's MEE emission standards are accelerating specification migration toward these advanced chemistries in domestic production.
- Conventional Oil:Mineral base stocks refined from crude oil fractions, historically dominant in price-sensitive service segments. Demand persists in India's aftermarket and Latin American markets with older vehicle parc and less stringent OEM warranty requirements.
- Blended Oil:Semi-synthetic formulations balancing cost and performance for mid-market vehicle owners.
- High Mileage Oil:Seal conditioners and anti-wear additives formulated for engines exceeding 75,000 miles.
Conventional oil anchors the volume base while synthetic oil gains share at the steepest rate.
Application:
Cost tier stratification separates passenger vehicle owners seeking OEM-certified formulations from commercial operators optimizing total cost of ownership through bulk procurement and oil analysis programs.
- Passenger Vehicles:Light-duty cars and SUVs specifying viscosity grades from 0W-16 to 5W-30. German OEM approval systems and US CAFE standards are tightening formulation requirements for this largest addressable segment.
- Commercial Vehicles:Fleets and long-haul trucks consuming higher volumes per unit with more frequent service intervals. Telematics-enabled drain optimization and direct blender relationships are reshaping procurement patterns in German and US logistics sectors.
- Motorcycles:Smaller-displacement engines requiring specialized friction modifiers and wet clutch compatibility.
- Heavy Machinery:Construction and agricultural equipment operating in severe-duty thermal and contamination environments.
Passenger vehicles generate the broadest revenue base while commercial vehicles deliver the highest per-account lifetime value.
Service Type:
Volume concentration clusters in routine oil change intervals, though margin expansion is concentrating in predictive maintenance services that leverage fluid analysis to extend drain cycles.
- Oil Change:Scheduled drain-and-fill services at franchised dealers, independent workshops, and quick-lube chains. Extended OEM intervals are compressing frequency while synthetic conversion elevates ticket averages in US and European service lanes.
- Maintenance Service:Bundled inspections combining lubricant replacement with filter changes and system checks. Warranty program bundling by Volkswagen and BMW is shifting volume toward authorized dealer networks in EU markets.
- Oil Analysis:Laboratory testing of used lubricant to optimize drain intervals and detect mechanical wear.
- Lubrication Service:Specialized applications for chassis, transmission, and auxiliary systems beyond engine crankcase.
Oil change services anchor the volume base while oil analysis gains share at the steepest rate.
Distribution Channel:
Geographic concentration of vehicle parc shapes channel importance, with dense urban corridors favoring quick-service formats and rural markets sustaining traditional auto parts retail.
- Retail Stores:Mass merchandisers and big-box automotive departments serving DIY consumers. US market concentration in Walmart and Costco drives volume through private-label and national brand shelf placement.
- Online Platforms:E-commerce direct-to-consumer and B2B procurement portals. Amazon Business and specialized lubricant distributors are disintermediating traditional wholesale networks in fleet segments.
- Service Stations:Fuel-retail-integrated quick-lube operations.
- Auto Parts Stores:Specialist retailers serving independent repair shops and enthusiast segments.
Retail stores anchor the volume base while online platforms gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, the United States, and Germany each consume car engine oil through fundamentally different service models—extended OEM fill intervals in Germany, high-volume quick-lube chains in the US, and a bifurcated synthetic-conventional split across China's tiered cities.
China
Domestic OEMs SAIC and Geely are accelerating Group III synthetic adoption to meet MEE national emission standards, while conventional oil persists in inland provinces with aging vehicle parc. The Yangtze River Delta lubricant blending cluster around Shanghai supplies both factory-fill contracts and aftermarket distribution, with Ningbo port handling base oil imports from South Korea and Singapore.
United States
Quick-lube chains and Walmart dominate volume through 5W-30 and 0W-20 synthetic formulations, while fleet operators deploy telematics-enabled oil analysis to extend drain intervals. EPA fuel economy standards cascade into CAFE compliance requirements that OEMs address through lower viscosity factory-fill specifications, with the US Gulf Coast base oil complex supplying domestic blenders.
Germany
Volkswagen, Mercedes-Benz, and BMW operate proprietary approval systems that lock factory-fill contracts to pre-certified additive packages, compressing aftermarket share toward authorized dealer networks. REACH restrictions on zinc dialkyldithiophosphate are forcing reformulation cycles, with the Rhine-Ruhr industrial corridor hosting major blending operations serving EU-wide distribution.
India
BS6 emission standards are maturing synthetic conversion in metropolitan markets, though conventional oil retains volume leadership in tier-2 and tier-3 cities with vehicles exceeding 100,000 kilometers. The Maharashtra-Gujarat industrial belt concentrates domestic base oil refining and lubricant blending capacity, with Mumbai port handling additive imports from Singapore and the UAE.
Japan
Toyota and Honda pioneered 0W-16 and 0W-8 ultra-low viscosity specifications now migrating into export powertrains, with domestic demand concentrated in dealer-network service lanes. METI energy efficiency guidelines reinforce lubricant performance requirements, while the Chubu region around Nagoya anchors specialized additive chemistry R&D clusters.
Global Car Engine Oil Market Vendor Landscape
Capability concentration sits with integrated majors possessing captive base oil supply and additive chemistry expertise; scale advantage sits with blenders commanding distribution density in high-volume aftermarket channels. The market structures around three archetypes: vertically integrated oil majors controlling upstream refining, independent specialists with OEM approval depth, and regional blenders competing on price in unregulated segments. Competitive moves center on backward integration into base oil production and digital platform partnerships that disintermediate traditional distributor networks.
Among the integrated majors, ExxonMobil and Shell exemplify the capability-scale intersection, with ExxonMobil representing synthetic technology leadership in OEM fill negotiations and Shell anchoring positions through upstream control over base oil refining. BP occupies a differentiated tier through Castrol's motorsport-derived brand positioning and specialized high-performance formulations. These three companies illustrate how competitive advantage in this market derives from the combination of technical certification depth and supply chain control rather than scale alone.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| BP |
| Chevron Corporation |
| TotalEnergies |
| Castrol |
| Valvoline |
| Lukoil |
| Fuchs |
| Others |
Supply Flow & Price Mechanics
The US Gulf Coast base oil refining cluster around Houston anchors global capacity for Group II and Group III stocks, concentrating upstream supply power among integrated majors who leverage captive feedstock access to dictate formulation premiums downstream. This geographic concentration translates directly into pricing leverage for factory-fill contracts, where OEMs negotiate multi-year offtake agreements against limited alternative sourcing.
Pricing Analysis
Long-term offtake contracts dominate premium synthetic procurement, with Volkswagen and BMW locking in 18-36 month factory-fill commitments that insulate approved suppliers from spot price volatility. Price differentiation rests on OEM certification tier and volume scale, with unapproved blenders competing on transactional spot sales in price-sensitive aftermarket segments. Pricing pressure intensifies in conventional mineral oil tiers as extended drain intervals compress replacement frequency. Fleet operators exhibit lowest price sensitivity due to total cost of ownership optimization, while independent workshops in emerging markets retain highest sensitivity to per-liter differentials.
Supply Chain Analysis
Upstream feedstock for synthetic formulations draws from ethylene crackers and gas-to-liquids facilities concentrated in the United States, South Korea, and Singapore, with Group III output tethered to regional refining economics. Key dependencies include alpha-olefin co-monomers, polyalphaolefin base stocks, and proprietary additive packages from Lubrizol and Infineum. Single-source vulnerability concentrates in specialized friction modifier chemistries facing REACH authorization delays. Distribution runs through authorized dealer networks for OEM-fill volumes, while bulk tanker and drum logistics serve independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated fleet operators and OEM procurement teams, fragmenting traditional distributor influence as direct blender relationships disintermediate legacy channel structures.
For Market Incumbents: Pre-empt electrification-driven volume erosion by deepening synthetic formulation share in hybrid powertrain certifications and securing backward integration into renewable base oil technologies. Lock in multi-year factory-fill extensions with Chinese domestic OEMs before local base oil capacity matures. Prioritize additive chemistry R&D talent retention as REACH restrictions constrain traditional anti-wear compound availability. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated synthetic aftermarket by targeting tier-2 city independent workshops with BS6-compliant Group III formulations priced below Castrol and Shell premiums. Pursue direct-to-workshop digital procurement partnerships with telematics-enabled fleet operators in Germany and the United States. Anchor initial volume through white-label supply contracts with quick-lube chains seeking approved-formulation alternatives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among blenders with captive OEM factory-fill positions and multi-year service contracts, offering superior cash flow predictability versus spot-market-dependent independents. Target acquisition profiles should emphasize additive chemistry R&D depth and regional certification breadth rather than scale alone. Monitor BEV sales penetration in Norway and California as early inflection signals for addressable market compression assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | Captive Group III supply secures margin control against feedstock volatility from South Korean imports. |
| OEM Factory-Fill Certification Investment | Volkswagen and BMW approval systems lock out competitors from premium contract pools. |
| Direct-to-Workshop Digital Platform Launch | Telematics-enabled procurement disintermediates traditional distributor networks in commercial fleet segments. |
| Renewable Base Oil Technology Development | Bio-based formulations align with EU taxonomy procurement preferences and circular economy mandates. |
| Hybrid Powertrain Formulation Specialization | Stop-start thermal management creates distinct lubricant requirements separate from conventional ICE applications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging lubricant blenders, OEM procurement directors, aftermarket distributors, additive chemistry suppliers, and fleet maintenance managers. Secondary validation drew from EPA fuel economy filings, REACH substance dossiers, MEE emission standard notifications, base oil trade customs data, and automotive production registration databases. Bottom-up volume modeling triangulated against top-down market sizing from integrated oil major segment disclosures.
Calibration anchored projections to historical OEM drain interval extensions, synthetic adoption curves in emission-regulated markets, and BEV penetration scenarios across the analysis window. Segmentation dimensions spanned product chemistry tier, vehicle propulsion architecture, service channel type, and regional regulatory cluster. CAGRs derived from slope analysis of viscosity grade migration timelines and factory-fill specification evolution rather than extrapolation of historical growth rates. Hybrid powertrain lubricant content per vehicle served as a critical forecast input.
Sensitivities concentrate around electrification pace, REACH authorization timelines for restricted additive chemistries, and Chinese domestic base oil capacity buildout. Forecasts reflect assumptions regarding OEM warranty bundling persistence and fleet telematics adoption curves. Cross-checking against IHS Markit vehicle production forecasts and national emission standard implementation schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Wiper Blade Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Wind Shield Washer Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Electric Vehicle Fasteners Market