
 Pipelayer Market | 2026-2036
Pipelayer Market Size, Share, and Industry Trends Forecast 2026-2036
Pipelayer Market Analysis
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified OEM suppliers and peripheral equipment traders. Caterpillar Inc. leverages its dealer network density to control aftermarket parts availability across North American oil patch territories. SANY Group anchors its position through aggressive pricing on hydraulic pipelayer models targeting emerging market infrastructure programs. Komatsu Construction differentiates via integrated machine control systems that reduce operator skill requirements on large-diameter pipeline spreads.
A pipelayer is a specialized tracked or wheeled construction machine engineered to lift, position, and align pipe sections into trenches using a counterweighted boom-and-hook assembly rated typically from 40 to over 200 metric tons of lift capacity. Its primary industrial purpose centers on ensuring precise pipe joint alignment and stress-free placement for welded pipeline systems across energy, water, and telecommunications infrastructure. Trenching machines command mature replacement demand in municipal water rehabilitation contracts where aging cast-iron networks require systematic renewal. Hydraulic technology dominates current fleet composition due to proven torque density and field-service familiarity, though electric drive architectures are gaining specification in European urban projects with emissions-restricted worksites. Pipeline layers oriented toward oil and gas operators carry the highest equipment margin pools given specification intensity for all-terrain undercarriages and automated welding compatibility.
EPA emission standards under the Clean Air Act and OSHA excavation safety protocols directly shape engine tier requirements and operator cab design mandates for equipment sold into United States infrastructure projects. State environmental agencies in California and New York enforce supplemental zero-emission equipment procurement rules that filter which machine configurations qualify for public works bidding. Stakeholders must monitor how federal infrastructure spending authorization timelines interact with state-level prevailing wage and domestic content provisions to determine fleet investment sequencing.
Market Dynamics
Water utility underground network replacement programs and EPA underground storage tank regulations are accelerating equipment procurement cycles while concentrating demand in shale corridor midstream operations.
Growth Catalysts
- Lead Service Line Mandates:State-level mandates in the United States are compelling municipal water authorities to accelerate cast-iron network renewal, directly expanding trenching machine replacement demand.
- Shale Midstream Expansion:Permian Basin operators deploy specialized pipeline construction fleets requiring high-lift-capacity pipelayers with all-terrain undercarriage specifications.
- Hydraulic Technology Proliferation:Proven torque density and field-service familiarity sustain hydraulic dominance in current fleet composition across energy infrastructure projects.
Market Restraints
- Steel Input Volatility:Boom-and-hook assembly fabrication faces structural margin pressure from fluctuating high-strength alloy steel prices.
- Emissions Compliance Friction:California and New York zero-emission equipment procurement rules filter qualified machine configurations for public works bidding.
- Electric Drive Technical Limitations:Battery energy density constraints restrict electric pipelayer lift capacity ratings below hydrocarbon-equivalent performance thresholds.
Strategic Opportunities
- European Urban Electrification:Emissions-restricted worksites in Germany and the Netherlands are specifying electric drive architectures for pipeline rehabilitation contracts.
- Automated Welding Convergence:Integration of machine control systems with automated joint welding equipment reduces operator skill requirements on large-diameter spreads.
- Telecommunications Infrastructure:Fiber optic cable burial programs create secondary demand for compact pipelayer configurations in urban utility corridors.
Industry Challenges
- ISO 9001 Certification Timeline:Quality management certification requirements bifurcate OEM suppliers from peripheral traders, extending vendor qualification cycles.
- Operator Skill Compression:Integrated machine control systems demand retraining programs for experienced pipelayer operators transitioning from manual boom positioning.
- Domestic Content Compliance:Federal infrastructure spending authorization interacts with prevailing wage provisions to complicate fleet investment sequencing for contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipelayer Market |
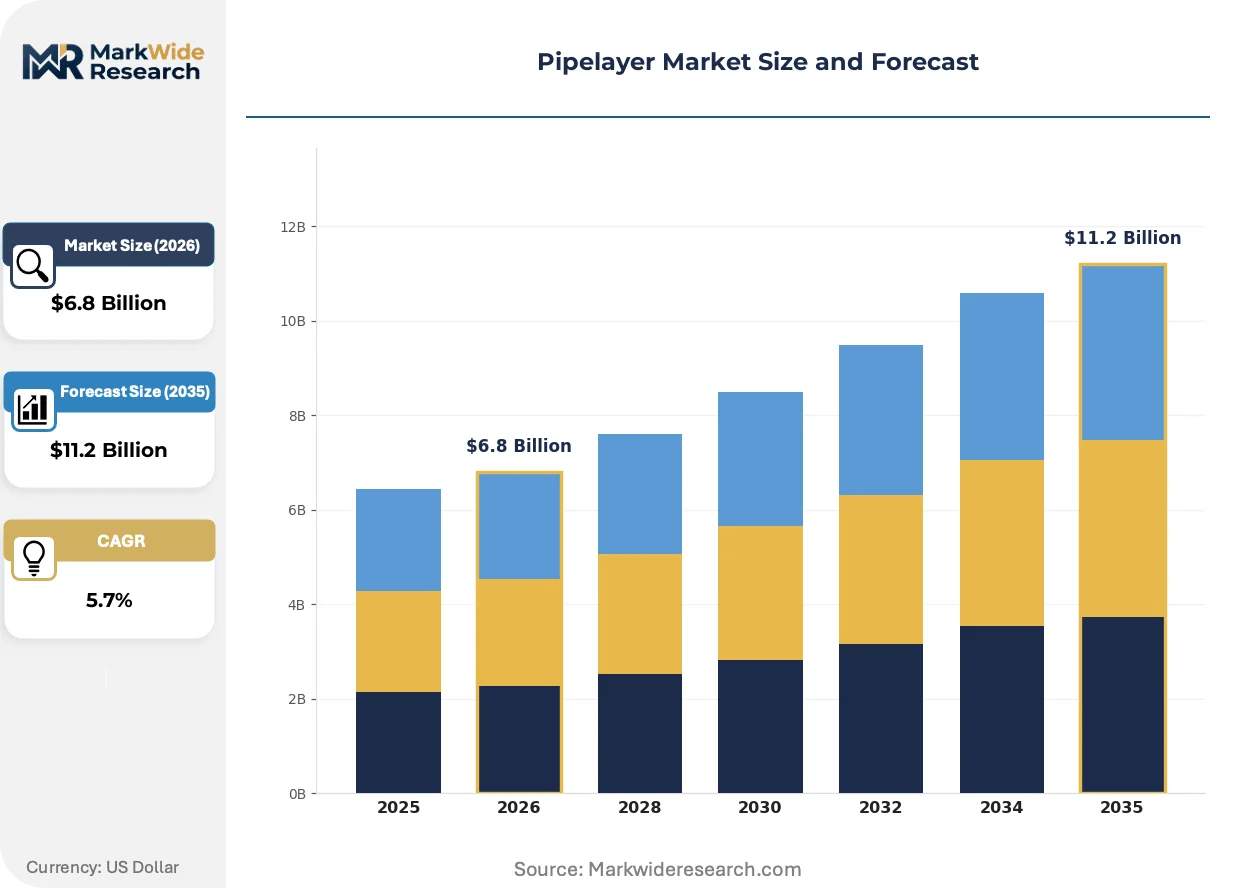
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trenching Machines, Pipeline Layers, Paving Machines, Roller Machines Technology: Hydraulic, Electric, Pneumatic, Mechanical End User: Construction Companies, Oil & Gas Operators, Water Utility Firms, Municipalities Application: Water Supply, Natural Gas Distribution, Sewage Systems, Telecommunications |
| Companies Covered | John Deere, SANY Group, Caterpillar Inc., Herrenknecht AG, Shantui Group, Volvo Group, Liebherr Group, Midwestern Manufacturing, Komatsu Construction, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipelayer Market Emerging Trajectories
Equipment specification intensity is reshaping competitive differentiation around emissions architecture, automation integration, and aftermarket parts availability control.
Electric drive architectures are bifurcating the product landscape between emissions-compliant urban configurations and conventional hydraulic models for unrestricted worksites. European municipal contractors in Germany and the Netherlands are specifying battery-electric pipelayers for pipeline rehabilitation in restricted zones. This technology is bifurcating fleet procurement strategies as rental houses maintain dual-technology inventories to serve divergent regulatory environments.
EPA Clean Air Act engine tier requirements and OSHA excavation safety protocols are mandating redesigned operator cabs and exhaust after-treatment systems for United States infrastructure eligibility. Equipment sold into federally funded projects must satisfy simultaneous federal emissions standards and state supplemental rules. Oil and gas operators in Texas and North Dakota are absorbing compliance costs through longer equipment holding periods rather than accelerated replacement cycles.
After-sales service unbundling is disrupting traditional dealer-dependent maintenance relationships in North American oil patch territories. Midstream operators are negotiating direct parts procurement agreements with component suppliers to reduce downtime exposure on remote pipeline spreads. This pattern is most visible in Permian Basin operations where fleet utilization rates exceed 85 percent and parts availability directly determines project schedule adherence.
Pipelayer Market Segmentation
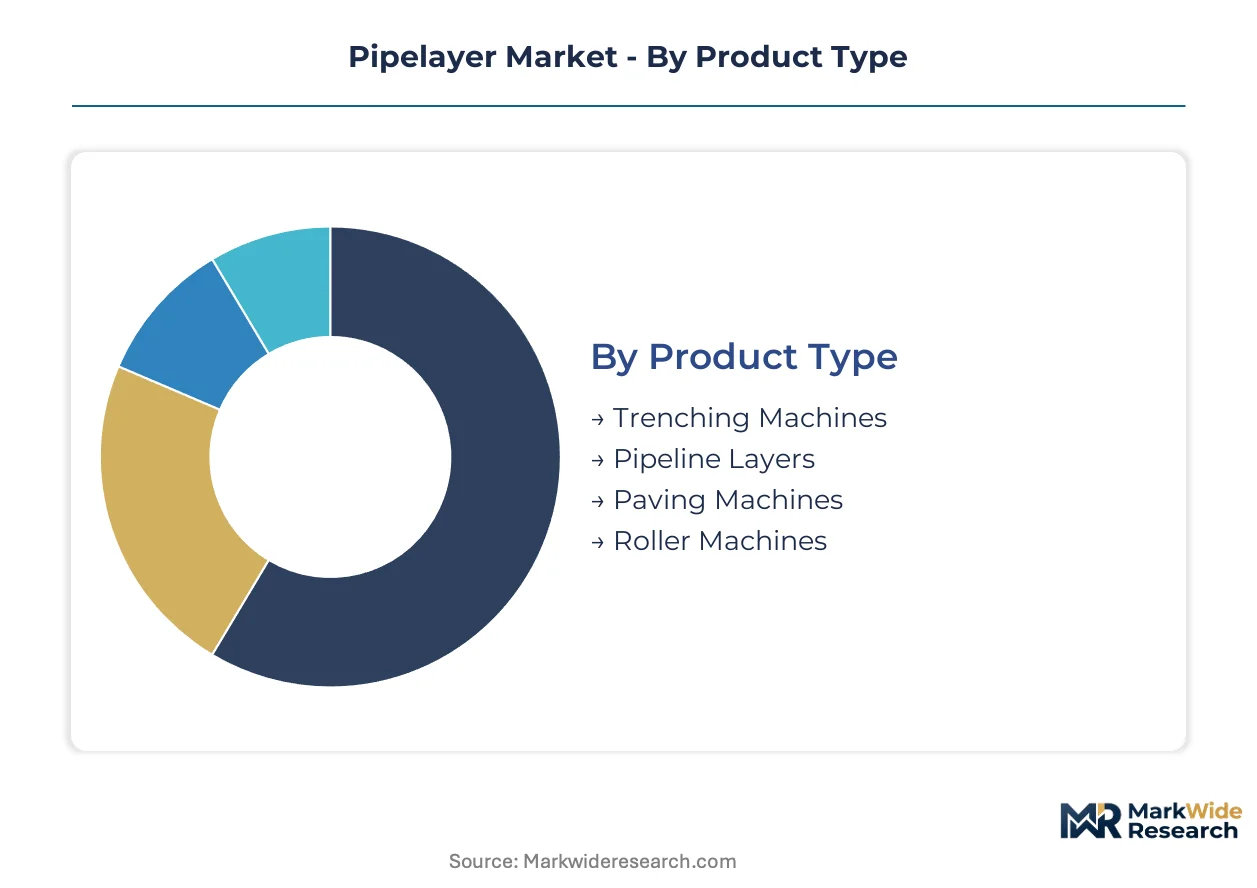
Pipelayer market segmentation reveals divergent procurement patterns across energy infrastructure, municipal water networks, and telecommunications burial programs. Equipment specification intensity varies sharply between shale corridor operators requiring high-lift capacity and urban utilities constrained by emissions-restricted worksites.
Product Type:
Domestic demand concentrates in pipeline layers for Permian Basin midstream operations, while trenching machines see export-led momentum into European water rehabilitation contracts.
- Pipeline Layers:Counterweighted boom-and-hook assemblies rated 40-200 metric tons dominate oil and gas infrastructure. Permian Basin operators specify all-terrain undercarriages and automated welding compatibility for large-diameter spreads.
- Trenching Machines:Mature replacement demand centers on municipal water rehabilitation where aging cast-iron networks require systematic renewal. EPA underground storage tank regulations and state lead service line mandates accelerate procurement cycles in United States markets.
- Paving Machines:Secondary pipeline support equipment for road restoration post-trenching.
- Roller Machines:Compaction equipment for pipeline bedding and backfill operations.
Pipeline layers hold the largest share; momentum sits with trenching machines.
Technology:
Cost tier bifurcation separates premium hydraulic systems from emerging electric configurations priced at significant premiums for emissions compliance.
- Hydraulic:Proven torque density and field-service familiarity sustain dominance across energy infrastructure fleets. Oil and gas operators in Texas and North Dakota absorb compliance costs through extended holding periods rather than technology transitions.
- Electric:Battery energy density constraints restrict lift capacity below hydrocarbon-equivalent thresholds. German and Dutch municipal contractors specify these for restricted urban worksites under supplemental zero-emission procurement rules.
- Pneumatic:Niche applications in specialized trenching environments.
- Mechanical:Legacy systems in developing market rental fleets.
Hydraulic systems command the largest share; electric architectures are expanding most quickly in European urban specifications.
End User:
Application maturity separates established oil and gas procurement from emerging telecommunications demand.
- Oil & Gas Operators:Shale midstream expansion in the Permian Basin drives specification intensity for high-lift-capacity equipment. Fleet utilization rates exceeding 85 percent force direct parts procurement agreements to reduce downtime exposure on remote spreads.
- Water Utility Firms:Underground network replacement programs accelerate equipment cycles under EPA and state regulatory pressure. Municipal authorities face lead service line mandates compelling cast-iron network renewal.
- Construction Companies:General infrastructure contractors serving diversified project portfolios.
- Municipalities:Direct procurement for public works with prevailing wage and domestic content compliance requirements.
Oil and gas operators hold the largest share; water utility firms are gaining share fastest on regulatory acceleration.
Application:
Volume concentration in energy infrastructure contrasts with margin opportunities in restricted-environment telecommunications burial.
- Natural Gas Distribution:Midstream pipeline construction commands the highest equipment margin pools given specification intensity for all-terrain performance. FERC-regulated interstate projects drive fleet investment sequencing.
- Water Supply:Municipal rehabilitation programs create sustained replacement demand for trenching configurations. State environmental agencies in California and New York enforce zero-emission equipment rules filtering qualified machine configurations.
- Sewage Systems:Underground infrastructure renewal parallel to water supply networks.
- Telecommunications:Fiber optic cable burial programs create secondary demand for compact pipelayer configurations in urban utility corridors with emissions restrictions.
Natural gas distribution holds the largest share; telecommunications is climbing the fastest on infrastructure digitization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA underground storage tank regulations and state-level lead service line mandates are accelerating equipment procurement cycles across municipal water authorities. Shale corridor midstream operators in Texas and North Dakota deploy specialized pipeline construction fleets with utilization rates exceeding 85 percent. Equipment specification intensity bifurcates between emissions-restricted urban worksites and unrestricted energy infrastructure zones.
United States
Permian Basin shale operators drive demand for high-lift-capacity pipelayers with all-terrain undercarriage specifications. EPA Clean Air Act engine tier requirements and OSHA excavation safety protocols mandate redesigned operator cabs and exhaust after-treatment systems for federal project eligibility. Houston-Gulf Coast corridor contractors absorb compliance costs through extended equipment holding periods rather than accelerated replacement cycles.
Germany
Municipal contractors specify battery-electric pipelayers for pipeline rehabilitation in emissions-restricted urban zones. EU Green Deal implementation and national zero-emission equipment procurement rules filter qualified machine configurations for public infrastructure bidding. Rhine-Ruhr industrial cluster utilities are systematically renewing aging cast-iron water networks under federal infrastructure modernization programs.
China
State-led pipeline construction programs for natural gas distribution expansion sustain demand for hydraulic pipelayer configurations. MIIT equipment emission standards and GB certification requirements shape domestic manufacturer product development priorities. Yangtze River Delta infrastructure contractors are deploying specialized fleets for urban utility corridor fiber optic burial alongside water network renewal.
Canada
Oil sands midstream operators in Alberta require heavy-lift pipelayers rated for extreme cold-weather performance specifications. Health Canada environmental regulations and provincial emissions standards govern equipment eligibility for federally funded energy infrastructure projects. Calgary-Edmonton corridor contractors maintain dual-technology inventories to serve divergent regulatory environments across provincial boundaries.
Australia
Mining-linked pipeline construction for iron ore and coal transport infrastructure drives demand for high-capacity tracked pipelayers. TGA-equivalent equipment safety standards and state environmental protection regulations influence procurement specifications for remote site operations. Western Australia Pilbara region operators prioritize parts availability control through direct component supplier agreements to reduce downtime exposure.
Pipelayer Market Vendor Landscape
Listed leaders compete with private specialists across technology architecture and aftermarket service models. The vendor base separates into consolidated multinational OEMs controlling distribution density, mid-scale regional fabricators competing on price-positioning, and specialized component suppliers unbundling after-sales relationships. Three strategic archetypes dominate: full-line construction equipment conglomerates, dedicated pipeline machinery specialists, and emerging-market cost competitors. Competitive moves concentrate on dealer network expansion and direct parts procurement agreements with midstream operators.
Within the full-line equipment tier, Caterpillar Inc. and Komatsu Construction exemplify multinational OEMs leveraging dense service networks to control aftermarket parts availability across North American oil patch territories. SANY Group occupies a position among emerging-market cost competitors targeting aggressive pricing on hydraulic configurations for infrastructure programs in developing economies. These three anchors illustrate how competitive positioning separates around distribution control, technology integration, and price-access trade-offs.
| Leading Market Players |
|---|
| John Deere |
| SANY Group |
| Caterpillar Inc. |
| Herrenknecht AG |
| Shantui Group |
| Volvo Group |
| Liebherr Group |
| Midwestern Manufacturing |
| Komatsu Construction |
| Others |
Supply Flow & Price Mechanics
ISO 9001 quality management certification gates both supply qualification and price differentiation in the pipelayer market, bifurcating OEM suppliers from peripheral traders while creating tiered pricing spreads based on documented quality assurance protocols. Municipal water authorities and shale operators face divergent procurement economics as certification-compliant configurations command substantial premiums over uncertified alternatives.
Pricing Analysis
Certification level (ISO 9001, CE marking for EU eligibility) creates the primary spread between premium OEM configurations and economy-tier peripheral equipment. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels reflects divergent buyer requirements, with oil and gas operators absorbing compliance premiums through extended holding periods rather than volume discounting. Cost compression in economy hydraulic tiers is intensifying because emerging-market cost competitors flood rental house inventories with aggressive positioning. Municipal water authorities exhibit highest price sensitivity due to prevailing wage and domestic content constraints, while Permian Basin midstream operators prioritize specification intensity over unit economics.
Supply Chain Analysis
Port congestion on Asia-North America trade lanes elevates inbound logistics costs for hydraulic component shipments originating from Chinese and South Korean manufacturing clusters. Boom-and-hook assembly fabrication draws from high-strength alloy steel mills in China, Germany, and Japan, with engine powertrain sourcing anchored in Japanese and German Tier 1 supplier networks. Single-source vulnerability concentrates in specialized undercarriage track systems from limited qualified foundries. Distribution runs through dense dealer networks for aftermarket parts availability control, though midstream operators increasingly negotiate direct procurement agreements with component suppliers to reduce downtime exposure on remote pipeline spreads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across emissions-restricted urban worksites and unrestricted energy corridors creates niche specialization opportunities for equipment configurations targeting divergent compliance environments.
For Market Incumbents: Compound dealer network density advantages by integrating predictive maintenance telemetry into service contracts, locking in aftermarket revenue streams against emerging direct-parts-procurement threats from Permian Basin operators. Extend certification investment into battery-electric architectures to preempt European municipal contractor specification shifts under EU Green Deal procurement rules. For New Entrants and Emerging Players: Aftermarket service unbundling in North American oil patch territories exposes white-space opportunity for specialized component suppliers offering direct fulfillment partnerships with midstream operators seeking schedule adherence guarantees. Target telecommunications fiber burial programs as the most penetrable application segment, deploying compact electric configurations through rental house channel partnerships rather than direct OEM competition. For Investors and Strategic Acquirers: EPA Clean Air Act engine tier implementation timelines reshape the acquisition landscape toward dual-technology fleet operators capable of serving both emissions-restricted and unrestricted project environments. Long-term viability centers on manufacturers with demonstrated electric architecture development pipelines and established dealer service density. Monitor state-level zero-emission equipment procurement rule adoption velocity as the critical inflection signal for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Architecture Development | Battery-electric configurations unlock bidding eligibility under California and New York zero-emission procurement mandates. |
| Dealer Network Densification | Service proximity controls aftermarket parts availability for Permian Basin operators facing 85-percent-plus utilization rates. |
| Direct Component Supplier Agreements | Unbundled procurement relationships reduce downtime exposure for remote pipeline spread operations. |
| ISO 9001 Certification Investment | Quality management documentation gates municipal water authority bidding and separates OEMs from peripheral traders. |
| Machine Control System Integration | Automated welding compatibility reduces operator skill requirements on large-diameter pipeline spreads. |
Methodological Framework
A spread of perspectives from equipment procurement managers at midstream operators, municipal water authority engineering directors, rental house fleet managers, and aftermarket service heads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA regulatory filings, FERC project authorization databases, state environmental agency procurement rule publications, and OEM technical specification documentation. Bottom-up equipment shipment tallies triangulated against top-down infrastructure spending authorization estimates to anchor volume projections.
Segmentation dimensions modeled encompass product type (pipeline layers, trenching machines, paving equipment, compaction rollers), technology architecture (hydraulic, electric, pneumatic, mechanical), end-user category (oil and gas operators, water utility firms, construction contractors, municipalities), and application (natural gas distribution, water supply, sewage systems, telecommunications burial). CAGRs were derived through regression analysis of historical procurement cycles against regulatory mandate implementation timelines, with shale corridor utilization rates and European electrification adoption curves as industry-specific forecast inputs across the projection horizon.
Material uncertainties — steel input cost volatility, battery energy density breakthrough timing, federal infrastructure spending authorization delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance trajectory and equipment replacement cycle elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Stair Lifts and Climbing Devices Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Global Submersible Slurry Pumps Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Container Handling Equipment Market