
 AAA Battery Market | 2026-2036
AAA Battery Market Size, Share, and Industry Trends Forecast 2026-2036
AAA Battery Market Insights
The premium alkaline segment is consolidating around extended-life formulations and mercury-free certifications, while commodity zinc-carbon tiers compete on shelf price alone. Duracell leverages its Ultra line to sustain brand loyalty in high-drain consumer electronics. Energizer anchors North American retail placement through exclusive retail partnerships. Panasonic differentiates via lithium primary cells for medical and industrial applications.
AAA batteries are cylindrical dry cells measuring 10.5 mm in diameter and 44.5 mm in length, delivering nominal voltages from 1.2 V to 1.5 V depending on chemistry, designed for portable low-to-moderate drain devices. Alkaline chemistry occupies the volume core of consumer replacement cycles, while lithium variants command margin premiums in temperature-critical medical devices. Rechargeable NiMH segments are gaining traction in toys and consumer electronics as sustainability preferences harden.
EPA hazardous waste rules and EU REACH substance restrictions shape permissible chemistries and end-of-life obligations for manufacturers selling across multiple jurisdictions. The EU Battery Regulation mandates recycled content thresholds and digital battery passports, altering supply chain documentation burdens. Stakeholders must monitor evolving chemistry bans and extended producer responsibility frameworks to anticipate compliance-driven cost reallocations.
Market Dynamics
EU Battery Regulation mandates are compressing supply chain documentation burdens while medical device procurement concentrates demand for lithium primary cells in Germany's industrial corridor, forcing chemistry diversification and recycled content compliance across all tiers.
Growth Catalysts
- EU Battery Regulation recycled content thresholds:Mandates for recovered lithium, cobalt, and nickel are pulling investment into European recycling infrastructure and battery passport digitization.
- Medical device OEM procurement:Precision instrument manufacturers in Germany are expanding long-term supply agreements for lithium primary cells with temperature-stable discharge profiles.
- Mercury-free certification requirements:REACH substance restrictions and state-level bans in the US are eliminating legacy chemistries and accelerating alkaline formulation upgrades.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress margin predictability for premium cell producers dependent on South American and Australian supply.
- East Asian cathode powder concentration:Supply risk concentrates in Chinese and South Korean precursor material production, creating single-source vulnerability for European and North American assemblers.
- Alkaline energy density ceiling:Zinc-manganese dioxide chemistry hits physical limits in high-drain applications, ceding ground to lithium variants regardless of cost.
Strategic Opportunities
- Indian consumer electronics assembly:PLI scheme incentives for local device manufacturing are creating captive demand for NiMH and alkaline cell sourcing within the subcontinent.
- Digital battery passport services:Compliance-as-a-service platforms can capture value from EU Battery Regulation documentation mandates across mid-tier producers lacking in-house traceability systems.
- Industrial IoT sensor networks:Ultra-low-power wireless protocols are extending replacement cycles and favoring lithium primary cells with decade-long shelf stability.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell formulation expertise pools narrowly in Japan and South Korea, constraining European and North American R&D expansion timelines.
- Dual chemistry production line capex:Alkaline and lithium cell manufacturing require incompatible dry-room and electrolyte handling infrastructure, complicating portfolio diversification.
- EU Battery Regulation certification lag:Digital passport system integration and third-party conformity assessment timelines are delaying product launches by 8-14 months for non-integrated producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AAA Battery Market |
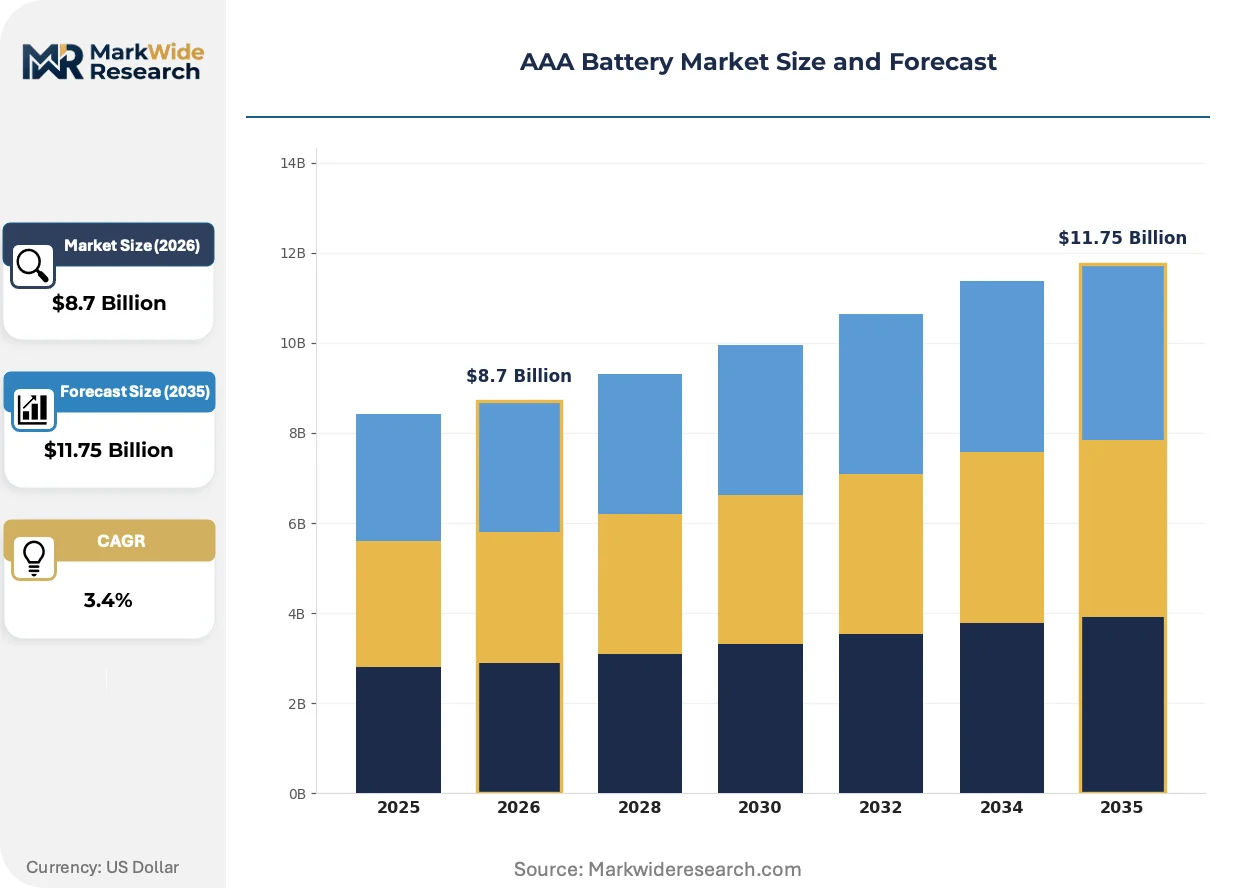
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, Lithium, Rechargeable NiMH, Zinc-Carbon End User: Consumer Electronics, Toys, Medical Devices, Industrial Equipment Technology: Chemical Energy Storage, Dry Cell, Fuel Cell, Solid-State Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale Distributors |
| Companies Covered | Duracell, Energizer, Panasonic, Rayovac, Varta, Sony, Maxell, GP Batteries, Eveready, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AAA Battery Market Trends and Innovations
Solid-state electrolyte research and digital traceability mandates are compressing traditional chemistry cycles while medical-grade reliability standards permeate consumer tiers.
Lithium iron disulfide (LiFeS2) primary chemistry is unifying high-drain performance with cold-temperature stability in a single cell format. Medical device OEMs in Germany and precision instrument clusters are adopting this chemistry for field-deployed diagnostic equipment. The technology is unifying what previously required separate alkaline and lithium battery inventories into standardized procurement streams.
EU Battery Regulation digital passport requirements are mandating full lifecycle traceability from raw material extraction to recycling. Cell assemblers must now integrate blockchain-verified chain-of-custody documentation into every SKU. Premium tier producers with existing ERP sophistication are capturing compliance margin while commodity tiers face documentation cost compression.
Hospital procurement consortia are consolidating battery purchasing across diagnostic, monitoring, and implantable device categories. Group purchasing organizations are replacing individual department spot-buying with multi-year chemistry-agnostic supply agreements. This consolidation is most visible in Germany's university hospital networks and radiology equipment clusters.
AAA Battery Market Segmentation
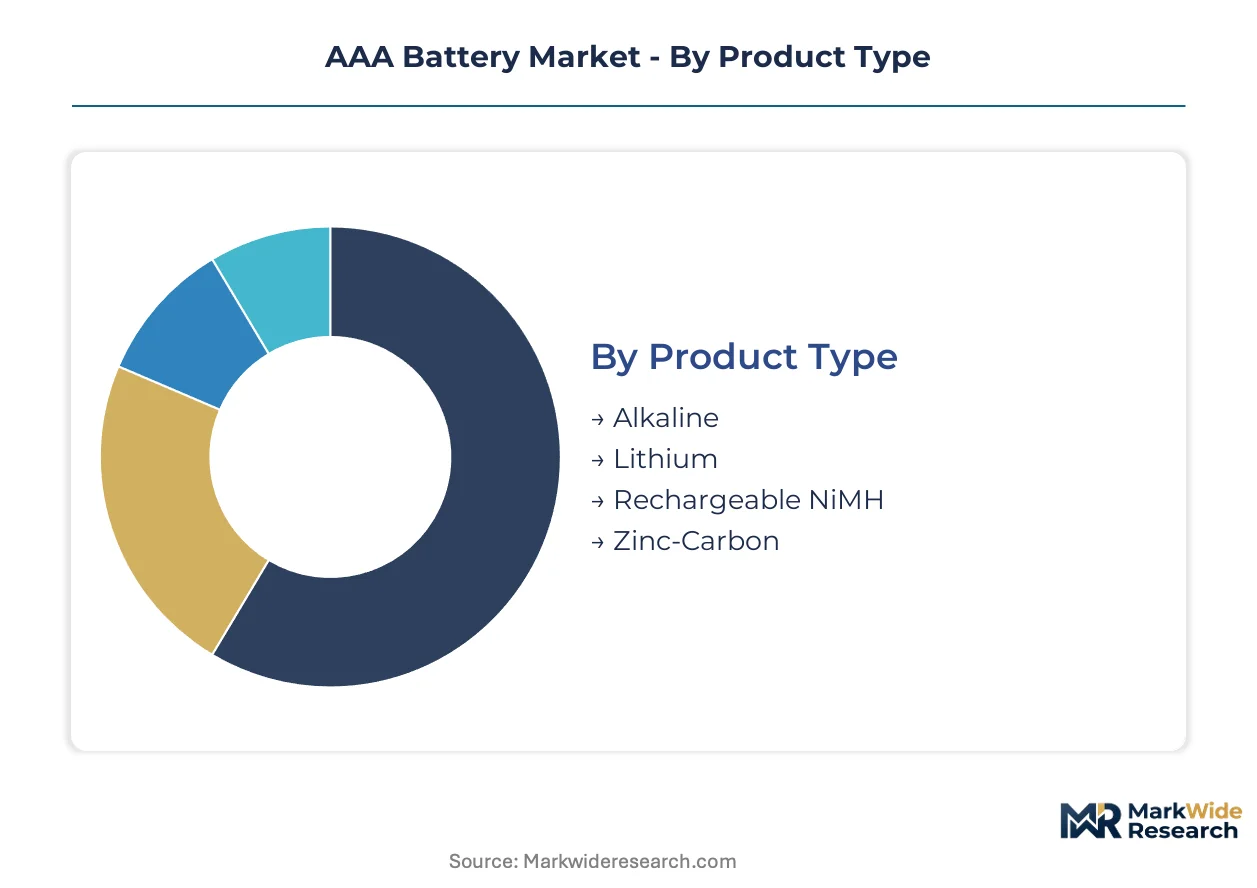
AAA battery segmentation reveals divergent margin structures across chemistries and channels. Embedded medical applications command lithium premiums while standalone consumer replacement cycles anchor alkaline volume.
Product Type:
Integration depth separates standalone replacement purchases from embedded OEM supply chains, with chemistry choice driven by discharge profile requirements.
- Alkaline:Zinc-manganese dioxide cells deliver 1.5V nominal voltage with shelf-stable chemistry optimized for intermittent-use devices. Volume concentrates in German and US retail replacement cycles for remote controls and flashlights, constrained by physical energy density ceilings in high-drain applications.
- Lithium:Lithium iron disulfide chemistry achieves superior cold-temperature performance and decade-long shelf stability with 1.5V output. Demand clusters in Germany's precision instrument corridor for field-deployed diagnostic equipment, pulled by EU Battery Regulation traceability mandates requiring digital passport documentation.
- Rechargeable NiMH:Nickel-metal hydride cells offer 1.2V output with 500-1000 cycle lifespans for high-frequency use cases. India's PLI scheme incentives for local electronics assembly are expanding captive procurement of NiMH cells for toy and consumer device manufacturing.
- Zinc-Carbon:Leclanché-derived chemistry provides lowest-cost 1.5V output for price-sensitive intermittent applications. Shelf price competition dominates positioning in emerging market convenience retail.
Volume placements concentrate in Alkaline; the faster expansion belongs to Lithium.
End User:
Application maturity dictates procurement sophistication, from spot retail purchases to multi-year OEM supply agreements with embedded traceability requirements.
- Consumer Electronics:Wireless peripherals, remote controls, and portable audio devices drive replacement cycle demand through retail channels. Extended-life alkaline formulations capture loyalty in high-drain applications.
- Toys:High-drain motorized products and electronic learning devices create seasonal demand spikes. NiMH rechargeable adoption is climbing fastest as sustainability preferences harden among parent purchasers.
- Medical Devices:Diagnostic monitors, infusion pumps, and implantable equipment require temperature-stable discharge profiles with failure-rate guarantees. German hospital procurement consortia are consolidating multi-year chemistry-agnostic supply agreements across university hospital networks.
- Industrial Equipment:Wireless sensor networks and portable instrumentation favor lithium primary cells with ultra-low self-discharge for decade-long deployment cycles. EU Battery Regulation recycled content thresholds are reshaping supplier qualification criteria.
Procurement sophistication stratifies across Medical and Industrial tiers; Consumer Electronics maintains the broadest geographic footprint.
Technology:
Cost tier alignment separates mature mass-production chemistries from emerging solid-state architectures with capital-intensive manufacturing requirements.
- Chemical Energy Storage:Electrochemical redox reactions in alkaline, lithium, and zinc-carbon formats dominate current production volumes. Established supply chains and automated winding equipment support cost-efficient scale.
- Dry Cell:Aqueous electrolyte-free construction defines portable primary battery architecture. Leakage resistance and orientation independence sustain relevance in consumer replacement markets.
- Fuel Cell:Hydrogen or methanol-fed electrochemical conversion offers theoretical energy density advantages. Miniaturization challenges and fuel cartridge logistics constrain AAA-scale deployment.
- Solid-State:Ceramic or polymer electrolyte architectures promise enhanced safety and energy density. Research-stage development with Japanese and South Korean electrochemical engineering pools leading cell formulation advances.
Manufacturing scale concentrates in Chemical Energy Storage; Solid-State holds the steepest expansion trajectory contingent on dry-room infrastructure maturation.
Distribution Channel:
Customer type separation distinguishes impulse replacement purchases from planned procurement with contract terms and technical specifications.
- Online Retail:E-commerce platforms capture bulk purchasing and subscription replacement programs with transparent price comparison. Digital battery passport compliance services are emerging as value-add differentiation.
- Supermarkets:Mass merchandisers anchor alkaline volume through end-cap placement and private-label competition. Mercury-free certification visibility influences shelf positioning decisions.
- Convenience Stores:Emergency replacement purchases at premium per-unit pricing sustain zinc-carbon relevance. Location density near residential clusters determines competitive positioning.
- Wholesale Distributors:B2B supply to OEMs and institutional buyers requires lot traceability and certificate-of-analysis documentation. EU Battery Regulation mandates are compressing mid-tier producers lacking in-house ERP sophistication.
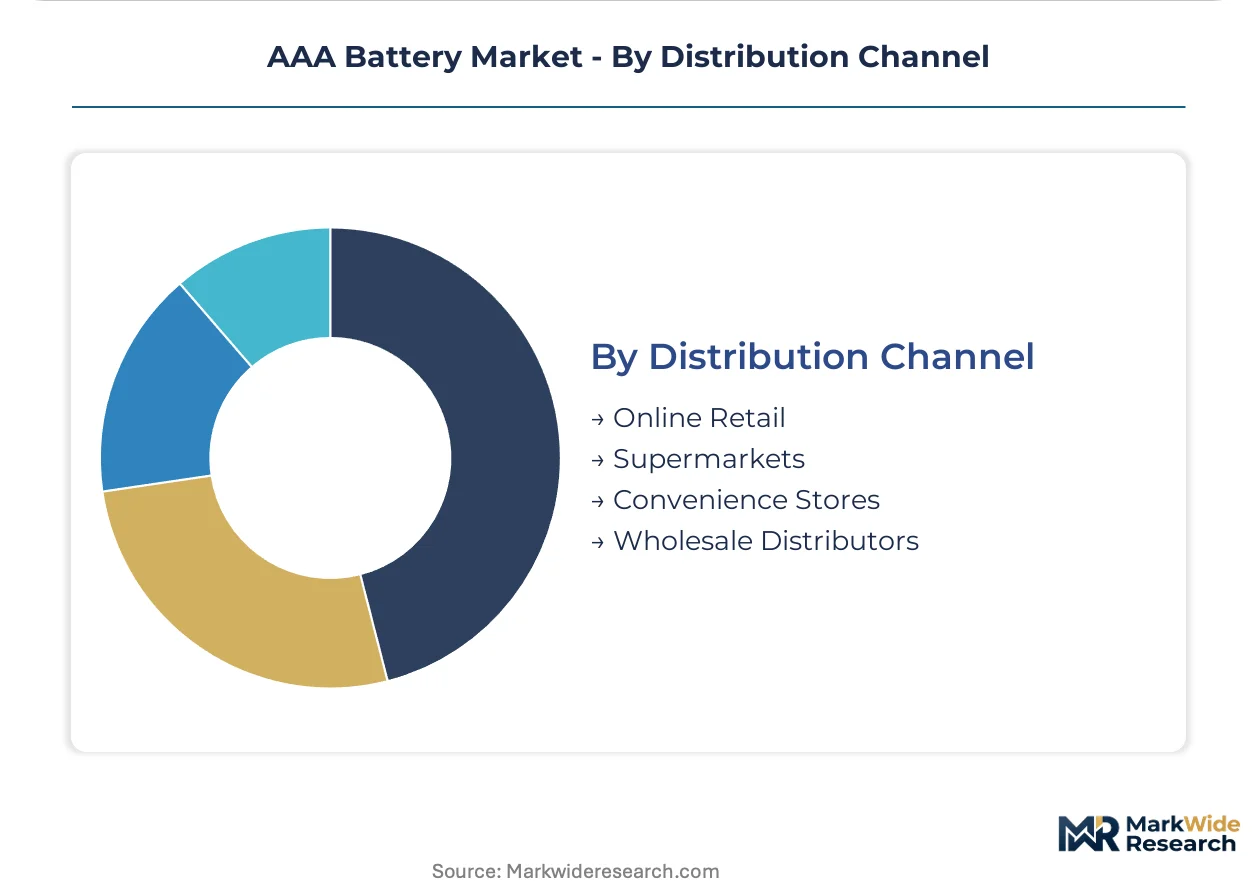
Margin capture concentrates in Wholesale Distributors; Online Retail is gaining share fastest through subscription model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision instrument corridor along the Rhine-Main-Neckar region concentrates lithium primary cell procurement for medical device OEMs, while regulatory divergence across major economies fragments compliance strategies.
United States
EPA hazardous waste rules and state-level mercury bans reshape permissible chemistries for alkaline producers. FDA device regulations drive reliability standards for medical-grade lithium cells. Boston's medical device cluster and Detroit's industrial automation belt sustain dual chemistry demand streams.
Germany
EU Battery Regulation recycled content thresholds force supply chain documentation upgrades for cell assemblers. ECHA REACH substance restrictions eliminate legacy mercury formulations. The Rhine-Main industrial corridor hosts precision instrument makers expanding long-term lithium primary supply agreements.
China
MIIT battery industry standards and dual carbon goals accelerate domestic recycling infrastructure investment. NMPA medical device regulations align with international reliability benchmarks. Shenzhen's consumer electronics assembly ecosystem and Shanghai's chemical precursor production dominate alkaline and lithium cathode supply.
India
PLI scheme incentives for local electronics manufacturing create captive NiMH and alkaline demand from toy and device assemblers. BIS certification requirements tighten quality thresholds for imported cells. Tamil Nadu's electronics manufacturing clusters and Gujarat's chemical processing zones concentrate new cell procurement.
Japan
METI energy storage policy frameworks support solid-state electrolyte research programs. PMDA medical device regulations mandate failure-rate documentation for implantable power sources. Osaka-Kobe's electrochemical engineering talent pools and Nagoya's precision manufacturing base sustain premium lithium cell development.
AAA Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across chemistry certification tiers, with lithium primary specialists commanding reliability premiums while zinc-carbon assemblers compete on shelf price alone. The vendor base stratifies into three functional tiers: multinational chemistry-agnostic portfolios, regional alkaline specialists, and niche lithium primary producers. Dominant competitive moves include backward integration into precursor material production and digital battery passport service layering for EU compliance.
Within the multinational chemistry-agnostic tier, Duracell and Energizer occupy positions exemplifying brand-anchored retail placement strategies, while Panasonic represents the industrial-medical specialization archetype with lithium primary focus. These three entities sit within distinct margin structures: alkaline volume leadership, North American retail exclusivity, and temperature-stable medical-grade supply respectively.
| Leading Market Players |
|---|
| Duracell |
| Energizer |
| Panasonic |
| Rayovac |
| Varta |
| Sony |
| Maxell |
| GP Batteries |
| Eveready |
| Others |
Pricing and Supply Chain Analysis
Lithium primary certification tiers split alkaline commodity producers from medical-grade specialists, with EU Battery Regulation compliance costs embedding in premium pricing while zinc-carbon assemblers compete on shelf price alone. This bifurcation concentrates margin capture among passport-compliant producers and squeezes documentation-burdened mid-tiers.
Pricing Analysis
Value-based pricing anchors on decade-long shelf stability and temperature performance guarantees for medical device OEMs. Three-tier pricing structure across premium lithium, standard alkaline, and economy zinc-carbon levels reflects certification grade and traceability investment. Cost compression in commodity alkaline runs through private-label competition and energy density ceilings. Hospital procurement consortia exhibit lowest price sensitivity; emerging market convenience retail shows highest.
Supply Chain Analysis
Lithium carbonate feedstock rests on South American and Australian mining operations with Chinese cathode precursor dominance. Electrolyte salts, separator membranes, and steel can stock complete the input matrix. Single-source vulnerability concentrates in East Asian cathode powder production. Distribution runs through wholesale distributors for OEM supply and mass merchandisers for retail replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AAA battery market functions as a cost-of-compliance story where EU Battery Regulation mandates create an 8-14 month certification lag, erecting barrier-to-entry moats for producers with pre-built traceability infrastructure.
For Market Incumbents: Extend digital battery passport service offerings to capture compliance-as-a-service revenue from mid-tier producers lacking ERP sophistication. Expand backward integration into precursor material production to insulate margin from lithium carbonate volatility. Solid-state electrolyte R&D partnerships with Japanese electrochemical engineering pools defend against chemistry displacement.
For New Entrants and Emerging Players: Launch via online retail subscription models targeting consumer electronics bulk purchasers with transparent price positioning. India's PLI scheme electronics manufacturing clusters offer the most penetrable geography for NiMH captive supply agreements. Compliance-as-a-service partnerships with existing passport platforms reduce regulatory entry barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with lithium primary specialists given medical device OEM procurement consolidation and EU recycled content mandates. Five-to-ten year viability favors producers with dual chemistry flexibility and hospital GPO contract anchoring. The signal to watch is German precision instrument maker long-term supply agreement announcements.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Battery Passport Integration | Blockchain-verified chain-of-custody documentation satisfies EU Battery Regulation mandates for mid-tier producers. |
| Backward Integration into Cathode Precursors | Captive supply of lithium iron disulfide powder reduces exposure to East Asian single-source concentration. |
| Hospital GPO Contract Consolidation | Multi-year chemistry-agnostic agreements with German university hospital networks lock in procurement volumes. |
| Solid-State Electrolyte R&D Partnership | Japanese electrochemical engineering collaboration accelerates dry-room infrastructure maturation timelines. |
| India PLI Scheme Manufacturing Localization | Tamil Nadu and Gujarat cell assembly captures captive NiMH demand from toy and consumer device OEMs. |
Research Methodology
Independent corroboration across cell assembler procurement directors, hospital GPO contracts managers, and retail category buyers underwrites the qualitative findings. Secondary validation draws from EU Battery Regulation implementation documents, ECHA REACH substance restriction updates, and customs trade data for lithium carbonate and cathode powder flows. Bottom-up demand modeling from end-use device production data triangulates against top-down chemistry shipment aggregates.
Rate-of-change decomposition separates volume growth from mix shift and pricing dynamics across the analysis window. Segmentation dimensions include chemistry tier, integration depth, end-use application, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and OEM procurement trend extrapolation. Forecast inputs incorporate EU recycled content threshold implementation timelines and medical device reliability standard evolution.
The model assumes a particular technology adoption path; alternative pathways for solid-state electrolyte commercialization would alter the outlook. Forecasts reflect assumptions around lithium carbonate supply elasticity and digital passport system interoperability. A small set of triggers—German hospital consortium award announcements, EU conformity assessment body accreditation delays, and Indian PLI scheme participant rosters—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Watch Battery Market
Batteries
East Africa Battery Market
Batteries
South Korea Rechargeable Battery Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Global Industrial Battery Market
Batteries
Portable Battery Market
Batteries
Global Battery Market
Batteries
East Asia Battery Market
Batteries
South Asia Battery Market
Batteries
Vietnam Battery Market
Batteries
Forklift Battery Rental Market
Batteries
Water-Based Zinc-Ion Battery Market