
 Molten Salt Battery Market | 2026-2036
Molten Salt Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Molten Salt Battery Market Analysis
Software-defined battery management is repositioning how molten salt systems get monetized, shifting vendor economics from hardware-only sales toward recurring performance contracts. Ambri leverages its liquid metal chemistry expertise to anchor utility-scale deployments in North American grids. NGK Insulators sustains manufacturing scale through its sodium-sulfur platform, which dominates long-duration installations in Japanese utility networks. SolarReserve competes on thermal storage integration, combining molten salt reservoirs with concentrated solar power towers.
Molten salt batteries utilize alkali metal salts—typically lithium-sodium or sodium-nickel chloride compositions—operating between 270°C and 350°C to achieve ionic conductivity through liquid electrolyte phases, with primary purpose being multi-hour to multi-day electrochemical energy storage for grid and industrial applications. High-temperature thermal storage leads in installed base due to proven compatibility with concentrated solar power plants, while electrochemical technology segments are capturing expanding margin pools as utilities seek decoupled storage assets. Low-temperature variants are gaining traction in residential and commercial backup applications where reduced thermal management costs improve total cost of ownership.
EPA emissions standards and FERC Order 2222 are reshaping U.S. market access by rewarding storage assets that reduce grid carbon intensity and participate in wholesale markets, while the EU Green Deal and CE marking requirements under the MDR framework enforce circularity and safety protocols for European deployments. China's MIIT dual carbon goals and GB standards are accelerating domestic molten salt R&D through state-backed demonstration programs. Stakeholders must monitor how evolving carbon border adjustment mechanisms and domestic content incentives across these jurisdictions reshape supply chain qualification criteria and project finance structures.
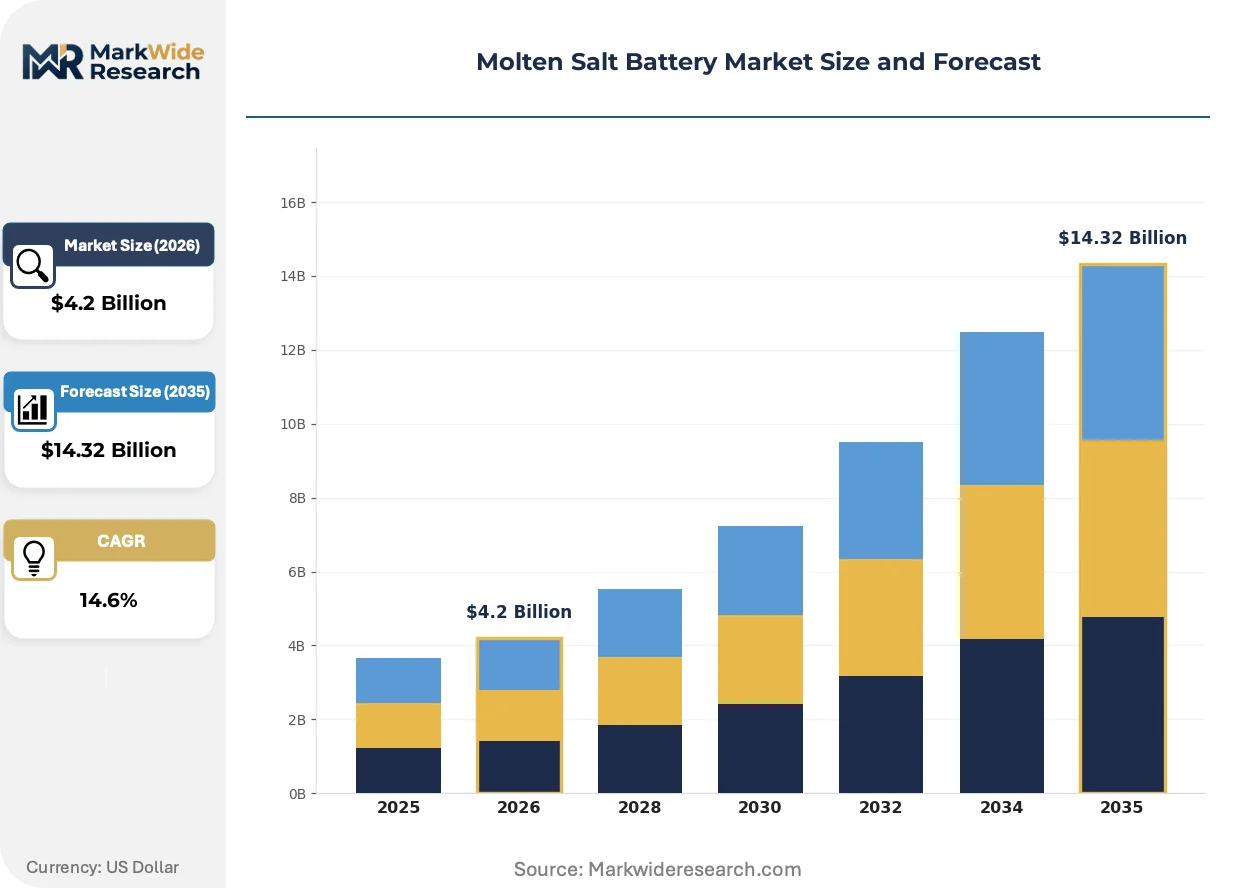
Market Dynamics
Utility-scale renewable integration is compressing storage procurement cycles and forcing chemistry diversification beyond lithium-ion dominance. The F-Gas Regulation and EU Green Deal are mandating thermal management fluid transitions that favor molten salt architectures in European grid tenders.
Growth Catalysts
- Long-duration storage mandates:Grid operators in Germany and California now require 8+ hour discharge capability for renewable pairing, disqualifying conventional lithium-ion from an expanding share of utility RFPs.
- EU F-Gas phase-down:The regulation's hydrofluorocarbon quotas are elevating molten salt systems in industrial heat-recovery applications where thermal integration replaces mechanical cooling.
- Concentrated solar power expansion:Moroccan and Spanish solar tower developers are specifying molten salt thermal storage as the default configuration for new capacity additions.
Market Restraints
- Alkali metal supply concentration:Sodium and lithium carbonate processing clusters in China and Chile create input vulnerability for cell manufacturers outside these supply orbits.
- High-temperature corrosion:Stainless steel containment alloys face degradation rates that compress asset life estimates in 300°C+ operating environments.
- Cell manufacturing scale gaps:Electrochemical molten salt production lines remain at pilot scale while sodium-sulfur incumbent NGK Insulators controls commercial volume.
Strategic Opportunities
- Industrial decarbonization clusters:German chemical parks in Ludwigshafen and Leuna are piloting molten salt buffers to electrify steam networks and arbitrage power price volatility.
- Maritime propulsion hybridization:Norwegian ferry operators are evaluating sodium-nickel chloride packs for zero-emission port operations with thermal waste heat recovery.
- Software-defined performance contracting:Vendors can capture recurring revenue streams by guaranteeing round-trip efficiency and cycle life rather than selling hardware alone.
Industry Challenges
- High-temperature sealing expertise:The talent pool for ceramic-to-metal joining and thermal expansion matching remains thin across North American and European engineering labor markets.
- Extended certification timelines:UL 9540A thermal runaway propagation testing protocols were not designed for 300°C+ operating temperatures, creating regulatory ambiguity for insurers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molten Salt Battery Market |
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $14.32 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Temperature, Low-Temperature, Hybrid, Thermal End User: Utilities, Renewable Energy, Industrial, Residential Application: Energy Storage, Grid Stabilization, Power Backup, Load Shifting Technology: Thermal Energy Storage, Electrochemical, Phase Change, Chemical Reaction |
| Companies Covered | Ambri, SolarReserve, NGK Insulators, Sumitomo Electric Industries, Energy Dome, TerraPower, Fluor Corporation, 24M Technologies, Rongke Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molten Salt Battery Market Emerging Trajectories
Electrochemical and thermal storage architectures are converging as developers seek unified assets that deliver both grid services and industrial process heat. This convergence is compressing the traditional separation between power and thermal applications.
Solid-state ceramic electrolyte development is unifying the safety profile of molten salt systems with the modularity of lithium-ion packaging. German research institutes are validating beta-alumina separators that enable sodium-metal halide cells with reduced thermal management overhead. Industrial off-takers in cement and steel are piloting these configurations for simultaneous power backup and waste heat integration.
The EU Green Deal's carbon border adjustment mechanism is reshaping qualification criteria for storage assets deployed in European industrial zones. Manufacturers must now document embodied carbon and end-of-life recyclability to maintain eligibility for green hydrogen and renewable power offtake agreements. Battery-as-a-service providers are responding by securing EU-based salt processing and steel recycling partnerships.
Buyers are consolidating procurement authority from site engineers to centralized sustainability offices, compressing vendor evaluation cycles and elevating lifecycle assessment documentation over upfront capital cost. This shift is most visible in German automotive supplier parks and Dutch greenhouse clusters, where molten salt tenders now require 20-year performance guarantees and verified carbon intensity scores rather than simple $/kWh metrics.
Molten Salt Battery Market Segmentation
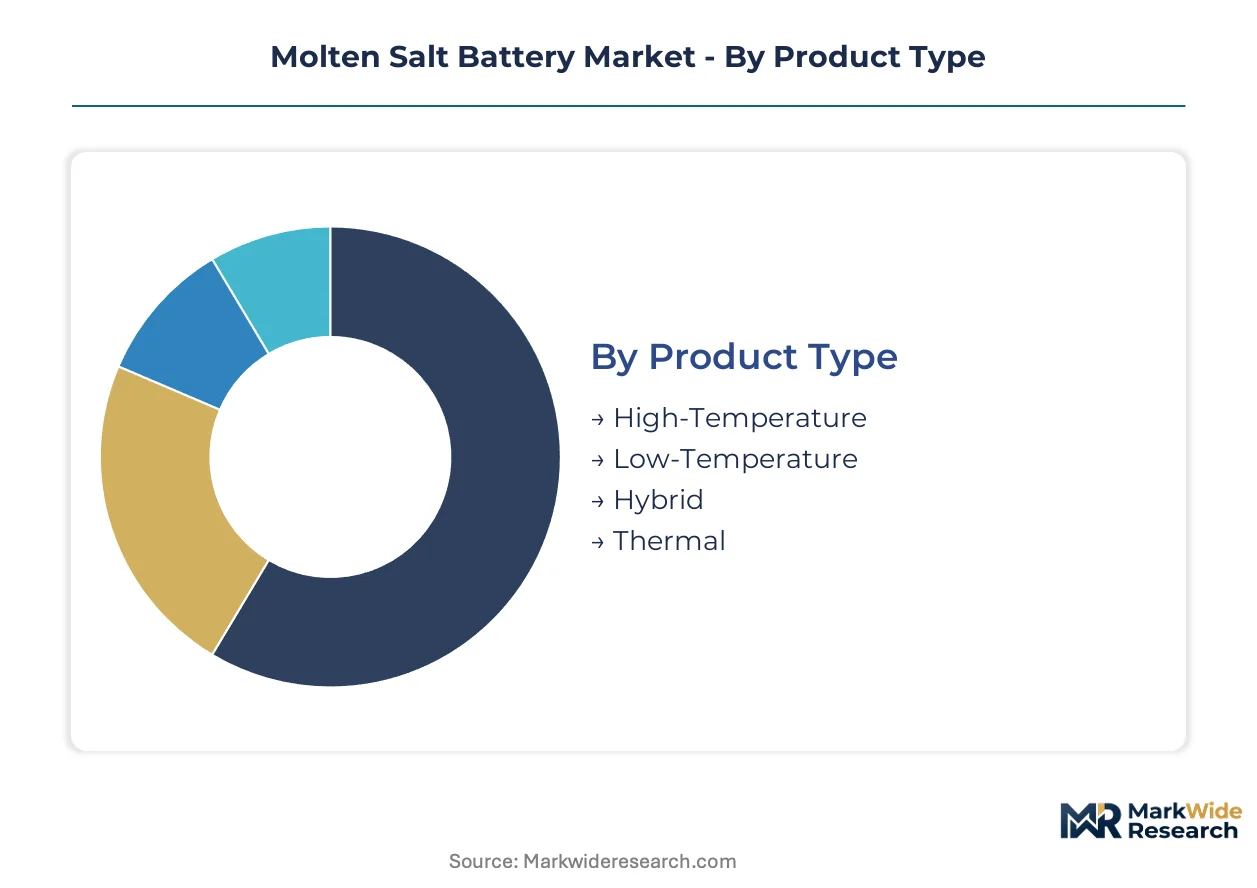
Molten salt battery architectures diverge sharply in capital requirements, thermal management infrastructure, and grid integration complexity. Segment selection dictates project finance structures, offtake contract terms, and vendor qualification criteria for utility procurement teams.
Product Type:
Capital intensity varies by an order of magnitude across temperature classes, with thermal containment systems and corrosion-resistant alloys driving front-loaded investment profiles.
- High-Temperature:Systems operating between 270°C and 350°C utilize lithium-sodium or sodium-nickel chloride chemistries in stainless steel containment. German grid operators and Spanish concentrated solar developers specify these configurations for 8-12 hour discharge durations where round-trip efficiency thresholds exceed 85%.
- Thermal:Molten salt reservoirs paired with concentrated solar power towers dominate installed capacity globally. Moroccan Noor Ouarzazate and Spanish Gemasolar plants demonstrate commercial viability at gigawatt-hour scale, though electrochemical alternatives are capturing marginal share in decoupled storage tenders.
- Low-Temperature:Reduced thermal management overhead improves total cost of ownership for commercial backup applications. Sodium-metal halide cells with beta-alumina separators are gaining traction in German automotive supplier parks.
- Hybrid:Configurations combining electrochemical cells with thermal storage buffers enable simultaneous power delivery and industrial process heat. Pilot deployments in Ludwigshafen chemical parks validate this architecture for steam network electrification.
Most installed capacity flows through Thermal. Expansion is steepest in Low-Temperature.
End User:
Procurement authority concentrates in sustainability offices rather than site engineering teams, elevating lifecycle assessment documentation and 20-year performance guarantees over upfront capital metrics.
- Utilities:Grid operators in California and Germany now mandate 8+ hour discharge capability for renewable pairing, disqualifying conventional lithium-ion from expanding RFP volumes. FERC Order 2222 enables wholesale market participation for utility-scale molten salt assets.
- Industrial:German chemical parks and Dutch greenhouse clusters are piloting molten salt buffers to electrify steam networks and arbitrage power price volatility. The EU Green Deal's carbon border adjustment mechanism requires documented embodied carbon for storage asset qualification.
- Renewable Energy:Concentrated solar power developers in Spain and Morocco specify molten salt thermal storage as default configuration for new capacity additions.
- Residential:Backup power applications favor low-temperature variants where reduced thermal management costs improve accessibility.
Utility procurement volumes anchor manufacturer revenue. Industrial off-takers are expanding most quickly as decarbonization targets harden.
Application:
Revenue models shift from hardware sales toward performance contracting as software-defined battery management enables guaranteed round-trip efficiency and cycle life monetization.
- Energy Storage:Multi-hour to multi-day electrochemical storage for grid and industrial applications. German utilities specify sodium-sulfur and sodium-metal halide cells for renewable integration.
- Load Shifting:Industrial facilities in Leuna and Ludwigshafen deploy molten salt buffers to capture power price arbitrage and reduce peak demand charges.
- Grid Stabilization:Frequency regulation services require rapid response capabilities that thermal storage architectures deliver through thermal-electric conversion.
- Power Backup:Commercial and critical infrastructure applications favor low-temperature variants with reduced standby energy consumption.
Energy Storage commands the largest project pipeline. Load Shifting is gaining share fastest as industrial power markets liberalize.
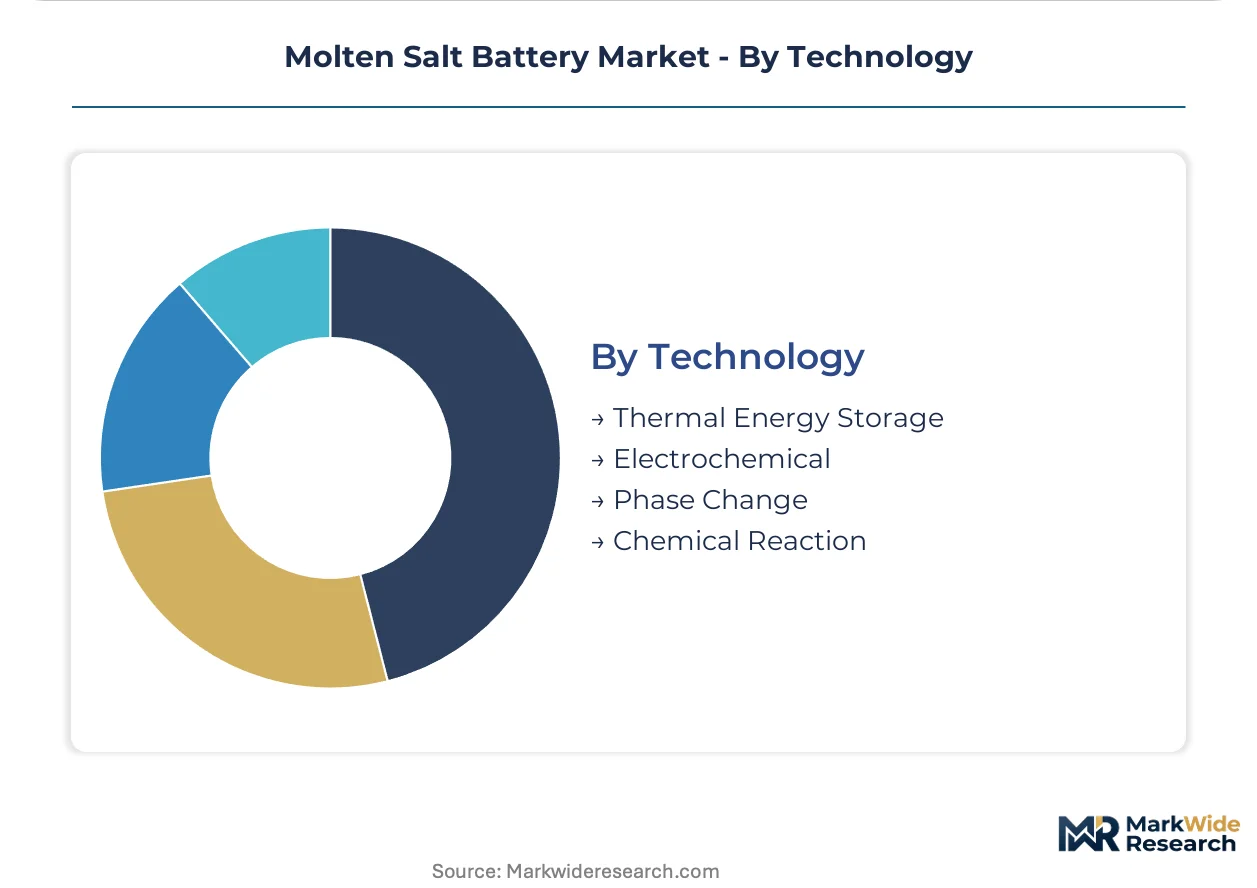
Technology:
Manufacturing scale gaps persist between thermal storage incumbents and electrochemical challengers, with pilot-scale production lines constraining commercial deployment timelines.
- Thermal Energy Storage:Molten salt reservoirs dominate long-duration installations in concentrated solar power plants. Proven compatibility with tower configurations sustains procurement preference in Spanish and Moroccan tenders.
- Electrochemical:Sodium-sulfur and sodium-metal halide cells capture expanding margin pools as utilities seek decoupled storage assets. German research institutes validate beta-alumina separators that reduce thermal management overhead.
- Phase Change:Salt mixtures with defined melting points enable precise temperature control for industrial process heat applications.
- Chemical Reaction:Thermochemical storage mechanisms remain at laboratory scale with limited commercial deployment.
Thermal Energy Storage retains the dominant installed base. Electrochemical technology is climbing the fastest as chemistry diversification accelerates beyond lithium-ion dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in procurement pace, with German utilities mandating 8+ hour discharge capability while American developers await FERC Order 2222 implementation clarity. Japan sustains manufacturing scale through sodium-sulfur incumbent dominance. China accelerates domestic R&D through state-backed demonstration programs.
United States
California grid operators now require long-duration storage for renewable pairing, disqualifying conventional lithium-ion from expanding RFP volumes. FERC Order 2222 enables wholesale market participation for utility-scale molten salt assets. Greater Boston hosts Ambri's liquid metal chemistry development for North American utility deployments.
Germany
Ludwigshafen and Leuna chemical parks pilot molten salt buffers to electrify steam networks and arbitrage power price volatility. The EU Green Deal and F-Gas Regulation mandate thermal management fluid transitions favoring molten salt architectures. Grid modernization investments concentrate procurement authority in sustainability offices rather than site engineering teams.
Japan
Utility networks sustain sodium-sulfur platform dominance for long-duration installations. METI industrial policy supports thermal electrochemical storage integration. Domestic manufacturing scale through NGK Insulators controls commercial volume for electrochemical molten salt production.
China
MIIT dual carbon goals accelerate domestic molten salt R&D through state-backed demonstration programs. GB standards enforce safety protocols for high-temperature electrochemical systems. Yangtze River Delta clusters concentrate salt processing and steel recycling partnerships for battery-as-a-service providers.
Spain
Concentrated solar power developers specify molten salt thermal storage as default configuration for new capacity additions. EU Green Deal carbon border adjustment mechanisms reshape qualification criteria for storage assets in industrial zones. Andalusian solar tower projects demonstrate commercial viability at gigawatt-hour scale.
Molten Salt Battery Market Vendor Landscape
Top-tier vendors anchor utility-scale deployments, while mid-scale specialists occupy industrial and residential niches. The vendor base stratifies across thermal storage incumbents, electrochemical challengers, and integrated solar developers. Ceramic-to-metal joining expertise and high-temperature sealing capabilities differentiate technical positioning. Capacity expansion and strategic partnerships dominate competitive moves as manufacturing scale gaps constrain commercial timelines.
Within the electrochemical tier, Ambri and NGK Insulators exemplify divergent geographic anchoring strategies. Ambri occupies a position representing North American liquid metal chemistry development. NGK Insulators sits within the established sodium-sulfur manufacturing orbit serving Japanese utility networks. SolarReserve exemplifies the integrated solar-thermal configuration approach among concentrated solar power developers.
| Leading Market Players |
|---|
| Ambri |
| SolarReserve |
| NGK Insulators |
| Sumitomo Electric Industries |
| Energy Dome |
| TerraPower |
| Fluor Corporation |
| 24M Technologies |
| Rongke Power |
| Others |
Supply Flow & Price Mechanics
Beta-alumina separator commercialization is compressing thermal management costs while concentrating procurement leverage among German and Japanese ceramic suppliers. This manufacturing transition simultaneously reduces cell-level cost structures and deepens dependency on specialized sintering capacity.
Pricing Analysis
Capacity additions in China are reshaping price floors for sodium carbonate and lithium hydroxide precursors. Three-tier pricing structure across premium, standard, and economy levels reflects UL 9540A certification status and volume scale. Cost compression in the economy tier is intensifying because Chinese state-backed demonstration programs are subsidizing domestic cell production. Industrial offtakers in German chemical parks exhibit the highest price sensitivity, while utility procurement teams prioritize 20-year performance guarantees over upfront capital metrics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese sodium carbonate processing and Chilean lithium brine extraction. Manufacturing scale draws from China, Japan, and Germany for beta-alumina separators, stainless steel containment alloys, and precision ceramic-to-metal joining. Supply chain risk centers on tariff exposure for alkali metal imports into European fabrication facilities. Distribution runs through EPC contractors and battery-as-a-service providers rather than direct hardware sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through software-defined performance contracting and captive salt processing partnerships that capture value formerly lost to commodity suppliers.
For Market Incumbents: Anticipate sodium-sulfur platform displacement by sodium-metal halide architectures in European utility tenders. Defend position by securing backward integration into beta-alumina separator production and anchoring long-term offtake agreements with German grid operators. Prioritize ceramic-to-metal joining talent acquisition in North American and European engineering labor markets.
For New Entrants and Emerging Players: Begin with industrial decarbonization clusters in Ludwigshafen and Leuna where procurement authority has shifted to sustainability offices seeking verified carbon intensity scores. Target maritime propulsion hybridization in Norwegian ferry networks as the most penetrable segment. Lead with thermal waste heat recovery integration as the go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among electrochemical challengers with pilot-scale production lines and software-defined battery management platforms. Long-term viability hinges on manufacturing scale gaps closing faster than lithium-ion cost curves flatten. Target acquisition archetype: mid-scale specialists with EU-based salt processing partnerships and UL 9540A certification pathways. Watch FERC Order 2222 implementation clarity as the inflection signal for North American utility procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salt Processing | Captures margin pools from Chinese sodium carbonate suppliers and secures EU Green Deal qualification. |
| Software-Defined Performance Contracting | Shifts vendor economics from hardware sales toward recurring revenue through guaranteed round-trip efficiency. |
| Ceramic-to-Metal Joining Talent Acquisition | Addresses the thin engineering labor pool for high-temperature sealing expertise in North America and Europe. |
| EU-Based Recycling Partnerships | Satisfies carbon border adjustment mechanism documentation requirements for industrial zone deployments. |
| Long-Term Supply Agreement with Utility | Locks in offtake volumes for 8+ hour discharge systems mandated by German and California grid operators. |
Methodological Framework
Direct dialogue with utility planning officers, EPC contractors, ceramic materials suppliers, and industrial sustainability directors grounded the qualitative assessment. Secondary validation drew from FERC filings, EIA storage deployment databases, EU Green Deal implementation trackers, and IEA long-duration storage reports. Bottom-up and top-down triangulation cross-checked project-level procurement data against national policy targets.
Bottom-up modeling aggregated individual project pipelines across German chemical parks, Spanish concentrated solar developments, and California utility RFPs. Top-down analysis calibrated penetration rates against regulatory mandates including F-Gas Regulation phase-down schedules and MIIT dual carbon goals. Segmentation dimensions spanned temperature class, end-use vertical, and discharge duration tier. CAGRs were derived from installed capacity build rates and technology substitution curves.
Caveats apply where FERC Order 2222 implementation delays, alkali metal supply disruptions, or UL 9540A protocol revisions could materially shift the outlook. Forecasts reflect assumptions about manufacturing scale gaps closing and ceramic separator cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
All-In-One Solar Storage Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Low Temperature Battery Market
Batteries
East Asia Battery Market
Batteries
Nuclear Battery Sales Market
Batteries
Residential Battery Market
Batteries
United States Household Battery Market
Batteries
China Battery Market
Batteries
India Rechargeable Battery Market
Batteries
N-Type Battery Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
Zinc Carbon Battery Market
Batteries
North America Battery Market
Batteries
Global Bio Compatible Battery Market