
 Battery Simulator Market | 2026-2036
Battery Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Simulator Market Insights
Leasing-based access to high-channel-count battery simulator arrays is rewriting competitive dynamics for mid-tier test houses. Chroma ATE leverages its Taiwan manufacturing base to control cost structures on modular systems. Keysight dominates the premium segment through R&D intensity in precision source-measure units. Digatron Power Electronics anchors European automotive OEM relationships with application-specific configurations.
A battery simulator is an electronic test instrument that emulates the voltage, current, and impedance characteristics of electrochemical cells under controlled conditions, typically achieving microsecond response times and programmable slew rates for dynamic load profiles. Its primary commercial purpose is to validate battery management systems, charger circuits, and energy storage architectures without requiring physical cell inventories. The standalone product category leads current revenue as legacy automotive test floors favor dedicated rack-mounted units, while modular architectures are capturing the fastest expansion as research institutions demand reconfigurable channel counts. Digital technology segments command margin premiums through software-defined test sequencing, whereas analog systems persist in cost-sensitive utility provider installations.
The EU Battery Regulation and UN ECE R100 are mandating traceable cell-level test documentation, which forces simulator vendors to embed audit-grade data logging. The US EPA and NHTSA coordinate on EV powertrain validation protocols that specify thermal cycling reproducibility. China's MIIT issues GB standards for new energy vehicle component testing that require domestic certification of simulation accuracy. Stakeholders must decide whether to absorb compliance engineering costs directly or partner with regionally certified system integrators.
Market Dynamics
Leasing-based access to high-channel-count battery simulator arrays is compressing capital requirements for mid-tier test houses and fragmenting vendor power across the value chain.
Growth Catalysts
- EU Battery Regulation traceability mandates:The EU Battery Regulation forces OEMs to document cell-level test histories, embedding audit-grade data logging as a non-negotiable procurement criterion.
- Electric vehicle test-lab expansion:EV manufacturers are scaling validation capacity for cell characterization, pulling demand for precision source-measure units with microsecond response capabilities.
- Solid-state battery R&D pipelines:Next-generation chemistries require reconfigurable channel architectures that legacy rack-mounted units cannot accommodate.
Market Restraints
- Precision electronics input cost volatility:High-resolution ADCs and GaN power stages face semiconductor foundry allocation constraints, compressing gross margins on mid-range systems.
- Supply concentration in Taiwan:Modular power electronics manufacturing clusters heavily on the island, exposing procurement timelines to geopolitical friction.
- Calibration infrastructure scarcity:Third-party metrology labs capable of certifying sub-millivolt accuracy remain concentrated in Germany, the United States, and Japan.
Strategic Opportunities
- India BIS certification pathways:Domestic new energy vehicle component testing standards are mandating localized simulator validation, creating first-mover positioning for certified system integrators.
- Second-life battery testing protocols:Grid-scale storage refurbishment operations need low-cost impedance emulation for state-of-health determination.
- Software-defined test sequencing:Python-scriptable instrument control is converging with cloud-based data lakes to enable distributed R&D collaboration.
Industry Challenges
- Electrochemical modeling expertise scarcity:Vendors struggle to recruit engineers capable of translating cell degradation physics into programmable load profiles.
- Multi-standard certification timelines:Simultaneous UN ECE R100, GB standards, and EPA protocol compliance extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Simulator Market |
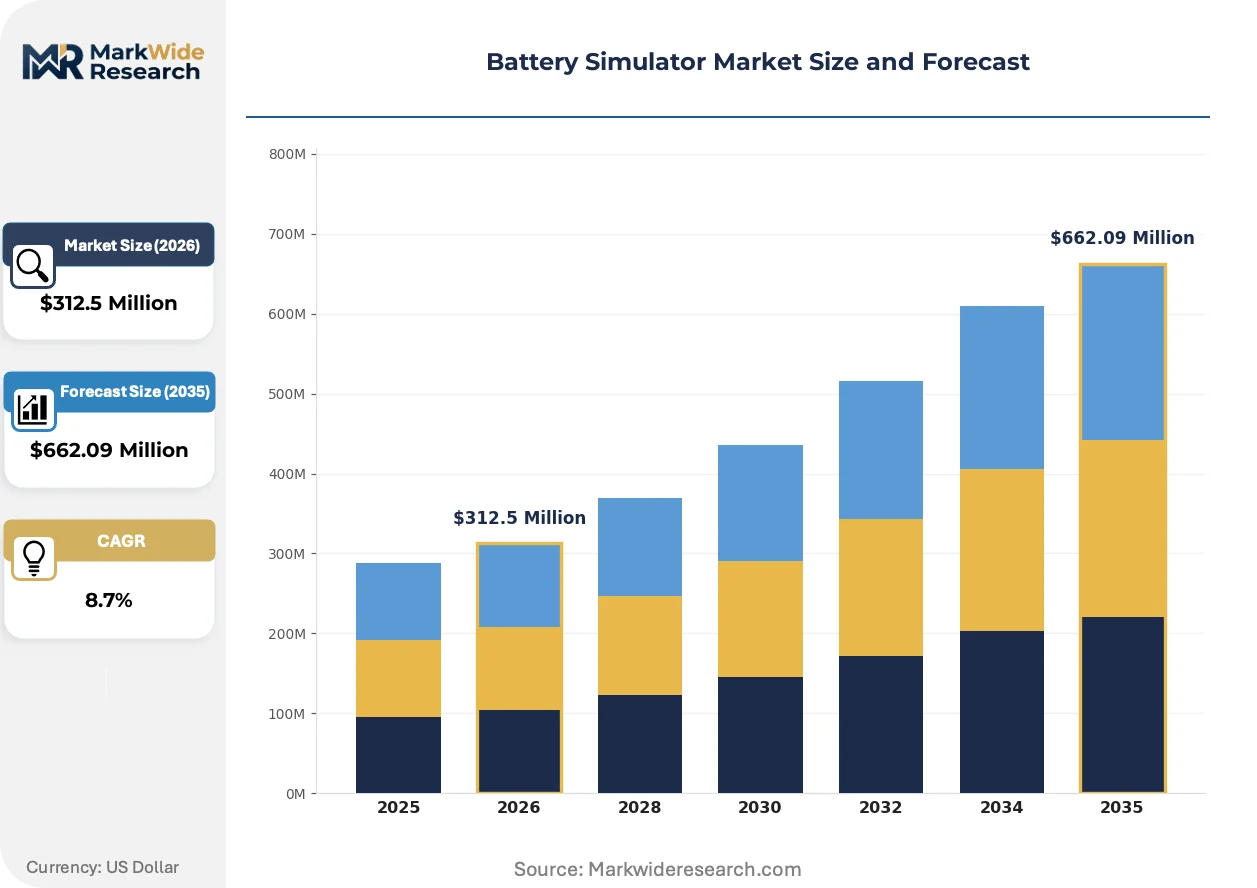
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Modular, Compact Technology: Analog, Digital, Hybrid, Smart Application: Automotive Testing, Renewable Energy, Research, Telecommunications End User: Manufacturers, Research Institutions, Automotive OEMs, Utility Providers |
| Companies Covered | Keithley (Tektronix), Ametek, Rohde & Schwarz, National Instruments, MEIDENSHA, Keysight, Regatron AG, Digatron Power Electronics, Chroma ATE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Simulator Market Trends and Innovations
Digital twin architectures and software-defined instrumentation are collapsing the boundary between physical cell testing and virtual validation environments.
Silicon-carbide power switching is rendering obsolete traditional IGBT-based analog load stages in high-slew-rate applications. Research institutions adopting 200 kHz bandwidth systems are compressing test cycle duration for dynamic drive profiles. The technology is rendering obsolete legacy rack architectures that cannot achieve sub-100 microsecond transient response.
REACH substance restrictions on heavy metals in electronics manufacturing are forcing simulator vendors to redesign thermal management subsystems. Industrial consequence includes accelerated validation of lead-free solder joints under thermal cycling stress. Automotive OEMs in Germany and France are responding by mandating full material disclosure from sub-tier power electronics suppliers.
Subscription-based access to pooled simulator capacity is displacing capital purchase models among university consortia and startup cell developers. Equipment-as-a-service platforms are capturing share from traditional distribution channels by unbundling maintenance and software upgrades. This pattern is most visible in California and Bavaria, where battery research clusters face facility space constraints.
Battery Simulator Market Segmentation
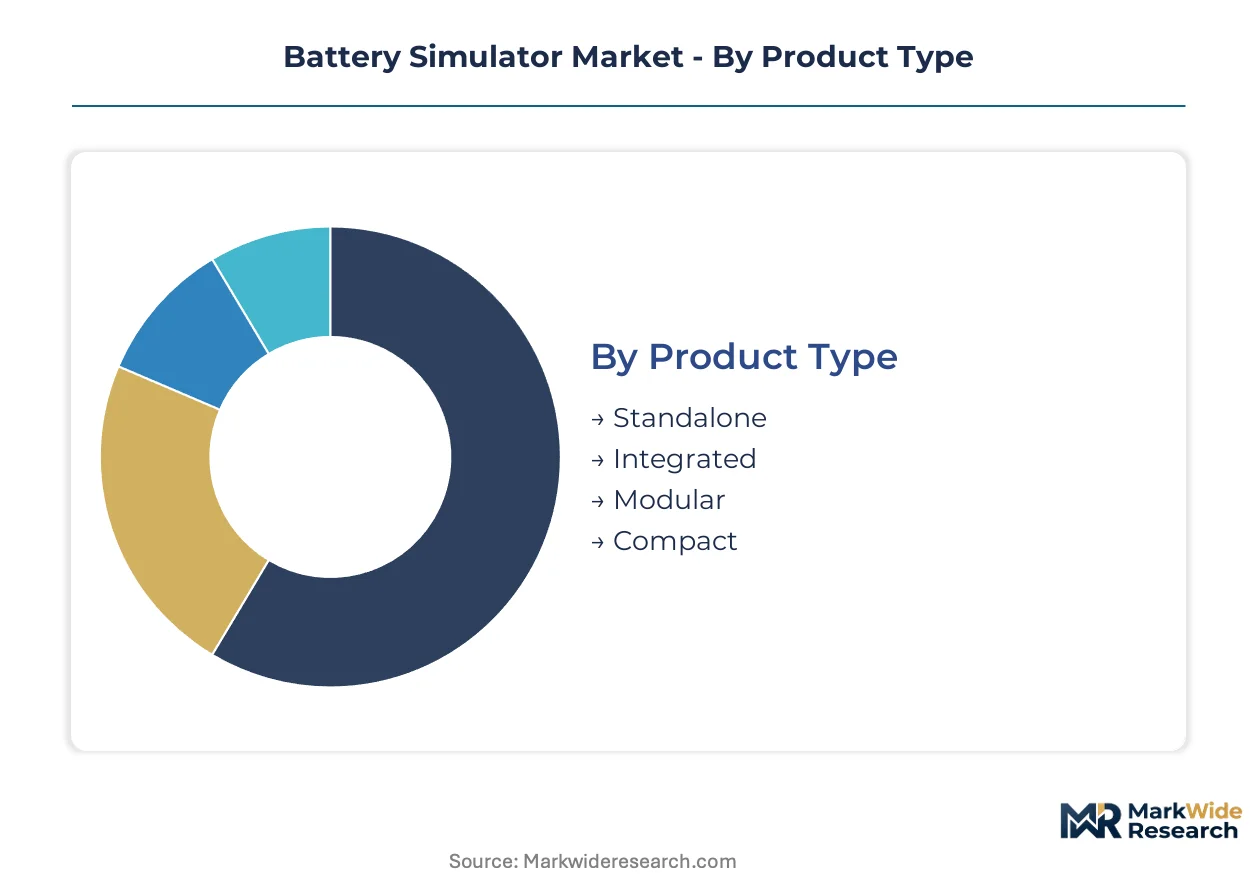
Segmentation in the battery simulator market maps directly to capital deployment patterns and compliance workflows. Test houses configure procurement around channel density needs, while OEMs prioritize traceability architecture for regulatory submission.
Product Type:
Cost tier determines procurement authority and replacement cycles across test floor hierarchies.
- Standalone:Rack-mounted units with dedicated power stages and fixed channel configurations serve legacy automotive validation floors. German and United States OEMs favor these for UN ECE R100 compliance documentation where audit trails require dedicated hardware instances.
- Modular:Reconfigurable chassis with swappable source-measure cards accommodate solid-state battery R&D pipelines. Research institutions in California and Bavaria lease these arrays to match project-phase channel requirements without facility expansion.
- Integrated:Combined simulation and data acquisition systems reduce footprint for utility provider substations.
- Compact:Benchtop units with reduced bandwidth target startup cell developers and university laboratories.
Standalone holds installed capacity. Modular is rotating up the share rankings.
Technology:
Application criticality separates precision requirements from cost tolerance in test sequencing.
- Digital:Software-defined architectures with Python-scriptable control and cloud-native data lakes enable distributed R&D collaboration. These systems command margin premiums through programmable slew rates and microsecond transient response for dynamic drive profile validation.
- Analog:Discrete component load stages persist in cost-sensitive utility provider installations where bandwidth requirements stay below 10 kHz. China's MIIT GB standards for grid-connected storage accept these systems for domestic certification.
- Hybrid:Combined DSP-controlled analog stages bridge precision and cost for mid-tier test houses.
- Smart:AI-augmented impedance matching for predictive load profiling in second-life battery testing.
Digital dominates margin capture. Hybrid is climbing the fastest.
Application:
Customer type concentration varies sharply by validation protocol complexity and documentation burden.
- Automotive Testing:Cell characterization for EV powertrain validation demands 200 kHz bandwidth and thermal cycling reproducibility per US EPA-NHTSA coordinated protocols. Silicon-carbide switching is displacing IGBT stages in these high-slew-rate environments.
- Research:Multi-chemistry exploration requires reconfigurable channel architectures that accommodate solid-state, lithium-metal, and sodium-ion cell emulation within the same hardware instance.
- Renewable Energy:Grid-scale storage integration testing for inverter compatibility and frequency response.
- Telecommunications:Backup power system validation for base station battery backup duration under temperature extremes.
Automotive Testing commands channel density. Research is gaining share fastest.
End User:
Volume scale and certification authority create distinct procurement decision structures.
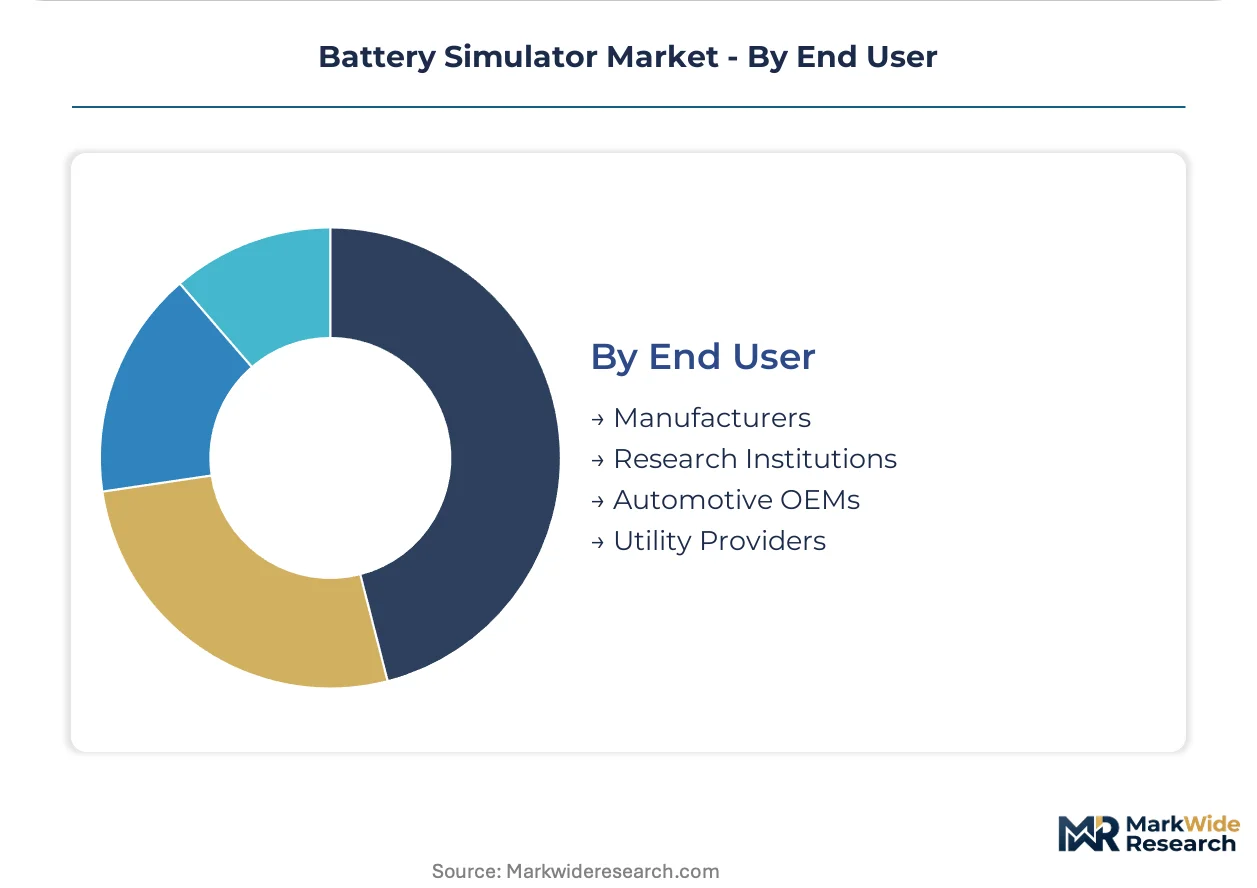
- Automotive OEMs:Centralized test-lab expansion in Germany, China, and the United States concentrates demand for high-channel-count arrays with embedded audit-grade data logging. EU Battery Regulation traceability mandates force direct vendor relationships over distributor channels.
- Research Institutions:Subscription-based access to pooled simulator capacity displaces capital purchases among university consortia facing facility space constraints in California and Bavaria.
- Manufacturers:Cell producers and BMS developers requiring validation for production release.
- Utility Providers:Grid operators testing energy storage integration and refurbishment protocols for second-life battery deployment.
Automotive OEMs anchor volume procurement. Research Institutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Battery Regulation traceability mandates and US EPA-NHTSA coordinated validation protocols are redirecting procurement toward jurisdictions with established metrology infrastructure and domestic certification authority.
United States
Automotive OEMs in Michigan and California are scaling test-lab capacity for EV powertrain validation. EPA and NHTSA protocols specify thermal cycling reproducibility requirements that favor precision source-measure units. The Detroit-Warren-Dearborn cluster concentrates demand for high-channel-count arrays with embedded audit-grade data logging.
Germany
UN ECE R100 compliance documentation forces direct vendor relationships over distributor channels for automotive validation floors. The country's national automotive regulator KBA enforces traceable cell-level test histories. The Stuttgart and Munich metropolitan areas anchor European procurement for rack-mounted standalone systems.
China
MIIT GB standards for new energy vehicle component testing require domestic certification of simulation accuracy. The Yangtze River Delta and Pearl River Delta clusters host expanding R&D pipelines for solid-state battery chemistries. Modular architectures with reconfigurable channel counts are capturing share from legacy installations.
Japan
METI industrial policy supports precision electronics manufacturing for semiconductor test equipment adjacent markets. The Tokyo-Yokohama and Nagoya metropolitan areas concentrate calibration infrastructure for sub-millivolt accuracy certification. Research institutions lease pooled simulator capacity to match project-phase requirements.
India
BIS certification pathways for new energy vehicle component testing are mandating localized simulator validation. The Maharashtra and Karnataka state clusters face facility space constraints that favor subscription-based equipment access. First-mover positioning is available for certified system integrators meeting domestic standards.
Battery Simulator Market Competitive Landscape
On the supply side, the industry is structured around three tiers differentiated by channel density capability and software integration depth. Precision instrumentation specialists with legacy test equipment portfolios occupy the premium segment. Modular power electronics fabricators with Taiwan manufacturing footprints control cost structures on reconfigurable systems. Regional system integrators with domestic certification authority capture compliance-driven procurement in emerging markets. Competitive moves center on strategic partnerships with automotive OEMs for test-lab expansion and technology licensing for silicon-carbide power switching.
Among precision instrumentation specialists, Keysight and Keithley (Tektronix) exemplify the premium-tier archetype through R&D intensity in source-measure units. Chroma ATE represents the modular manufacturing archetype with Taiwan-based production control. Digatron Power Electronics anchors European automotive relationships through application-specific configurations.
| Leading Market Players |
|---|
| Keithley (Tektronix) |
| Ametek |
| Rohde & Schwarz |
| National Instruments |
| MEIDENSHA |
| Keysight |
| Regatron AG |
| Digatron Power Electronics |
| Chroma ATE |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Taiwan's modular power electronics fabrication facilities is compressing pricing power for mid-range battery simulator systems while simultaneously pressuring vendors to absorb compliance engineering costs for EU Battery Regulation traceability mandates. This utilization dynamic forces procurement officers at automotive OEMs to negotiate harder on channel-count bundles as suppliers chase volume to cover fixed costs.
Pricing Analysis
Certification level (ISO/IEC 17025-grade metrology) creates the primary spread between premium and standard tiers, with UN ECE R100-compliant systems commanding substantial premiums over utility-grade analog alternatives. Pricing stratifies across audit-grade digital architectures, hybrid DSP-controlled platforms, and cost-sensitive analog installations. Cost compression in the mid-tier segment is intensifying because semiconductor foundry allocation constraints for high-resolution ADCs and GaN power stages are squeezing gross margins. Startup cell developers and university consortia exhibit the highest price sensitivity through their shift toward subscription-based equipment access, while German automotive OEMs remain least sensitive due to regulatory non-negotiability.
Supply Chain Analysis
Export control regimes restricting high-bandwidth semiconductor test equipment flows are fragmenting procurement timelines for precision source-measure units. Manufacturing gravity centers on Taiwan for modular chassis fabrication, Germany for calibration infrastructure and rack-mounted systems, and China for domestic-certified GB-standard compliant units. The supply chain draws from gallium nitride foundries in Taiwan, precision ADC suppliers in the United States and Japan, and silicon-carbide substrate producers. Single-source vulnerability around Taiwan Strait logistics chokepoints poses structural risk. Distribution runs through direct vendor relationships for automotive OEM compliance documentation and regional system integrators for emerging market certification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from software-defined instrumentation architectures that collapse the boundary between physical cell testing and virtual validation environments. Defense requires pre-emptive positioning before digital twin platforms capture R&D budgets.
For Market Incumbents: Pre-empt displacement by silicon-carbide switching specialists through backward integration into GaN power stage sourcing and captive calibration infrastructure in Germany. Lock in automotive OEM relationships with embedded audit-grade data logging that cloud-native competitors cannot replicate overnight. Prioritize certification investment for India's BIS pathways before domestic system integrators consolidate first-mover positioning.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka state clusters offer the most penetrable geography, where facility space constraints and emerging BIS mandates favor subscription-based equipment-as-a-service platforms over capital purchases. Target second-life battery testing protocols for grid-scale storage refurbishment operations, where low-cost impedance emulation demand outstrips supply. Lead with Python-scriptable instrument control and cloud-native data lakes to differentiate from legacy rack-mounted vendors.
For Investors and Strategic Acquirers: Capital is best deployed toward precision instrumentation specialists with established automotive OEM test-lab relationships and embedded software-defined sequencing capabilities. Long-term viability hinges on defensible metrology infrastructure and regulatory certification authority rather than hardware manufacturing scale. Watch for inflection signals in solid-state battery R&D pipeline funding, which would accelerate demand for reconfigurable channel architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Power Switching Migration | Sub-100 microsecond transient response displaces IGBT-based legacy rack architectures in automotive validation floors. |
| Domestic Certification Authority Partnership | India BIS and China MIIT GB compliance creates procurement preference over non-certified imports. |
| Subscription-Based Equipment Access | California and Bavaria research clusters favor pooled capacity over capital purchases due to facility constraints. |
| Audit-Grade Data Logging Integration | EU Battery Regulation traceability mandates embed non-negotiable procurement criteria for automotive OEMs. |
| Cloud-Native Distributed R&D Collaboration | Python-scriptable control converges with data lakes to enable multi-site solid-state battery development. |
Research Methodology
Two parallel data streams informed the analysis: structured primary engagements with battery test lab directors, automotive OEM platform engineers, power electronics procurement leads, and research institution facility managers; and secondary validation through UN ECE R100 regulatory filings, MIIT GB standard documentation, EPA-NHTSA coordinated protocol releases, and customs trade data on precision electronics imports. Bottom-up channel-count demand modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Forecast inputs incorporated product type segmentation by channel density configuration, technology tier by bandwidth and software integration depth, application workflow by validation protocol complexity, and end-user procurement authority by centralized versus distributed decision structures. CAGRs were derived from installed base replacement cycles, test-lab expansion pipelines, and regulatory mandate implementation timelines. Solid-state battery R&D funding trajectories and leasing model adoption curves served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by modular power electronics fabricators would shift outcomes. Material shifts in Taiwan Strait logistics stability or REACH substance restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Coin Cell Lithium Batteries Market
Batteries
Elastic Battery Binders Market
Batteries
N-Type Battery Market
Batteries
Europe Battery Market
Batteries
Taiwan Battery Market
Batteries
Breathing Battery Market
Batteries
High Voltage Battery Market
Batteries
Battery Terminal Brushes Market
Batteries
Iron Flow Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Mobile Battery Market
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
Smart Battery Market
Batteries
Automotive Starting Battery Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market