
 Forklift Battery Market | 2026-2036
Forklift Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift Battery Market Analysis
Modular battery pack architecture is shifting procurement patterns as warehouse operators swap entire units rather than servicing individual cells. EnerSys leverages captive distribution networks to control aftermarket service revenue. GS Yuasa Corporation anchors Asian manufacturing scale through integrated lead-acide and lithium-ion production lines. Crown Battery Manufacturing specializes in flooded and sealed lead-acid configurations for price-sensitive material handling fleets.
A forklift battery is an electrochemical storage system engineered to deliver sustained deep-cycle power at voltages typically ranging from 24V to 80V for counterbalance and reach trucks. These batteries employ lead-acid, lithium-ion, or nickel-cadmium chemistries housed in steel trays with electrolyte containment and automated watering systems to ensure continuous multi-shift operation. Lithium-ion technology leads new fleet procurement due to opportunity-charging compatibility and elimination of battery changeout rooms. Lead-acid chemistry retains dominance in aftermarket replacement cycles where existing charging infrastructure and lower capital outlay govern purchasing decisions. Fast charging and smart charging systems represent the fastest-growing technology segments as fleet managers prioritize uptime over asset ownership.
OSHA mandates ventilation standards for battery charging areas, while EPA regulations govern lead recycling and sulfuric acid handling across United States facilities. EU F-Gas Regulation and REACH compliance requirements restrict certain electrolyte additives and mandate end-of-life documentation for industrial batteries sold in Europe. Stakeholders must monitor evolving carbon border adjustments and battery passport requirements that will reshape supplier qualification criteria and total cost of ownership calculations.
Market Dynamics
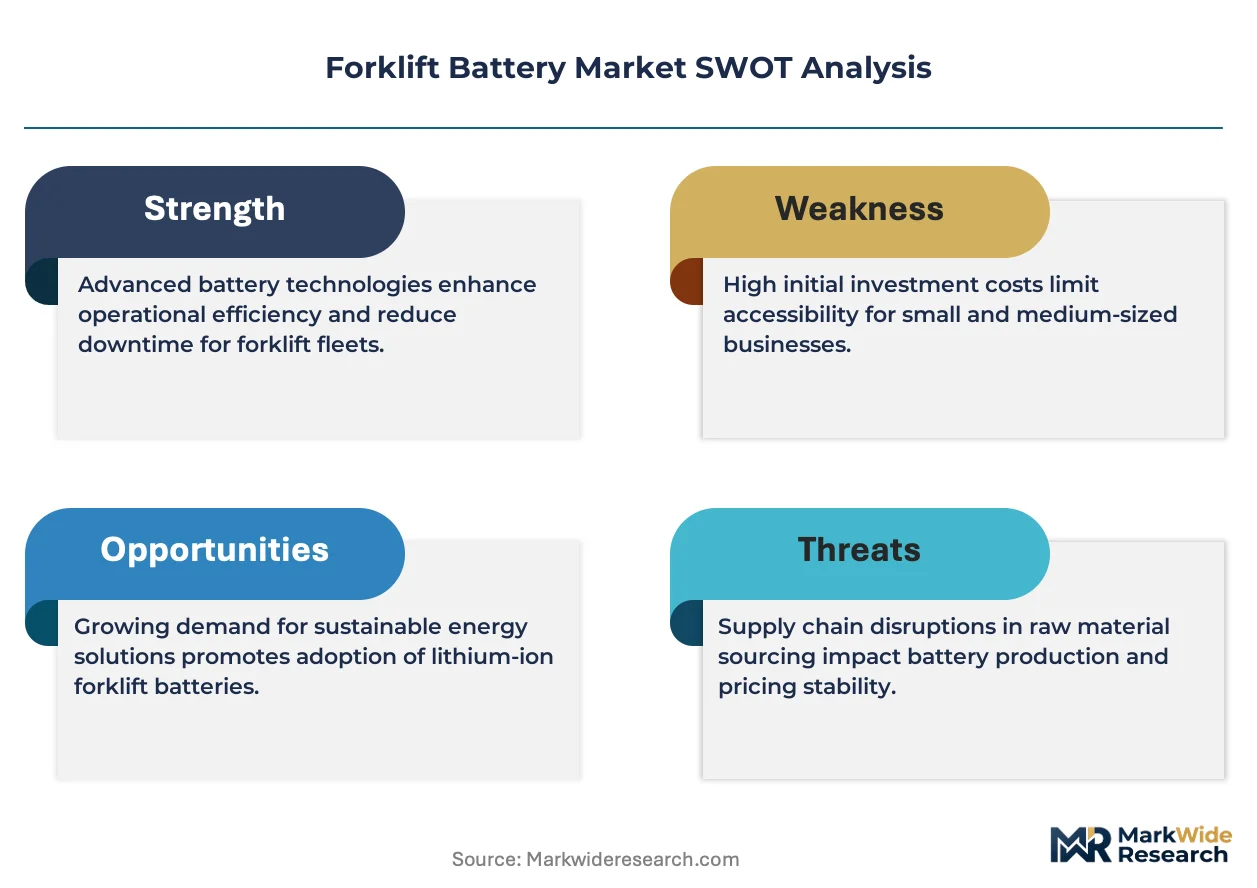
Lithium-ion chemistry is modularizing forklift power systems faster than charging infrastructure can standardize, forcing warehouse operators to choose between retrofitting legacy lead-acid bays or abandoning battery changeout rooms entirely.
Growth Catalysts
- EU F-Gas Regulation:Tightening emissions standards for indoor air quality are accelerating fleet electrification mandates across German automotive logistics hubs and chemical manufacturing corridors.
- E-commerce fulfillment density:Multi-shift warehouse operations in North American distribution centers are driving demand for opportunity-charging compatible battery architectures.
- Fast charging systems:Advanced charging technologies are compressing dwell time requirements and enabling continuous operation without dedicated battery swap infrastructure.
Market Restraints
- Lithium carbonate volatility:Raw material price swings for cathode active materials are compressing margins for battery pack assemblers and delaying project financing.
- Lead-acid infrastructure lock-in:Existing charging bay investments and watering system maintenance contracts create switching friction for incumbent fleet operators.
- REACH compliance documentation:European end-of-life battery passport requirements are extending supplier qualification timelines and raising administrative costs for cross-border sales.
Strategic Opportunities
- India material handling electrification:PLI scheme incentives for domestic cell manufacturing are opening procurement pathways for lithium-ion forklift batteries in emerging logistics corridors.
- Battery-as-a-service models:Pay-per-cycle financing structures are displacing capital expenditure procurement in third-party logistics provider fleets.
- Smart charging convergence:Integration of telematics-enabled battery management systems with warehouse energy management platforms is creating new software revenue streams.
Industry Challenges
- Electrolyte handling certification:OSHA ventilation standard compliance for sulfuric acid containment requires specialized technician training that outpaces workforce pipeline development.
- Interoperability fragmentation:Proprietary battery management system protocols from incumbent suppliers are complicating multi-brand fleet standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift Battery Market |
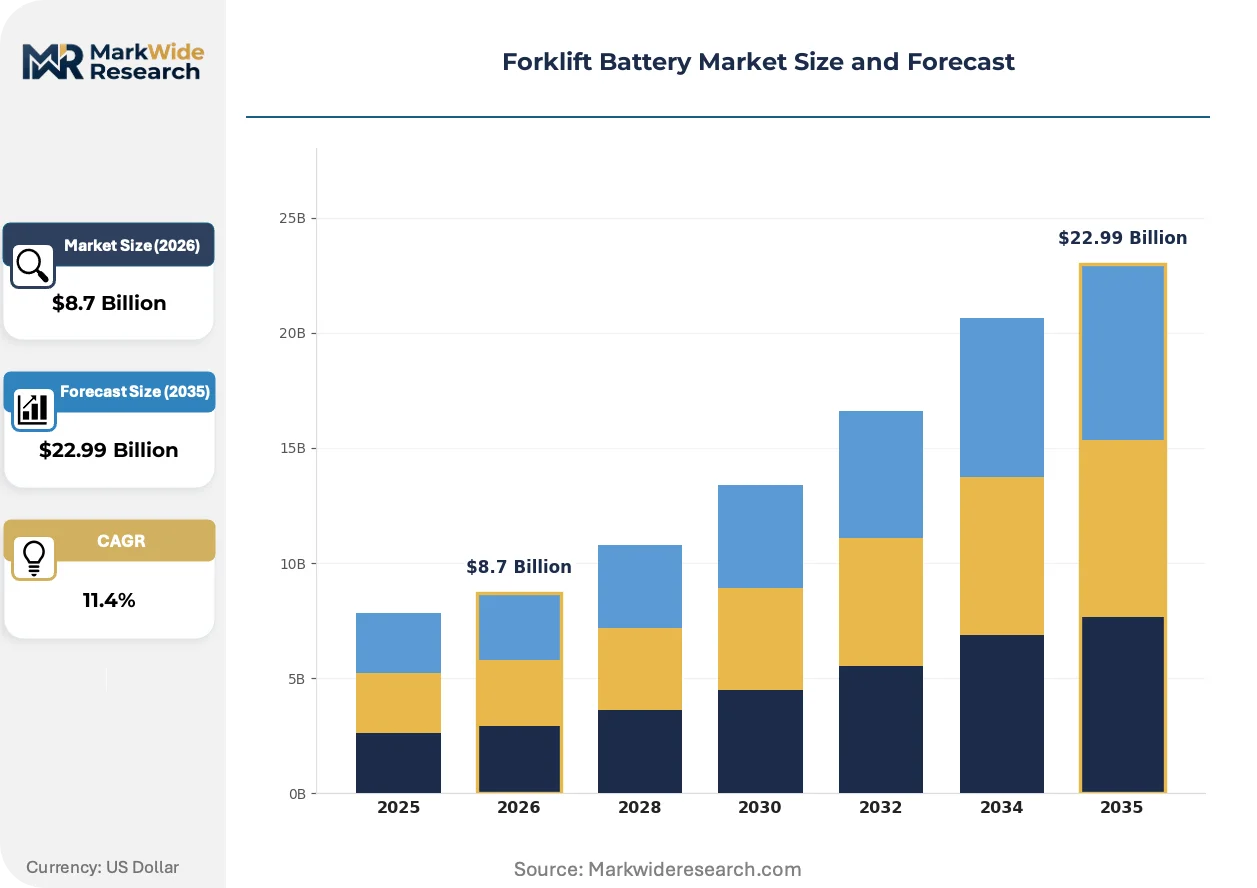
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Lead Acid, Lithium-ion, Nickel Cadmium, Others Application: Warehouse Operations, Construction, Manufacturing, Retail End User: Logistics, E-commerce, Automotive, Food & Beverage Technology: Fast Charging, Smart Charging, Maintenance-Free, Environmentally Friendly |
| Companies Covered | East Penn Manufacturing Company, Crown Battery Manufacturing, EnerSys, Hoppecke Batteries, Trojan Battery Company, GS Yuasa Corporation, Amara Raja Batteries, Flux Power Holdings, Exide Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift Battery Market Emerging Trajectories
Power system architecture is fragmenting along chemistry lines as fleet managers weigh total cost of ownership against capital constraints and charging infrastructure sunk costs.
Cell-to-pack designs are eliminating module housings and busbar assemblies from forklift battery construction. Tier-one automotive suppliers are licensing these architectures to industrial battery assemblers under technology transfer agreements. The technology is modularizing procurement patterns as warehouse operators swap standardized pack units rather than servicing individual cells or modules.
OSHA ventilation mandates for battery charging areas are tightening enforcement of hydrogen gas concentration limits and emergency eyewash station requirements. Facilities managers are responding by consolidating charging operations into purpose-built structures with automated fire suppression. Multi-shift distribution centers in the United States are most affected, with many operators accelerating lithium-ion conversion to eliminate watering protocols and ventilation infrastructure entirely.
Fleet operators are unbundling after-sales service contracts from initial equipment procurement. Third-party logistics providers are negotiating direct relationships with battery recyclers and refurbishment specialists to capture residual value. This pattern is most visible in German automotive supply chain hubs, where circular economy mandates and extended producer responsibility frameworks are reshaping supplier selection criteria toward cradle-to-cradle certified systems.
Forklift Battery Market Segmentation
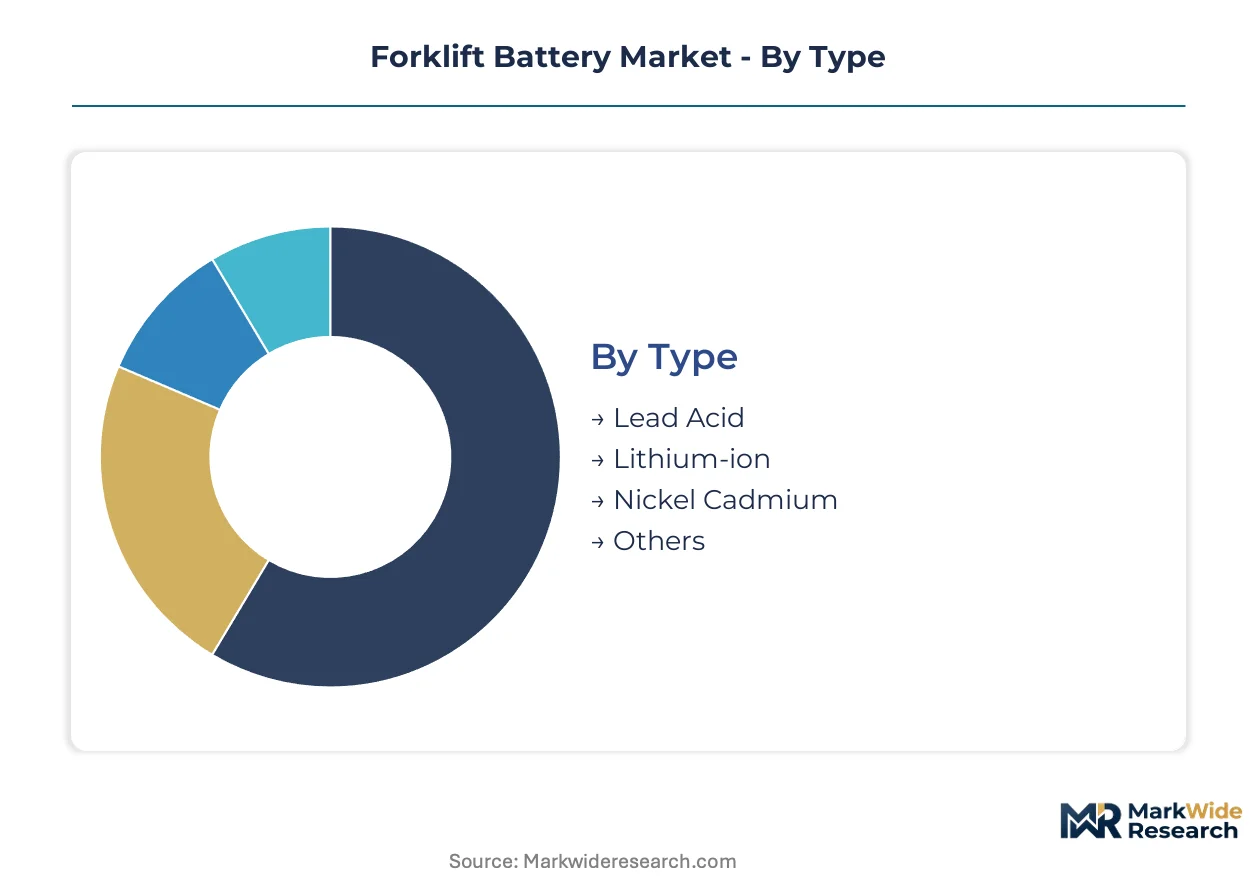
Forklift battery procurement patterns diverge sharply across chemistry types, operational environments, and charging infrastructure maturity. Fleet managers segment their sourcing decisions around total cost of ownership calculations, regulatory exposure, and shift intensity requirements.
Type:
Capital allocation separates buyers seeking lowest first cost from those prioritizing lifecycle economics and opportunity-charging flexibility.
- Lithium-ion:These batteries employ nickel-manganese-cobalt or lithium-iron-phosphate cathode formulations with integrated battery management systems. German automotive logistics hubs in Stuttgart and Wolfsburg are concentrating procurement here as EU F-Gas Regulation tightens indoor air quality mandates for multi-shift operations.
- Lead Acid:Flooded and sealed absorbed glass mat configurations dominate replacement cycles where existing charging bay infrastructure and watering system maintenance contracts create switching friction. North American third-party logistics providers with legacy fleet footprints represent the core demand cluster.
- Nickel Cadmium:Sintered plate designs tolerate extreme temperature cycling for cold storage applications in frozen food distribution centers.
- Others:Sodium-ion and solid-state experimental chemistries occupy pilot program budgets at technology-forward material handling operators.
Volume sits with Lead Acid; growth tilts toward Lithium-ion.
Application:
Operational intensity and dwell time availability determine whether fleets standardize on opportunity-charging architectures or retain battery swap infrastructure.
- Warehouse Operations:Multi-shift e-commerce fulfillment centers with 22-hour utilization cycles demand fast-charging compatible batteries. Amazon and Walmart distribution networks in the United States are eliminating dedicated battery changeout rooms entirely.
- Construction:Outdoor rough-terrain forklifts expose batteries to vibration and temperature extremes. Rental fleet operators in Texas and Florida prioritize sealed maintenance-free configurations to reduce field service calls.
- Manufacturing:Just-in-time automotive supply chains require predictable power delivery across 16-hour production schedules.
- Retail:Big-box store receiving docks with intermittent usage patterns favor lower-capital lead-acid systems.
Procurement scale clusters in Warehouse Operations; technology upgrade rates run highest there.
End User:
Contractual risk allocation and residual value capture shape whether end users own batteries outright or adopt service-based procurement models.
- Logistics:Third-party providers with asset-light balance sheets are piloting battery-as-a-service contracts to convert capital expenditure into operating expense. DHL and XPO Logistics operations in California and Illinois lead this transition.
- E-commerce:Vertical integration of fulfillment networks allows direct negotiation with cell manufacturers. Shein and Temu distribution expansions in the United Kingdom and Netherlands are sourcing lithium-ion packs through direct OEM relationships.
- Automotive:OEM captive fleets maintain strict supplier qualification protocols aligned with production quality systems.
- Food & Beverage:Cold chain operators face dual constraints of refrigeration load and material handling power demand.
Logistics commands current installed base; E-commerce shows steepest expansion trajectory.
Technology:
Charging infrastructure investment horizons separate early adopters of intelligent power management from operators extending legacy asset life.
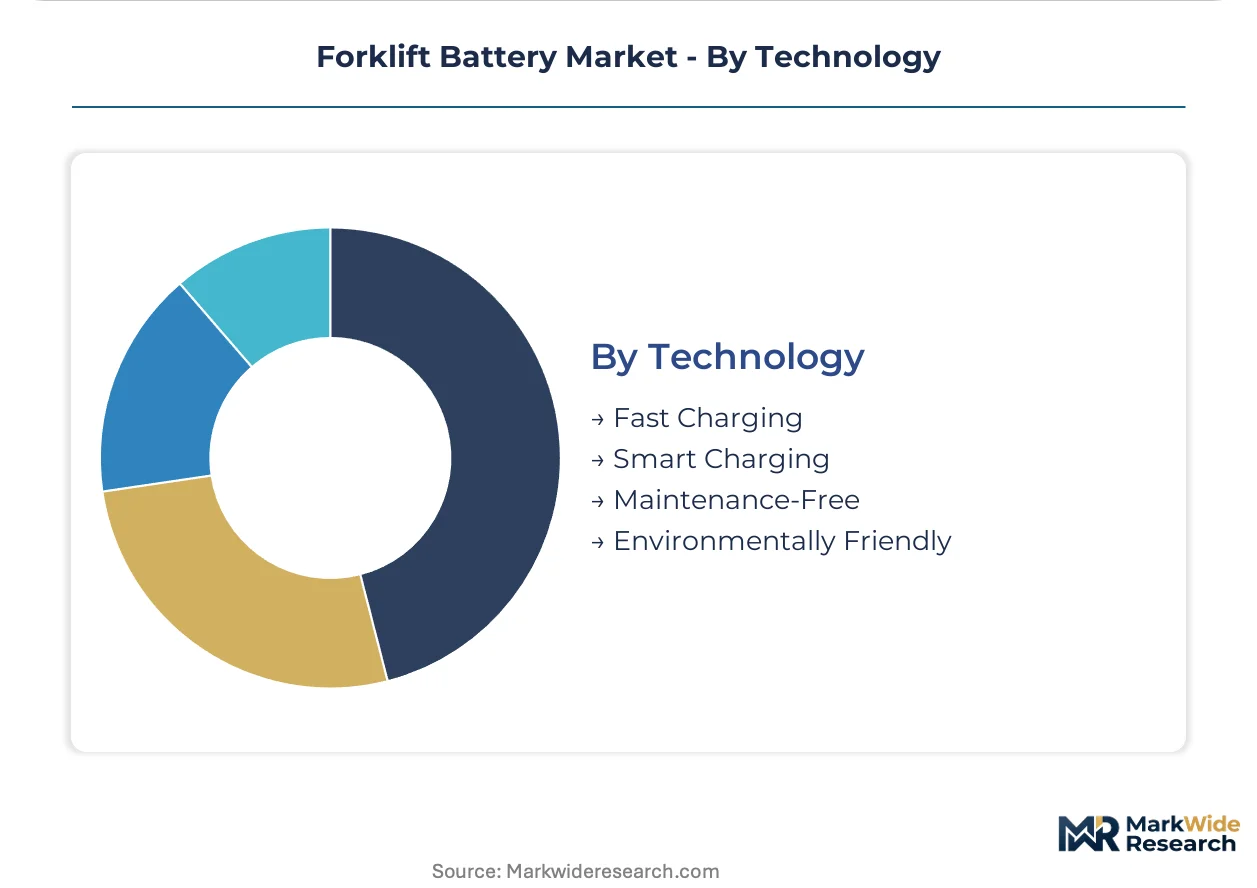
- Fast Charging:High-amperage systems deliver 80% state-of-charge in 30-45 minutes, eliminating shift-change battery swaps. Kroger and Target distribution centers are retrofitting charging bays with 350A output capability.
- Smart Charging:Telematics-integrated battery management systems communicate with warehouse energy management platforms to optimize demand charge avoidance.
- Maintenance-Free:Sealed valve-regulated designs eliminate watering protocols and ventilation infrastructure for smaller fleets without dedicated battery technicians.
- Environmentally Friendly:Cradle-to-cradle certified systems with documented recycling pathways satisfy extended producer responsibility requirements in German and French automotive supply chains.
Fast Charging anchors near-term upgrade budgets; Smart Charging gains share fastest as energy management platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in East Asian cell production hubs while consumption tilts toward North American and European distribution centers. Battery pack assembly gravitates toward logistics corridors where fleet electrification accelerates fastest.
United States
Multi-shift e-commerce fulfillment centers in California and Illinois drive lithium-ion procurement at scale. OSHA ventilation standards for battery charging areas tighten enforcement across Midwest distribution networks. Amazon and Walmart distribution hubs in Phoenix and Dallas-Fort Worth are eliminating dedicated battery changeout rooms entirely.
Germany
Automotive logistics corridors in Stuttgart and Wolfsburg anchor premium battery demand from just-in-time supply chains. EU F-Gas Regulation mandates indoor air quality standards that accelerate lead-acid displacement. Chemical manufacturing clusters along the Rhine River prioritize cradle-to-cradle certified systems for extended producer responsibility compliance.
China
Domestic cell manufacturing scale supports cost-competitive lithium-ion pack assembly for export markets. MIIT industrial standards govern battery management system interoperability for material handling equipment. Yangtze River Delta logistics hubs in Shanghai and Suzhou pilot sodium-ion alternatives for cold storage applications.
India
PLI scheme incentives for domestic cell manufacturing open procurement pathways for lithium-ion forklift batteries in emerging logistics corridors. Bureau of Indian Safety certification requirements extend supplier qualification timelines for imported systems. Maharashtra and Karnataka warehouse clusters near Mumbai and Bangalore lead electrification pilots among third-party logistics providers.
Japan
Integrated lead-acid and lithium-ion production lines serve captive demand from automotive and electronics manufacturing. METI energy efficiency standards shape charging infrastructure investment patterns. Chubu region industrial corridors around Nagoya maintain dense supplier networks for just-in-sequence material handling systems.
Forklift Battery Market Vendor Landscape
The competitive structure tilts toward integrated manufacturers with captive cell supply and established aftermarket service networks. Market concentration remains moderate with distinct tiering between multinational battery specialists and regional pack assemblers. Two archetypes dominate: chemistry-agnostic producers with dual lead-acid and lithium-ion portfolios, and pure-play lithium-ion specialists targeting opportunity-charging deployments. Capacity expansion and strategic technology licensing represent the primary competitive vectors as players position for fleet electrification acceleration.
Among established industrial battery manufacturers, EnerSys and GS Yuasa Corporation exemplify integrated scale archetypes with diversified chemistry portfolios and captive distribution networks. Crown Battery Manufacturing occupies a position within the North American specialist tier, serving price-sensitive material handling fleets with legacy lead-acid configurations. Flux Power Holdings represents the lithium-ion pure-play segment, targeting fast-charging compatible architectures for multi-shift warehouse operations.
| Leading Market Players |
|---|
| East Penn Manufacturing Company |
| Crown Battery Manufacturing |
| EnerSys |
| Hoppecke Batteries |
| Trojan Battery Company |
| GS Yuasa Corporation |
| Amara Raja Batteries |
| Flux Power Holdings |
| Exide Technologies |
| Others |
Supply Flow & Price Mechanics
Skilled battery technician concentrations in Michigan and Ohio widen pricing-tier spreads between premium lithium-ion service contracts and economy lead-acid replacement cycles. Labor-cost differentials across these Midwest maintenance hubs directly compress margins for aftermarket service providers serving price-sensitive third-party logistics fleets.
Pricing Analysis
Cost-down pressure on standard-tier lead-acid packs accelerates because lithium-ion opportunity-charging systems capture multi-shift warehouse contracts. Pricing stratifies across premium certified-lithium, standard lead-acid with service bundling, and economy direct-replacement tiers. Price differentiation traces to REACH compliance documentation costs and fast-charging infrastructure compatibility. Buyer price sensitivity peaks among North American third-party logistics operators with legacy fleet footprints; German automotive logistics hubs show lowest sensitivity due to cradle-to-cradle certification mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor European battery pack assembly flows. Cell manufacturing concentrates in China, South Korea, and Japan. Raw material dependencies draw from Chilean lithium brine operations, Indonesian nickel processing, and Chinese cathode precursor synthesis. Single-source vulnerability in lithium carbonate supply chains feeds from South American evaporation pond concentration. Distribution runs through captive OEM networks and independent material handling dealers serving aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification economics favor integrated manufacturers with captive cell supply, forcing standalone pack assemblers toward acquisition or exit. Lithium carbonate volatility and REACH compliance documentation burdens accelerate this consolidation dynamic.
For Market Incumbents: Extend aftermarket service contract penetration to lock in replacement-cycle revenue before lithium-ion conversion peaks. Deepen backward integration into battery management system firmware development to defend against pure-play software entrants. Prioritize certification investment for EU battery passport compliance to maintain German automotive logistics corridor access. For New Entrants and Emerging Players: The mid-tier price-point gap between premium lithium-ion and economy lead-acid creates white-space for sodium-ion pilot programs in cold storage applications. Target Indian logistics corridors near Mumbai and Bangalore where PLI scheme incentives reduce import qualification friction. Pursue battery-as-a-service financing structures to bypass capital expenditure barriers among asset-light third-party logistics providers. For Investors and Strategic Acquirers: Re-rating potential sits with lithium-ion pure-plays given fast-charging infrastructure buildout acceleration across North American distribution networks. Long-term viability favors specialists with telematics-integrated battery management platforms and direct OEM relationships. Watch sodium-ion chemistry maturation in Yangtze River Delta pilot programs as inflection indicator for next-generation chemistry displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Manufacturing | Captive lithium supply secures margin protection against carbonate price swings from Chilean and Australian producers. |
| Fast-Charging Infrastructure Partnership | 350A charging bay deployments at Kroger and Target distribution centers eliminate battery swap room capital requirements. |
| Battery-as-a-Service Platform Launch | Pay-per-cycle financing converts DHL and XPO Logistics procurement from capex to opex, expanding addressable fleet base. |
| EU Battery Passport Certification Program | REACH-compliant documentation systems satisfy extended producer responsibility mandates in Stuttgart automotive supply chains. |
| Sodium-Ion Chemistry Pilot Program | Cold storage trials in Shanghai and Suzhou logistics hubs test lithium alternative for frozen food distribution applications. |
Methodological Framework
Independent corroboration across fleet maintenance directors, OEM procurement teams, and aftermarket service heads underwrites the qualitative findings. Primary interviews with warehouse operations managers, battery technician training program leads, and third-party logistics sustainability officers combined with secondary validation from OSHA enforcement records, EPA lead recycling reports, EU F-Gas Regulation filings, and customs trade data. Bottom-up installation tracking and top-down industrial battery consumption estimates triangulate market sizing.
Rate-of-change decomposition across chemistry type, charging technology, and end-user procurement model structures the analytical framework over the projection horizon. Segmentation dimensions span lithium-ion versus lead-acid versus emerging chemistries, fast-charging versus conventional infrastructure, and captive fleet versus third-party logistics ownership patterns. CAGRs derive from shift-intensity growth curves in e-commerce fulfillment and regulatory electrification mandate trajectories. Lithium carbonate price volatility bands and charging infrastructure depreciation schedules feed sensitivity analysis.
Inputs from European battery passport pilot programs and Indian PLI scheme disbursement records were available through the study window; gaps in Chinese MIIT standard enforcement data introduce uncertainty bands around interoperability adoption timelines. Forecasts reflect documented assumptions regarding fleet replacement cycle acceleration and opportunity-charging penetration curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Light Towers Market
Batteries
Industrial Backup Battery Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Deep Cycle Battery Market
Batteries
North America Battery Market
Batteries
Breathing Battery Market
Batteries
India SLI Battery Market
Batteries
India Alkaline Battery Market
Batteries
Automotive Starting Battery Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Global Industrial Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
Tubular Batteries Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Electric Battery Market
Batteries
Lithium-Based Battery Charger Market