
 East Africa Battery Market | 2026-2036
East Africa Battery Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Battery Market Foresight
Telecom tower operators across East Africa are consolidating procurement through regional hubs, and this buyer concentration is pivoting contract terms toward multi-year supply agreements with performance guarantees. Panasonic Corporation leverages its lithium-ion cell technology leadership to anchor utility-scale storage deployments in Kenya and Ethiopia. Exide Industries Ltd sustains manufacturing proximity through its established African operations, competing on lead-acid replacement cycles for commercial fleets. Bodawerk International Ltd specializes in locally assembled battery packs for agricultural machinery, navigating import duty structures that favor regional content.
A battery is an electrochemical device that stores and releases electrical energy through reversible redox reactions between electrodes and electrolytes, with energy density typically measured in watt-hours per kilogram and cycle life defined by depth-of-discharge thresholds. Its primary commercial purpose is to provide portable or stationary power where grid connectivity is unreliable or unavailable, buffering intermittent generation from renewable sources. Lithium-ion chemistry dominates premium applications in electric mobility and solar-storage hybrids, where longer cycle life justifies higher upfront cost. Lead-acid technology occupies the mass-market tier for backup power and automotive starter functions across price-sensitive segments. Flow batteries represent an emerging structural bet for grid-scale duration storage, though current deployment remains limited to pilot projects.
Kenya's Energy Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority both enforce battery import standards that align with IEC 62660 cell safety protocols, shaping product eligibility for government tender programs. Rwanda's Rwanda Utilities Regulatory Authority has introduced e-mobility incentives that mandate local battery assembly partnerships, restricting market access to firms with domestic manufacturing commitments. Ethiopia's Ethiopian Energy Authority is drafting storage integration rules for its national grid expansion, creating compliance timelines that suppliers must anticipate. Stakeholders should monitor which regulator moves first on unified regional certification to avoid fragmented compliance costs across the East African Community customs union.
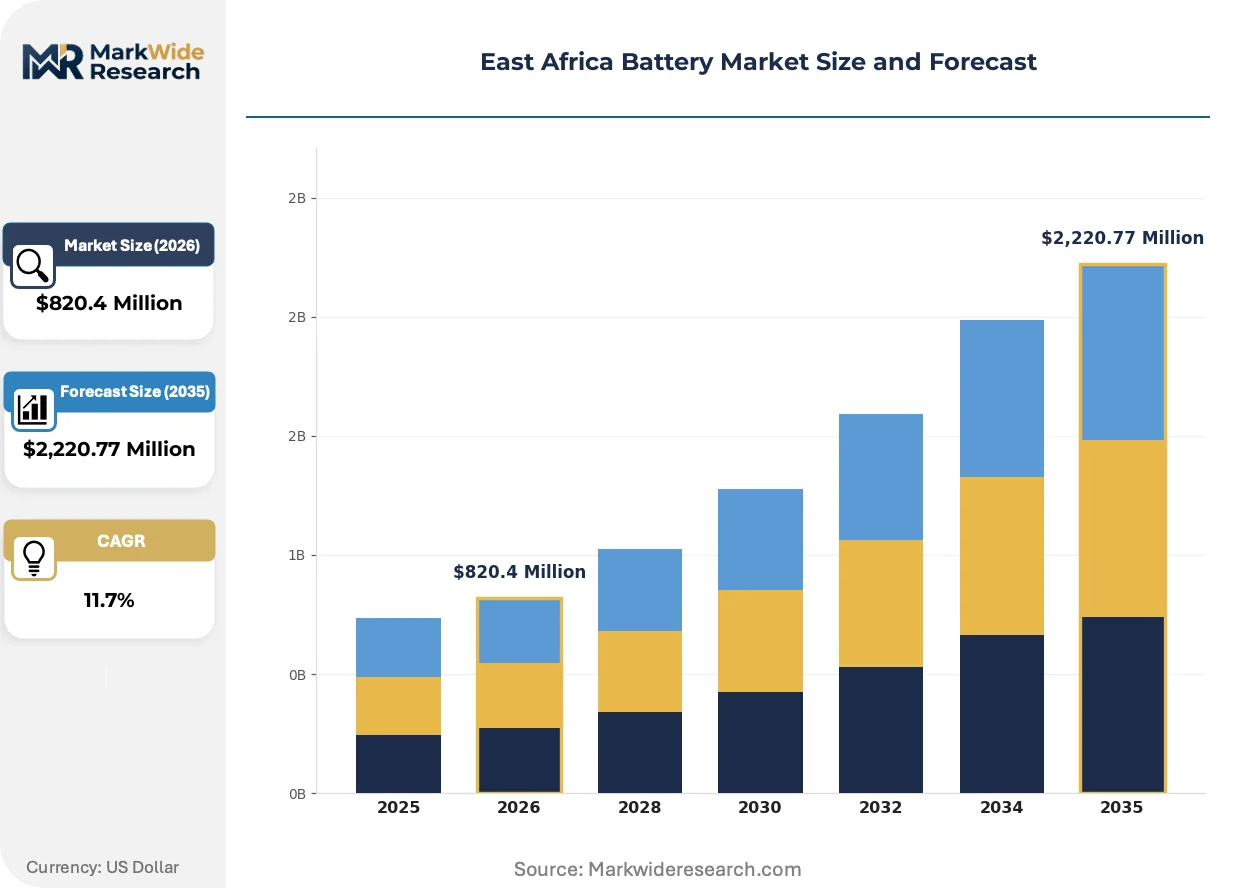
Market Dynamics
Lithium-ion cell chemistry is overtaking lead-acid across East Africa's solar-storage and mobility segments, compressing replacement cycles and forcing distributors to rebuild inventory profiles around higher-value, longer-life products.
Growth Catalysts
- Rural electrification acceleration:Kenya's Rift Valley region anchors bulk procurement from commercial farming operations and telecom tower operators expanding off-grid coverage.
- Import certification streamlining:Kenya's Energy Regulatory Authority has cut compliance timelines for battery energy storage systems, reducing distributor friction.
- Local assembly incentives:Rwanda's e-mobility mandates require domestic battery assembly partnerships, creating captive demand for regional manufacturing commitments.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs swing unpredictably, squeezing pack assembler margins and destabilizing project financing.
- Cell supply concentration:East African pack assemblers depend on concentrated Asian cell suppliers, exposing procurement to shipping disruptions and currency fluctuations.
- Lead-acid residual infrastructure:Existing recycling networks and technician familiarity with flooded lead-acid chemistry slow lithium-ion penetration in price-sensitive automotive starter segments.
Strategic Opportunities
- Ethiopian grid integration:The Ethiopian Energy Authority's pending storage integration rules for national grid expansion create first-mover positioning for compliant suppliers.
- Agricultural machinery electrification:Bodawerk International Ltd's locally assembled battery packs demonstrate how regional content rules favor domestic assembly for farm equipment applications.
- Regional certification harmonization:Stakeholders anticipate unified East African Community customs union standards that would eliminate fragmented compliance costs across Kenya, Tanzania, Rwanda, and Uganda.
Industry Challenges
- Electrochemical technician scarcity:Lithium-ion battery management system diagnostics and thermal runaway prevention require skills scarce in East African service networks.
- Multi-jurisdiction certification timelines:IEC 62660 alignment requirements vary between Kenya's Energy Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority, complicating regional product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Battery Market |
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $2,220.77 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-cadmium, Flow Batteries Application: Electric Vehicles, Renewable Energy Storage, UPS Systems, Consumer Electronics End User: Residential, Commercial, Industrial, Government Technology: Solar, Wind, Thermoelectric, Chemical |
| Companies Covered | Murata Manufacturing Co Ltd, Uganda Batteries Limited, Panasonic Corporation, ABM Group, Bodawerk International Ltd, Exide Industries Ltd, Toshiba Corporation, Trojan Battery Company, Duracell Inc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Battery Market Shifts & Advancements
Cell chemistry transitions, regulatory harmonization efforts, and buyer consolidation are restructuring how storage technology reaches end-users across Kenya, Tanzania, Ethiopia, and Rwanda.
Lithium iron phosphate (LFP) cathode formulations are overtaking nickel-manganese-cobalt alternatives in East African solar home systems. Off-grid installers in Kenya and Tanzania prioritize LFP's thermal stability and extended cycle life for rural deployments where replacement logistics prove costly. This chemistry shift is compressing the addressable market for lead-acid replacement cycles and elevating performance guarantee terms in supply contracts.
Rwanda's Utilities Regulatory Authority has introduced e-mobility incentives mandating local battery assembly partnerships, restricting tender access to firms with domestic manufacturing footprints. This policy architecture forces foreign cell suppliers to co-locate pack assembly operations or forfeit government-backed fleet electrification contracts. Two-wheeler and three-wheeler segments face the steepest compliance thresholds, with Rwanda's Kigali corridor serving as the regulatory testbed.
Telecom tower operators across East Africa are consolidating procurement through regional hubs, pivoting contract structures toward multi-year supply agreements with embedded performance guarantees. This buyer concentration displaces spot-market purchasing and forces cell suppliers to absorb longer receivable cycles. Kenya's Rift Valley and Tanzania's Dar es Salaam corridor exhibit the most pronounced procurement centralization, with tower operators leveraging scale to demand predictive maintenance telemetry integration.
East Africa Battery Market Segmentation
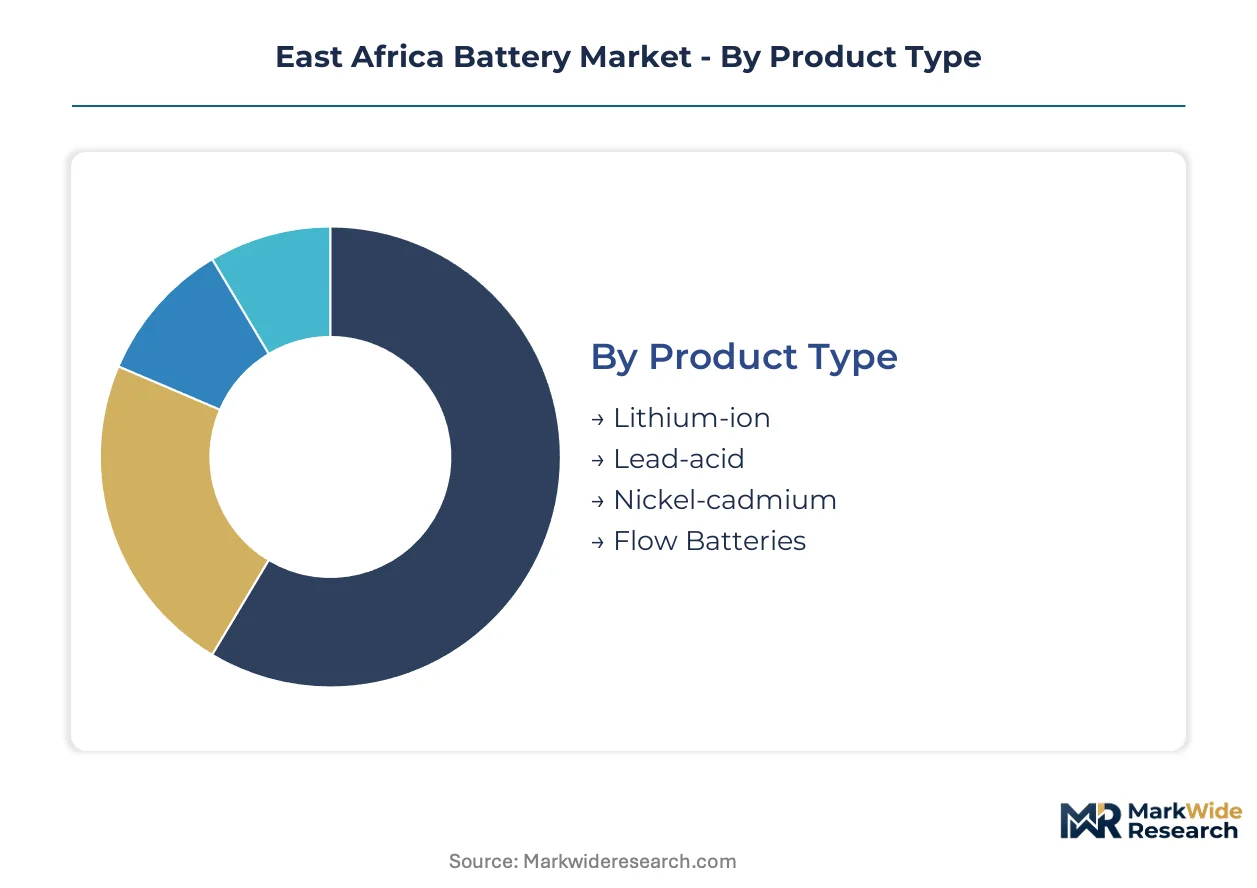
East Africa's battery market segments along electrochemical chemistry, end-use application, and procurement scale. Each axis reveals distinct margin structures and regulatory exposure across Kenya, Tanzania, Rwanda, and Ethiopia.
Product Type:
Cathode and anode material combinations determine energy density, cycle life, and thermal stability profiles across East African deployment conditions.
- Lithium-ion:Reversible intercalation chemistry stores 150-250 Wh/kg with 2,000-5,000 cycle durability. Kenya's Rift Valley telecom towers and Rwanda's Kigali e-mobility corridor anchor procurement. Lithium iron phosphate variants dominate solar home systems for thermal stability in ambient temperatures exceeding 35°C.
- Lead-acid:Flooded and valve-regulated designs deliver 30-50 Wh/kg with 300-800 cycle lifespans. Tanzania's Dar es Salaam automotive starter market and backup power segments sustain volume. Technician familiarity and established recycling networks slow displacement despite inferior energy density.
- Nickel-cadmium:Pocket plate and sintered electrode constructions tolerate deep discharge cycles across temperature extremes. Ethiopian grid stabilization pilots and railway signaling applications in Kenya utilize cadmium-bearing chemistry despite environmental handling restrictions.
- Flow Batteries:Vanadium redox and zinc-bromine systems decouple power and energy scaling for multi-hour duration storage. Ethiopian Energy Authority grid integration pilots represent the sole regional deployment, constrained by electrolyte logistics and membrane cost structures.
Mature deployment sits with lead-acid across automotive and backup segments. Newer deployment is concentrated in lithium-ion for solar-storage hybrids and electric mobility.
Application:
Load profile characteristics and duty cycle intensity shape battery specification requirements across mobility, stationary, and portable power domains.
- Electric Vehicles:Two-wheeler and three-wheeler segments in Rwanda's Kigali corridor drive pack demand with 2-5 kWh capacity requirements. Kenya's nascent bus electrification pilots and Ethiopia's Addis Ababa fleet trials expand addressable volume. Rwanda's local assembly mandates force foreign cell suppliers into domestic partnership structures.
- Renewable Energy Storage:Diurnal solar buffering for off-grid installations consumes 5-15 kWh residential systems and 50-500 kWh commercial arrays. Kenya's Rift Valley farming operations and Tanzania's rural electrification programs anchor procurement. Performance guarantee terms now extend to 10-year cycle life commitments.
- UPS Systems:Short-duration backup for telecom infrastructure, healthcare facilities, and financial services demands 15-minute to 4-hour runtime coverage. Lead-acid retains cost advantage in sub-10 kVA installations across price-sensitive segments.
- Consumer Electronics:Smartphone, laptop, and power tool applications source cylindrical and prismatic cells through regional distributors. Nairobi and Dar es Salaam retail channels concentrate import logistics.
Volume concentration rests with renewable energy storage. Margin expansion is sharpest in electric vehicles.
End User:
Procurement scale and technical specification authority fragment across household, enterprise, and institutional buyers.
- Residential:Individual households acquire 1-5 kWh solar home systems through PAYGO financing models. Kenya's off-grid solar penetration exceeds regional peers. Battery replacement cycles drive recurring revenue for distributors.
- Commercial:Farming cooperatives, telecom tower operators, and retail chains procure 10-100 kWh systems. Tanzania's tower consolidation through regional hubs concentrates buyer power and extends payment terms.
- Industrial:Manufacturing facilities and mining operations demand 100 kWh to multi-MWh installations for peak shaving and backup. Ethiopian industrial parks and Kenyan export processing zones represent qualified demand.
- Government:Rural electrification agencies, defense installations, and public infrastructure tenders specify IEC 62660-aligned products. Kenya's Energy Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority enforce divergent certification timelines.
Procurement scale peaks with government tenders. Payment reliability favors commercial buyers.
Technology:
Generation source integration requirements dictate battery management system architecture and cycling protocols.
- Solar:Photovoltaic coupling dominates East African deployment with daily cycling profiles. Maximum power point tracking integration and depth-of-discharge optimization shape pack design.
- Wind:Intermittent generation from Ethiopian and Kenyan highland sites requires rapid response buffering. Limited installed capacity constrains dedicated battery procurement.
- Thermoelectric:Waste heat recovery and remote power applications utilize solid-state conversion with minimal storage coupling. Niche industrial applications in geothermal-adjacent sites.
- Chemical:Fuel cell and hydrogen hybrid systems remain pre-commercial across the region. Pilot demonstrations in Rwanda's clean mobility strategy lack scaled procurement.
Installed base concentrates in solar coupling. Technology diversification is nascent in wind and chemical pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate supply routes from Zimbabwe's Bikita mine and the DRC's Manono deposit feed East African cell assemblers, anchoring procurement geography for Kenya, Tanzania, Rwanda, and Ethiopia.
Kenya
Telecom tower operators and Rift Valley farming cooperatives drive bulk procurement of solar-storage systems. Kenya's Energy Regulatory Authority enforces IEC 62660-aligned import certification for battery energy storage systems. Nairobi anchors distributor networks while Nakuru hosts commercial farming clusters deploying 50-500 kWh arrays.
Tanzania
Rural electrification programs and Dar es Salaam's automotive starter market sustain lead-acid volumes alongside lithium-ion growth. Tanzania's Energy and Water Utilities Regulatory Authority maintains parallel certification timelines to Kenya's framework. Telecom tower consolidation through regional procurement hubs concentrates buyer power in the commercial corridor.
Rwanda
E-mobility incentives mandate local battery assembly partnerships for government fleet tenders. Rwanda's Utilities Regulatory Authority restricts market access to firms with domestic manufacturing commitments. Kigali's two-wheeler and three-wheeler electrification corridor serves as the regional regulatory testbed for assembly requirements.
Ethiopia
Industrial parks and nascent bus electrification pilots generate qualified demand for grid-scale and mobility storage. Ethiopia's Energy Authority drafts storage integration rules for national grid expansion. Addis Ababa hosts fleet trials while industrial zones in the Oromia region demand peak-shaving installations.
Uganda
Off-grid solar penetration and agricultural machinery electrification create distributed demand across rural districts. Uganda's national standards body aligns with East African Community technical regulations for battery safety. Kampala's assembly operations supply regional content for farming equipment applications.
East Africa Battery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue localized assembly partnerships to satisfy domestic content mandates. Panasonic Corporation and Toshiba Corporation anchor premium lithium-ion supply through regional distribution networks. Three archetypes define competitive positioning: Asian cell suppliers leveraging technology leadership, Indian and Japanese manufacturers with established African operations, and local assemblers exploiting regional content rules. Capacity expansion and strategic partnerships dominate competitive moves, with foreign suppliers co-locating pack assembly to secure government tenders.
Among Japanese multinationals, Panasonic Corporation and Toshiba Corporation exemplify technology-led positioning in utility-scale and commercial segments. Exide Industries Ltd represents Indian manufacturing proximity competing on replacement cycle economics. Bodawerk International Ltd occupies the local assembly archetype, navigating import duty structures that favor regional content in agricultural applications. Murata Manufacturing Co Ltd and Trojan Battery Company sit within specialized tiers serving consumer electronics and deep-cycle industrial applications respectively.
| Leading Market Players |
|---|
| Murata Manufacturing Co Ltd |
| Uganda Batteries Limited |
| Panasonic Corporation |
| ABM Group |
| Bodawerk International Ltd |
| Exide Industries Ltd |
| Toshiba Corporation |
| Trojan Battery Company |
| Duracell Inc |
| Others |
Supply & Pricing Matrix
Lithium-ion cell assembly technician clusters in Kenya's Rift Valley and Tanzania's Dar es Salaam corridor anchor labor-cost differentials that widen pricing-tier spreads between premium certified packs and economy-grade lead-acid alternatives.
Pricing Analysis
Volume concentrates in lead-acid automotive starters and backup systems across price-sensitive segments, while margin expansion sits with lithium-ion solar-storage hybrids and e-mobility packs. Pricing stratifies across IEC 62660-certified premium tiers, standard commercial-grade offerings, and economy lead-acid replacements. Cost compression in economy tiers is intensifying because raw material input volatility squeezes pack assembler margins. Commercial farming cooperatives in Kenya's Rift Valley exhibit the sharpest price sensitivity, whereas telecom tower operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Lithium carbonate feedstock rests on Zimbabwe's Bikita mine and the DRC's Manono deposit, with cell fabrication concentrated in China, South Korea, and Japan. East African pack assemblers draw from concentrated Asian cell suppliers for cathode materials, electrolyte formulations, and battery management system components. Single-source vulnerability in lithium carbonate procurement exposes margins to shipping disruptions and currency fluctuations. Distribution runs through Nairobi and Dar es Salaam distributor networks that supply regional installers and end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa's battery market sits in a technology-transition phase as lithium-ion chemistry displaces legacy lead-acid across solar-storage and mobility applications.
For Market Incumbents: Acquire local assembly facilities to satisfy Rwanda's domestic content mandates and Kenya's regional procurement preferences. Panasonic Corporation and Exide Industries Ltd should expand pack assembly capacity in Nairobi to defend against emerging Asian entrants exploiting import duty differentials. Backward integration into lithium carbonate sourcing from Zimbabwe and the DRC reduces exposure to Asian cell supplier concentration. For New Entrants and Emerging Players: E-commerce distribution channels targeting Kenya's PAYGO solar home system segment offer white-space access with lower capital requirements than utility-scale tenders. Uganda's agricultural machinery electrification presents the most penetrable geography given Bodawerk International Ltd's limited production scale and import duty structures favoring regional content. Partner with established telecom tower operators to embed predictive maintenance telemetry as a differentiated service layer. For Investors and Strategic Acquirers: Re-rating potential sits with local assembly specialists given Rwanda's e-mobility mandates and Kenya's import certification streamlining. The five-to-ten-year viability window favors firms with captive lithium carbonate offtake and IEC 62660-aligned certification pathways. Acquisition targets should demonstrate domestic manufacturing commitments and established distributor relationships. Lithium carbonate price stabilization serves as the critical inflection indicator for margin recovery across the pack assembler tier.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | Rwanda's Utilities Regulatory Authority mandates domestic manufacturing for fleet electrification tenders. |
| Lithium Carbonate Backward Integration | Zimbabwe's Bikita mine and DRC's Manono deposit anchor raw material security for regional pack assemblers. |
| IEC 62660 Certification Investment | Kenya's Energy Regulatory Authority alignment unlocks government tender eligibility and telecom tower procurement. |
| Telecom Tower Performance Guarantee Contracts | Multi-year supply agreements with embedded telemetry integration displace spot-market purchasing in Kenya and Tanzania. |
| Agricultural Machinery Electrification | Regional content rules in Uganda and Kenya favor domestic assembly for farming equipment battery packs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with East African battery pack assemblers, telecom tower procurement officers, solar home system distributors, agricultural machinery OEMs, and energy regulatory authority officials. Kenya Energy Regulatory Authority import certification databases, Tanzania Energy and Water Utilities Regulatory Authority safety filings, Rwanda Utilities Regulatory Authority e-mobility incentive documentation, and East African Community customs union trade statistics provided quantitative foundations. Bottom-up unit economics modeling triangulated against top-down market sizing from regional electrification program disclosures.
Country-level modeling captured Kenya, Tanzania, Rwanda, Ethiopia, and Uganda across chemistry type, application segment, and end-user category granularity. Product-type segmentation distinguished lithium-ion, lead-acid, nickel-cadmium, and flow battery chemistries with distinct energy density and cycle life profiles. Application modeling separated electric vehicles, renewable energy storage, UPS systems, and consumer electronics with divergent duty cycle requirements. End-user segmentation captured residential, commercial, industrial, and government procurement scale and payment reliability differentials. CAGRs derived from installed base growth rates, replacement cycle compression, and electrification program expansion trajectories across the projection horizon.
The model holds under sustained rural electrification funding and lithium carbonate supply continuity; deviation in raw material price volatility or regulatory certification fragmentation would shift volume and value trajectories. A small set of named triggers warrants ongoing watch: lithium carbonate price stabilization, East African Community certification harmonization, and Rwanda e-mobility mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
FORTELION Battery Module Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Battery Swapping Market
Batteries
Denmark Rechargeable Battery Market
Batteries
North Europe Battery Market
Batteries
United Kingdom SLI Battery Market
Batteries
Elastic Battery Binders Market
Batteries
Lithium Starters Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Stationary Lead-Acid Battery Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Flow Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Power-Sports Batteries Market
Batteries
Residential Battery Market