
 Forestry Equipment Market | 2026-2036
Forestry Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Forestry Equipment Market Analysis
EU Deforestation Regulation (EUDR) is rebalancing the cost-of-entry calculus for equipment suppliers serving European timber supply chains. Deere & Company leverages its precision agriculture heritage to extend sensor-integrated harvester platforms into Nordic markets. Komatsu Ltd anchors its position through in-house production of hydraulic powertrains purpose-built for steep-terrain extraction. Tigercat International Inc. specializes in regional manufacturing configurations that navigate North American and European emission tier differences.
Forestry equipment encompasses mechanized machinery engineered for timber harvesting, processing, and site management, typically operating at engine outputs exceeding 100 kW and incorporating load-sensing hydraulic circuits for grapple and boom functions. Its primary commercial purpose centers on replacing manual felling with continuous-cut harvesting systems that integrate felling, delimbing, and bucking in single-pass operations. Harvesters command the largest value share within product type segmentation, driven by multi-year replacement cycles among Scandinavian logging companies. GPS Navigation and Automated Controls represent the fastest-expanding technology dimension, as contractors prioritize machine-guided cut-to-length systems that reduce residual stand damage and improve log assortment accuracy. Hydraulic Systems retain dominance across installed fleets, though electric motor adoption is accelerating in urban land-clearing applications where noise ordinances constrain conventional diesel operation.
EPA Tier 4 Final and EU Stage V emission frameworks shape engine architecture and after-treatment costs for manufacturers selling into regulated markets. BIS certification requirements in India and GB standards enforcement in China create divergent product validation pathways that fragment equipment specification globally. Stakeholders must monitor how carbon border adjustment mechanisms and emerging battery-electric duty cycles reshape total cost-of-ownership calculations across contractor procurement decisions.
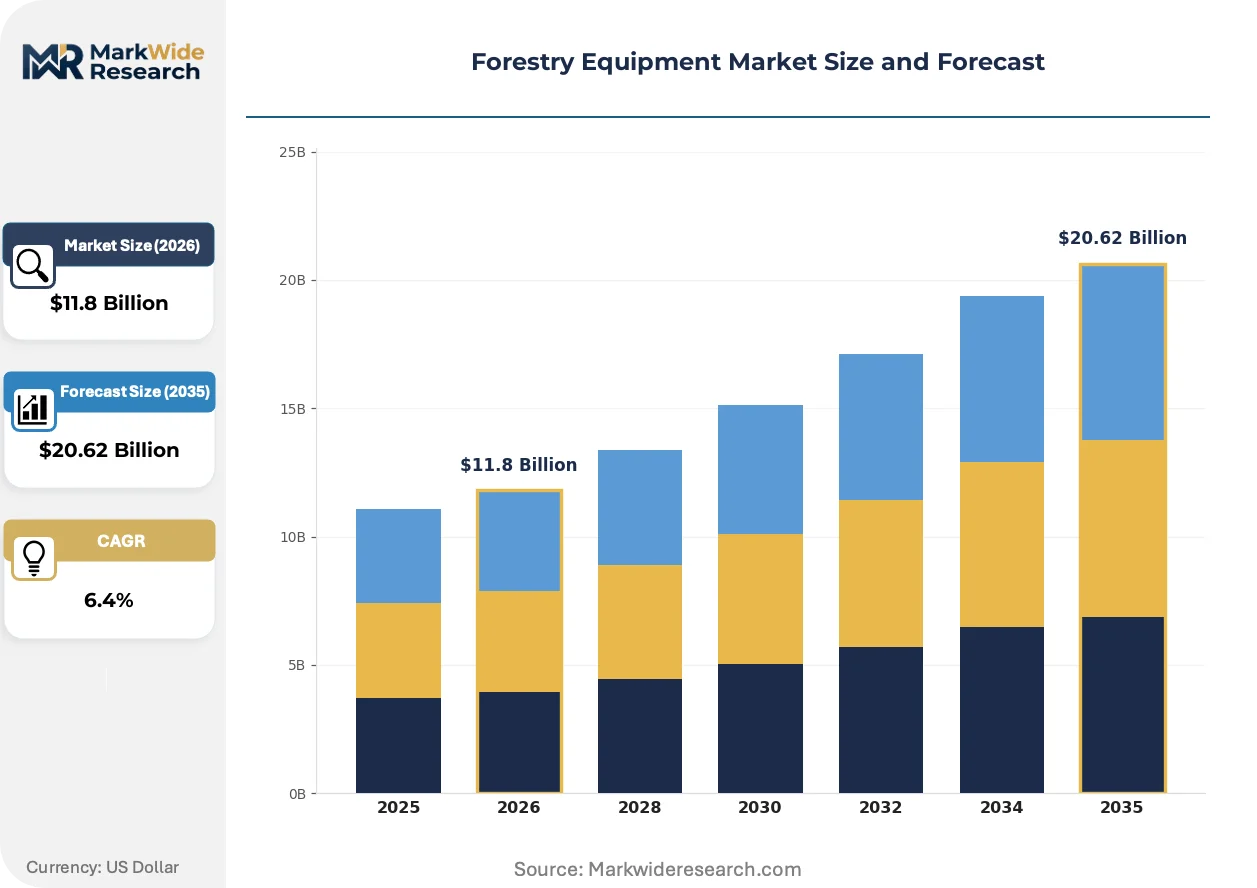
Market Dynamics
Mechanized cut-to-length harvesting systems are displacing manual felling across Scandinavian and Baltic timber supply chains as EU Deforestation Regulation compliance deadlines compress contractor equipment replacement cycles and reshape fleet composition toward sensor-integrated platforms.
Growth Catalysts
- EU Timber Regulation compliance deadlines:Scandinavian logging contractors face mandatory certified sustainable sourcing requirements that mechanized harvesting fleets satisfy through GPS-tracked chain-of-custody documentation.
- Precision forestry technology:Machine-guided cut-to-length systems reduce residual stand damage and improve log assortment accuracy, driving replacement demand among German and Finnish timber producers.
- Baltic equipment modernization:Aging forwarder and harvester inventories across Estonia, Latvia, and Lithuania create concentrated replacement demand as contractors seek emission-compliant platforms.
Market Restraints
- EPA Tier 4 Final and EU Stage V after-treatment costs:Diesel particulate filters and selective catalytic reduction systems add substantial capital burden to harvester and forwarder acquisitions, compressing contractor margins.
- Hydraulic component supply concentration:Precision load-sensing valves and high-pressure pumps for grapple and boom functions concentrate among specialized German and Japanese suppliers, creating procurement vulnerability.
- Electric duty cycle limitations:Battery-electric powertrains currently lack the sustained kilowatt-hour output required for steep-terrain extraction applications, constraining zero-emission adoption outside urban land-clearing.
Strategic Opportunities
- Urban land-clearing electrification:Noise ordinances in German and Swedish municipalities accelerate electric motor adoption for grapple saw and mulching equipment previously dominated by diesel hydraulic systems.
- Carbon border adjustment mechanism positioning:EU CBAM implementation creates first-mover advantage for equipment suppliers documenting embedded carbon in steel fabrication and engine manufacturing.
- Sensor-telemetry convergence:Integration of LiDAR stem detection with cloud-based fleet management platforms enables outcome-based harvesting contracts tied to cubic-meter recovery rates rather than machine-hour billing.
Industry Challenges
- Certified technician scarcity:Advanced diagnostics for CAN-bus controlled hydraulic circuits and emission after-treatment systems outpace vocational training capacity across Nordic logging regions.
- Dual certification burden:BIS requirements in India and GB standards enforcement in China fragment product validation pathways, forcing parallel engineering tracks that extend development timelines.
- Legacy fleet integration complexity:Older mechanical-control harvesters lack the data architecture to feed telemetry into modern fleet optimization platforms, creating stranded asset risk for contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forestry Equipment Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chainsaws, Harvesters, Chippers, Stump Grinders End User: Logging Companies, Timber Producers, Landowners, Contractors Application: Tree Felling, Wood Processing, Site Preparation, Land Clearing Technology: Hydraulic Systems, Electric Motors, GPS Navigation, Automated Controls |
| Companies Covered | Ponsse PLC, Volvo Construction Equipment, Deere & Company, Bell Equipment, Hitachi Construction Machinery Co. Ltd, Komatsu Ltd, Tigercat International Inc., Rottne Industri AB, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forestry Equipment Market Emerging Trajectories
GPS navigation and automated control systems are compressing operator skill requirements while elevating precision thresholds across European timber harvesting operations, fundamentally restructuring contractor workforce economics and equipment specification priorities.
LiDAR-based stem detection coupled with automated bucking optimization is overtaking manual measurement and operator judgment in cut-to-length harvester cabins. Baltic logging contractors adopting these platforms report reduced stem damage and improved value recovery per cubic meter. The technology is overtaking conventional harvester head designs that relied on mechanical diameter sensors and operator experience for log-length determination.
EU Deforestation Regulation traceability mandates now require geolocation tagging and timestamp verification for every harvested stem entering European supply chains. Equipment manufacturers must embed tamper-resistant GPS modules and encrypted data loggers directly into harvester and forwarder electronics. Scandinavian contractors face the steepest compliance burden as they supply certified timber to German and Dutch sawmills subject to EUDR enforcement.
Outcome-based contracting is displacing traditional machine-hour rental arrangements across Finnish and Swedish timber harvesting. Contractors now bid on cubic-meter recovery guarantees with penalties for residual stand damage, transferring yield risk from forest owners to equipment operators. This shift concentrates demand in southern Sweden and western Finland where large industrial forest owners possess the scale to structure performance-based agreements.
Forestry Equipment Market Segmentation
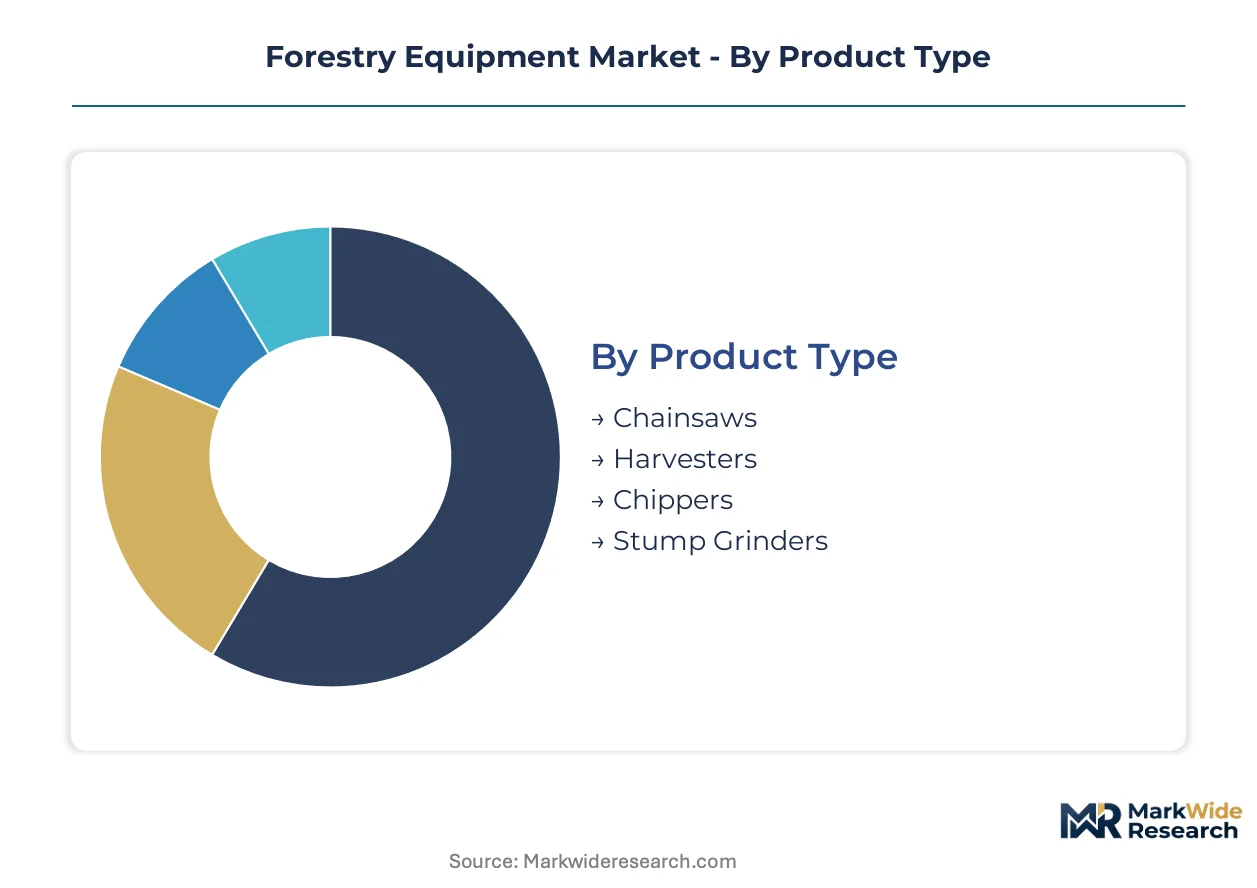
Segmentation in forestry equipment reveals how regulatory pressure and terrain constraints reshape procurement priorities across contractor tiers. Equipment specification diverges sharply between Scandinavian industrial harvesters and Baltic replacement cycles.
Product Type:
Replacement cycles dominate purchasing decisions as aging forwarder and harvester inventories across Estonia, Latvia, and Lithuania compress decision timelines toward emission-compliant platforms.
- Harvesters:Continuous-cut systems integrate felling, delimbing, and bucking through single-pass operations at engine outputs exceeding 100 kW. Scandinavian logging companies concentrate multi-year replacement demand here as EU Deforestation Regulation compliance deadlines force fleet modernization toward sensor-integrated platforms with GPS-tracked chain-of-custody documentation.
- Chainsaws:Portable internal combustion and battery-electric units serve manual felling in steep-terrain extraction where mechanized access proves uneconomical. German and Swedish municipalities accelerate electric motor adoption where noise ordinances constrain conventional diesel operation, though battery duty cycles limit sustained kilowatt-hour output for professional timber harvesting.
- Chippers:Drum and disc configurations reduce logging residue and urban land-clearing debris into uniform chip stock for biomass fuel or mulch applications.
- Stump Grinders:Hydraulic or mechanical drive systems remove residual root structures during site preparation for replanting or construction conversion.
Volume placements concentrate in Harvesters; the faster expansion belongs to Chainsaws as electrification penetrates municipal maintenance contracts.
End User:
Contractor scale determines technology absorption capacity, with large industrial forest owners structuring outcome-based agreements that transfer yield risk to equipment operators.
- Logging Companies:Mechanized fleet operators execute cut-to-length harvesting under cubic-meter recovery guarantees with penalties for residual stand damage. Finnish and Swedish industrial forest owners possess the scale to structure these performance-based agreements, concentrating demand in southern Sweden and western Finland.
- Contractors:Independent operators bid on machine-hour or outcome-based contracts using leased or owned equipment across fragmented Baltic and Central European timber supply chains. These stakeholders face the steepest EU Deforestation Regulation compliance burden as they supply certified timber to German and Dutch sawmills.
- Timber Producers:Vertically integrated forest owners combine harvesting operations with sawmill or pulp mill ownership.
- Landowners:Private and public forest holders contract harvesting services rather than maintaining captive equipment fleets.
Procurement authority clusters with Logging Companies; Contractors gain share fastest as outsourcing concentrates specialized harvesting expertise.
Application:
Site conditions and end-product specifications dictate equipment configuration, from precision stem selection to bulk biomass recovery.
- Tree Felling:Mechanized harvester heads with LiDAR stem detection and automated bucking optimization displace manual measurement in cut-to-length systems. Baltic contractors report reduced stem damage and improved value recovery per cubic meter versus conventional mechanical diameter sensors.
- Wood Processing:Delimbing, bucking, and sorting operations integrated into harvester platforms or executed at centralized yard facilities.
- Site Preparation:Scarification, mounding, and drainage restoration using dedicated forwarders or attachment-equipped excavators.
- Land Clearing:Urban and peri-urban vegetation removal where noise ordinances and emission regulations constrain equipment selection most severely.
Activity intensity peaks in Tree Felling; Land Clearing expands most quickly as urban boundary expansion and infrastructure construction accelerate.
Technology:
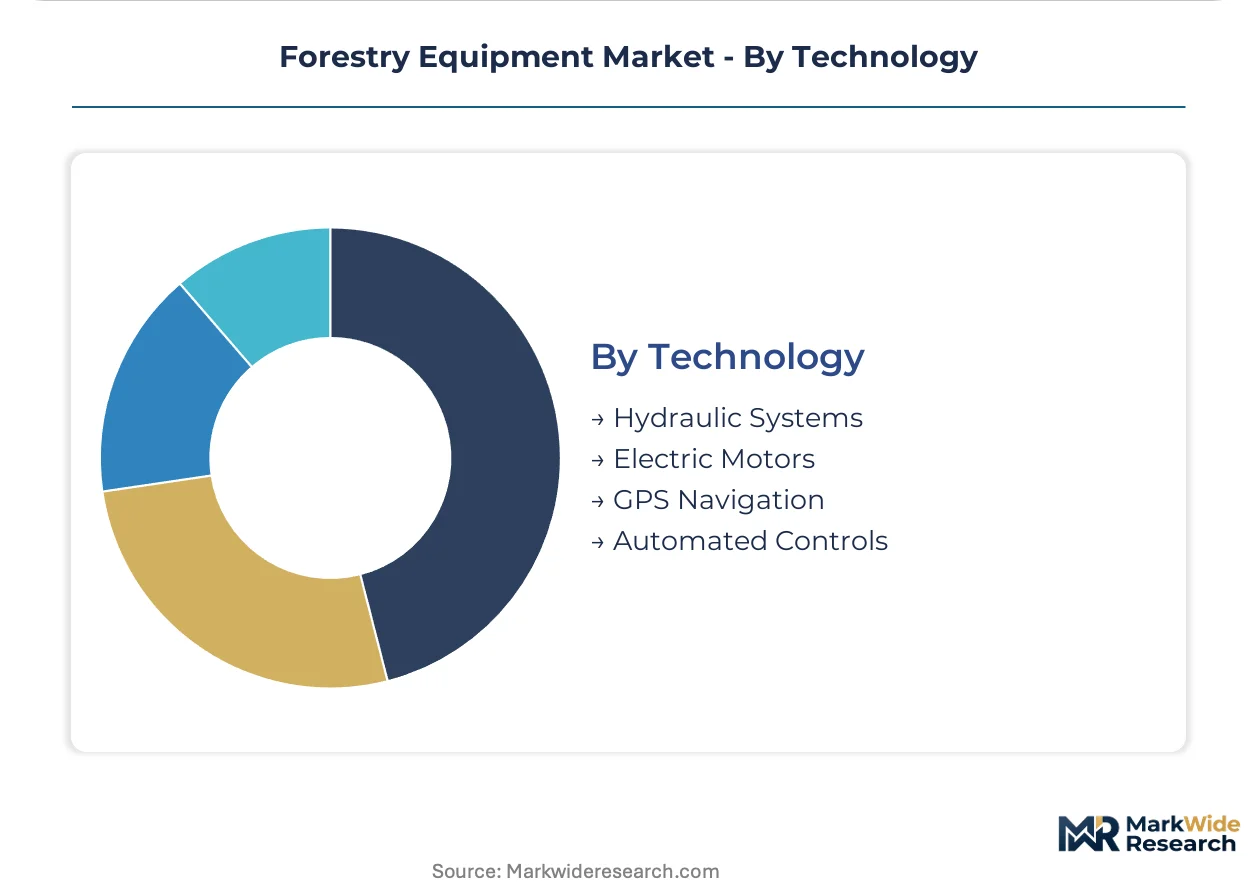
Powertrain architecture and control systems differentiate equipment performance tiers, with hydraulic dominance eroding in noise-sensitive applications.
- GPS Navigation:Machine-guided cut-to-length systems reduce residual stand damage and improve log assortment accuracy through geolocation tagging and timestamp verification for every harvested stem. EU Deforestation Regulation traceability mandates now require tamper-resistant GPS modules and encrypted data loggers embedded directly into harvester electronics.
- Automated Controls:CAN-bus controlled hydraulic circuits and emission after-treatment systems outpace vocational training capacity across Nordic logging regions, creating certified technician scarcity.
- Hydraulic Systems:Load-sensing circuits for grapple and boom functions retain dominance across installed fleets, though component supply concentrates among specialized German and Japanese suppliers.
- Electric Motors:Battery-electric powertrains currently lack sustained output for steep-terrain extraction, constraining adoption to urban land-clearing where noise ordinances prevail.
Installed base tilts toward Hydraulic Systems; GPS Navigation climbs the fastest as EU regulatory compliance hardens data architecture requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian timber supply chains concentrate mechanized harvesting investment through Swedish and Finnish special economic zones that incentivize precision forestry technology adoption.
Sweden
Southern Swedish logging contractors structure outcome-based harvesting contracts tied to cubic-meter recovery guarantees. EU Deforestation Regulation traceability mandates force embedded GPS modules and encrypted data loggers into harvester electronics. Västerbotten and Norrbotten counties host the densest concentration of cut-to-length fleet modernization.
Finland
Western Finnish industrial forest owners possess scale to impose performance-based agreements with penalties for residual stand damage. EU Timber Regulation compliance deadlines compress equipment replacement cycles toward sensor-integrated platforms. Kainuu and North Karelia regions drive demand for automated bucking optimization systems.
Germany
German municipalities accelerate electric motor adoption for urban land-clearing grapple saws where noise ordinances constrain diesel hydraulic operation. EU Stage V emission frameworks shape engine architecture and after-treatment costs for domestic manufacturers. Baden-Württemberg and Bavaria concentrate precision forestry technology demand from sawmill operators.
United States
Pacific Northwest timber producers face EPA Tier 4 Final after-treatment cost burdens on harvester and forwarder acquisitions. USDA forest management programs incentivize mechanized thinning operations on federal timber sales. Washington and Oregon logging contractors modernize aging forwarder inventories toward emission-compliant platforms.
Canada
British Columbia coastal contractors navigate steep-terrain extraction applications where battery-electric powertrains lack sustained kilowatt-hour output. Health Canada and PMRA coordinate with provincial regulators on equipment emission certification pathways. Interior British Columbia and Alberta foothills concentrate hydraulic powertrain demand for grapple and boom functions.
Forestry Equipment Market Vendor Landscape
North American producers anchor the scale-driven tier; Nordic specialists hold the precision-technology segment. The vendor base organizes around three strategic archetypes: diversified construction equipment conglomerates with forestry divisions, dedicated harvester-forwarder pure-plays, and regional fabrication shops serving emission-tier niche markets. Competitive moves concentrate on in-house production of hydraulic powertrains and sensor-telemetry platform integration.
Among Nordic pure-plays, Ponsse PLC and Rottne Industri AB exemplify the dedicated harvester-forwarder archetype with concentrated exposure to Scandinavian replacement cycles. Deere & Company occupies a position bridging agricultural precision heritage with forestry platform extension. Komatsu Ltd anchors the construction-conglomerate tier through purpose-built steep-terrain extraction systems.
| Leading Market Players |
|---|
| Ponsse PLC |
| Volvo Construction Equipment |
| Deere & Company |
| Bell Equipment |
| Hitachi Construction Machinery Co. Ltd |
| Komatsu Ltd |
| Tigercat International Inc. |
| Rottne Industri AB |
| Caterpillar Inc. |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of hydraulic powertrains anchors both the supply position and pricing power for tier-one manufacturers serving emission-regulated markets. German and Japanese component suppliers concentrate precision load-sensing valve production, creating procurement leverage that feeds into harvester platform cost structures across Scandinavian and Baltic contractor fleets.
Pricing Analysis
Short lead-time premiums command substantial markups as Baltic contractors face compressed EU Deforestation Regulation compliance deadlines. Three-tier pricing structure across premium sensor-integrated platforms, standard emission-compliant units, and economy-tier legacy configurations stratifies the market. Cost compression in standard-tier harvesters intensifies because EPA Tier 4 Final after-treatment systems add fixed capital burdens regardless of platform sophistication. Independent contractors exhibit highest price sensitivity due to thin margins on machine-hour contracts, while industrial forest owners absorb premium tier pricing for outcome-based cubic-meter guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Swedish and Finnish industrial forest owners, while dealer networks serve fragmented Baltic contractor segments. Manufacturing concentrates in Germany, Finland, and Japan for precision hydraulic components and control systems. Steel fabrication and high-pressure pump production draw from specialized German and Japanese suppliers, creating single-source vulnerability for load-sensing circuits. Distribution runs through regional equipment dealers with certified technician capacity, though CAN-bus diagnostic scarcity constrains aftermarket service reach across Nordic logging regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPS-tracked chain-of-custody systems are displacing manual documentation and mechanical-control harvesters across EU-regulated supply chains. This technology-transition phase compresses replacement cycles and elevates sensor-telemetry platforms from optional to mandatory specification.
For Market Incumbents: Extend precision agriculture heritage into forestry telemetry platforms to capture EUDR-mandated data architecture demand. Deepen backward integration into hydraulic powertrain production to defend margin position against German and Japanese component supplier concentration. Prioritize certified technician training partnerships across Västerbotten and Norrbotten counties to constrain aftermarket service competition. For New Entrants and Emerging Players: Municipal electric grapple saw operators in German and Swedish urban boundaries represent an underserved buyer archetype with noise-ordinance-driven procurement autonomy. Target battery-electric duty cycle optimization for land-clearing applications where steep-terrain extraction constraints exclude established diesel-hydraulic incumbents. Pursue direct municipal contracting relationships bypassing dealer network barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in precision-telemetry pure-plays with EUDR-compliant data logger integration and established Scandinavian fleet relationships. Long-term viability hinges on carbon border adjustment mechanism positioning and embedded carbon documentation capabilities. Monitor EU CBAM implementation timelines as inflection indicator for first-mover valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Telemetry Platform Integration | LiDAR stem detection with cloud fleet management enables outcome-based cubic-meter contracting. |
| Hydraulic Powertrain Backward Integration | In-house production of load-sensing circuits reduces dependency on concentrated German and Japanese suppliers. |
| Certified Technician Training Expansion | CAN-bus diagnostic capacity constraints across Nordic regions create captive aftermarket revenue streams. |
| Electric Duty Cycle Development | Battery-electric optimization for urban land-clearing addresses noise ordinance procurement requirements. |
| Carbon Border Adjustment Positioning | Embedded carbon documentation in steel fabrication and engine manufacturing secures EU CBAM first-mover advantage. |
Methodological Framework
Independent corroboration across equipment procurement directors at Scandinavian logging companies, aftermarket service managers at regional dealer networks, and hydraulic component sourcing leads at tier-one manufacturers underwrites the qualitative findings. Primary interviews with fleet optimization officers, certified technician training coordinators, and EU regulatory compliance specialists combined with secondary validation from EPA certification databases, EU Timber Regulation implementation reports, and customs trade data for harvester and forwarder imports. Bottom-up equipment shipment analysis and top-down timber harvesting activity estimates triangulate market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user scale, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis, EUDR compliance deadline impact assessment, and precision forestry technology penetration curves. Industry-specific inputs encompass Baltic forwarder fleet age profiles and German municipal electric equipment procurement trajectories.
Revisions become necessary when EU Deforestation Regulation enforcement timelines shift, battery-electric duty cycle capabilities breach steep-terrain extraction thresholds, or carbon border adjustment mechanism scope expands beyond pilot phases. Forecasts reflect assumptions regarding technician training capacity expansion and hydraulic component supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Cordless Handheld Cultivator Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Solar Fruit Dryer Market