
 Plow Folding System Market | 2026-2036
Plow Folding System Market Size, Share, and Industry Trends Forecast 2026-2036
Plow Folding System Market Analytics
Preventive maintenance subscriptions and telemetry-enabled service contracts is pivoting how OEMs capture lifetime value from municipal and contractor fleets. Eastey leverages its regional dealer density to lock in recurring revenue streams across Midwest snow removal operations. ABM Equipment sustains competitive positioning through vertical integration into hydraulic actuator production. MFT Automation specializes in compact-class electric folding systems for landscape professionals seeking reduced fuel overhead.
A plow folding system integrates hydraulic, mechanical, or electric actuation mechanisms that enable snowplow blades to collapse into transport configurations without manual disassembly, typically achieving fold cycles under 30 seconds and operating pressure ratings exceeding 3,000 PSI for municipal-grade hydraulic units. The primary purpose centers on reducing equipment transport width, protecting blade edges during road transit, and enabling rapid deployment across multi-route snow removal operations. Hydraulic folding plows occupy the dominant revenue position given their torque density and proven performance in severe cold-cycle conditions, while electric folding plows represent the fastest-expanding category as battery-electric municipal vehicles gain fleet share. Steel remains the baseline material specification for heavy-duty contractor applications, though aluminum variants command premium positioning where fuel economy regulations tighten operational cost structures.
EPA Tier 4 Final emissions standards and NHTSA highway transport width regulations directly shape product design requirements and fleet procurement criteria across United States municipal buyers. ISO 9001 quality management and AWS D1.1 structural welding standards further constrain supplier qualification for public-sector contracts. Stakeholders must monitor electrification timelines in municipal fleet procurement mandates and assess captive service revenue potential before equipment margins compress under total-cost-of-ownership bidding frameworks.
Market Dynamics
Municipal fleet electrification mandates are compressing procurement cycles for hydraulic-compatible folding architectures while simultaneously opening parallel demand tracks for all-electric actuation systems. This dual-technology pressure is forcing incumbent OEMs to maintain dual product lines without sacrificing the torque density advantages that retain heavy-duty contractor loyalty.
Growth Catalysts
- EPA Tier 4 Final Emissions Standards:Municipal buyers in the Upper Midwest must replace legacy diesel-powered plow trucks, triggering synchronized fleet-wide folding system upgrades that bundle with chassis procurement.
- Battery-Electric Municipal Vehicle Adoption:Cities across Minnesota and Wisconsin are piloting electric snow removal fleets that demand compact electric folding systems with reduced parasitic load on battery packs.
- ISO 9001 Certification Requirements:Public-sector contract eligibility now hinges on documented quality management systems, filtering out uncertified fabricators and consolidating specification authority with qualified suppliers.
Market Restraints
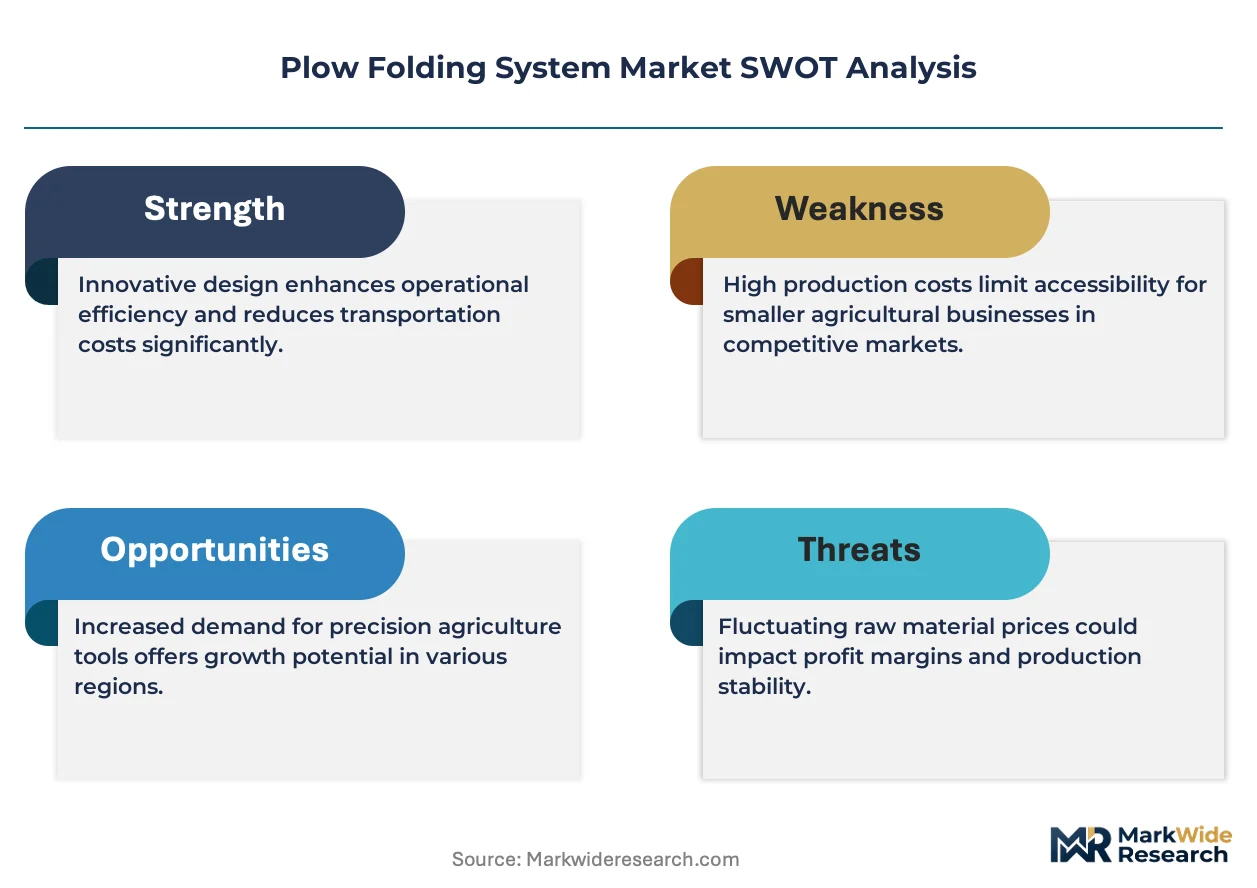
- Hydraulic Fluid Cold-Weather Performance:Synthetic hydraulic fluids rated for sub-zero viscosity carry 40-60% cost premiums over standard formulations, eroding operating margins for contractor fleets in North Dakota and Montana.
- Steel Price Volatility:Structural-grade steel plate specifications for heavy-duty moldboards expose fabricators to commodity swings that compress bid profitability on fixed-price municipal contracts.
- Electrification Timeline Uncertainty:Inconsistent federal funding disbursement for EV infrastructure creates fleet planning paralysis, delaying folding system replacement decisions across mid-sized municipal departments.
Strategic Opportunities
- Telematics-Enabled Service Contracts:Real-time fold-cycle monitoring and predictive hydraulic maintenance is creating recurring revenue streams that offset equipment margin compression in competitive bidding environments.
- Aluminum Alloy Adoption in Fuel-Economy-Conscious Fleets:Lightweight folding architectures are penetrating landscape contractor segments where tow vehicle fuel costs dominate total ownership calculations.
- NHTSA Width Regulation Compliance Services:Transport configuration verification and roadside inspection support packages represent untapped value-adds for OEMs serving multi-state contractor operations.
Industry Challenges
- AWS D1.1 Structural Welding Certification Scarcity:Qualified welders capable of certifying municipal-grade plow frames command wage premiums that inflate production costs beyond automated fabrication alternatives.
- Dual Hydraulic-Electric Platform Development:Engineering teams must simultaneously optimize for 3,000 PSI hydraulic circuits and 48V electric architectures without fragmenting R&D budgets across incompatible design paradigms.
- Legacy Fleet Retrofit Integration:Backward compatibility with 10-15 year old truck chassis requires custom mounting bracket engineering that delays project timelines and strains technical support resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plow Folding System Market |
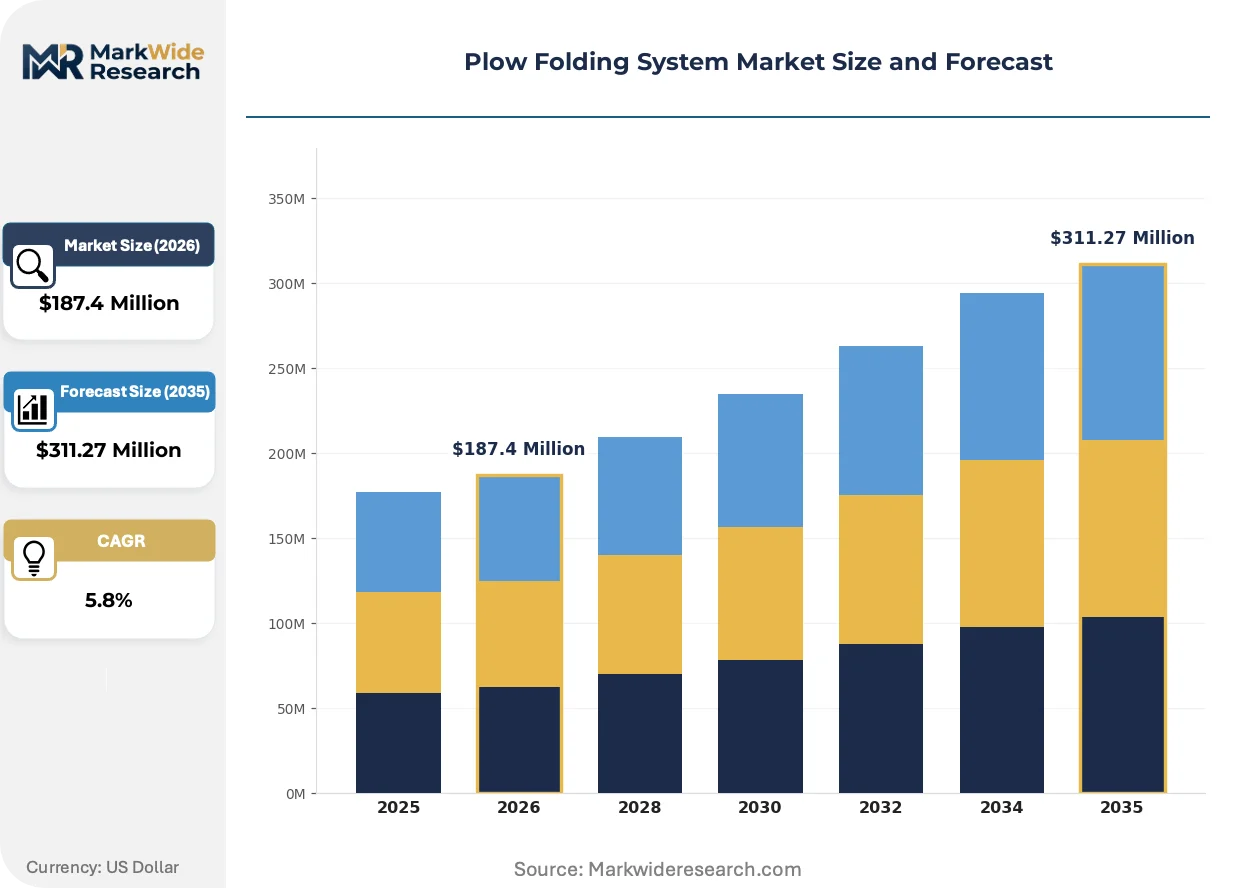
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Folding Plows, Mechanical Folding Plows, Manual Folding Plows, Electric Folding Plows End User: Agriculture, Municipalities, Contractors, Landscape Professionals Size: Compact, Medium, Large, Extra Large Material: Steel, Aluminum, Composite, Iron |
| Companies Covered | Eastey, Planar Motor Inc., ABM Equipment, Horizon, Capmatic Ltd., MFT Automation, McGinn-Wilkins Automation Inc., Advantage Puck Technologies, LLC, Durst Organization, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plow Folding System Market Evolving Landscape
Electrification is bifurcating product development roadmaps while connected service layers are capturing value downstream from hardware transactions. These simultaneous shifts are compressing traditional equipment margins while expanding addressable revenue per installed unit.
Electric linear actuation is overtaking hydraulic cylinders in sub-10,000 lb GVW municipal applications where duty cycles permit reduced torque density. Wisconsin DOT pilot programs are validating 20-second fold cycles at 48V, and this performance threshold is enabling single-motor architectures that slash maintenance intervals and eliminate fluid contamination risks.
EPA enforcement of idle-reduction protocols is tightening specification language in Minnesota and Iowa municipal RFPs. Contract penalties for excessive warm-up periods are driving demand for rapid-deploy folding systems that minimize pre-positioning time, and this regulatory pressure is accelerating specification migration toward electric actuation that eliminates hydraulic warm-up requirements.
Subscription-based maintenance is displacing transactional parts sales across Upper Midwest dealer networks. Landscape contractors in Michigan are locking in multi-season service agreements that bundle telemetry monitoring with preventive actuator replacement, and this shift is concentrating aftermarket value with OEM-captive service operations rather than independent repair facilities.
Plow Folding System Market Segmentation
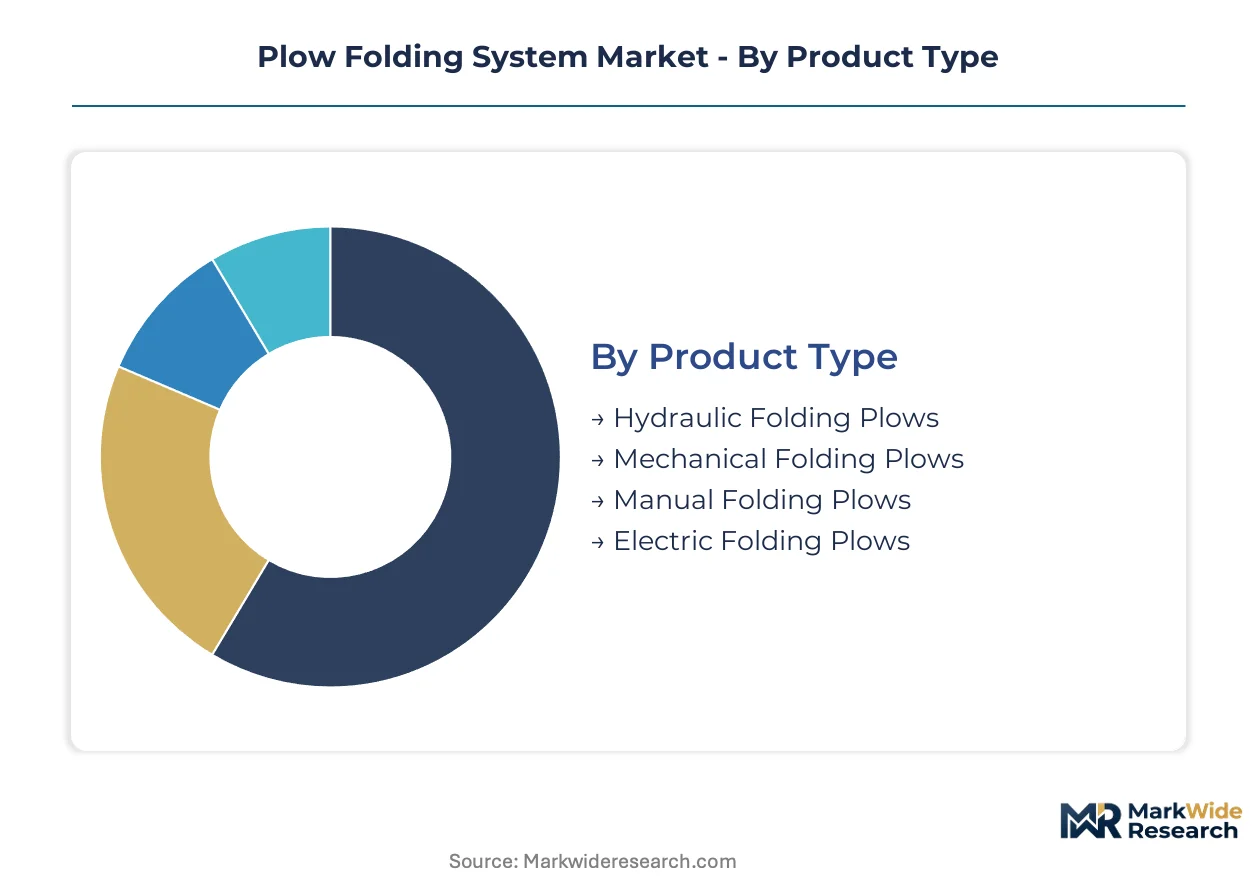
Plow folding system procurement specifications diverge sharply across municipal, contractor, and agricultural channels, with certification requirements and duty-cycle demands dictating viable product configurations. Understanding these segment boundaries clarifies where engineering investments concentrate and which customer types drive specification migration toward electric architectures.
Product Type:
ISO 9001 quality management certification filters out uncertified fabricators across all four product categories, while AWS D1.1 structural welding standards specifically constrain hydraulic and mechanical folding plow suppliers bidding municipal contracts.
- Hydraulic Folding Plows:These systems leverage 3,000+ PSI hydraulic circuits delivering torque density for severe cold-cycle conditions. Municipalities in Minnesota and Wisconsin specify hydraulic units for heavy-duty route clearing where fold cycles under 30 seconds minimize pre-positioning time. EPA Tier 4 Final emissions compliance for legacy diesel chassis sustains synchronized fleet-wide replacement demand.
- Electric Folding Plows:Compact 48V linear actuation architectures eliminate hydraulic warm-up requirements and fluid contamination risks. Battery-electric municipal vehicle pilots in Wisconsin DOT programs validate 20-second fold cycles, positioning this category for procurement cycles tied to fleet electrification mandates.
- Mechanical Folding Plows:Leverage-and-latch architectures serve cost-sensitive agricultural operators in North Dakota prioritizing mechanical simplicity over deployment speed.
- Manual Folding Plows:Basic hinge-and-pin configurations persist in small-scale landscape operations where transport width constraints remain minimal.
Leading the category by volume: Hydraulic Folding Plows. Growing fastest: Electric Folding Plows.
End User:
Customer procurement authority concentrates differentially across public-sector RFP processes, fleet-scale contractor operations, and dispersed agricultural purchasing.
- Municipalities:Public-sector buyers in the Upper Midwest command specification authority through centralized fleet modernization programs. NHTSA highway transport width regulations and EPA idle-reduction protocols tighten RFP language, with contract penalties for excessive warm-up periods accelerating electric actuation migration.
- Contractors:Multi-route snow removal operations spanning Minnesota, Iowa, and Wisconsin prioritize rapid-deploy folding systems that protect blade edges during interstate transit. Telematics-enabled service contracts are displacing transactional parts sales across this segment.
- Agriculture:Farm operators in Montana and North Dakota select mechanical and hydraulic units for field-to-road versatility, with synthetic hydraulic fluid cost premiums eroding operating margins in sub-zero conditions.
- Landscape Professionals:Compact-class electric folding systems address fuel economy pressures where tow vehicle operating costs dominate total ownership calculations.
Highest specification authority: Municipalities. Fastest service-contract penetration: Contractors.
Size:
Chassis GVW ratings and transport width regulations segment demand across compact landscape applications through extra-large municipal highway units.
- Large:Heavy-duty moldboards on 26,000+ lb GVW chassis dominate municipal highway clearing contracts. Steel plate specifications expose fabricators to commodity price volatility on fixed-price public contracts.
- Compact:Sub-10,000 lb configurations align with battery-electric municipal vehicle pilot programs where reduced parasitic load preserves battery range.
- Medium:Mid-size contractor fleets in Michigan balance route coverage with fuel economy optimization.
- Extra Large:Specialized airport and highway maintenance applications requiring custom mounting bracket engineering for legacy chassis integration.
Dominant procurement volume: Large. Steepest expansion trajectory: Compact.
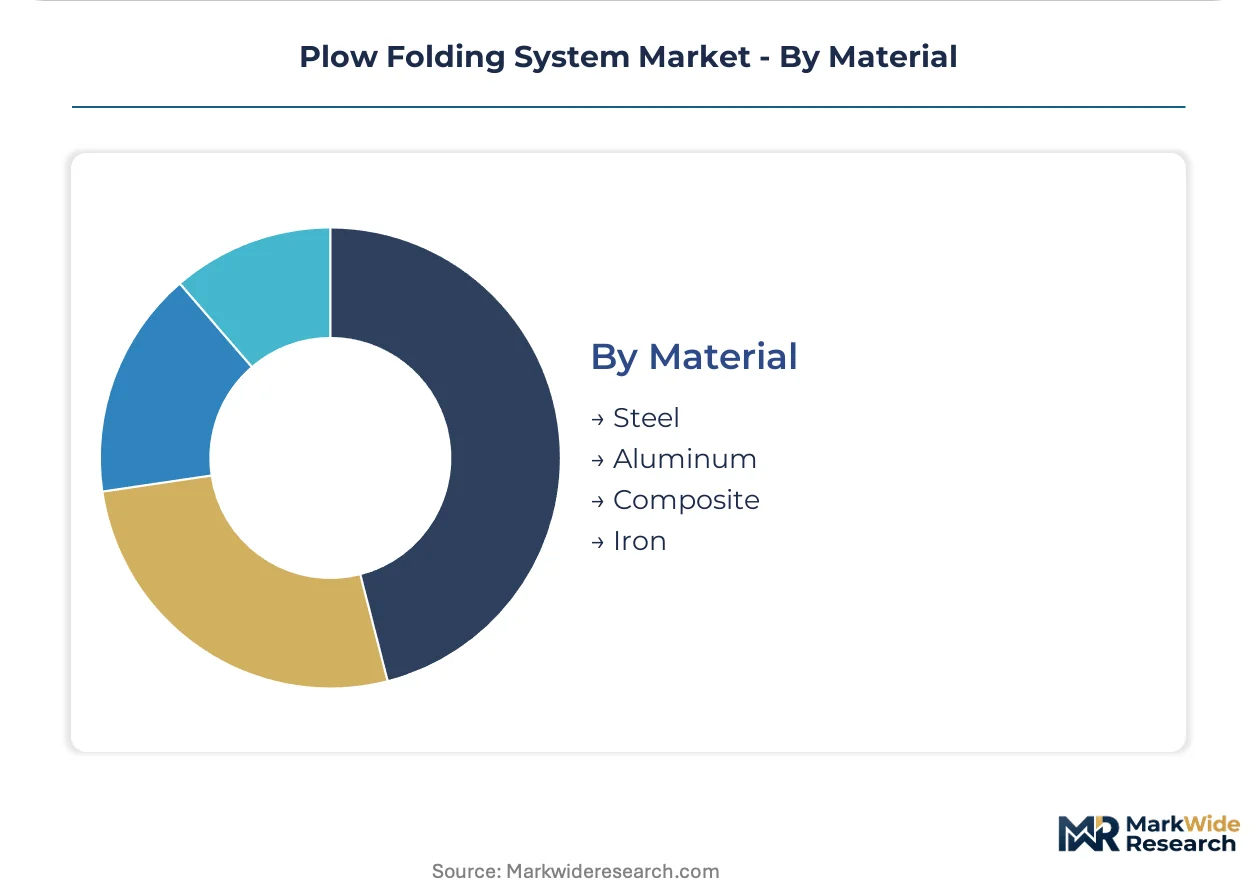
Material:
Structural performance requirements and fuel economy regulations bifurcate material selection between heavy-duty durability and lightweight operational efficiency.
- Steel:Structural-grade plate specifications remain baseline for heavy-duty contractor applications where moldboard impact resistance outweighs weight penalties. AWS D1.1 certification requirements constrain qualified supplier pools.
- Aluminum:Alloy variants command premium positioning in fuel-economy-conscious landscape fleets where tow vehicle operating costs drive total ownership calculations.
- Composite:Emerging material option for specialized corrosion-resistant applications in coastal municipal operations.
- Iron:Cast components persist in mechanical linkage assemblies for cost-sensitive agricultural segments.
Highest volume share: Steel. Gaining share fastest: Aluminum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-St. Paul metropolitan corridor anchors North American demand for plow folding systems, with municipal fleet operators managing over 1,200 route-miles of snow removal infrastructure. Regional procurement patterns concentrate in the Upper Midwest where freeze-thaw cycles exceed 120 days annually.
United States
Upper Midwest municipalities in Minnesota and Wisconsin are synchronizing fleet replacements with EPA Tier 4 Final diesel compliance deadlines. NHTSA highway transport width regulations constrain blade configurations during interstate transit between route zones. The Twin Cities metro area hosts the densest concentration of snow removal contractors deploying rapid-deploy folding architectures.
Canada
Provincial transportation departments in Ontario and Quebec are expanding winter maintenance contracts across the Trans-Canada Highway corridor. Transport Canada vehicle width standards align with US NHTSA specifications, enabling cross-border equipment interoperability. Montreal-based fleet operators are piloting telematics-enabled service contracts for predictive maintenance of hydraulic actuation systems.
Germany
Municipal authorities in Bavaria and North Rhine-Westphalia are modernizing Autobahn maintenance fleets with ISO 9001-certified folding systems. KBA vehicle certification requirements ensure compliance with EU transport dimension regulations. Stuttgart industrial clusters supply precision hydraulic components to OEMs serving Alpine snow removal operations.
Sweden
Transport agencies in Stockholm and Gothenburg are electrifying municipal vehicle fleets under national carbon neutrality mandates. Swedish Transport Administration regulations specify maximum transport widths for winter equipment convoys. Scania's Södertälje manufacturing corridor influences Nordic specification standards for heavy-duty folding architectures.
Japan
Prefectural governments in Hokkaido and Tohoku regions face sustained snowfall volumes exceeding 8 meters annually. METI industrial standards govern structural welding qualifications for public works equipment. Nagoya manufacturing clusters produce compact electric actuation systems for sub-10,000 lb GVW municipal vehicles.
Plow Folding System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the plow folding system market, with fabrication capabilities determining tier boundaries. The vendor base separates between integrated hydraulic system manufacturers and specialized folding mechanism designers. Three strategic archetypes dominate: regional dealer-network operators, upstream-integrated component producers, and compact electric specialists. Incumbents defend position through captive service revenue expansion while challengers penetrate via aluminum lightweighting and telematics integration.
Among North American fabricators, Eastey exemplifies the regional dealer-density archetype, while ABM Equipment anchors the upstream-integrated tier through in-house hydraulic actuator production. MFT Automation occupies the compact electric specialist position. These three company structures represent the dominant competitive vectors reshaping procurement relationships with municipal and contractor fleets.
| Leading Market Players |
|---|
| Eastey |
| Planar Motor Inc. |
| ABM Equipment |
| Horizon |
| Capmatic Ltd. |
| MFT Automation |
| McGinn-Wilkins Automation Inc. |
| Advantage Puck Technologies, LLC |
| Durst Organization |
| Others |
Value Network & Pricing Analysis
Electric actuation migration across municipal fleets is compressing hydraulic component demand while simultaneously fragmenting supplier pricing power between legacy fluid-power fabricators and emerging linear-motion specialists. This technology bifurcation concentrates procurement leverage with OEMs capable of dual-platform sourcing, while tier-two fabricators face margin erosion on single-technology dependencies.
Pricing Analysis
Fold-cycle uptime guarantees anchor value-based pricing for municipal service contracts, with ISO 9001-certified suppliers commanding 15-25% premiums over uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and telemetry bundling, with landscape contractors exhibiting highest price sensitivity due to fuel-cost-driven total ownership calculations. Cost compression in hydraulic tiers is intensifying because synthetic fluid cold-weather formulations inflate operating budgets.
Supply Chain Analysis
Single-source vulnerability sits with precision hydraulic valve suppliers concentrated in Germany and Japan, where KBA and METI certification requirements constrain qualified fabricator pools. Structural-grade steel plate and 48V electric actuators draw from US Midwest and Nagoya manufacturing clusters respectively. Tariff exposure on alloy aluminum from Canadian smelters threatens lightweighting cost advantages. Distribution runs through regional dealer networks anchored in Minneapolis-St. Paul and Montreal corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 9001 quality management mandates construct a compliance moat that filters out uncertified fabricators, consolidating specification authority with qualified suppliers capable of documenting traceable welding and actuator performance.
For Market Incumbents: Deepen captive service revenue through telemetry-enabled predictive maintenance contracts that offset equipment margin compression. Prioritize backward integration into hydraulic actuator production to secure supply continuity against valve-supplier concentration in Germany and Japan. Defend municipal fleet relationships by certifying dual electric-hydraulic platform capabilities before electrification mandates accelerate.
For New Entrants and Emerging Players: Launch via direct-to-fleet telematics subscriptions targeting mid-sized landscape contractors in Michigan and Wisconsin where fuel-economy pressures dominate procurement criteria. Penetrate the compact electric segment serving battery-electric municipal vehicle pilots, where incumbent hydraulic legacy creates specification gaps. Position aluminum lightweighting architectures as premium alternatives to steel moldboards in fuel-cost-sensitive contractor fleets.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial equipment OEMs seeking municipal snow removal exposure. Long-term viability hinges on dual-platform engineering capabilities spanning hydraulic torque density and electric parasitic-load optimization. Monitor Wisconsin DOT electrification pilot outcomes as the critical signal for procurement-cycle inflection toward 48V architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Enabled Service Contract Launch | Recurring revenue streams from Minnesota municipal fleets offset transactional equipment margin compression. |
| Dual Hydraulic-Electric Platform Development | Engineering investment preserves specification authority across both legacy diesel and emerging battery-electric chassis procurement. |
| Aluminum Alloy Lightweighting Transition | Fuel-economy certification appeals to landscape contractors in Iowa where tow vehicle operating costs dominate ownership calculations. |
| ISO 9001 Certification Investment | Quality management documentation unlocks public-sector RFP eligibility filtering out uncertified competitor fabricators. |
| Regional Dealer Network Expansion | Density in Upper Midwest corridors captures aftermarket service concentration away from independent repair facilities. |
Research Methodology
Independent corroboration across municipal fleet directors, hydraulic systems engineers, and aftermarket service managers underwrites the qualitative findings presented in this study. Primary fieldwork with snow removal contractors in Minnesota, Wisconsin, and Iowa combined with secondary validation from EPA emissions filings, NHTSA transport regulation dockets, and ISO certification registries. Bottom-up triangulation across procurement volume estimates and top-down validation against municipal budget disclosures anchored the market sizing framework.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product type, end-user procurement authority, chassis size classification, and material specification tier. CAGRs were derived from regression analysis of replacement-cycle timing tied to EPA Tier 4 Final compliance deadlines and fleet electrification pilot expansions. Forecast inputs incorporated synthetic hydraulic fluid cost elasticity and battery-electric vehicle adoption curves from Wisconsin DOT program data.
Electrification timeline acceleration, steel commodity price volatility, and federal EV infrastructure funding disbursement delays are the dominant revision risks to the outlook presented. Deviation in municipal fleet electrification mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Fly Trap Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Green Beans Harvester Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Intelligent Milking Robot Market
Agricultural Equipment
Australia Bird Feeder Market