
 Pre-Harvest Equipment Market | 2026-2036
Pre-Harvest Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Harvest Equipment Market Analytics
Precision agriculture technology integration is reshaping pre-harvest equipment design, embedding IoT sensors and variable-rate control systems directly into tillage and seeding platforms. Deere & Company leverages its proprietary command-center software to anchor premium positioning in autonomous tractor guidance. CNH Industrial N.V. competes through Raven-acquired autonomy stacks applied across Case IH and New Holland tillage lines. AGCO Corporation differentiates via Fuse-connected platforms that extend real-time field data analytics to smaller fleet operators.
Pre-harvest equipment encompasses soil preparation, seeding, and cultivation machinery engineered to operating widths exceeding 18 meters, draft forces above 200 kW, and seed placement accuracy within 2 centimeters for uniform germination. The equipment serves commercial crop production by optimizing seedbed conditions, residue management, and planting depth prior to crop emergence. Plows and harrows occupy mature replacement cycles where margin pools concentrate in wear-part aftermarket services. Autonomous technology represents the fastest-expanding segment as labor scarcity and 24-hour operational windows drive fleet investment. Electric and hydraulic architectures split demand by farm scale, with electric systems penetrating greenhouse and horticulture applications where duty cycles permit battery sizing.
The EPA enforces Tier 4 Final and emerging Stage V-aligned emissions standards for off-road diesel engines above 56 kW, compelling engine redesigns and after-treatment integration that elevate equipment cost structures. The EU F-Gas Regulation and CE machinery directives restrict refrigerants and mandate safety interlocks, shaping product compliance roadmaps for European-bound equipment. Brazil's national agricultural regulator enforces CONAMA resolutions on soil conservation that tie mechanized tillage practices to environmental licensing. Stakeholders must monitor regulatory convergence between emissions, autonomous operation liability frameworks, and soil-health mandates as these forces jointly determine product development prioritization and market access requirements.
Market Dynamics
Autonomous tillage architectures are compressing operator labor requirements while expanding 24-hour operational windows across large-scale row-crop operations. Tier 4 Final and Stage V emissions compliance is forcing engine redesigns that elevate capital costs and reshape supplier relationships.
Growth Catalysts
- Precision seeding mandates:Brazil's CONAMA resolutions tie environmental licensing to mechanized soil conservation practices, accelerating replacement of conventional tillage with GPS-guided systems.
- Labor scarcity in commercial farming:Vineyard and orchard operators in Germany face seasonal worker shortages that drive investment in autonomous cultivation platforms.
- EU F-Gas Regulation:Refrigerant restrictions on climate-controlled seed storage equipment are creating upgrade cycles for compliant pre-harvest machinery.
Market Restraints
- Diesel after-treatment complexity:EPA Tier 4 Final compliance requires exhaust fluid systems and particulate filters that add maintenance burden and total cost of ownership.
- Steel and rare earth input volatility:Hydraulic actuator and electric motor supply chains concentrate in Chinese processing facilities, exposing equipment manufacturers to price swings.
- Autonomous liability frameworks:Absence of standardized fault allocation for unmanned tillage operations creates insurance and legal barriers to fleet deployment.
Strategic Opportunities
- Horticulture electrification:Greenhouse operators in the Netherlands seek battery-powered cultivation equipment where duty cycles permit compact battery sizing.
- Variable-rate control convergence:Integration of IoT soil sensors with seeding platforms enables prescription tillage services that command premium positioning.
- Rural equipment-as-a-service:Dealer networks in the United States are piloting subscription models that bundle precision tillage hardware with telemetry and maintenance.
Industry Challenges
- Mechatronics skill scarcity:Field service technicians require combined expertise in hydraulic systems, CAN bus diagnostics, and GPS guidance calibration that training pipelines struggle to produce.
- Legacy fleet integration friction:Retrofitting autonomous guidance to existing tillage lines demands mechanical interface standardization that OEMs have not harmonized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Harvest Equipment Market |
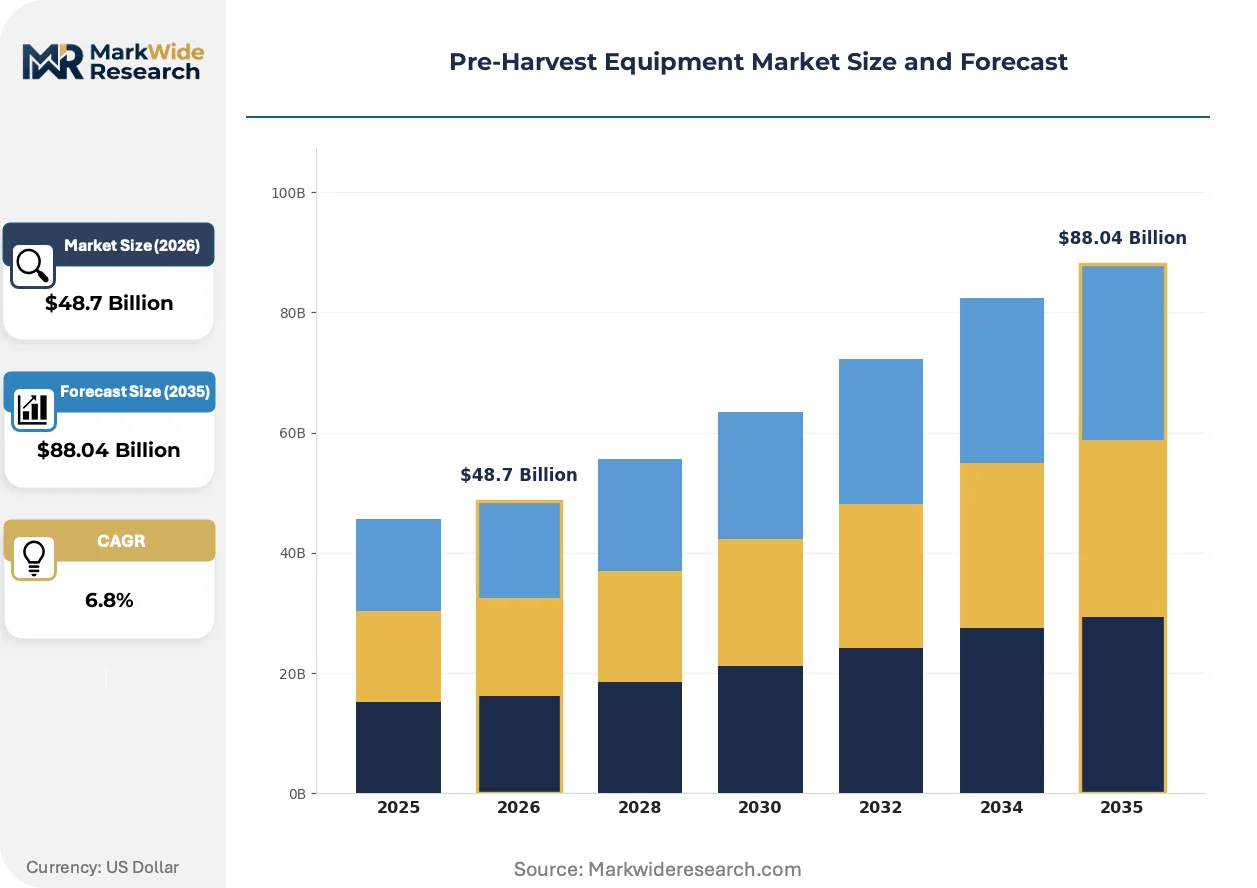
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plows, Harrows, Seeders, Mulchers End Use Industry: Agriculture, Horticulture, Viticulture, Organic Farming Technology: Manual, Hydraulic, Electric, Autonomous Application: Crops, Orchards, Vineyards, Greenhouses |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, Kubota Corporation, Mahindra & Mahindra Ltd, CLAAS KGaA mbH, Bucher Industries AG, Valmont Industries, Iseki & Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Harvest Equipment Market Evolving Landscape
Pre-harvest equipment design is pivoting from mechanical reliability toward software-defined functionality, with connectivity and automation becoming primary purchase criteria alongside draft force and operating width.
Electrified powertrains are migrating from hydraulic architectures in compact cultivation equipment for specialty crop applications. Greenhouse and vineyard operators in Germany and the Netherlands are piloting battery-electric tillage platforms where intermittent duty cycles accommodate overnight charging infrastructure. This shift is compressing the addressable market for conventional diesel engines below 75 kW while expanding service revenue pools around battery management systems.
The EU F-Gas Regulation and emerging Stage V alignment are forcing refrigerant transitions in climate-controlled seed treatment equipment. Manufacturers must redesign thermal management systems and validate alternative working fluids, elevating R&D intensity for European-bound product lines. Seed handling and conditioning equipment faces the steepest compliance timeline, with 2027 implementation deadlines already shaping procurement decisions.
Equipment financing is fragmenting from captive lender dominance toward agtech-focused venture debt and revenue-based instruments. Midwestern US row-crop operators are accessing autonomous tillage hardware through yield-linked repayment structures that align capital outflows with harvest cash flows. This restructuring is visible most acutely in Iowa and Illinois, where dealer groups have partnered with fintech platforms to bypass traditional credit scoring for precision agriculture investments.
Pre-Harvest Equipment Market Segmentation
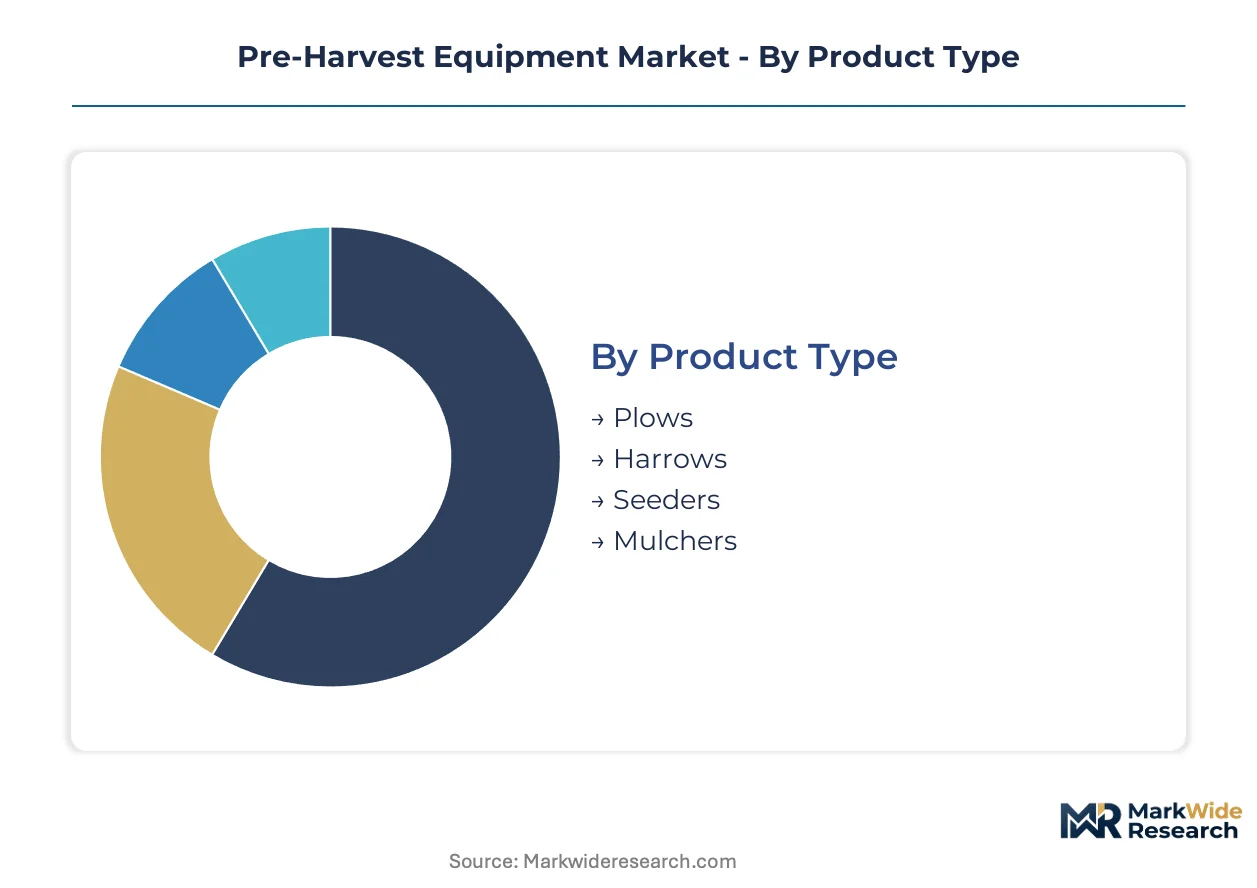
Pre-harvest equipment segmentation reveals divergent replacement cycles across product architectures. Cycle timing varies from annual wear-part turnover in tillage implements to decade-long investment horizons for autonomous platforms.
Product Type:
Replacement velocity splits sharply between mechanical wear components and precision seeding systems.
- Plows:Moldboard and disc configurations dominate soil inversion tasks with operating widths spanning 3 to 12 meters. Brazilian commercial soybean operations drive replacement demand as CONAMA soil conservation mandates accelerate turnover of conventional tillage fleets.
- Seeders:Precision air-seed and planter systems achieve placement accuracy within 2 centimeters through GPS-guided variable-rate control. Large-scale row-crop operators in Iowa and Illinois prioritize these platforms for 24-hour planting windows compressed by weather volatility.
- Harrowers:Secondary tillage implements prepare seedbeds through disc, tine, or chain configurations. German vineyard operators specify compact folding harrows for inter-row cultivation on slopes exceeding 15 degrees.
- Mulchers:Residue management equipment processes cover crops and post-harvest biomass ahead of primary tillage. Organic farming operations in California's Central Valley specify flail and rotary mulchers for certified no-till transitions.
Plows anchor the volume base while seeders gain share at the steepest rate.
End Use Industry:
Capital intensity scales inversely with operational scale across end-use categories.
- Agriculture:Commercial row-crop and grain operations deploy the widest equipment with draft requirements above 200 kW. Midwestern US corn-soy rotations concentrate demand for 18-meter operating widths and telemetry-integrated platforms.
- Horticulture:Protected cultivation and open-field vegetable production favors compact electric equipment with intermittent duty cycles. Netherlands greenhouse clusters specify battery-powered cultivation tools where overnight charging infrastructure exists.
- Viticulture:Vineyard preparation demands narrow-track tractors and specialized inter-row equipment for steep terrain. German Rheingau and Pfalz regions drive specification of autonomous guidance for labor-scarce seasonal operations.
- Organic Farming:Certification requirements mandate mechanical weed control and residue incorporation without synthetic inputs. Brazilian organic soybean operators combine mulchers with minimum-till seeders to satisfy audit protocols.
Agriculture commands the installed base while viticulture climbs fastest on autonomous conversion.
Technology:
Architecture selection tracks farm scale, labor availability, and duty cycle predictability.
- Manual:Human-operated mechanical systems persist in smallholder and specialty applications where capital constraints outweigh labor costs. Subsistence operators in developing regions maintain these configurations for tillage tasks below 5 hectares.
- Hydraulic:Fluid-power actuation dominates mid-scale commercial equipment for force-intensive soil engagement. Hydraulic seeding platforms remain standard in Brazilian Cerrado operations where dust and vibration challenge electronic alternatives.
- Electric:Battery-electric powertrains penetrate greenhouse and orchard applications with predictable duty cycles and charging access. Netherlands horticulture clusters pilot compact electric tillage for zero-emission zone compliance.
- Autonomous:GPS-guided unmanned platforms eliminate operator presence through RTK correction and obstacle detection. Large-scale US row-crop operators deploy these systems for continuous 24-hour planting windows during compressed spring seasons.
Hydraulic systems anchor current revenue while autonomous configurations expand most quickly.
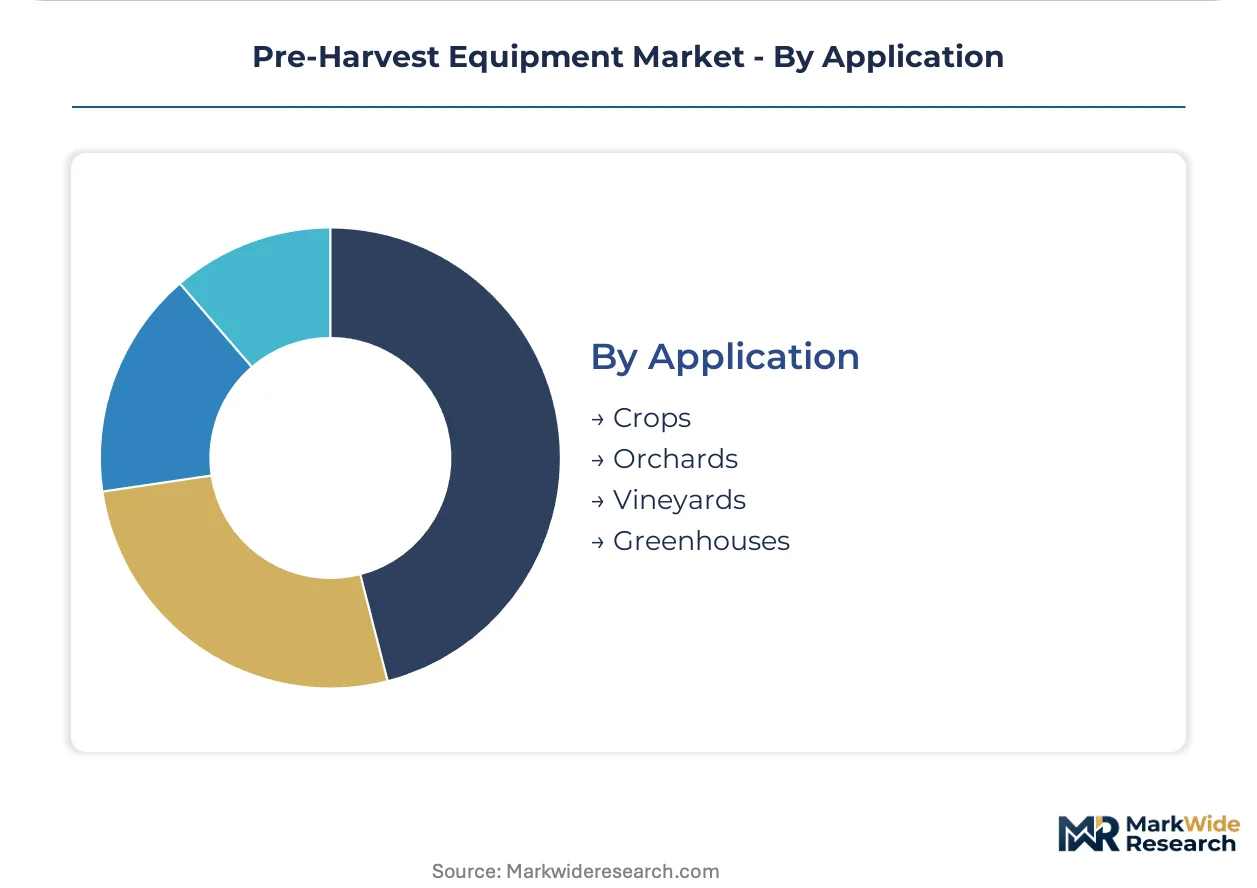
Application:
Surface geometry and crop architecture dictate equipment specification and attachment compatibility.
- Crops:Broad-acre grain and oilseed production utilizes the widest implements with highest draft requirements. Iowa and Illinois operators specify 24-row planters and 15-meter cultivators for corn-soy rotations.
- Orchards:Tree-fruit and nut production demands narrow-profile equipment with protected crop clearance. California almond growers deploy specialized mowers and mulchers for inter-row vegetation management.
- Vineyards:Trellised grape production requires lateral offset capabilities and slope stability for angled terrain. German steep-slope vineyards specify tracked carriers and gyro-stabilized implements.
- Greenhouses:Protected cultivation environments favor low-emission electric equipment with compact turning radii. Netherlands glasshouse operators specify battery-powered bed preparation tools for year-round vegetable production.
Crop applications dominate unit volume while greenhouse segments show the steepest technology upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows reveal sharp asymmetries between manufacturing concentration and agricultural deployment zones. Brazil and the United States import precision tillage systems while Germany and the Netherlands export specialized cultivation platforms to horticulture clusters worldwide.
United States
Midwestern corn-soy operators in Iowa and Illinois drive replacement demand for 18-meter tillage implements and GPS-guided seeders. The EPA enforces Tier 4 Final emissions standards for diesel engines above 56 kW, compelling after-treatment integration that elevates capital costs. Dealer networks in the Corn Belt pilot subscription-based equipment-as-a-service models that bundle telemetry with hardware.
Brazil
Commercial soybean and sugarcane operations in Mato Grosso and Goiás scale procurement of precision tillage systems to meet CONAMA soil conservation licensing requirements. The national environmental regulator ties mechanized cultivation practices to environmental permits, accelerating fleet turnover. Cerrado region operators specify hydraulic seeding platforms that withstand dust and vibration extremes.
Germany
Viticulture operations in Rheingau and Pfalz face acute seasonal labor scarcity that drives autonomous cultivation platform investment. The EU F-Gas Regulation restricts refrigerants in climate-controlled seed storage equipment, forcing thermal system redesigns for European-bound machinery. Baden-Württemberg manufacturers anchor precision agriculture R&D clusters serving steep-slope vineyard applications.
Netherlands
Greenhouse operators in Westland and North Brabant specify battery-electric tillage equipment where overnight charging infrastructure supports intermittent duty cycles. National zero-emission zone mandates in urban peripheries compress demand for compact electric cultivation tools. Wageningen agtech clusters pilot variable-rate control convergence between IoT soil sensors and seeding platforms.
India
Smallholder and emerging commercial operators in Punjab and Haryana maintain manual and hydraulic tillage configurations where capital constraints outweigh labor costs. The central government's PLI scheme for farm mechanization subsidizes precision equipment procurement for cooperatives above 10 hectares. Northwestern grain belts concentrate demand for mid-scale seeders compatible with 75-100 kW tractors.
Pre-Harvest Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around integrated technology stacks that bundle hardware with proprietary software platforms. Three structural tiers have emerged: full-line OEMs with captive autonomy stacks, component specialists supplying guidance systems across brands, and regional fabricators serving price-sensitive replacement markets. Dominant competitive moves include strategic acquisitions of autonomy software providers and vertical integration into sensor manufacturing to secure supply chain control.
Among North American and European full-line manufacturers, Deere & Company, CNH Industrial N.V., and AGCO Corporation exemplify the integrated technology archetype. Deere represents the proprietary software-platform approach through its command-center ecosystem. CNH Industrial occupies a position leveraging acquired autonomy capabilities across multiple equipment brands. AGCO exemplifies the connected-platform strategy targeting smaller fleet operators with telemetry-integrated offerings. These three anchors demonstrate how competitive positioning now hinges on software-defined functionality rather than mechanical specifications alone.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra Ltd |
| CLAAS KGaA mbH |
| Bucher Industries AG |
| Valmont Industries |
| Iseki & Co. Ltd |
| Others |
Value Network & Pricing Analysis
Steel and rare earth input volatility concentrated in Chinese processing facilities compresses margin pools across equipment tiers while forcing tiered pricing stratification between hydraulic and electric architectures. Tier 4 Final after-treatment integration elevates baseline production costs, widening spreads between premium autonomous platforms and economy manual configurations as OEMs pass compliance burdens differentially.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on autonomy-stack sophistication and EPA Tier 4 Final certification grade, with subscription-telemetry bundles commanding premiums over transactional hardware sales. Cost compression in economy tillage lines is intensifying because Brazilian and Indian price-sensitive operators resist after-treatment cost pass-through, while large-scale US row-crop buyers show lowest price sensitivity for 24-hour autonomous capability.
Supply Chain Analysis
Extended payment terms from component suppliers to tier-1 actuator manufacturers now stretch 90-120 days, straining working capital across European and North American assembly operations. Hydraulic valve and electric motor production draws from China, Germany, and Japan, with rare earth magnet processing tethered to Chinese refining capacity. Single-source vulnerability in RTK-GPS module supply creates exposure to semiconductor allocation volatility. Distribution runs through captive dealer networks in mature markets and cooperative procurement channels in Brazil and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-harvest equipment is crossing into platform economics as Deere's command-center ecosystem and CNH's Raven-acquired stacks create interoperability moats that relegate mechanical specifications to secondary purchase criteria. Autonomous guidance API standardization represents the decisive interoperability shift determining which OEMs capture telemetry revenue pools.
For Market Incumbents: Build software-platform moats through proprietary telemetry APIs that lock aftermarket service revenue and prevent dealer disintermediation. Defensive moves center on backward integration into sensor manufacturing to secure RTK-GPS and LiDAR supply against allocation volatility, plus exclusive distribution agreements with Brazilian cooperatives facing CONAMA compliance deadlines. Threat substitution from agtech pure-plays offering retrofit autonomy kits demands preemptive certification investment in ISO 26262 functional safety for unmanned operations. For New Entrants and Emerging Players: Pursue battery-electric cultivation niches in Netherlands greenhouse clusters and German vineyard slopes where duty cycles and zero-emission mandates create penetrable white space. Target horticulture automation as the least defended segment, bypassing entrenched hydraulic incumbents in broad-acre grain markets. Go-to-market angle emphasizes equipment-as-a-service subscriptions with yield-linked repayment structures that bypass traditional credit barriers for mid-scale operators. For Investors and Strategic Acquirers: Stage V emissions alignment and EU F-Gas refrigerant deadlines reshape the acquisition landscape toward thermal management and electric powertrain specialists. Long-term viability favors targets with captive software stacks over mechanical component fabricators facing margin compression. Signal to watch is OEM consolidation of autonomy software providers, indicating platform economics tipping point and valuation multiple expansion for connected-fleet enablers.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomy Stack Acquisition | CNH's Raven integration demonstrates software-defined differentiation commanding premium positioning in GPS-guided tillage. |
| Battery Supply Agreement | Netherlands greenhouse electrification hinges on Korean cell manufacturer partnerships for compact cultivation platforms. |
| Platform Integration | Deere's command-center ecosystem locks telemetry revenue and prevents dealer channel disintermediation by third-party service providers. |
| Geographic Manufacturing Footprint | Baden-Württemberg precision agriculture clusters anchor European R&D for steep-slope vineyard automation. |
| Long-term Supply Agreement | Brazilian Cerrado operators secure hydraulic seeding platform allocation through cooperative procurement contracts with tier-1 distributors. |
Research Methodology
A spread of perspectives from OEM product strategy directors, dealer network operations heads, aftermarket service technicians, and large-scale farm operators converged on the working assumptions driving segmentation and growth estimates. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement actions, EU F-Gas implementation timelines, ANVISA resolution texts, and customs trade data on equipment import flows. Bottom-up equipment unit economics triangulated against top-down agricultural GDP and mechanization intensity metrics.
Demand-supply balance modeling across the analysis window weighted replacement cycle timing, regulatory compliance deadlines, and labor scarcity indices by geography. Segmentation dimensions included powertrain architecture, autonomy level, farm scale tier, and crop application type. CAGRs derived from logistic diffusion curves for autonomous adoption and S-curve penetration rates for electric powertrains. Industry-specific inputs incorporated CONAMA licensing velocity, Tier 4 Final enforcement intensity, and greenhouse zero-emission zone implementation pace.
The forecast holds incumbent behavior within observed patterns; aggressive platform exclusivity moves by Deere or CNH would shift outcomes through dealer network lock-in effects. Macroeconomic deviation in agricultural commodity prices, regulatory acceleration in autonomous liability frameworks, or breakthrough battery energy density gains would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Powder Feed Center Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Agricultural Trailer Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Asia-Pacific Agricultural Tires Market
Agricultural Equipment
Green Beans Harvester Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Intelligent Milking Robot Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Pond Aeration System Market