

Cordless Handheld Cultivator Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Handheld Cultivator Market Insights
Chinese lithium-ion cell manufacturing is rebalancing global battery economics for outdoor power equipment. RYOBI leverages its captive 18V platform ecosystem to lock in repeat battery purchases across tool categories. Greenworks Tools anchors its position through dedicated brushless motor R&D and aggressive North American retail placement. Black+Decker competes on brand recognition and mass-merchandiser shelf density, sustaining volume despite narrower margins.
A cordless handheld cultivator is a battery-operated soil-tilling implement, typically weighing under 10 pounds and delivering 200-300 RPM through rotating tines or cultivator claws, designed for loosening compacted earth in beds and borders without fuel exhaust or cord constraints. Its primary commercial purpose is enabling precision soil preparation in confined residential and light commercial spaces where full-size tillers prove excessive. The lithium-ion battery segment commands the widest margin pool as energy density improvements extend runtime per charge, while the brushless motor category posts the fastest structural growth due to reduced heat generation and extended service intervals. Among applications, small-scale farming and horticulture attract premium pricing as these buyers prioritize tool portability over absolute power output.
The EPA regulates exhaust emissions from gasoline-powered garden equipment under Phase 3 small spark-ignition engine standards, indirectly elevating cordless alternatives in retail assortments. OSHA guidelines for vibration exposure and hand-arm safety also influence ergonomic design priorities among manufacturers seeking commercial landscaper contracts. The EU F-Gas Regulation and CE marking requirements for battery systems create parallel compliance thresholds for brands exporting into European markets. Stakeholders must monitor how solid-state battery prototyping timelines reshape runtime expectations and whether agricultural suppliers expand their cordless inventory beyond established homeowner channels.
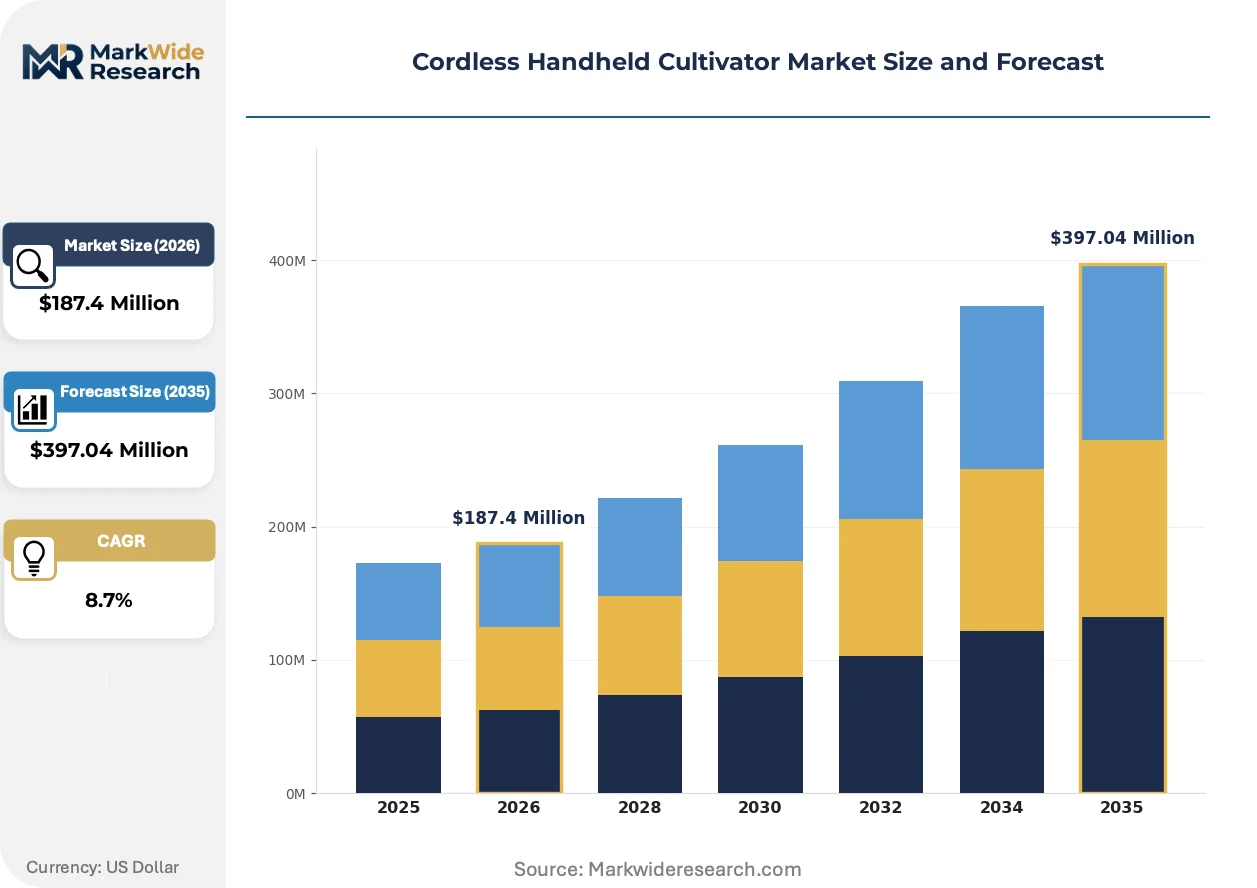
Market Dynamics
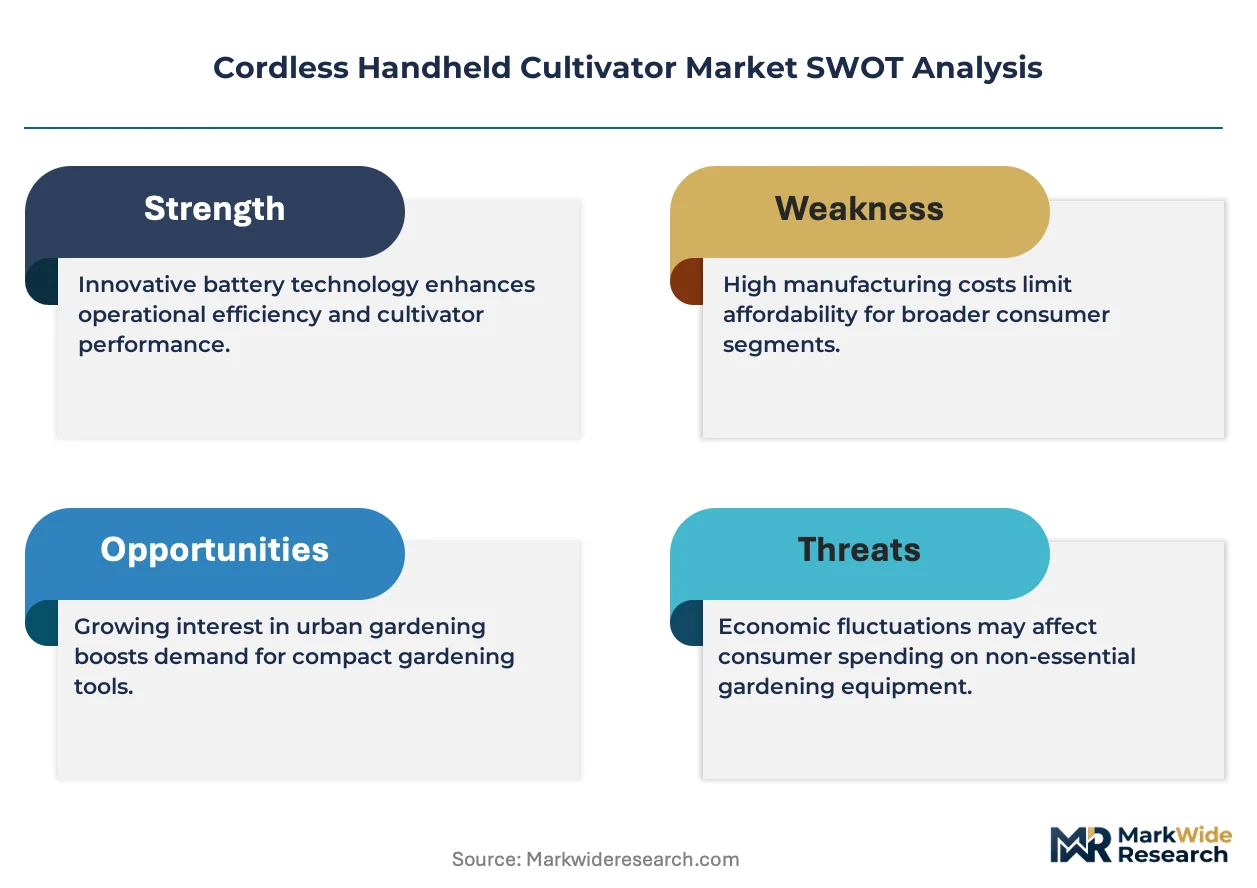
The cordless handheld cultivator market pivots on the collision between tightening small-engine emissions mandates and the maturation of lithium-ion cell economics, which together compress the total cost of ownership gap versus gasoline alternatives.
Growth Catalysts
- EPA Phase 3 Standards:Exhaust limits on spark-ignition engines force retailers to reallocate shelf space toward battery-powered alternatives, accelerating cordless cultivator visibility in home improvement channels.
- Urban Gardening Surge:Residential participation in compact-space horticulture creates demand for sub-10-pound soil preparation tools that full-size tillers cannot address.
- Lithium-Ion Energy Density Gains:Chinese cell manufacturing scale has reduced battery pack costs, extending runtime per charge and eliminating the primary performance objection among suburban homeowners.
Market Restraints
- Cobalt and Lithium Price Volatility:Raw material swings in cathode chemistry inputs compress margin stability for manufacturers lacking long-term offtake agreements.
- Charging Infrastructure Gaps:Rural and ex-urban properties without reliable grid access or outdoor-rated outlets limit cordless adoption among small-scale farming operators.
- Runtime Anxiety in Clay Soils:Dense, unbroken earth in Midwestern and Southern US states drains batteries faster than manufacturer ratings, creating performance skepticism.
Strategic Opportunities
- Solid-State Battery Prototyping:Next-generation cell architectures promise 40% energy density improvements, enabling single-battery operation across full property cultivation sessions.
- Direct-to-Consumer Subscription Models:Battery-platform ecosystems can lock in repeat hardware purchases through annual tine replacement and seasonal tune-up programs shipped to homeowner addresses.
- EU F-Gas Regulation Alignment:Export-oriented manufacturers certifying to European battery safety and recycling standards gain preferential placement in garden center chains across Germany, France, and the Netherlands.
Industry Challenges
- Brushless Motor Technician Scarcity:Repair networks lack trained personnel for Hall sensor diagnostics and stator rewinding, forcing premature unit replacement.
- Multi-Jurisdiction Certification Timelines:UL, CE, and CSA testing sequences for battery management systems add 8-14 months to product launch windows.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Handheld Cultivator Market Trends and Innovations
Product development in cordless cultivators centers on runtime extension and user fatigue reduction, with motor and battery architectures converging toward platform standardization that rewards ecosystem loyalty.
Brushless DC motor technology is expanding into mid-tier price bands previously occupied by brushed alternatives. Residential buyers in suburban US markets now expect 20+ minute runtime in compacted soil without thermal cutoff. This motor transition compresses maintenance revenue for service centers while extending manufacturer warranty exposure.
OSHA hand-arm vibration exposure guidelines are reshaping ergonomic design priorities among brands seeking commercial landscaping contracts. Compliance testing now occurs at the prototype stage rather than post-production. Landscapers in California and New York states increasingly specify sub-2.5 m/s² vibration ratings as bid prerequisites.
Platform stickiness now governs replacement cycles as homeowners accumulate batteries and chargers within single-voltage ecosystems. The hardware margin shifts toward consumable tines and seasonal attachments. This behavioral lock-in concentrates volume with early platform entrants in the US Southeast and Pacific Northwest metro corridors.
Cordless Handheld Cultivator Market Segmentation
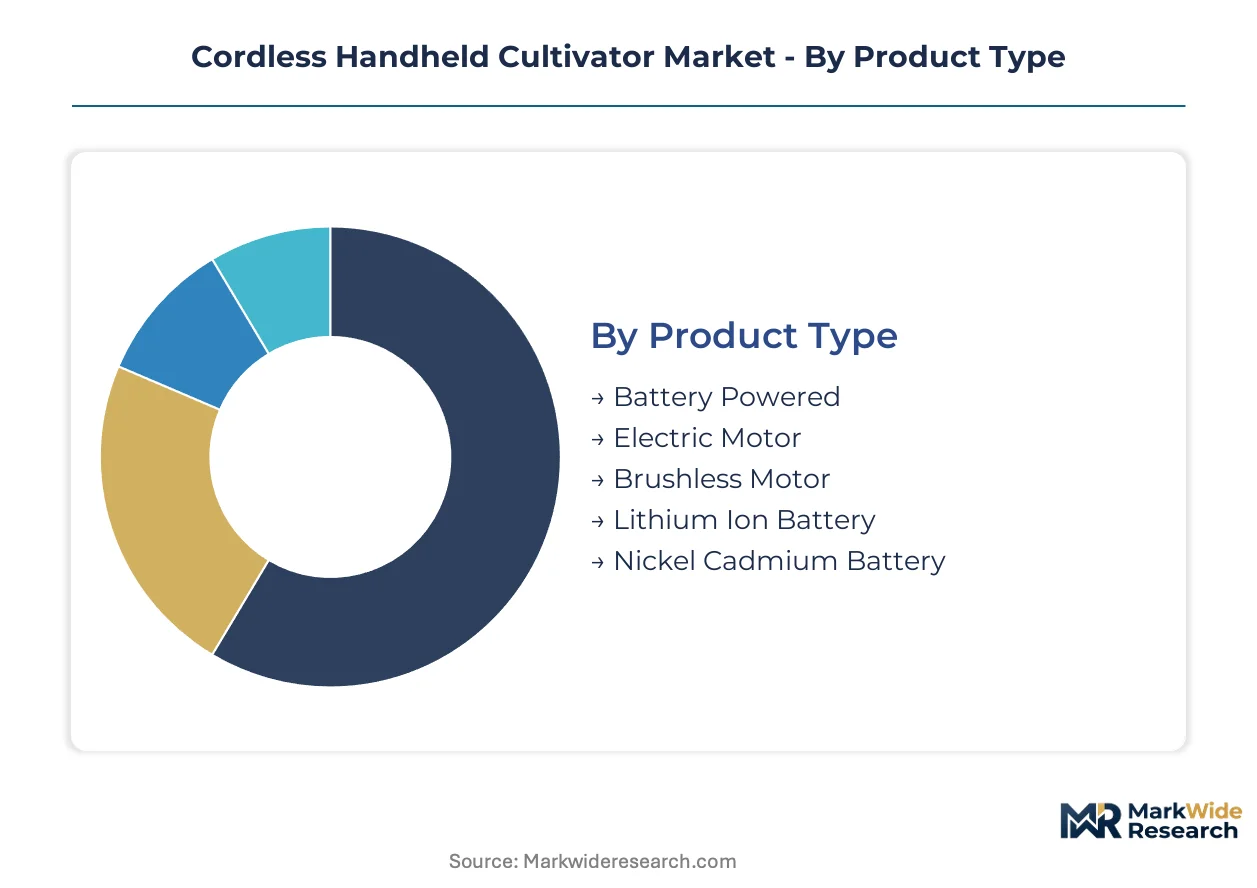
Segmentation in the cordless handheld cultivator market reveals how battery platform economics and user workflow intensity reshape purchasing patterns. Manufacturers optimize SKUs around runtime expectations, soil compaction levels, and ecosystem lock-in potential rather than simple price tiers.
Product Type:
Supply concentration in battery cell manufacturing tilts competitive advantage toward brands with captive lithium-ion platforms and vertical motor integration.
- Lithium Ion Battery:Cells with nickel-manganese-cobalt or lithium iron phosphate cathodes deliver 18V to 40V nominal outputs with energy densities above 250 Wh/kg. Residential buyers in US suburban markets prioritize these packs for their runtime-to-weight ratios in raised bed cultivation. Chinese cell manufacturing scale has compressed pack costs, extending adoption into mid-tier price bands previously served by nickel-cadmium alternatives.
- Brushless Motor:Electronically commutated designs eliminate brush friction losses and thermal degradation, sustaining 200-300 RPM under load without maintenance intervals. Commercial landscapers in California and New York specify sub-2.5 m/s² vibration ratings that brushless architectures achieve through precision rotor balancing. These motors displace brushed alternatives in premium cordless cultivators as runtime expectations harden around 20+ minutes in compacted clay.
- Battery Powered:Cordless architectures dependent on interchangeable pack systems dominate retail assortments at home improvement chains.
- Electric Motor:Brushed DC designs persist in entry-level SKUs where absolute cost minimization outweighs longevity concerns.
- Nickel Cadmium Battery:Legacy chemistry retains niche presence in rental fleet equipment and price-sensitive replacement markets.
Today's leader: Lithium Ion Battery. Tomorrow's challenger: Brushless Motor.
Application:
Cost tier stratification separates precision soil preparation in confined spaces from broad-acre cultivation where full-size tillers retain economic advantage.
- Horticulture:Container gardening and greenhouse bed preparation demand sub-10-pound implements with narrow tine spans for root-zone precision. Professional growers in the Netherlands and Pacific Northwest US metro corridors specify cordless units for their zero-emission operation in enclosed propagation environments. Premium pricing persists here as buyers prioritize tool portability over absolute power output.
- Small-Scale Farming:Market garden operations on 1-5 acre plots require runtime endurance across multiple bed rows without recharge delays. Operators in Midwestern US states with dense clay soils drive demand for higher-voltage platforms that resist thermal cutoff under sustained load. Charging infrastructure gaps in rural ex-urban properties constrain penetration despite EPA Phase 3 standards accelerating cordless visibility.
- Gardening:Residential bed and border maintenance constitutes the volume base for 18V platform ecosystems.
- Landscaping:Commercial service contracts specify vibration compliance and rapid battery swap protocols for crew efficiency.
- Lawn Care:Aeration and overseeding prep applications favor lighter-duty units with interchangeable cultivation heads.
Horticulture commands premium positioning. Small-Scale Farming climbs fastest as agricultural suppliers expand cordless inventory.
End User:
Customer type determines battery platform stickiness and replacement cycle velocity, with ecosystem accumulation behavior concentrating volume among early 18V adopters.
- Homeowners:Suburban property holders with accumulated tool batteries within single-voltage ecosystems drive replacement purchases toward compatible cultivator SKUs. Platform loyalty in US Southeast and Pacific Northwest metro corridors locks in repeat hardware buys across seasonal categories. Direct-to-consumer subscription models for tine replacement and tune-up programs target this segment's convenience preferences.
- Commercial Landscapers:Crew-based operations in California and New York states mandate OSHA-compliant vibration exposure limits and rapid field-swappable batteries. Bid prerequisites increasingly specify cordless equipment for municipal and corporate sustainability requirements. These buyers prioritize runtime consistency over absolute acquisition cost.
- Hobbyists:Enthusiast growers with multiple battery platforms comparison-shop across voltage ecosystems for optimal runtime value.
- Gardening Services:Sole proprietors balance equipment portability against vehicle cargo constraints for mobile operations.
- Nurseries:Wholesale propagation facilities specify zero-emission tools for enclosed greenhouse compliance.
Homeowners anchor current volume. Commercial Landscapers reshape specification standards fastest.
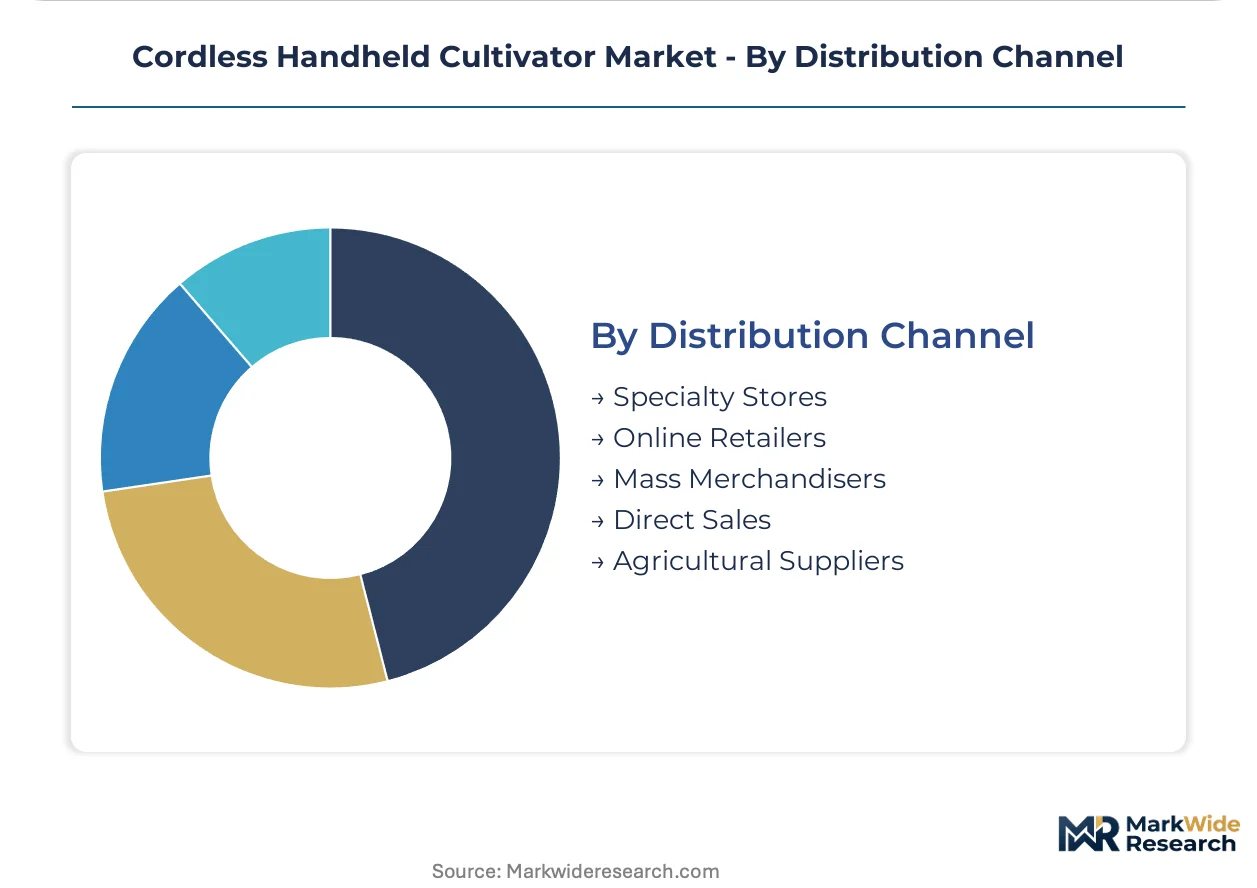
Distribution Channel:
Geography of retail placement determines brand visibility, with suburban corridor density and direct-to-consumer penetration reshaping channel economics.
- Mass Merchandisers:Home improvement chains with US Southeast and Midwest suburban proximity dominate volume through seasonal endcap placement and private-label battery platform ecosystems. RYOBI and Greenworks Tools anchor positions here through dedicated retail space and cross-category charger compatibility. Shelf density sustains brand recognition despite compressed margins versus specialty channels.
- Online Retailers:Direct-to-consumer penetration enables subscription attachment for consumable tines and extended warranty programs. Black+Decker competes through search visibility and mass-merchandiser digital integration. Platform stickiness translates into replacement cycle capture as homeowners accumulate purchase history data.
- Specialty Stores:Independent garden centers provide hands-on demonstration and horticultural expertise for premium-tier sales.
- Agricultural Suppliers:Rural-focused dealers with small-scale farming relationships represent expansion opportunity beyond homeowner channels.
- Direct Sales:Manufacturer-owned channels capture full margin on replacement batteries and proprietary attachments.
Mass Merchandisers defend volume leadership. Online Retailers gain share fastest through subscription model attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage favors jurisdictions with lower battery manufacturing compliance costs, while demand concentrates where suburban lawn culture and emissions enforcement intersect most aggressively.
United States
Suburban homeowners in the Southeast and Pacific Northwest metro corridors drive replacement cycles through accumulated 18V platform ecosystems. EPA Phase 3 small spark-ignition engine standards force retailers to reallocate shelf space toward cordless alternatives. Home improvement chains in Atlanta and Seattle suburbs anchor volume through seasonal endcap placement and cross-category charger compatibility programs.
Germany
Professional horticulture operations in the Netherlands-adjacent Lower Saxony region specify zero-emission tools for enclosed greenhouse compliance. EU F-Gas Regulation and CE marking requirements for battery systems create preferential placement thresholds in garden center chains across Bavaria and North Rhine-Westphalia. Stuttgart-area engineering clusters concentrate brushless motor R&D for premium-tier export models.
China
Zhejiang and Jiangsu province manufacturing basins supply lithium-ion cells that compress global battery pack economics for outdoor power equipment. MIIT dual carbon goals accelerate domestic phase-out of small gasoline engines in urban gardening applications. Shenzhen and Ningbo industrial zones host vertically integrated motor-controller-battery assembly operations serving North American and European OEM contracts.
United Kingdom
London commuter-belt allotment gardening sustains demand for sub-10-pound soil preparation tools in confined spaces. HSE vibration exposure guidelines align with OSHA-equivalent ergonomic design priorities for commercial landscaping contracts. Midlands distribution hubs facilitate direct-to-consumer fulfillment across the Southeast and Northwest England metro corridors.
Japan
Compact-space horticulture in the Kanto and Kansai regions favors precision soil preparation implements over full-size tillers. METI energy efficiency standards for battery-powered equipment elevate runtime expectations in metropolitan Tokyo and Osaka gardening communities. Nagoya-area precision manufacturing clusters supply compact brushless motor assemblies for premium cordless cultivator SKUs.
Cordless Handheld Cultivator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue platform ecosystem lock-in through battery compatibility architectures. The vendor base stratifies between mass-merchandiser volume anchors and specialty-channel premium specialists. Three archetypes dominate: ecosystem-integrated power tool conglomerates, dedicated outdoor equipment pure-plays, and private-label contract manufacturers serving retail captive brands. Competitive moves center on retail shelf space negotiations and battery platform exclusivity agreements rather than direct price confrontation.
Within the ecosystem-integrated tier, RYOBI and Black+Decker represent archetypal platform stickiness strategies, while Greenworks Tools occupies a position as a dedicated outdoor power specialist. These three anchors exemplify how battery interchangeability across tool categories concentrates replacement purchase decisions within single-voltage ecosystems, shifting hardware margin toward consumable attachments and seasonal tune-up programs.
| Leading Market Players |
|---|
| RYOBI |
| Greenworks Tools |
| Black+Decker |
| Earthwise Tools |
| Sun Joe |
| Fiskars |
| Yard Butler |
| Garden Weasel |
| Corona |
| Others |
Pricing and Supply Chain Analysis
Brushless motor manufacturing automation simultaneously compresses per-unit production costs and concentrates supplier capability among Zhejiang and Jiangsu province industrial clusters. This technological transition reshapes margin allocation between battery pack assemblers and finished goods OEMs.
Pricing Analysis
Retailer markup layers in home improvement chains absorb margin compression from lithium-ion cell cost declines. Pricing stratifies across premium, standard, and economy tiers based on voltage platform and vibration certification grade. Cost compression in entry-level brushed motor SKUs intensifies because Chinese cell manufacturing scale eliminates nickel-cadmium alternatives. Homeowners with accumulated 18V platform ecosystems exhibit lowest price sensitivity; rural small-scale farming operators without charging infrastructure show highest.
Supply Chain Analysis
Returns and refurbishment flows for battery packs remain underdeveloped, constraining circular economics despite EU battery recycling mandates. Manufacturing concentrates in China, South Korea, and Japan for lithium-ion cells; Mexico and Vietnam host final assembly for North American tariff optimization. Raw material dependencies center on cobalt cathodes, lithium carbonate, and rare-earth magnet feedstocks. Single-source vulnerability in Chinese graphite anode supply creates structural risk. Distribution runs through mass merchandiser DC networks and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Phase 3 small spark-ignition engine standards compound regulatory pressure that accelerates cordless cultivator shelf space allocation against gasoline alternatives.
For Market Incumbents: Anticipate cobalt price volatility by securing long-term offtake agreements with Chinese cell manufacturers or accelerating lithium iron phosphate chemistry transitions. Defend against private-label entrants by deepening exclusive retail space agreements with home improvement chains and expanding proprietary battery platform SKUs into seasonal attachment categories. For New Entrants and Emerging Players: Agricultural suppliers with underserved rural small-scale farming relationships represent the most penetrable channel partner type for bypassing mass merchandiser incumbent dominance. Target Midwestern US states with dense clay soils where runtime anxiety creates demand for higher-voltage platforms. Pursue go-to-market angles through demonstration programs at county extension offices and farmers market equipment showcases. For Investors and Strategic Acquirers: Valuations sit cheapest among brushless motor controller specialists with captive stator winding capabilities but limited brand recognition. Long-term viability favors acquisition targets with UL/CE certification infrastructure and established OEM supply relationships. Monitor solid-state battery prototyping announcements from Chinese manufacturers as inflection indicators for next-generation runtime expectations.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Expansion | RYOBI's 18V charger compatibility locks homeowners into repeat hardware purchases across seasonal categories. |
| Brushless Motor Vertical Integration | Greenworks Tools' in-house rotor balancing capability achieves OSHA sub-2.5 m/s² vibration ratings for commercial landscaper contracts. |
| Direct-to-Consumer Subscription Launch | Annual tine replacement and seasonal tune-up programs shipped to homeowner addresses capture consumable attachment margin. |
| EU F-Gas Regulation Certification | CE marking for battery management systems enables preferential placement in German and Dutch garden center chains. |
| Solid-State Battery R&D Partnership | Next-generation cell architectures promising 40% energy density improvements would eliminate runtime anxiety in dense clay soils. |
Research Methodology
Multiple input streams — regulatory filing analysis, retail audit data, and supply chain documentation — were reconciled through structured primary interviews with outdoor power equipment product managers, lithium-ion cell procurement leads at OEMs, home improvement chain category buyers, commercial landscaping fleet operators, and agricultural supply cooperative managers. Secondary validation drew from EPA Phase 3 compliance documentation, UL certification databases, Chinese customs export records, and SEC 10-K disclosures from listed power tool conglomerates. Bottom-up SKU-level volume estimates and top-down market sizing triangulated to produce convergent figures.
Data-stream reconciliation across the projection horizon employed segmentation modeling by battery chemistry, motor architecture, end-user type, and distribution channel. CAGRs derived from historical volume trajectories adjusted for regulatory enforcement timelines and platform ecosystem saturation curves. Industry-specific forecast inputs included lithium-ion cell cost decline curves and EPA small engine phase-out implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state battery commercialization timelines and cobalt supply chain disruptions. Practitioners should monitor Chinese MIIT dual carbon policy announcements and Midwestern US charging infrastructure buildout rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.