
 Farm Equipment Market | 2026-2036
Farm Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Farm Equipment Market Intelligence
Multi-source component procurement is recalibrating how original equipment manufacturers manage supply risk and cost exposure across volatile steel and semiconductor markets. John Deere leverages its captive foundry network to buffer against casting supply shocks. AGCO Corporation anchors its European assembly footprint through regional forging partnerships. Kubota Corporation competes on compact tractor specialization, sustaining margin pools in sub-40 horsepower segments where Asian manufacturing scale dominates.
Farm equipment comprises self-propelled and trailed machinery engineered for soil preparation, crop establishment, protection, and harvest operations, with power outputs ranging from 15 to 600+ horsepower and hydraulic flow rates determining implement compatibility. Tractors remain the revenue backbone across all geographies, while autonomous systems represent the fastest-expanding technology category as labor scarcity intensifies. Precision sensors and variable rate technology concentrate margin capture among large-scale growers who amortize hardware costs across thousand-acre footprints, whereas small-scale farmers gravitate toward equipment rental firms for seasonal access without capital commitment.
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine after-treatment integration, adding hardware cost and maintenance complexity that shapes buyer preferences toward newer compliant fleets. The USDA and EU Common Agricultural Policy subsidize precision technology adoption, redirecting capital flows toward GPS guidance and telematics-enabled machines. Stakeholders must weigh regulatory compliance timelines against residual value risk in legacy diesel inventories as alternative powertrains advance from prototype to field validation.
Market Dynamics
Precision agriculture hardware and EPA Tier 4 Final after-treatment systems are forcing simultaneous capital deployment, compressing replacement cycles and redrawing competitive boundaries between engine-integrated and retrofit-capable suppliers.
Growth Catalysts
- USDA Conservation Reserve Program incentives:Subsidized precision technology adoption accelerates GPS-guided planting and variable-rate fertilization across Corn Belt operations.
- Brazilian soybean belt mechanization:Large-scale growers in Mato Grosso and Goiás states expand tractor fleets to capture export window timing advantages.
- Telematics-enabled predictive maintenance:Sensor-embedded hydraulic systems reduce unplanned downtime during critical planting and harvest windows.
Market Restraints
- Steel and semiconductor input volatility:Foundry-grade steel pricing swings and chip allocation constraints disrupt transmission controller availability.
- EU Stage V after-treatment cost burden:Diesel particulate filter and selective catalytic reduction hardware adds maintenance complexity that deters smallholder fleet renewal.
- Used equipment import substitution:Refurbished Tier 3 tractors from North American auctions displace new machine sales in price-sensitive African and Southeast Asian markets.
Strategic Opportunities
- Ukraine post-conflict reconstruction:Black Sea region grain corridor recovery will demand rapid fleet replacement for winter wheat and sunflower production.
- Autonomous implement retrofit kits:Aftermarket autonomy packages for existing tractor platforms open technology access without full machine replacement.
- Equipment-as-a-service rental networks:Seasonal access models reduce capital barriers for mid-scale operations in India's Punjab and Haryana states.
Industry Challenges
- Mechatronics technician scarcity:Hydraulic-electronic system integration expertise lags behind fleet complexity, extending repair timelines.
- Legacy fleet telematics incompatibility:Older CAN bus architectures resist seamless integration with cloud-based fleet management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farm Equipment Market |
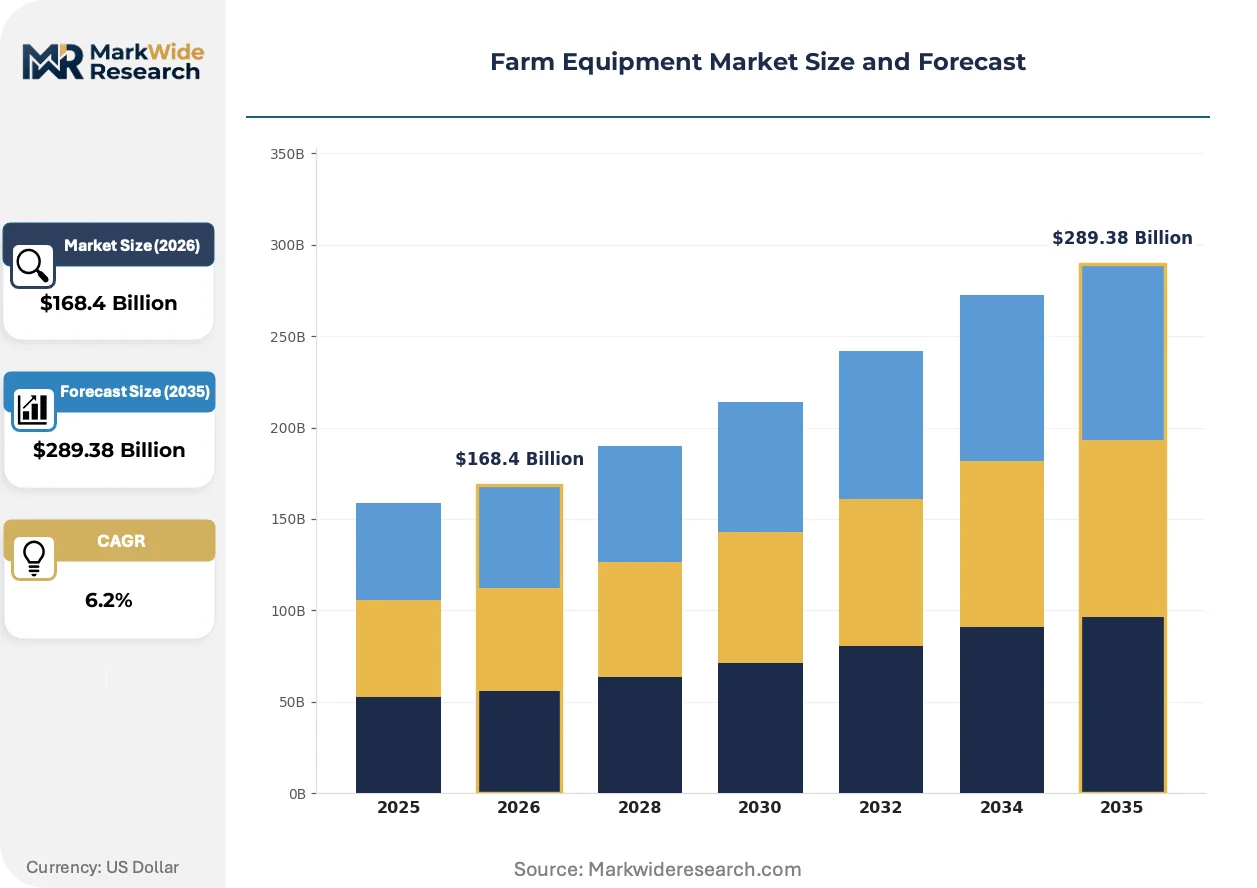
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $289.38 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Plows, Seeders, Sprayers, Balers Technology: GPS Guidance, Autonomous Systems, Precision Sensors, Telematics, Drone Integration, Variable Rate Technology Application: Tillage, Planting, Crop Protection, Harvesting, Fodder Collection, Soil Management End User: Small Scale Farmers, Agricultural Cooperatives, Large Scale Growers, Contract Operators, Agro-Service Providers, Equipment Rental Firms |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Claas, SDF Group, Mahindra & Mahindra, Caterpillar, Yanmar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farm Equipment Market Strategic Shifts & Innovations
Autonomous navigation, emissions after-treatment integration, and service model restructuring are simultaneously altering equipment specifications, ownership economics, and dealer revenue composition.
Computer vision-based weed recognition is converging with precision sprayer actuation to enable spot-application chemistry reduction. Large-scale row-crop operators in Iowa and Illinois deploy these systems across thousand-acre footprints to compress herbicide input costs. The technology is converging with existing planter and sprayer platforms rather than requiring dedicated autonomous machines.
EPA Tier 4 Final and EU Stage V emissions frameworks mandate diesel exhaust fluid infrastructure and ash-service protocols that reshape dealer service department staffing. Engine manufacturers redesign combustion chambers and turbocharger maps to minimize active regeneration frequency. North American row-crop segments absorb these costs through financing term extension, while European mixed-farming operations accelerate tractor downsizing to avoid after-treatment complexity.
Rental and cooperative ownership models displace individual machine possession among mid-scale operators facing compressed commodity margins. Equipment pools in Germany's Schleswig-Holstein and France's Picardy regions coordinate seasonal access through digital scheduling platforms. Dealer networks respond by unbundling service contracts from hardware sales, capturing recurring revenue through uptime guarantees rather than transaction margins.
Farm Equipment Market Segmentation
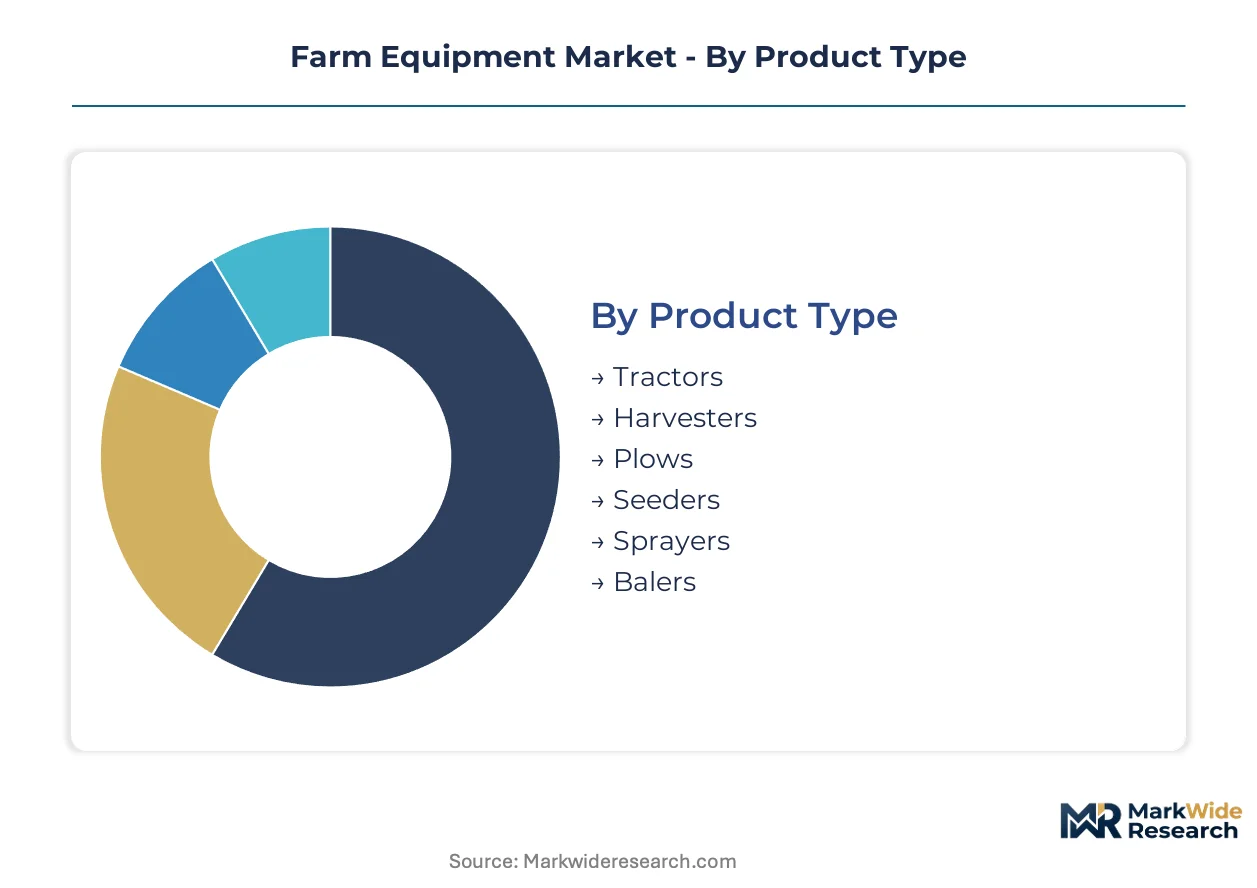
Segmentation in farm equipment reveals divergent technology absorption rates across operator scale and cropping intensity. Equipment specifications, precision technology integration, and ownership models fragment along capital availability and acreage thresholds.
Product Type:
Standalone machinery dominates capital allocation, while implement-tractor integration depth varies by cropping system and regional mechanization maturity.
- Tractors:Power units ranging from 15 to 600+ horsepower with hydraulic flow rates determining implement compatibility. Demand concentrates in Brazilian Mato Grosso soybean operations and Iowa Corn Belt row-crop farms where fleet replacement cycles compress under emissions compliance pressure.
- Harvesters:Self-propelled combines and forage harvesters with threshing and cleaning systems matched to grain moisture windows. Large-scale growers in Goiás and Illinois prioritize capacity-per-hour metrics to capture narrow harvest windows before weather degradation.
- Plows:Moldboard and disc configurations for primary tillage, typically trailed rather than integrated. European mixed-farming operations in Picardy downsize tractor-implement pairings to avoid Stage V after-treatment complexity.
- Seeders:Precision planting units with seed metering and depth control. GPS-guided systems penetrate North American operations faster than Black Sea region adoption curves.
- Sprayers:Boom and air-assisted configurations for crop protection chemistry application. Computer vision integration enables spot-application reduction in Iowa and Illinois thousand-acre footprints.
- Balers:Round and square configurations for fodder collection and densification. Seasonal rental demand peaks in Germany's Schleswig-Holstein equipment pools.
Tractors lead volumes today; autonomous retrofit kits for existing tractor platforms are gaining share fastest.
Technology:
Cost tier stratification separates embedded factory installations from aftermarket retrofits, with subscription models emerging for data-layer services.
- GPS Guidance:Satellite-based steering correction enabling sub-inch pass-to-pass accuracy. USDA Conservation Reserve Program subsidies accelerate adoption across Corn Belt planting operations.
- Autonomous Systems:Computer vision and LiDAR-based navigation eliminating operator presence. Field validation concentrates in North American row-crop segments where labor scarcity intensifies.
- Precision Sensors:Soil moisture, nutrient, and yield monitoring arrays. Variable-rate fertilization deployment dominates large-scale operations with thousand-acre amortization bases.
- Telematics:Cellular and satellite-connected fleet monitoring for predictive maintenance. Dealer service departments in Germany restructure staffing around uptime guarantee contracts.
- Drone Integration:Aerial scouting and spot-spray actuation for crop health mapping. Regulatory fragmentation across national aviation authorities constrains cross-border equipment standardization.
- Variable Rate Technology:Prescription-driven input modulation for seed, fertilizer, and chemistry. Margin capture concentrates among operations with documented yield response histories.
GPS guidance leads volumes today; autonomous systems are climbing the fastest.
Application:
Customer type determines application intensity, with contract operators and cooperatives driving higher equipment utilization hours than owner-operators.
- Tillage:Soil preparation for seedbed establishment through mechanical disturbance. Reduced-tillage adoption in Brazil preserves moisture for soybean establishment windows.
- Planting:Crop establishment with timing precision critical for yield potential. GPS-guided systems in Iowa compress planting windows against weather variability.
- Crop Protection:Herbicide, fungicide, and insecticide application for yield preservation. Spot-application technology reduces chemistry volumes in Illinois corn and soybean rotations.
- Harvesting:Grain and forage removal with moisture and loss-rate optimization. Black Sea region fleet replacement demand will intensify with Ukraine corridor recovery.
- Fodder Collection:Hay and silage preservation for livestock feed security. Seasonal rental networks in India's Punjab reduce capital barriers for mid-scale operators.
- Soil Management:Erosion control and organic matter maintenance through cover crop and amendment integration. EU Common Agricultural Policy redirects capital toward conservation-oriented equipment specifications.
Harvesting leads volumes today; soil management is expanding most quickly.
End User:
Ownership economics fragment across capital commitment horizons, with rental and cooperative models displacing individual possession among margin-compressed mid-scale operators.
- Small Scale Farmers:Sub-hundred-acre operations relying on used equipment or seasonal rental. Refurbished Tier 3 tractors from North American auctions displace new machine sales in price-sensitive markets.
- Agricultural Cooperatives:Pooled machinery ownership with scheduled access protocols. Equipment pools in France's Picardy coordinate seasonal deployment through digital scheduling platforms.
- Large Scale Growers:Thousand-acre-plus operations with in-house maintenance infrastructure. Precision technology amortization across large footprints justifies hardware costs that deter smaller operators.
- Contract Operators:Fee-for-service providers with high annual machine-hour utilization. Telematics-enabled uptime guarantees reshape dealer revenue composition toward recurring service contracts.
- Agro-Service Providers:Specialized input application and scouting services. Drone integration and variable-rate technology differentiate service tiers in competitive bidding environments.
- Equipment Rental Firms:Seasonal access models without capital commitment or residual value risk. India's Haryana state sees network expansion for planting and harvest window equipment access.
Large scale growers lead volumes today; equipment rental firms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Moline-Rock Island industrial corridor anchors North American farm equipment manufacturing, with precision technology development clustering around Iowa and Illinois research partnerships. Brazil's Mato Grosso soybean belt and Germany's Lower Saxony machinery districts represent parallel demand centers where emissions compliance and labor scarcity reshape procurement patterns.
United States
EPA Tier 4 Final compliance compresses replacement cycles across Corn Belt row-crop operations, with GPS-guided planting systems penetrating Iowa and Illinois thousand-acre footprints. USDA Conservation Reserve Program subsidies redirect capital toward telematics-enabled machines. The Moline-Rock Island corridor concentrates tractor assembly and precision technology R&D.
Brazil
Mato Grosso and Goiás state growers expand mechanized acreage to capture export window timing advantages for soybean shipments. The national agricultural ministry supports precision agriculture adoption through subsidized credit lines for large-scale operators. São Paulo state's industrial belt hosts forging and transmission component suppliers serving domestic assembly plants.
Germany
EU Stage V after-treatment requirements accelerate tractor downsizing among mixed-farming operations in Schleswig-Holstein and Lower Saxony. The national KBA enforces emissions certification timelines that reshape dealer service department staffing around diesel exhaust fluid infrastructure. Equipment pools in Picardy coordinate seasonal access through digital scheduling platforms.
India
Punjab and Haryana state operators confront capital barriers through expanding equipment rental networks for planting and harvest windows. The central government's PLI scheme for farm mechanization redirects investment toward domestic manufacturing scale. Gujarat's industrial corridor concentrates compact tractor component forging for sub-40 horsepower segments.
China
Yangtze River Delta and Shandong Peninsula provinces drive domestic combine harvester demand for wheat and rice production consolidation. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate electric tractor prototype validation. Zhengzhou's machinery district anchors hydraulic system component sourcing for regional assembly networks.
Farm Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue autonomous retrofit and equipment-as-a-service models. The vendor base stratifies across integrated engine-tractor manufacturers, specialized implement fabricators, and precision technology licensors. Three archetypes dominate: captive foundry operators buffering casting supply shocks, regional forging partnership anchors, and compact tractor specialists leveraging Asian manufacturing scale. Competitive moves concentrate on emissions after-treatment integration partnerships and telematics platform unbundling from hardware sales.
Among North American integrated manufacturers, John Deere exemplifies the captive supply archetype through foundry network control. AGCO Corporation occupies a position within the European regional partnership tier. Kubota Corporation anchors the compact specialization segment where sub-40 horsepower manufacturing scale concentrates margin capture.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Claas |
| SDF Group |
| Mahindra & Mahindra |
| Caterpillar |
| Yanmar |
| Others |
Cost & Logistics Intelligence
Foundry-grade steel and semiconductor allocation constraints cascade through equipment manufacturing tiers, compressing margins on transmission controllers while EPA Tier 4 Final compliance costs concentrate in premium tractor segments purchased by Iowa and Illinois row-crop operators.
Pricing Analysis
Input-cost pass-through from volatile steel and chip markets feeds into a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on emissions certification grade and after-sales service bundling. Pricing pressure stems from Tier 4 Final after-treatment hardware additions that deter smallholder fleet renewal. Small-scale farmers in price-sensitive markets exhibit highest price sensitivity, while large-scale Brazilian soybean operators absorb premiums through financing term extension.
Supply Chain Analysis
Regional distribution centers in the Moline-Rock Island corridor, São Paulo state's industrial belt, and Germany's Lower Saxony machinery districts anchor hub-and-spoke patterns for finished equipment delivery. Geographic supply concentration centers on the United States, Brazil, and Germany for final assembly, with China and India feeding component forging for compact tractor segments. Raw material dependencies draw from foundry-grade steel, hydraulic system castings, and transmission controller semiconductors. Single-source vulnerability in chip allocation disrupts production scheduling. Distribution runs through dealer networks with service department integration for emissions compliance maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
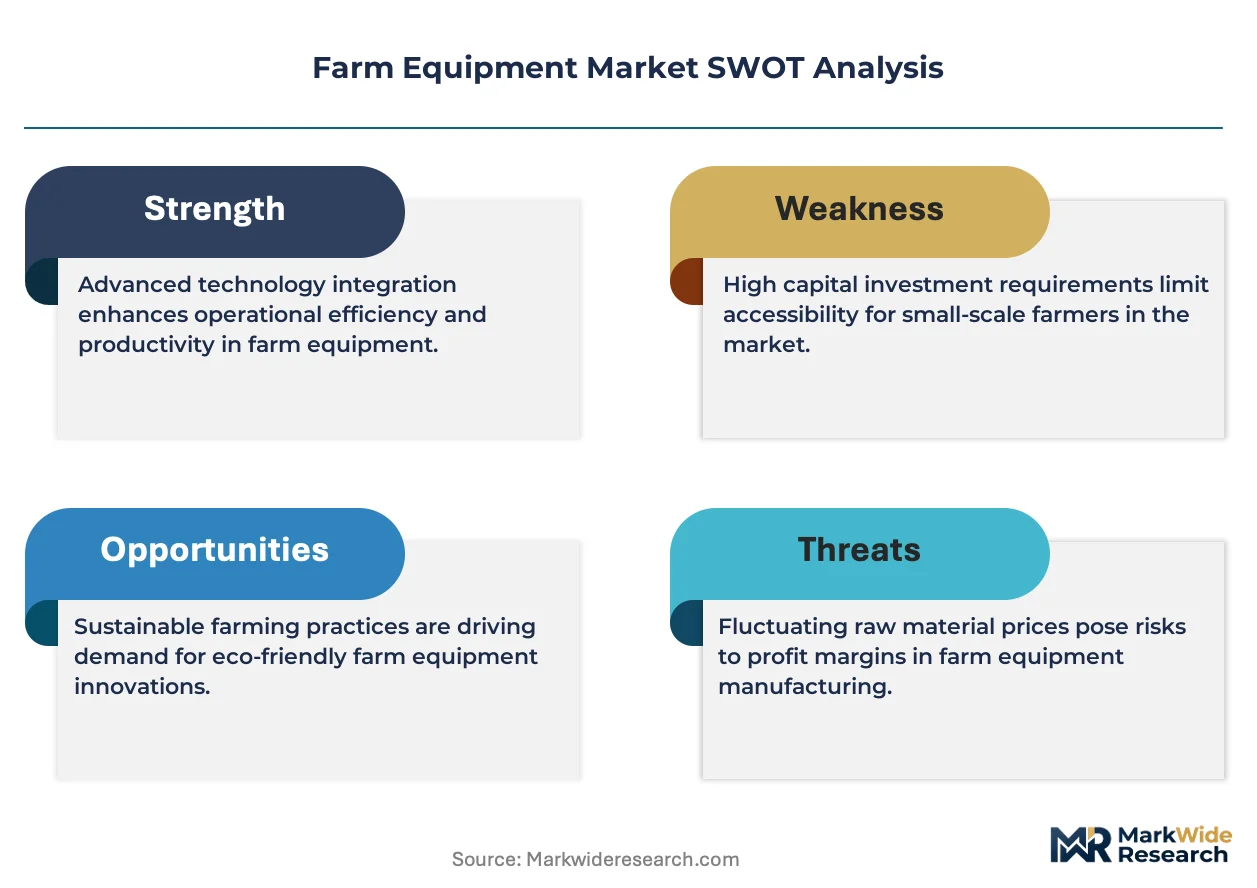
This market operates as a regulatory compounder where EPA Tier 4 Final and EU Stage V emissions milestones force simultaneous capital deployment across precision agriculture hardware and after-treatment systems.
For Market Incumbents: To counter autonomous retrofit kit entrants, John Deere and AGCO Corporation should deepen captive foundry control over casting supply and extend telematics platform unbundling into recurring uptime guarantee contracts that lock dealer service revenue. For New Entrants and Emerging Players: EU Stage V in Germany opens a window for downsized tractor autonomy packages that bypass after-treatment complexity, with equipment-as-a-service rental networks in India's Punjab representing the most penetrable white-space for seasonal access models without capital commitment. For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics technician scarcity extends repair timelines and legacy fleet telematics incompatibility fragments customer data platforms. Long-term viability favors targets with precision sensor integration capabilities and regional forging partnerships rather than pure assembly operations. The signal to watch is Ukraine Black Sea corridor reconstruction tender announcements for winter wheat fleet replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Emissions After-Treatment Integration Partnership | Engine-tractor bundling secures EPA Tier 4 Final compliance timelines for Corn Belt OEM procurement. |
| Telematics Platform Unbundling | Dealer revenue shifts from transaction margins to recurring uptime guarantees in Germany's Schleswig-Holstein. |
| Autonomous Retrofit Kit Development | Computer vision packages for existing tractor platforms open technology access without full machine replacement. |
| Equipment-as-a-Service Network Expansion | Seasonal rental pools reduce capital barriers for mid-scale operators in India's Haryana state. |
| Regional Forging Partnership Anchoring | European assembly footprint secures component supply against steel price volatility and logistics disruption. |
Research Approach
Direct dialogue with OEM procurement directors, dealer service department heads, large-scale grower operations managers, and precision technology integration specialists grounded qualitative findings in operational reality. Secondary validation drew from USDA Conservation Reserve Program filings, EPA emissions certification databases, EU Common Agricultural Policy implementation reports, and Brazilian agricultural ministry credit line disclosures. Bottom-up equipment unit economics triangulated against top-down regional mechanization indices.
Bottom-up modeling of tractor, harvester, and implement unit shipments across power segments converged with top-down agricultural GDP and commodity price elasticity assumptions over the projection horizon. Segmentation dimensions included product type, technology tier, application intensity, and end-user scale. CAGRs derived from historical replacement cycle compression under emissions compliance pressure and precision agriculture adoption curves. Industry-specific inputs incorporated steel price volatility indices and semiconductor lead time fluctuations.
Revisions become necessary when EPA or EU emissions timeline accelerations materialize, commodity margin collapses extend equipment replacement deferrals, or autonomous field validation failures delay commercial deployment. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology cost reduction trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Feller Buncher Market
Agricultural Equipment
Soil Testing Equipment Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Commercial Grain Mill Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Battery Powered Cultivators Market