
 Bucking Machine Market | 2026-2036
Bucking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Bucking Machine Market Analytics
OSHA logging safety standards are recalibrating the cost-of-entry calculus for bucking machine operators, mandating enhanced guarding and emergency-stop systems that favor capitalized equipment suppliers. CenturionPro Solutions leverages its specialization in automated trimming architectures to serve high-throughput forestry contractors. Munch Machine anchors its position through robust portable designs engineered for remote terrain access. Rayco Manufacturing competes on manufacturing scale, sustaining broad distribution across North American logging regions.
A bucking machine severs felled trees into predetermined log lengths using hydraulic, electric, or manual force applied through a cutting head or saw mechanism, typically achieving throughput rates measured in stems per hour for commercial timber operations. Automated bucking machines command premium positioning as labor scarcity and precision requirements reshape procurement patterns among large-scale Forestry Services. Electric bucking machines gain traction in noise-sensitive harvesting zones where regulatory pressure and operational flexibility intersect.
EPA Tier 4 Final emissions rules and OSHA logging safety directives shape equipment design mandates and operator certification pathways across the United States. The Forest Stewardship Council chain-of-custody standards further constrain machine eligibility for certified timber programs. Stakeholders must monitor the pace of electrification against hydraulic performance benchmarks to align capital deployment with evolving site constraints and compliance timelines.
Market Dynamics
Forestry Services in the Pacific Northwest are accelerating fleet modernization as EPA Tier 4 Final emissions standards and OSHA logging safety mandates recalibrate equipment procurement criteria. The convergence of labor scarcity with precision harvesting requirements is compressing replacement cycles for mechanized bucking systems.
Growth Catalysts
- EPA Tier 4 Final certification:Off-road diesel engine standards are forcing premature retirement of legacy equipment, generating replacement demand among capitalized logging contractors in Oregon and Washington.
- Forestry Services mechanization:Large-scale timber operators are consolidating harvesting contracts and standardizing on automated bucking architectures to offset skilled operator shortages.
- Electric powertrain maturation:Battery-electric cutting systems are penetrating noise-sensitive harvesting zones near urban-wildland interfaces where regulatory pressure intersects with operational flexibility requirements.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings for specialized alloys and high-pressure systems compress margin predictability for equipment fabricators.
- Pacific Northwest supply concentration:Demand clustering in Oregon and Washington corridors creates geographic exposure to regional timber market cycles and wildfire disruption.
- Manual bucking persistence:Low-capacity landowners and selective harvest operations continue relying on chainsaw crews for small-diameter or irregular stem processing.
Strategic Opportunities
- Forest Stewardship Council chain-of-custody alignment:Certification eligibility for mechanized harvesting equipment opens contracted timber programs requiring documented environmental compliance.
- Remote terrain electrification:Portable electric bucking systems are penetrating previously inaccessible high-elevation stands where diesel transport logistics constrain conventional deployment.
- Precision bucking software integration:Convergence of LiDAR stem scanning with real-time optimization algorithms is enabling value recovery maximization for high-grade sawlog operations.
Industry Challenges
- OSHA-certified operator scarcity:Enhanced guarding and emergency-stop system mandates extend training timelines and inflate wage premiums for qualified bucking machine technicians.
- Tier 4 engine integration complexity:Aftertreatment system packaging and thermal management requirements strain hydraulic system layout constraints in compact machine architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bucking Machine Market |
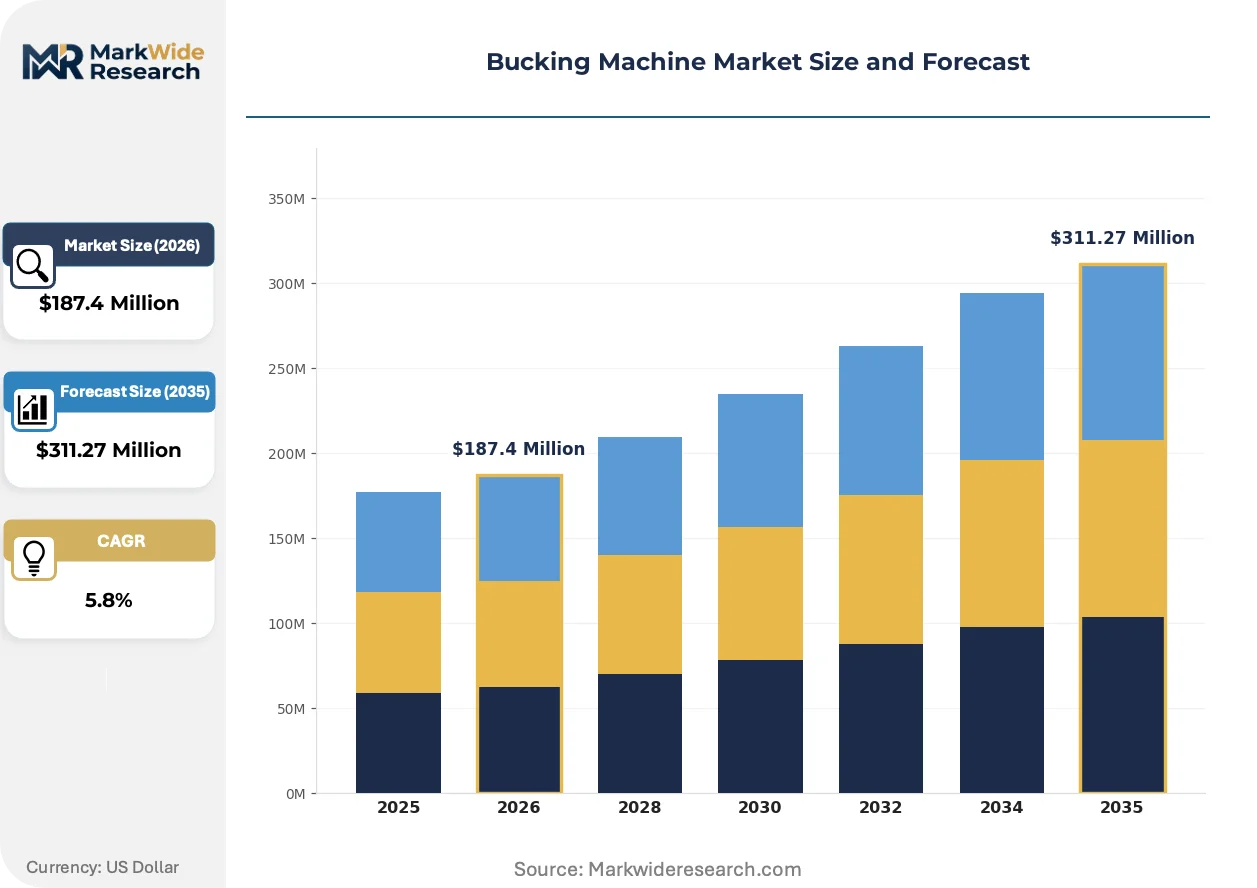
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Bucking Machine, Electric Bucking Machine, Manual Bucking Machine, Automated Bucking Machine Application: Oil Extraction, Logging Operations, Heavy Machinery, Construction End User: Oil & Gas Companies, Construction Firms, Mining Corporations, Forestry Services Features: Portable Design, High Efficiency, Low Noise Operation, Safety Mechanisms |
| Companies Covered | CenturionPro Solutions, Munch Machine, EZ Trim, Triminator, Mobius, Python Industries, Rayco Manufacturing, Bobcat Company, Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bucking Machine Market Evolving Landscape
Mechanized bucking equipment is undergoing fundamental architecture shifts as electrification, emissions compliance, and precision harvesting converge. These forces are compressing traditional equipment lifecycles while opening new operational domains previously reserved for manual methods.
Electrification is unifying powertrain and cutting system design in next-generation bucking machines. Battery-electric architectures are penetrating noise-restricted harvesting zones near recreational and residential boundaries. Forestry Services contractors in Washington's urban-wildland interface are piloting these systems to secure extended operating permits while eliminating diesel particulate exposure for ground crews.
OSHA logging safety directives are mandating enhanced guarding and emergency-stop systems across all new equipment certifications. These requirements are elevating design complexity and capital thresholds for market entry. Oregon-based contractors are responding by consolidating procurement with suppliers demonstrating sustained compliance engineering capabilities rather than sourcing from fragmented fabricators.
Equipment-as-service contracting is displacing traditional capital purchase models among mid-scale Forestry Services operators. Usage-based agreements with bundled maintenance and compliance updates are reducing balance-sheet exposure for contractors facing uncertain timber harvest allocations. This pattern is most visible in Washington state where volatile federal land access permits compress capital deployment confidence.
Bucking Machine Market Segmentation
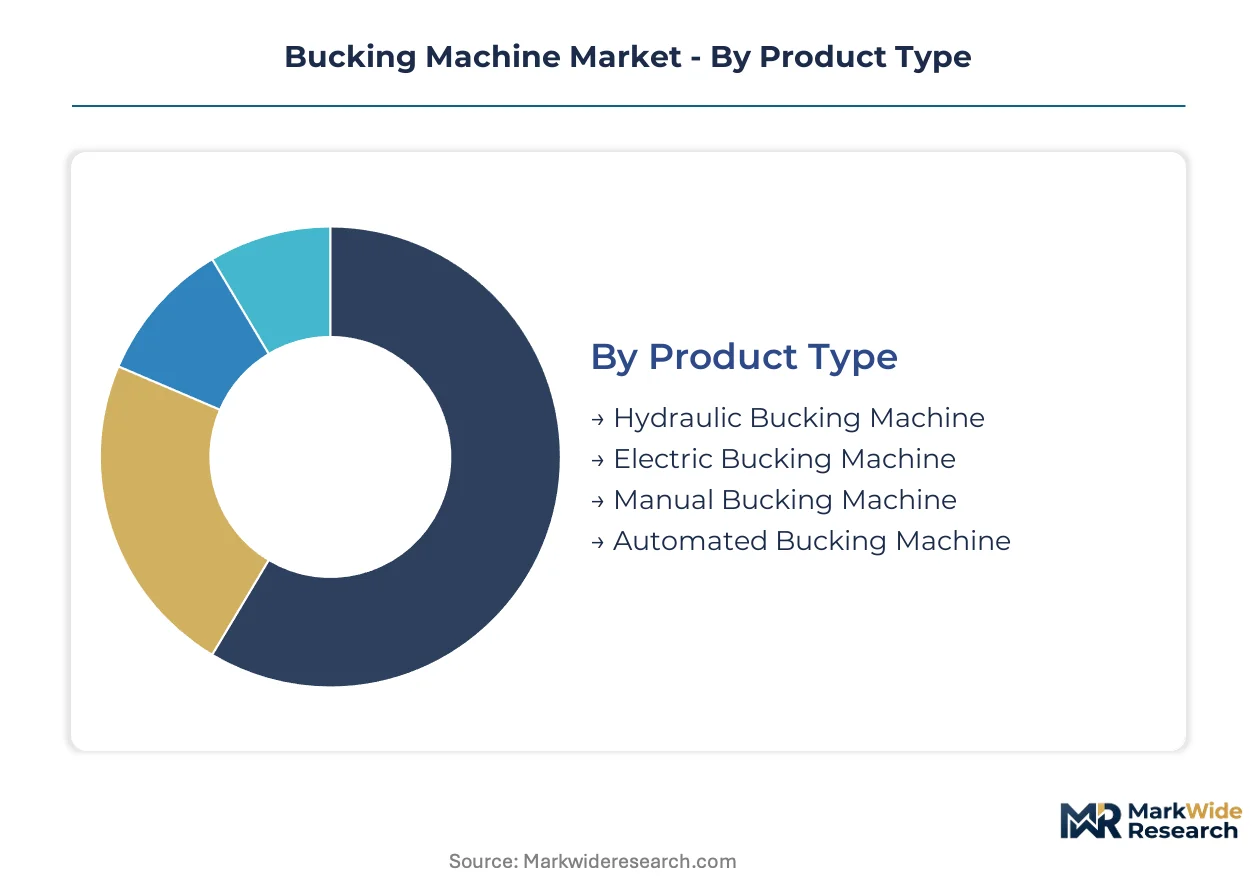
Segmentation in the bucking machine market reveals how powertrain architecture, operational environment, and procurement authority reshape equipment specifications. Distinct technical requirements across extraction industries fragment demand into specialized configurations that resist universal platform solutions.
Product Type:
Hydraulic systems dominate volume shipments while electric architectures capture premium positioning in regulated harvesting zones.
- Hydraulic Bucking Machine:These systems deploy high-pressure fluid power to drive cutting heads through dense timber species, achieving sustained throughput in commercial clearcut operations. Oregon and Washington logging contractors standardize on hydraulic platforms for their proven field reliability and rapid field-serviceability. Mature deployment sits with Hydraulic Bucking Machine. Newer deployment is concentrated in Electric Bucking Machine.
- Electric Bucking Machine:Battery-electric architectures eliminate diesel particulate emissions and reduce noise signatures below 75 decibels, enabling extended operating permits near urban-wildland interfaces. Washington state contractors pilot these systems where EPA emissions enforcement and municipal noise ordinances intersect.
- Manual Bucking Machine:Compact lever-operated units serve low-volume landowners and selective harvest operations where capital constraints outweigh productivity requirements.
- Automated Bucking Machine:LiDAR-integrated systems with real-time optimization algorithms maximize sawlog value recovery through precision length cutting.
Procurement patterns bifurcate between established hydraulic fleets and electrified pilot programs, with automation representing the steepest expansion trajectory among capitalized operators.
Application:
Logging operations absorb the majority of unit shipments while oil extraction applications command specialized engineering for hazardous environment certification.
- Logging Operations:Commercial timber harvesting deploys bucking machines at roadside landings and in-woods processing sites to convert felled stems into merchantable log lengths. Pacific Northwest Forestry Services drive replacement demand as EPA Tier 4 Final standards retire legacy equipment.
- Oil Extraction:Pipeline right-of-way maintenance and wellpad clearing require spark-resistant configurations for explosive atmosphere compliance. These applications concentrate in Texas and North Dakota shale formations where OSHA process safety management intersects with vegetation management contracts.
- Heavy Machinery:Equipment manufacturers integrate bucking attachments into multi-function forestry carriers for unified harvesting systems.
- Construction:Land clearing and site preparation operations utilize portable bucking units for dimensional timber recovery from demolition and deconstruction projects.
Application maturity clusters in Logging Operations. Emerging deployment is accelerating in Oil Extraction as pipeline integrity management expands vegetation control budgets.
End User:
Forestry Services consolidate procurement volume while mining corporations represent the highest specification tier for extreme-duty applications.
- Forestry Services:Contract harvesting operators standardize fleet configurations across multiple timber sale contracts, prioritizing interchangeability and parts commonality. These entities dominate Pacific Northwest equipment absorption.
- Mining Corporations:Surface mining reclamation and exploration camp timber requirements demand severe-duty guarding and extended maintenance intervals for remote deployment.
- Oil & Gas Companies:Integrated operators and midstream pipeline operators specify explosion-proof electrical systems and hot-work permitting compatibility.
- Construction Firms:General contractors and specialty site developers acquire portable units for project-specific vegetation management without fleet standardization requirements.
Established procurement authority rests with Forestry Services. Expanding purchase activity is concentrating in Mining Corporations as reclamation bonding requirements intensify.
Features:
Safety mechanism integration has shifted from optional to mandatory across all certified equipment, while noise attenuation determines market access in regulated zones.
- Safety Mechanisms:OSHA-mandated emergency-stop systems, interlocked guarding, and operator presence sensing now constitute baseline compliance rather than premium specification. Equipment lacking these features faces market exclusion.
- Low Noise Operation:Electric powertrains and acoustic enclosures enable regulatory compliance in noise-restricted harvesting zones near recreational and residential boundaries.
- Portable Design:Compact footprints and helicopter-lift compatibility extend mechanized bucking into high-elevation stands where road access is absent.
- High Efficiency:Optimized cutting cycles and reduced fuel consumption improve unit economics for contract operators paid per processed stem.
Feature adoption maturity centers on Safety Mechanisms. Rapid feature integration is occurring in Low Noise Operation as municipal permitting requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for bucking machines concentrates in timber-rich jurisdictions where mechanized harvesting standards and emissions enforcement intersect. Procurement patterns track regulatory stringency and commercial forestry scale across distinct national markets.
United States
EPA Tier 4 Final standards and OSHA logging safety mandates are compressing equipment replacement cycles across Oregon and Washington logging corridors. The Pacific Northwest Forestry Services sector drives premium absorption for automated bucking architectures. Contractors in the Willamette Valley cluster are consolidating procurement with compliance-certified suppliers.
Canada
British Columbia's coastal and interior timber operations sustain demand for severe-duty bucking systems engineered for high-elevation extraction. Health Canada's PMRA and provincial WorkSafeBC directives shape equipment guarding specifications. Vancouver Island contractors are piloting electric architectures in noise-sensitive watershed harvesting zones.
Germany
The EU Green Deal and F-Gas Regulation are accelerating electrification timelines for forestry equipment deployed in Baden-Württemberg's Black Forest management districts. ECHA REACH compliance requirements constrain hydraulic fluid formulations for sustainable timber certification programs. Bavarian state forest enterprises are standardizing on low-emission mechanized systems.
Sweden
Severe climate resilience requirements and SIS standards drive specification tiers for bucking machines operating above the Arctic Circle in Norrbotten County. The Swedish Forest Agency's mechanization incentives support precision harvesting technology adoption. Södra Skogsägarna cooperative members are integrating LiDAR-optimized bucking systems across Västerbotten stands.
Brazil
ANVISA industrial safety protocols and IBAMA environmental licensing shape equipment import requirements for Amazon frontier and Atlantic Forest plantation operations. Eucalyptus and pine commercial harvesting in Minas Gerais and Paraná sustains hydraulic platform demand. São Paulo state forestry cooperatives are evaluating automated bucking for certified timber export programs.
Bucking Machine Market Competitive Landscape
North American fabricators anchor the automated and portable equipment tier; European and Asian machinery conglomerates hold scale positions in integrated carrier systems. Market structure bifurcates between specialized bucking equipment pure-plays and diversified forestry machinery portfolios. Three archetypes dominate: compliance-engineering specialists, portable-system innovators, and multi-function platform integrators. Competitive moves concentrate on electrification partnerships and regional distribution consolidation.
Within the specialized equipment tier, CenturionPro Solutions and Munch Machine exemplify contrasting positioning strategies, while Rayco Manufacturing occupies a position among scale-oriented fabricators. CenturionPro Solutions represents the automated architecture archetype serving high-throughput contractors. Munch Machine anchors the portable design segment engineered for remote terrain access. Rayco Manufacturing sits within the broad-distribution manufacturing scale category across North American logging regions.
| Leading Market Players |
|---|
| CenturionPro Solutions |
| Munch Machine |
| EZ Trim |
| Triminator |
| Mobius |
| Python Industries |
| Rayco Manufacturing |
| Bobcat Company |
| Kubota Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up forestry equipment specialists anchor supply concentration across Oregon and Washington fabrication clusters, translating geographic consolidation into pricing discipline that favors capitalized contractors over fragmented buyers. This ownership pattern tightens margin capture at the OEM tier while channeling procurement leverage toward consolidated Forestry Services operators.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent replacement orders from scheduled fleet renewals, with Tier 4 Final compliance deadlines compressing delivery windows and inflating premiums for EPA-certified hydraulic platforms. Contract-based long-term offtake agreements dominate procurement between capitalized contractors and certified suppliers, while spot transactions concentrate among smaller operators facing emergency retirement of non-compliant legacy units. Price differentiation rests on EPA certification tier and bundled after-sales service coverage, with Oregon-based buyers exhibiting highest sensitivity to upfront capital outlay versus Washington operators prioritizing total cost of ownership.
Supply Chain Analysis
Domestic-content mandates under the Buy American Act reshape sourcing for federal land management contractors, compelling assembly localization even as specialized hydraulic components continue drawing from German and Japanese precision manufacturers. Steel alloy feedstock and high-pressure hydraulic systems anchor raw material dependencies, with supply chain risk concentrating in single-source vulnerability for Tier 4 Final aftertreatment modules. Distribution runs through manufacturer-direct field service networks and regional forestry equipment dealerships concentrated in Portland and Seattle metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final certification requirements construct a cost-of-compliance moat that advantages incumbent suppliers with sustained engineering investment, raising capital thresholds beyond reach of fragmented fabricators and consolidating procurement authority among certified OEMs.
For Market Incumbents: Deepen vertical integration into hydraulic system manufacturing to insulate margin capture from steel alloy volatility, while expanding certified service infrastructure across Washington's federal land corridor to preempt emerging entrants targeting volatile permit access. Consolidate position by acquiring portable-system specialists before electrification partnerships restructure competitive boundaries.
For New Entrants and Emerging Players: Forestry equipment rental cooperatives represent the most penetrable channel archetype for electric bucking architectures, with Vancouver Island noise-restricted zones offering white-space access where incumbent hydraulic dominance weakens. Target high-elevation helicopter-portable applications in British Columbia interior districts, deploying equipment-as-service contracting to circumvent capital-purchase consolidation among established buyers.
For Investors and Strategic Acquirers: Washington state electric pilot program announcements are the leading indicator that electrification timelines are compressing ahead of hydraulic replacement cycles, signaling acquisition window closure for battery-electric platform specialists. Long-term viability favors vertically integrated fabricators with EPA certification engineering depth and established Forestry Services channel control.
| Strategic Initiative | Industry Significance |
|---|---|
| EPA Tier 4 Final Certification Investment | Establishes regulatory compliance barrier protecting incumbent OEMs from fragmented import competition. |
| Electric Powertrain Platform Development | Captures noise-restricted harvesting permits near Washington urban-wildland interface zones. |
| Equipment-as-Service Contracting Model | Reduces balance-sheet exposure for contractors facing volatile federal timber sale allocations. |
| Precision Bucking Software Integration | Maximizes sawlog value recovery through LiDAR-optimized length cutting for high-grade operations. |
| Regional Service Network Expansion | Secures recurring revenue streams via mandatory OSHA-compliant maintenance and guarding updates. |
Research Methodology
Multi-period observation of EPA certification timelines, OSHA enforcement patterns, and Forestry Services fleet renewal cycles anchored the trend analysis, supplemented by interviews with equipment procurement directors at Pacific Northwest logging contractors, hydraulic systems engineers at Oregon fabrication facilities, and aftermarket service managers at regional dealership networks. Secondary validation drew from EPA engine certification databases, Oregon and Washington state timber harvest permit records, and SEC filings of publicly traded forestry machinery conglomerates. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Input-output matrices modeled powertrain architecture, operational environment, and procurement authority across the projection horizon, with segmentation spanning hydraulic-electric-manual-automated product tiers and logging-oil extraction-construction applications. CAGRs derived from replacement cycle compression analysis against electrification adoption curves, incorporating Tier 4 Final compliance deadlines and wildfire disruption frequency as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including speculative federal land management policy shifts, breakthrough battery energy density improvements, and catastrophic wildfire seasons exceeding historical disruption baselines. Forecasts reflect documented assumptions about regulatory enforcement continuity and timber price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Global Yield Monitoring Devices Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Plucker Machine Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Global Precision Harvesting Market