
 Plows Market | 2026-2036
Plows Market Size, Share, and Industry Trends Forecast 2026-2036
Plows Market Analysis
Premium-grade corrosion-resistant tillage specifications is collapsing the gap between commodity plow suppliers and precision agriculture specialists. Deere & Company leverages its integrated precision farming platform to dominate North American high-horsepower segments. AGCO Corporation sustains competitive positioning through specialized Fendt-branded mounted plow systems. LEMKEN GmbH & Co. KG anchors European demand with German-engineered subsoiler technology.
A plow is a soil-engaging implement featuring a share, moldboard, and landside assembly designed to cut, lift, and invert soil to depths typically ranging from fifteen to thirty centimeters, primarily serving seedbed preparation and residue burial in agricultural production. Mounted plows occupy the largest installed base due to tractor compatibility and lower capital requirements, while pull-behind configurations command premium positioning among large-scale cereal operations in Eastern Europe. Hydraulic technology segments capture expanding replacement cycles as farmers retrofit manual systems for real-time depth control.
EPA emission standards for off-road diesel equipment and EU F-Gas Regulation refrigerant mandates constrain engine and climate-system configurations in new plow tractor pairings. OSHA agricultural equipment safety directives and ISO 4254 machinery guarding standards shape product design thresholds for North American and European market access. Stakeholders must monitor evolving carbon border adjustment mechanisms and decide whether to localize heat-treated steel component forging or source from established supply basins.
Market Dynamics
Precision tillage adoption among commercial farming cooperatives is collapsing traditional equipment replacement cycles. EU Green Deal sustainability mandates and F-Gas Regulation compliance requirements are forcing rapid specification changes across European supply chains.
Growth Catalysts
- EU Green Deal sustainability mandates:Carbon-neutral farming targets in Germany's Rhineland agricultural corridor accelerate demand for low-disturbance subsoiler configurations. Equipment specifications now prioritize soil health metrics alongside productivity.
- Commercial farming cooperatives:Consolidated acreage operations in Eastern Europe drive pull-behind plow procurement at premium price points. Scale economics favor hydraulic retrofitting over manual system maintenance.
- F-Gas Regulation compliance:Refrigerant-phaseout timelines force climate-system redesigns in tractor-plow pairings. Manufacturers must certify new configurations to maintain EU market access.
Market Restraints
- Heat-treated steel input volatility:Forged component costs fluctuate with energy-intensive metallurgical processing. Localized forging capacity decisions carry multi-year payback uncertainty.
- Supply concentration in German engineering clusters:Premium subsoiler technology depends on Rhineland manufacturing density. Geographic clustering creates vulnerability to regional logistics disruptions.
- Technical limitation in real-time depth calibration:Hydraulic retrofit systems face sensor reliability gaps in variable soil conditions. Manual override requirements persist in clay-heavy substrates.
Strategic Opportunities
- Eastern European cereal belt expansion:Large-scale operations in Poland and Romania underinvest in precision tillage relative to yield potential. First-mover positioning in pull-behind segments offers margin capture.
- Carbon border adjustment mechanism preparation:Early compliance with embedded emissions tracking creates preferential access to EU procurement channels. Steel sourcing documentation becomes competitive differentiator.
- Telematics-predictive maintenance convergence:Sensor-enabled plow-tractor integration enables usage-based service models. Data monetization extends equipment lifecycle revenue beyond initial sale.
Industry Challenges
- ISO 4254 machinery guarding certification timelines:Safety standard updates require design freeze periods that compress product development windows. Testing bottlenecks delay market entry for new configurations.
- Hydraulic system integration complexity:Legacy tractor fleets lack compatible electronic architectures for precision depth control. Retrofit engineering demands strain OEM service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plows Market |
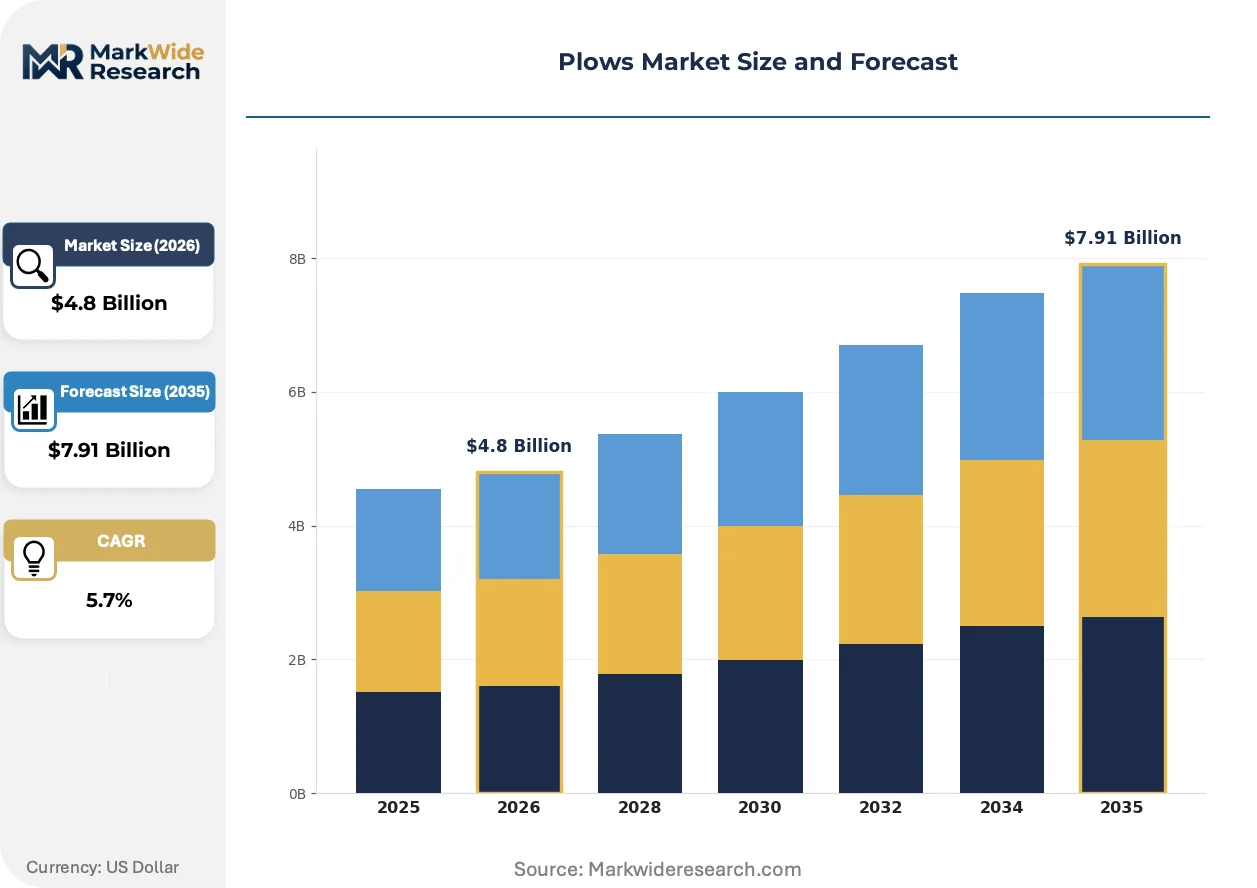
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mounted Plows, Pull-Behind Plows, Snow Plows, Subsoiler Plows End User: Agriculture, Landscaping Companies, Municipalities, Farmers Material: Steel, Cast Iron, Aluminum, Plastic Technology: Manual, Hydraulic, Electric, Automated |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial India Pvt. Ltd., KUHN SAS, LEMKEN GmbH & Co. KG, BEDNAR FMT s.r.o., ISEKI & CO. LTD., Amazonen-Werke G. Dreyer Maschinenfabrik GmbH, Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plows Market Emerging Trajectories
Active depth-sensing technology is compressing the performance gap between commodity tillage and precision agriculture systems. Regulatory pressure on embedded emissions and safety compliance is accelerating specification divergence across regional markets.
Electro-hydraulic depth control systems with sub-centimeter accuracy are displacing mechanical linkage configurations in high-horsepower tractor pairings. Commercial cooperatives in Germany and Poland adopt these systems at replacement-cycle inflection points. The technology is displacing manual calibration labor pools while enabling variable-rate tillage prescriptions that optimize fuel consumption per hectare.
EU F-Gas Regulation refrigerant mandates are forcing climate-system redesigns in new tractor-plow combinations. Equipment manufacturers must validate alternative cooling architectures to maintain CE marking eligibility. Pull-behind configurations with integrated hydraulic cooling face the steepest compliance redesign costs, compressing development budgets for Eastern European market variants.
Outcome-based equipment performance contracts are replacing traditional capital purchase models among consolidated farming operations. Dealer networks in the Rhineland corridor now bundle tillage-as-a-service with precision agriculture subscriptions. Poland's emerging cooperative sector exhibits the fastest behavioral transition, driven by liquidity constraints and yield-guarantee risk transfer preferences.
Plows Market Segmentation
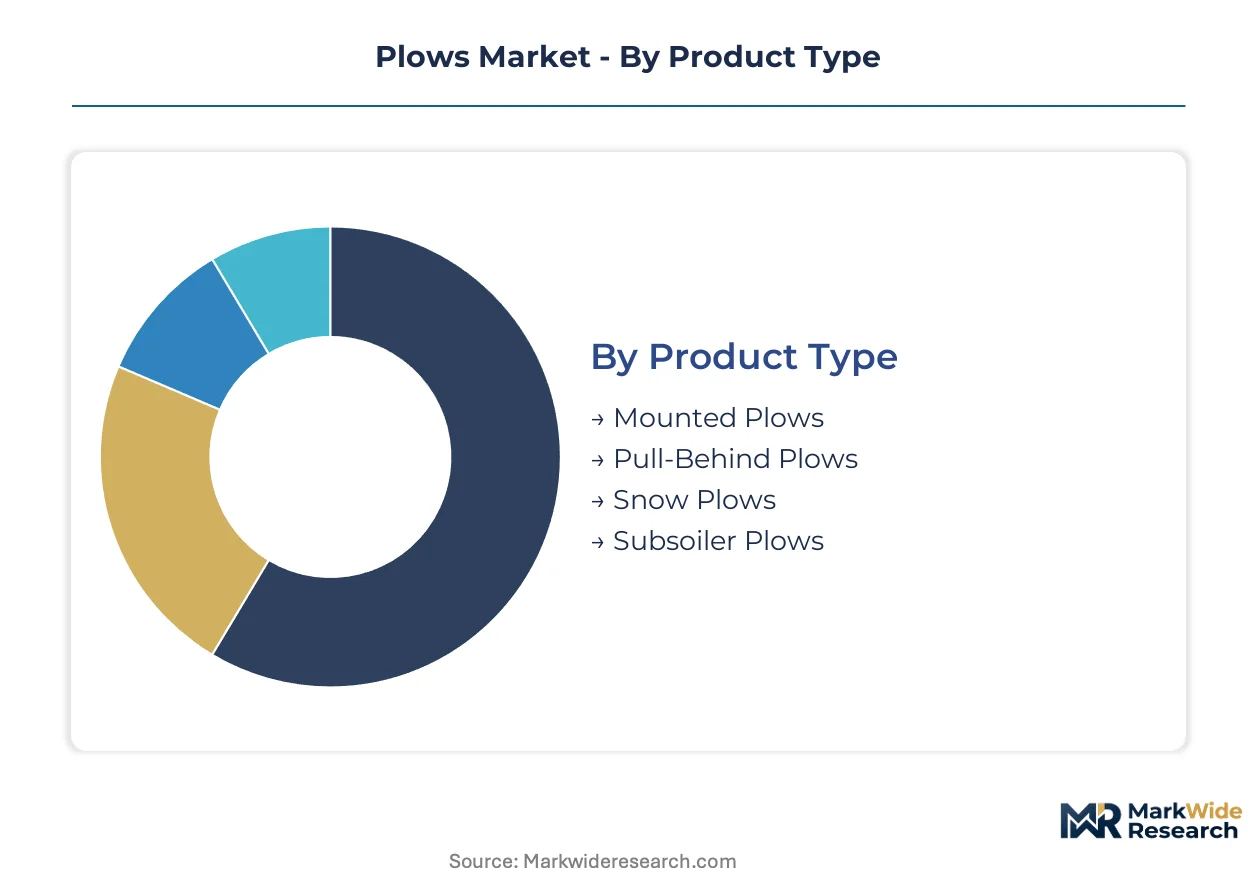
Margin capture in plow manufacturing diverges sharply across product architecture and control-system sophistication. Equipment specifications now stratify between commodity tillage for smallholders and precision-enabled systems for consolidated commercial operations.
Product Type:
Margin pools concentrate in pull-behind configurations and subsoiler systems where engineering complexity sustains premium pricing.
- Mounted Plows:Three-point hitch attachment systems dominate installed base economics through tractor compatibility and lower capital barriers. Demand concentrates among Germany's Rhineland cereal cooperatives where fleet standardization favors interchangeable implements.
- Pull-Behind Plows:Trailed configurations with independent hydraulic depth control command premium positioning in Eastern European large-scale operations. Poland's consolidated acreage farms drive procurement at price points reflecting scale economics and precision tillage requirements.
- Snow Plows:Municipal winter maintenance specifications vary by regional snowfall patterns and road infrastructure density.
- Subsoiler Plows:Deep tillage implements with minimal surface disturbance align with EU Green Deal soil health mandates.
The dominant share belongs to Mounted Plows, while Pull-Behind Plows is closing the gap fastest.
End User:
Volume concentration sits with commercial farming operations, though municipal procurement carries distinct specification and contract-tenure patterns.
- Agriculture:Commercial cooperatives in Germany and Poland drive replacement cycles for precision-enabled tillage systems. Yield-guarantee contracts and outcome-based service models are restructuring capital deployment patterns across Rhineland corridors.
- Farmers:Individual operators in Romania and Bulgaria underinvest in hydraulic retrofitting relative to productivity potential. Liquidity constraints and manual system maintenance habits delay technology adoption.
- Landscaping Companies:Specialized turf renovation and estate maintenance applications require compact mounted configurations.
- Municipalities:Public sector snow removal and roadside maintenance programs operate on multi-year equipment replacement schedules.
Agriculture commands the largest revenue pool, with Farmers expanding most quickly as cooperative consolidation accelerates.
Material:
Cost tier stratification follows metallurgical processing intensity and corrosion-resistance specifications.
- Steel:Heat-treated boron steel shares and moldboards dominate high-wear applications through hardness retention and field longevity. Forged component sourcing decisions carry multi-year payback uncertainty given energy-intensive metallurgical processing.
- Cast Iron:Lower-cost shares suit seasonal operations with limited annual hour accumulation.
- Aluminum:Weight reduction benefits transport and mounting logistics for specialized applications.
- Plastic:Polymer components appear in non-wearing structural elements and guard systems.
Steel retains the dominant specification share, while Cast Iron is gaining traction fastest in emerging market price-sensitive procurement.
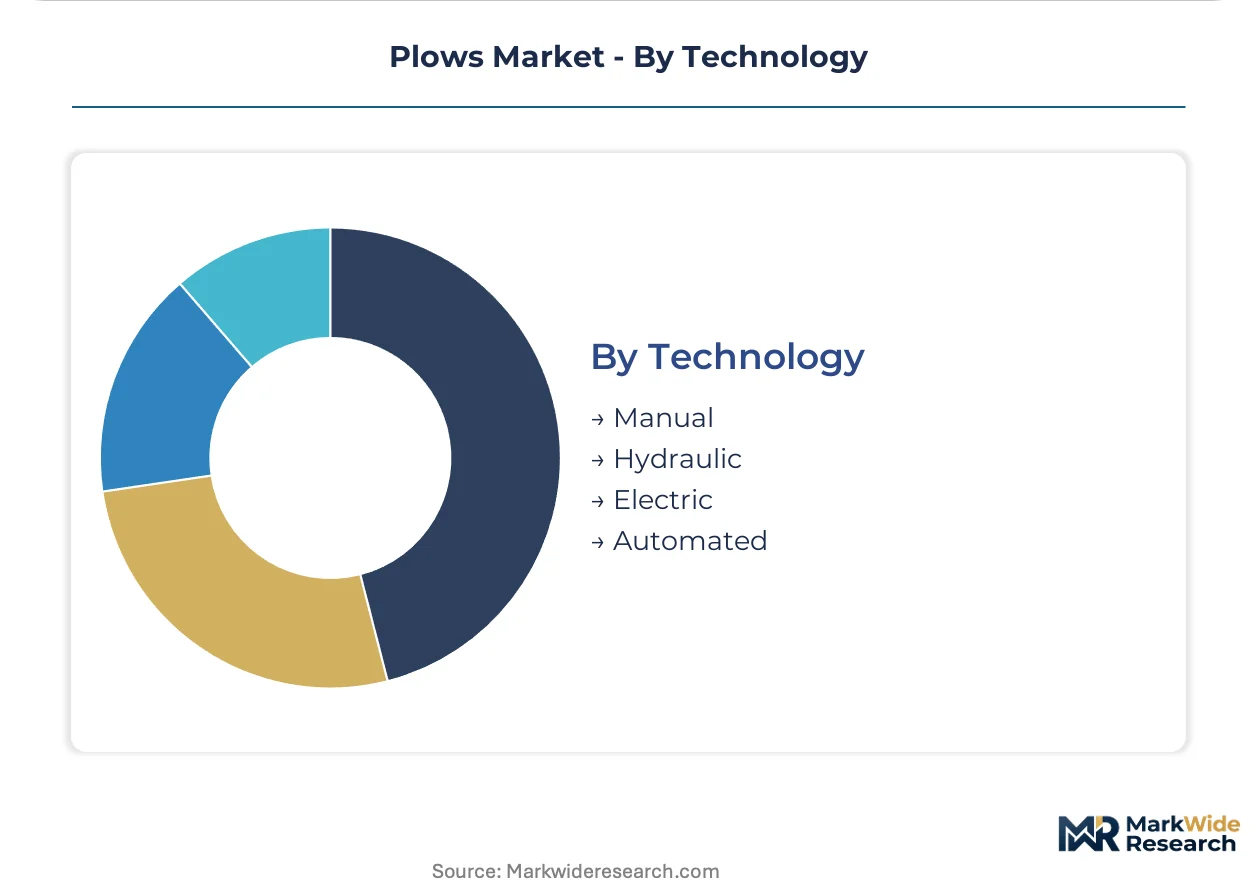
Technology:
Customer willingness-to-pay escalates with real-time control precision and labor substitution potential.
- Hydraulic:Electro-hydraulic depth control with sub-centimeter accuracy displaces mechanical linkages in high-horsepower tractor pairings. Commercial cooperatives adopt these systems at replacement-cycle inflection points, enabling variable-rate tillage prescriptions that optimize fuel consumption per hectare.
- Automated:Sensor-enabled plow-tractor integration with telematics connectivity supports predictive maintenance and usage-based service models. Data monetization extends equipment lifecycle revenue beyond initial sale for OEMs with integrated precision farming platforms.
- Manual:Mechanical linkage systems persist in clay-heavy substrates where sensor reliability gaps require override capability.
- Electric:Electrified actuation architectures remain nascent pending tractor electrical system standardization.
Hydraulic systems hold the dominant installed base, while Automated configurations are climbing the fastest as telematics-predictive maintenance convergence matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German-manufactured subsoiler systems flow primarily into Poland and Romania, establishing a Rhineland-to-Eastern Europe trade corridor that concentrates premium tillage procurement.
Germany
Rhineland agricultural cooperatives drive replacement cycles for precision-enabled hydraulic systems. EU F-Gas Regulation refrigerant mandates force climate-system redesigns in new tractor-plow combinations. Engineering clusters around Mönchengladbach and Düsseldorf anchor subsoiler production for export markets.
Poland
Consolidated cereal operations in Greater Poland and Masovia provinces generate pull-behind plow demand at premium price points. EU Green Deal carbon-neutral farming targets accelerate low-disturbance tillage specifications. Wrocław-based distribution hubs coordinate Eastern European equipment flows.
Romania
Large-scale farming cooperatives in the Wallachian Plain underinvest in hydraulic retrofitting relative to productivity potential. National rural development programs subsidize precision agriculture equipment procurement. Cluj-Napoca machinery dealers bridge service gaps for automated depth-control systems.
United States
Midwest corn-soybean belt operations sustain demand for high-horsepower mounted configurations. EPA emission standards for off-road diesel equipment constrain engine specifications in new tractor pairings. Illinois and Iowa implement dealers coordinate precision farming platform integration.
France
Beauce cereal producers prioritize soil health metrics alongside productivity in equipment specifications. REACH chemical compliance requirements shape corrosion-resistant coating specifications for tillage components. Bourges manufacturing clusters supply mounted plow systems to domestic cooperatives.
Plows Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base stratifies between integrated agricultural equipment conglomerates and focused tillage engineering houses. Three archetypes dominate: precision-platform integrators, specialized implement manufacturers, and diversified machinery conglomerates. Competitive moves concentrate on precision agriculture platform integration and Eastern European distribution network expansion.
Among German-engineered specialists, LEMKEN GmbH & Co. KG and BEDNAR FMT s.r.o. exemplify the focused implement manufacturer archetype, occupying positions where subsoiler technology depth sustains premium pricing. Deere & Company represents the precision-platform integrator tier, anchoring competitive positioning through integrated farming system architectures. These three companies illustrate how engineering specialization and platform breadth create distinct competitive vectors in tillage equipment procurement.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial India Pvt. Ltd. |
| KUHN SAS |
| LEMKEN GmbH & Co. KG |
| BEDNAR FMT s.r.o. |
| ISEKI & CO. LTD. |
| Amazonen-Werke G. Dreyer Maschinenfabrik GmbH |
| Kubota Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Rhineland forging clusters shapes both supply concentration and price floors for heat-treated boron steel components. Scale economics in German metallurgical processing anchor premium-tier pricing while smaller Eastern European fabricators compete on manual system retrofitting margins.
Pricing Analysis
Electro-hydraulic depth control systems command substantial premiums over mechanical linkage configurations, while next-generation automated telematics integration is widening the technology-generation gap further. Three-tier pricing structure across precision-enabled, standard hydraulic, and manual economy levels reflects certification grade and after-sales service bundling. Cost compression in manual tier equipment is intensifying because Romanian and Bulgarian smallholders delay replacement cycles. Commercial farming cooperatives in Poland exhibit the lowest price sensitivity, prioritizing yield-guarantee contract integration over capital expenditure minimization.
Supply Chain Analysis
Germany and Poland anchor forged component production for premium subsoiler systems, while Chinese steel mills feed commodity-grade material inputs. Heat-treated boron steel shares, hydraulic actuator assemblies, and sensor modules constitute critical component dependencies. Single-source vulnerability concentrates in Rhineland engineering clusters exposed to regional logistics disruptions. Distribution runs through Wrocław-based hubs coordinating Eastern European equipment flows and Rhineland cooperative direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled predictive maintenance subscriptions are expanding faster than hardware sales among consolidated farming cooperatives, transforming capital equipment markets into service-attach opportunities.
For Market Incumbents: Secure backward integration into heat-treated steel forging capacity to defend margin position against metallurgical input volatility. Anchor certification investment in ISO 4254 machinery guarding updates to compress competitor development windows. Prioritize channel control through dealer network exclusivity in Poland's Greater Poland corridor where cooperative consolidation accelerates replacement demand. For New Entrants and Emerging Players: Lead with telematics-predictive maintenance convergence as the go-to-market wedge in Romania's Wallachian Plain, where large-scale cooperatives underinvest in precision tillage relative to yield potential. Target municipal snow removal procurement as a white-space segment with multi-year contract tenure and lower competitive intensity. Bundle tillage-as-a-service with yield-guarantee risk transfer to bypass capital expenditure barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized implement manufacturers with subsoiler technology depth over diversified machinery conglomerates. Long-term viability across the projection horizon rests on precision agriculture platform integration capabilities and Eastern European distribution network density. Watch hydraulic-electrification standardization timelines in tractor electrical architectures as the inflection indicator for next-generation equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Captive supply of heat-treated boron steel components insulates margin from energy-intensive metallurgical processing volatility. |
| Telematics Platform Integration | Sensor-enabled plow-tractor connectivity enables usage-based service models extending lifecycle revenue beyond initial sale. |
| Eastern European Distribution Expansion | Wrocław-based hub positioning captures Poland-Romania cooperative consolidation driving pull-behind premium procurement. |
| EU F-Gas Regulation Compliance Certification | Alternative cooling architecture validation preserves CE marking eligibility for tractor-plow combination sales. |
| Outcome-Based Equipment Performance Contracts | Yield-guarantee bundling with precision agriculture subscriptions transfers risk and accelerates behavioral transition in liquidity-constrained segments. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with agricultural equipment procurement directors, aftermarket service heads, and cooperative farm managers across Germany and Poland; and secondary validation through customs trade records, EU F-Gas Regulation compliance filings, and SEC equipment manufacturer disclosures. Bottom-up triangulation across dealer network inventory data and top-down reconciliation against Rhineland production cluster output estimates anchored volume and value assessments.
Across the analysis window, forecasts incorporate product type segmentation by mounting configuration, technology tier by control system sophistication, and end-user archetype by operational scale. CAGRs derive from replacement cycle modeling calibrated to cooperative consolidation rates and EU Green Deal mandate implementation timelines. Inputs include tractor fleet age distributions, hydraulic retrofit penetration curves, and embedded emissions tracking compliance preparation status.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated Eastern European cooperative formation would require recalibration. Forecasts reflect assumptions regarding F-Gas refrigerant phaseout adherence and carbon border adjustment mechanism implementation scope. Recalibration cycles align with material shifts in precision tillage technology adoption rates and heat-treated steel input cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Commercial Grain Mill Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Green Beans Harvester Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market