
 Solar Fruit Dryer Market | 2026-2036
Solar Fruit Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Fruit Dryer Market Insights
Asset-light leasing and pay-per-use project finance is narrowing the capital barrier for smallholder cooperatives entering solar drying. Ecozen Solutions leverages its distributed energy expertise to sustain equipment deployment across South Asian agricultural belts. Rudra Solar Energy anchors its position through in-house photovoltaic integration, while Solar Dryers Australia competes via specialized tray configurations for temperate-climate fruits.
A solar fruit dryer harnesses concentrated thermal energy or photovoltaic electricity to reduce moisture content in harvested produce through controlled airflow and heat exchange, typically operating between 40-70°C to preserve nutritional integrity while preventing enzymatic degradation. The primary commercial purpose centers on extending shelf life, reducing post-harvest losses, and enabling commodity producers to access premium dried-fruit export markets without grid-dependent infrastructure. Hybrid dryer configurations command attention as the fastest-expanding product type, blending solar thermal collectors with biomass backup to ensure continuous operation during intermittent sunlight periods. Small-scale capacity units dominate volume shipments among home users and village-level agricultural producers, though industrial-scale installations serving food processing companies and exporters capture disproportionate margin pools through throughput efficiency and certification-grade output consistency.
The EU Green Deal and REACH chemical safety standards shape equipment material specifications for European market access, while India's BIS certification and MNRE solar mission guidelines define domestic product eligibility for subsidy-linked procurement. Kenya's Energy Regulatory Authority and Uganda's Rural Electrification Agency both incorporate solar drying into national agricultural mechanization programs, creating aligned demand pull across East African trade corridors. Stakeholders must monitor how evolving carbon border adjustment mechanisms and food safety traceability requirements reshape equipment specification standards and export eligibility criteria for dried fruit commodities.
Market Dynamics
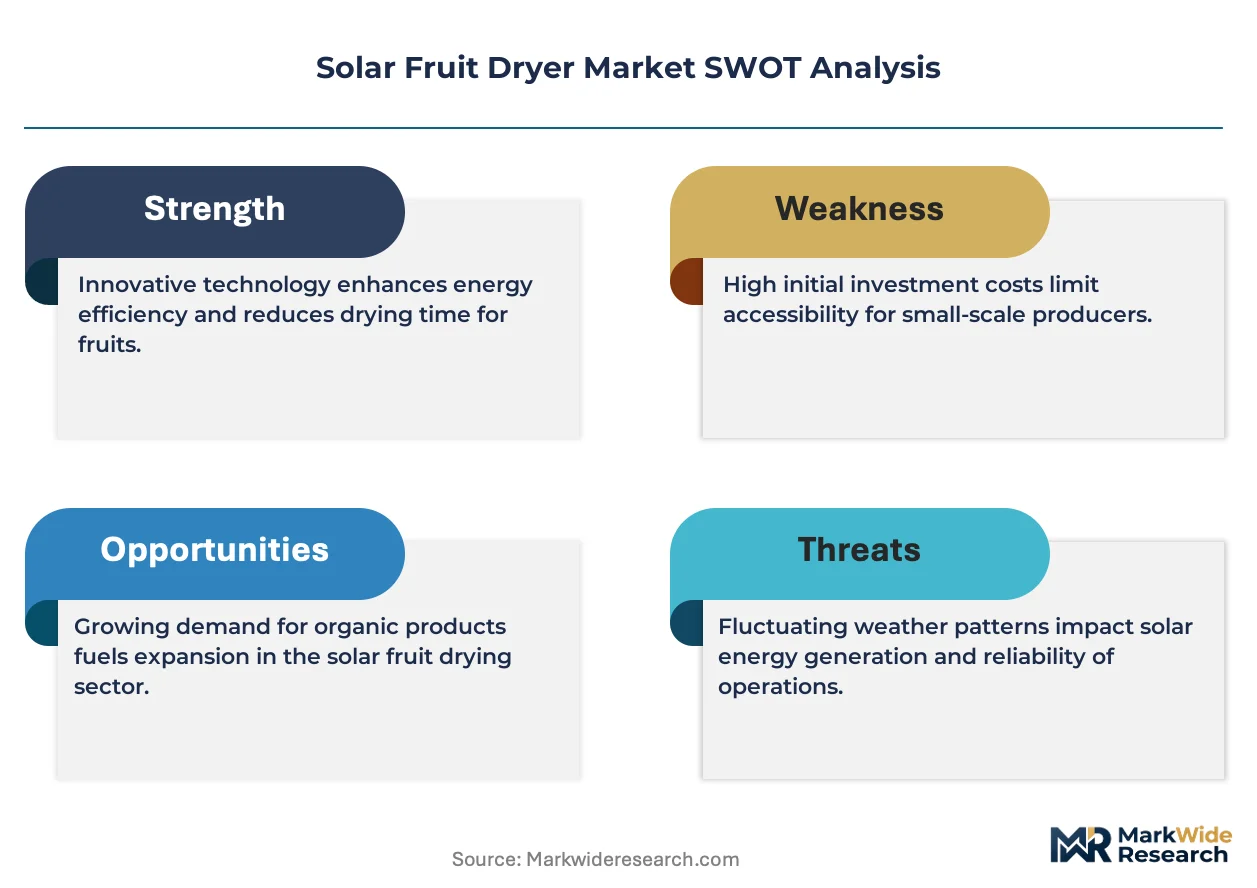
Hybrid solar-biomass dryer configurations are compressing payback periods for agricultural cooperatives, while EU Green Deal material mandates and India's MNRE subsidy frameworks reshape equipment procurement criteria across export corridors.
Growth Catalysts
- Kenya-Uganda Agricultural Mechanization:National programs by Kenya's Energy Regulatory Authority and Uganda's Rural Electrification Agency embed solar drying into cooperative infrastructure, creating aligned demand pull across East African trade corridors.
- EU Green Deal Sustainability Mandates:REACH chemical safety standards and carbon border adjustment mechanisms redirect dried-fruit export supply chains toward certified solar thermal processing equipment.
- Photovoltaic-Thermal Hybrid Integration:Biomass backup systems eliminate intermittency losses, enabling continuous operation that meets food safety traceability requirements for premium export markets.
Market Restraints
- Capital Intensity for Smallholders:Upfront equipment costs exceed liquidity thresholds for village-level producers absent leasing or pay-per-use finance structures.
- Aluminum-Glass Supply Concentration:Solar thermal collector manufacturing depends on concentrated Chinese and Indian glass processing and aluminum extrusion capacity.
- Moisture Calibration Complexity:Enzymatic degradation risks from imprecise temperature control limit output consistency for uncertified operators seeking export eligibility.
Strategic Opportunities
- Maharashtra-Gujarat Extension Networks:India's state-level agricultural programs offer underpenetrated deployment channels for decentralized post-harvest processing infrastructure.
- Carbon Credit Monetization:EU Emissions Trading System linkage opportunities create revenue stacking for solar thermal operations displacing LPG-dependent conventional drying.
- Blockchain Traceability Integration:Convergence of IoT sensors and distributed ledger systems enables premium pricing through verified origin and process documentation.
Industry Challenges
- Thermal Engineering Skill Scarcity:Design and maintenance of heat exchanger configurations and airflow optimization require specialized technicians absent in rural deployment zones.
- BIS Certification Timelines:India's Bureau of Indian Standards testing protocols create procurement delays for subsidy-linked equipment qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Fruit Dryer Market |
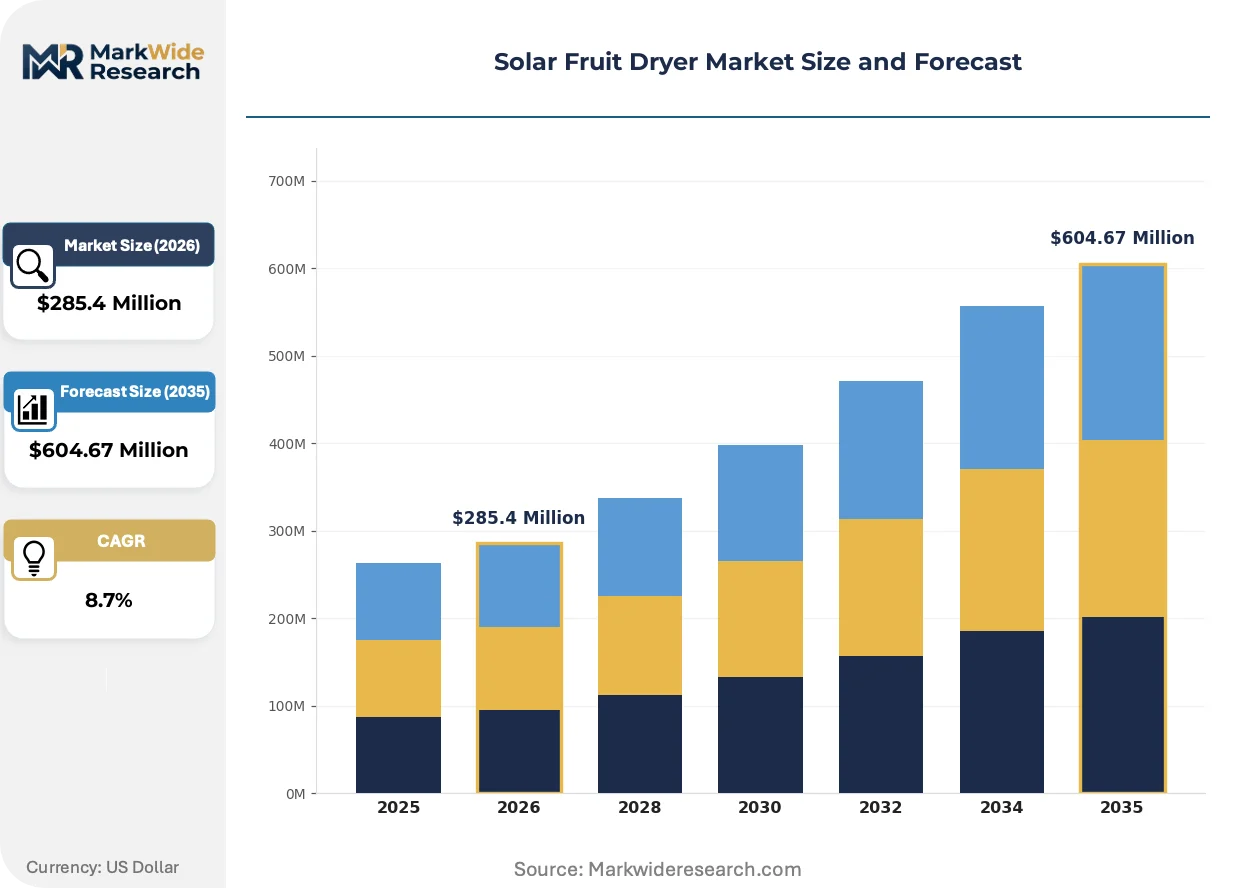
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Tunnel Dryer, Box Type Dryer, Hybrid Dryer, Tray Dryer End User: Agricultural Producers, Food Processing Companies, Home Users, Exporters Technology: Thermal Collector, Heat Exchanger, Reflective Panels, Airflow System Capacity: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | SunBest, SolarDrier, EcoDryer, SolarDryer Technologies, Inc., GrainPro Inc, Ecozen Solutions, Suncue Company Ltd., Solar Dryers Australia, Rudra Solar Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Fruit Dryer Market Trends and Innovations
Digital monitoring systems and modular thermal architectures are compressing operational complexity for distributed agricultural users, while regulatory material mandates and alternative finance structures reshape equipment access models.
Phase-change material thermal storage is virtualizing energy availability in solar drying operations by decoupling heat collection from drying cycles. Agricultural cooperatives in Kenya and Uganda are adopting PCM-augmented configurations to maintain 40-70°C chamber temperatures through overnight processing windows. This thermal buffering is virtualizing the intermittency constraint that previously limited solar dryer deployment to sun-dependent daytime operations.
EU REACH restrictions on chemical coatings and the EU Green Deal circular economy requirements are mandating stainless steel and food-grade aluminum substitutions in collector construction. Equipment manufacturers serving European export markets must reformulate material specifications to maintain market access. Indian and East African producers targeting EU dried-fruit import channels are retrofitting existing installations to comply with these evolving material standards.
Village-level cooperatives are fragmenting procurement authority away from centralized agricultural boards toward autonomous equipment leasing decisions. Pay-per-use and asset-light finance models displace traditional capital purchase structures in Maharashtra and Gujarat state networks. This decentralization is most visible among women-led cooperative societies in India's western agricultural belts, where group liability structures enable collective equipment access without individual collateral requirements.
Solar Fruit Dryer Market Segmentation
Solar fruit dryer procurement patterns diverge sharply across user sophistication levels, with maintenance protocols and technical support requirements varying by equipment complexity and deployment scale. Equipment manufacturers calibrate service networks and spare parts logistics around these segment-specific intensity profiles.
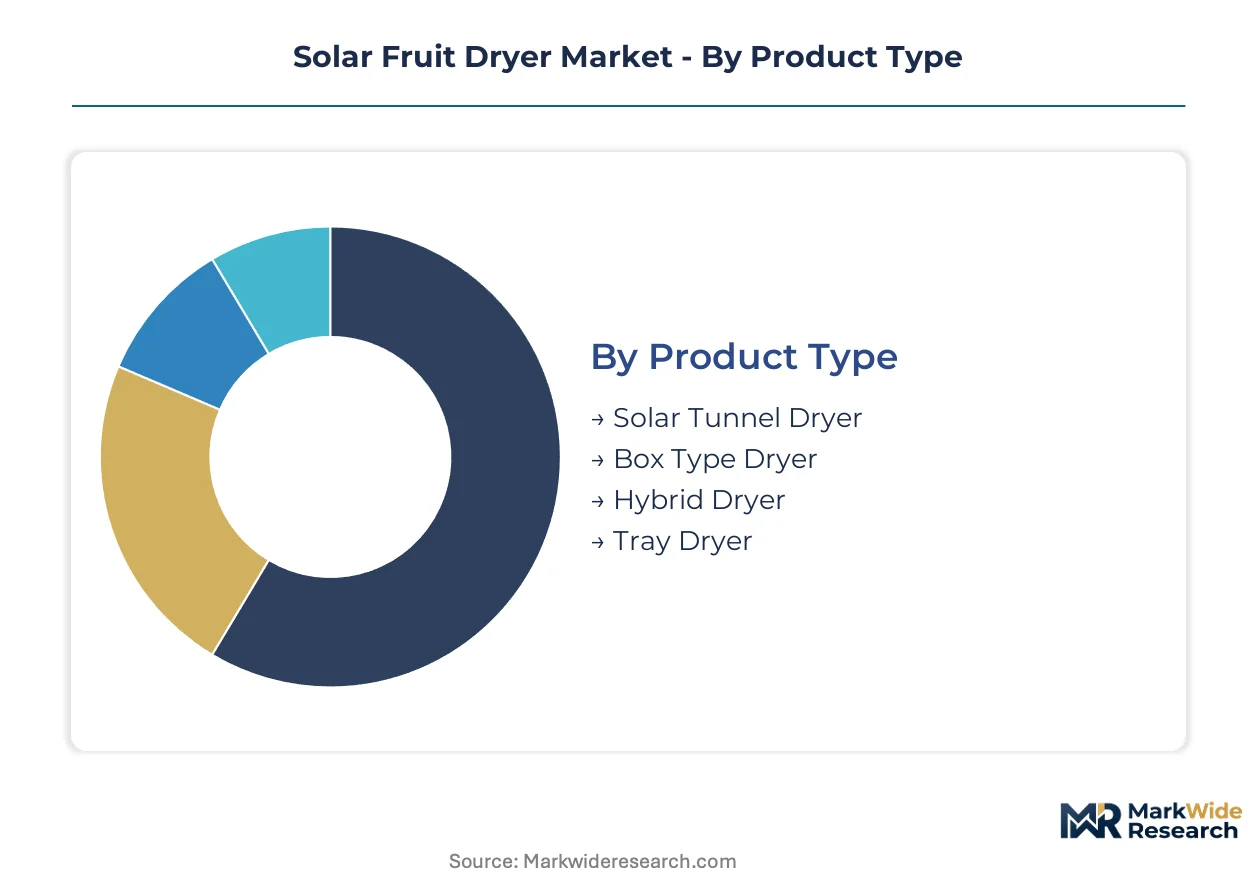
Product Type:
After-sales-service intensity escalates with system integration complexity, as hybrid configurations demand multi-technology maintenance capabilities while simple box units require minimal field support.
- Hybrid Dryer:Combines solar thermal collectors with biomass or photovoltaic backup systems to eliminate intermittency constraints. Agricultural cooperatives in Kenya and Uganda prioritize these configurations for continuous processing that meets export certification timelines. Demand concentrates among cooperative societies seeking uninterrupted throughput for premium dried-fruit consignments.
- Solar Tunnel Dryer:Employs elongated chamber designs with controlled airflow for batch processing of high-volume harvests. Maharashtra and Gujarat state extension programs subsidize tunnel configurations for village-level federations managing seasonal fruit gluts. These units dominate institutional procurement through agricultural mechanization grants.
- Box Type Dryer:Compact cabinet designs suited for home users and smallholder trial deployments.
- Tray Dryer:Modular stacking systems enabling graded moisture removal across multiple commodity layers.
Hybrid Dryer holds the largest share; momentum sits with Solar Tunnel Dryer.
End User:
Cost tier stratification separates capital-intensive industrial deployments from asset-light cooperative leasing arrangements.
- Food Processing Companies:Operate industrial-scale installations with automated moisture monitoring and certification-grade output consistency. These buyers command premium equipment specifications to satisfy EU Green Deal traceability mandates and REACH material compliance for European export channels. Procurement emphasizes throughput efficiency and documentation systems.
- Agricultural Producers:Village-level cooperatives and individual farmers accessing equipment through pay-per-use or group liability structures. India's MNRE subsidy frameworks and Kenya's Energy Regulatory Authority programs target this tier with decentralized post-harvest infrastructure. Financing innovation determines penetration depth.
- Exporters:Require carbon border adjustment documentation and blockchain-verified process records for premium market access.
- Home Users:Limited-scale adopters purchasing small-capacity units for household food preservation.
Agricultural Producers account for the greatest volume; Food Processing Companies generate the steepest expansion trajectory.
Technology:
Application-specific thermal engineering determines equipment performance margins across varying ambient conditions and commodity moisture profiles.
- Thermal Collector:Captures and concentrates solar radiation through glazed apertures and absorber plates, forming the core heat generation subsystem. Efficiency gains in evacuated tube and flat-plate designs are reshaping equipment standards under EU Green Deal sustainability mandates. Supply concentration in Chinese and Indian glass processing capacity creates procurement vulnerability.
- Heat Exchanger:Transfers collected thermal energy to drying air streams while isolating combustion byproducts in hybrid configurations. Phase-change material integration is virtualizing heat availability for overnight processing windows in East African cooperative deployments. Technical sophistication separates certified from uncertified operators.
- Reflective Panels:Redirect incident radiation toward collection surfaces to boost thermal capture rates.
- Airflow System:Regulates chamber ventilation and humidity evacuation to prevent enzymatic degradation.
Thermal Collector dominates installed base; Heat Exchanger is climbing the fastest.
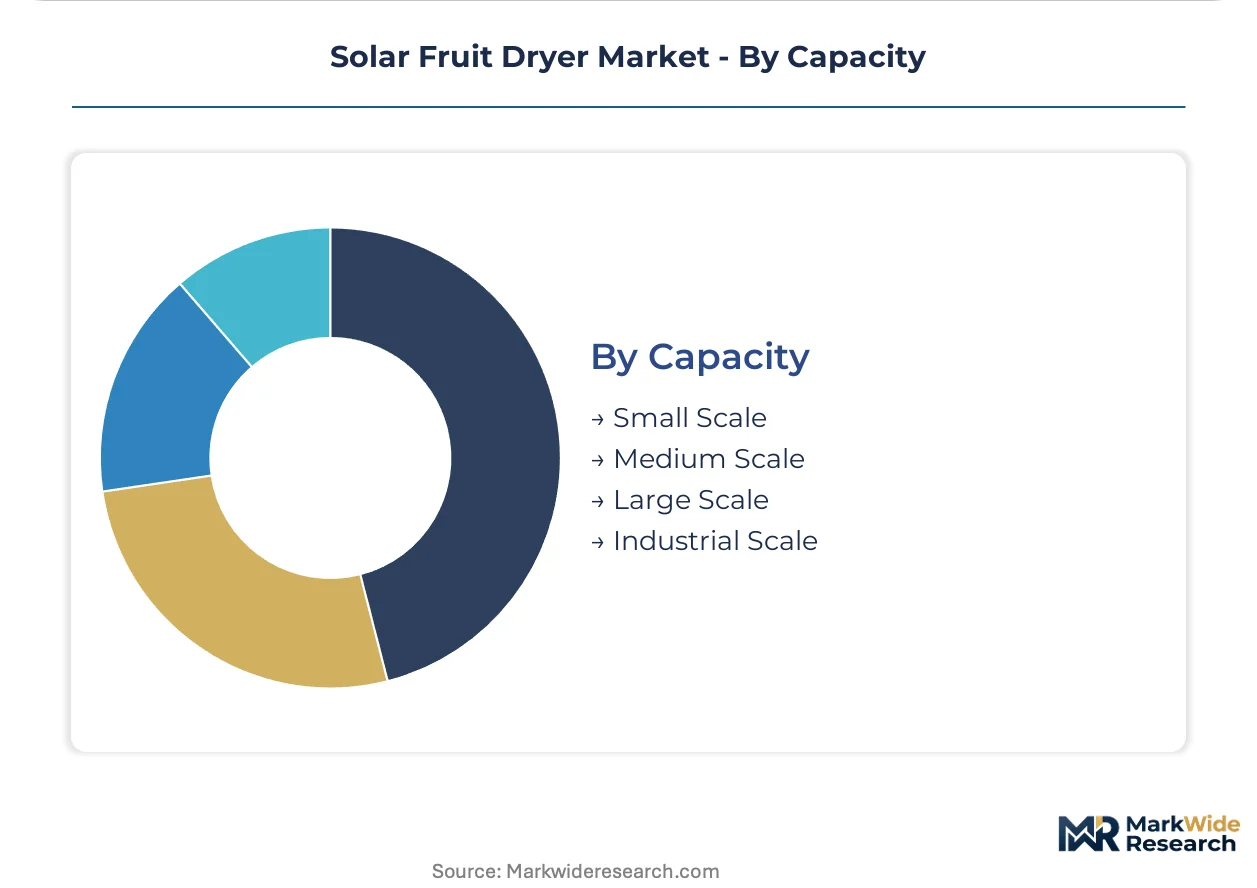
Capacity:
Customer type and margin structure invert across the scale spectrum, with small units saturating volume shipments while industrial installations capture disproportionate value pools.
- Small Scale:Units processing under 100 kilograms per batch serve home users and trial-stage cooperatives. India's western state networks and Uganda's Rural Electrification Agency programs prioritize this tier for women-led group liability structures. Asset-light finance models displace capital purchase in this segment.
- Industrial Scale:Continuous-flow systems exceeding 5 tons daily throughput serve export-oriented processing facilities. These installations integrate IoT sensors and blockchain documentation to command premium pricing through verified origin credentials. EU dried-fruit import channels drive specification requirements.
- Medium Scale:Batch systems serving emerging cooperatives transitioning from pilot to commercial operations.
- Large Scale:Semi-automated configurations bridging village-level and industrial processing thresholds.
Small Scale leads shipment volumes; Industrial Scale is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East African cooperatives command premium dried-fruit export pricing through solar thermal processing, while Indian smallholders absorb margin compression from subsidy-dependent procurement cycles. This pricing-power asymmetry reflects divergent finance structures and certification access across deployment zones.
Kenya
Agricultural cooperatives in the Rift Valley and Central Highlands drive hybrid dryer adoption for continuous processing of mango and pineapple harvests. Kenya's Energy Regulatory Authority embeds solar drying into national agricultural mechanization programs, channeling equipment subsidies through county-level extension networks. Nairobi-based equipment distributors coordinate last-mile logistics for cooperative federations seeking export certification.
Uganda
Rural Electrification Agency programs target post-harvest loss reduction through decentralized solar drying infrastructure in the Central and Western regions. The agency's cooperative financing schemes enable women-led societies to access equipment through group liability structures. Kampala serves as the procurement hub for East African trade corridor equipment flows.
India
Maharashtra and Gujarat state agricultural extension programs promote solar drying infrastructure for grape, mango, and banana processing cooperatives. MNRE solar mission guidelines define domestic product eligibility for subsidy-linked procurement, while BIS certification timelines create equipment qualification delays. Nashik and Surat industrial clusters concentrate fabrication capacity for thermal collector components.
Australia
Temperate-climate fruit producers in Victoria and New South Wales adopt specialized tray configurations for stone fruit and berry drying operations. Food safety traceability requirements from major export markets drive specification standards for equipment serving premium dried-fruit channels. Melbourne-based engineering firms supply heat exchanger subsystems to Asia-Pacific deployment zones.
Germany
EU Green Deal sustainability mandates and REACH chemical safety standards reshape equipment material specifications for European market access. Bavarian and Baden-Württemberg industrial zones concentrate thermal engineering expertise for high-efficiency collector design. German certification bodies validate equipment compliance for dried-fruit export supply chains targeting EU import channels.
Solar Fruit Dryer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in thermal engineering and material supply. The vendor base stratifies between full-system providers and subsystem fabricators, with cooperative procurement patterns favoring turnkey solutions over self-assembly configurations. Three archetypes dominate: distributed energy platforms with agricultural extension networks, photovoltaic-integrated fabricators with captive component production, and climate-specialized designers with region-specific tray geometries. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players seek to secure glass processing and aluminum extrusion supply commitments.
Among Asia-Pacific platform specialists, Ecozen Solutions and Suncue Company Ltd. occupy positions within the distributed energy tier, leveraging agricultural belt networks for equipment deployment. Rudra Solar Energy anchors the photovoltaic-integrated archetype through in-house component production capabilities. Solar Dryers Australia exemplifies climate-specialized positioning with temperate-region tray configurations. These three entities represent distinct strategic vectors: extension-network scale, vertical manufacturing control, and geographic adaptation.
| Leading Market Players |
|---|
| SunBest |
| SolarDrier |
| EcoDryer |
| SolarDryer Technologies, Inc. |
| GrainPro Inc |
| Ecozen Solutions |
| Suncue Company Ltd. |
| Solar Dryers Australia |
| Rudra Solar Energy |
| Others |
Pricing and Supply Chain Analysis
Mombasa-Nairobi freight corridors impose cost premiums on aluminum extrusion and tempered glass imports, compressing margins for East African equipment assemblers while enabling Indian and Chinese manufacturers to command price premiums through integrated component production and direct shipping access.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification-grade thermal collectors commanding substantial premiums over uncertified village-level units. Price differentiation rests on BIS certification status and EU Green Deal material compliance, with subsidy-linked procurement in Maharashtra and Gujarat intensifying cost compression in the standard tier. Agricultural cooperatives exhibit highest price sensitivity due to liquidity constraints, while export-oriented food processing companies absorb premium pricing for traceability documentation systems.
Supply Chain Analysis
Extended payment terms from Chinese and Indian glass processors and aluminum extruders dominate upstream financing structures, stretching working capital for equipment fabricators in Kenya and Uganda. Manufacturing draws from concentrated Chinese tempered glass capacity, Indian aluminum extrusion clusters, and German thermal engineering subsystems. Single-source vulnerability in evacuated tube collector supply creates procurement risk for hybrid dryer configurations. Distribution runs through agricultural extension networks and cooperative federations rather than conventional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal engineering expertise scarcity constrains deployment velocity, as heat exchanger design and PCM integration capabilities remain concentrated among Bavarian and Baden-Württemberg engineering clusters while rural East African and South Asian installation zones lack qualified maintenance technicians.
For Market Incumbents: Build certification moats around EU Green Deal REACH compliance and BIS qualification to lock out uncertified competitors from subsidy-linked procurement channels in India and European export corridors. Deepen backward integration into evacuated tube collector production to reduce exposure to Chinese glass supply concentration. Prioritize PCM thermal storage R&D to differentiate hybrid configurations from biomass-only backup alternatives. For New Entrants and Emerging Players: Uganda's Central Region cooperative financing schemes offer underpenetrated deployment channels where women-led group liability structures enable equipment access without traditional collateral requirements. Target Maharashtra's Nashik-Surat industrial corridor for component supply partnerships rather than direct system competition. Deploy pay-per-use finance platforms to bypass capital purchase barriers among village-level agricultural producers. For Investors and Strategic Acquirers: Distributed energy platforms with captive agricultural extension networks represent the most defensible acquisition archetype, combining equipment deployment with recurring service revenue streams. Long-term viability hinges on carbon credit monetization linkage to EU Emissions Trading System mechanisms. Monitor BIS certification timeline compression as an inflection signal for subsidy-linked procurement acceleration in Indian state networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Evacuated Tube Production | Captive glass processing capacity insulates margins from Chinese supply volatility and REACH compliance delays. |
| Phase-Change Material Thermal Storage Integration | PCM-augmented configurations enable overnight processing windows that differentiate East African cooperative offerings. |
| Carbon Credit Monetization Program | EU ETS linkage creates revenue stacking for solar thermal operations displacing LPG-dependent conventional drying. |
| Blockchain Traceability Platform Deployment | IoT sensor and distributed ledger integration commands premium pricing through verified origin documentation. |
| Women-Led Cooperative Financing Scheme | Group liability structures in Uganda's Central Region unlock village-level procurement without individual collateral requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with agricultural cooperative managers, thermal engineering specialists, equipment procurement officers at food processing companies, and MNRE subsidy program administrators. Secondary validation drew from BIS certification databases, Kenya Energy Regulatory Authority mechanization program filings, EU REACH regulatory updates, and India customs records for thermal collector component imports. Bottom-up shipment tallies by capacity tier and top-down market sizing by end-user segment were triangulated to constrain estimate variance.
Calibration against historical subsidy disbursement patterns and cooperative equipment deployment timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user sophistication tier, technology subsystem, and capacity scale, with additional cross-cutting analysis by certification status and finance structure. CAGRs were derived from fitted trend extrapolation moderated by regulatory milestone phasing assumptions. Key inputs encompassed MNRE subsidy allocation trajectories, EU carbon border adjustment implementation progress, and PCM thermal storage cost reduction curves.
Practitioners should monitor BIS certification timeline compression, EU Green Deal material mandate enforcement intensity, and carbon credit issuance volatility for early signals of forecast deviation. The analysis reflects documented assumptions regarding subsidy continuity and trade corridor stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Greenhouse Kit Market