
 Automated Turf Harvester Market | 2026-2036
Automated Turf Harvester Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Turf Harvester Market Analysis
Skilled equipment operator availability is collapsing across commercial turf operations, forcing landscape contractors toward autonomous harvesting platforms. FireFly Automatix, Inc. leverages proprietary cutting and stacking automation to anchor the high-volume sod farm segment. Kesmac Inc. competes through integrated roll-handling systems that reduce labor touchpoints. KWMI Equipment specializes in compact harvester configurations designed for constrained residential and municipal job sites.
An automated turf harvester is a self-propelled agricultural machine that cuts, rolls, and stacks sod using precision blade assemblies typically operating at depths of 0.5 to 2.0 inches, designed to replace manual labor in commercial turf extraction. GPS Navigation-equipped units dominate the technology segment where centimeter-level field mapping reduces overlap waste and fuel consumption. Robotic Harvesters represent the fastest-expanding product type as sod producers seek overnight unmanned cutting cycles. Smart Mowers occupy a mature adjacent position where margin pools have shifted toward software subscriptions and fleet management dashboards.
EPA Tier 4 Final emissions rules and OSHA agricultural equipment safety directives shape machine design requirements and compliance costs for domestic manufacturers. The EU Green Deal machinery standards and CE marking obligations govern export market access for North American producers shipping into European sports turf markets. Stakeholders must weigh capital deployment timing against pending battery-electric powertrain regulations that will redefine equipment specifications and dealer service infrastructure.
Market Dynamics
Skilled equipment operator shortages across commercial turf operations are accelerating capital reallocation toward autonomous harvesting platforms, compressing adoption timelines for GPS-guided and robotic systems.
Growth Catalysts
- EPA Tier 4 Final Emissions Standards:Diesel-powered grounds equipment faces tighter compliance deadlines, forcing sod producers to replace aging fleets with cleaner automated harvesters.
- Sports Turf Infrastructure Expansion:Professional stadium renovations and municipal field upgrades across the southeastern United States are driving concentrated demand for precision-cut sod volumes.
- Overnight Unmanned Operations:Robotic harvesters enable 24-hour cutting cycles that manual crews cannot match, extending productive harvesting windows during peak growing seasons.
Market Restraints
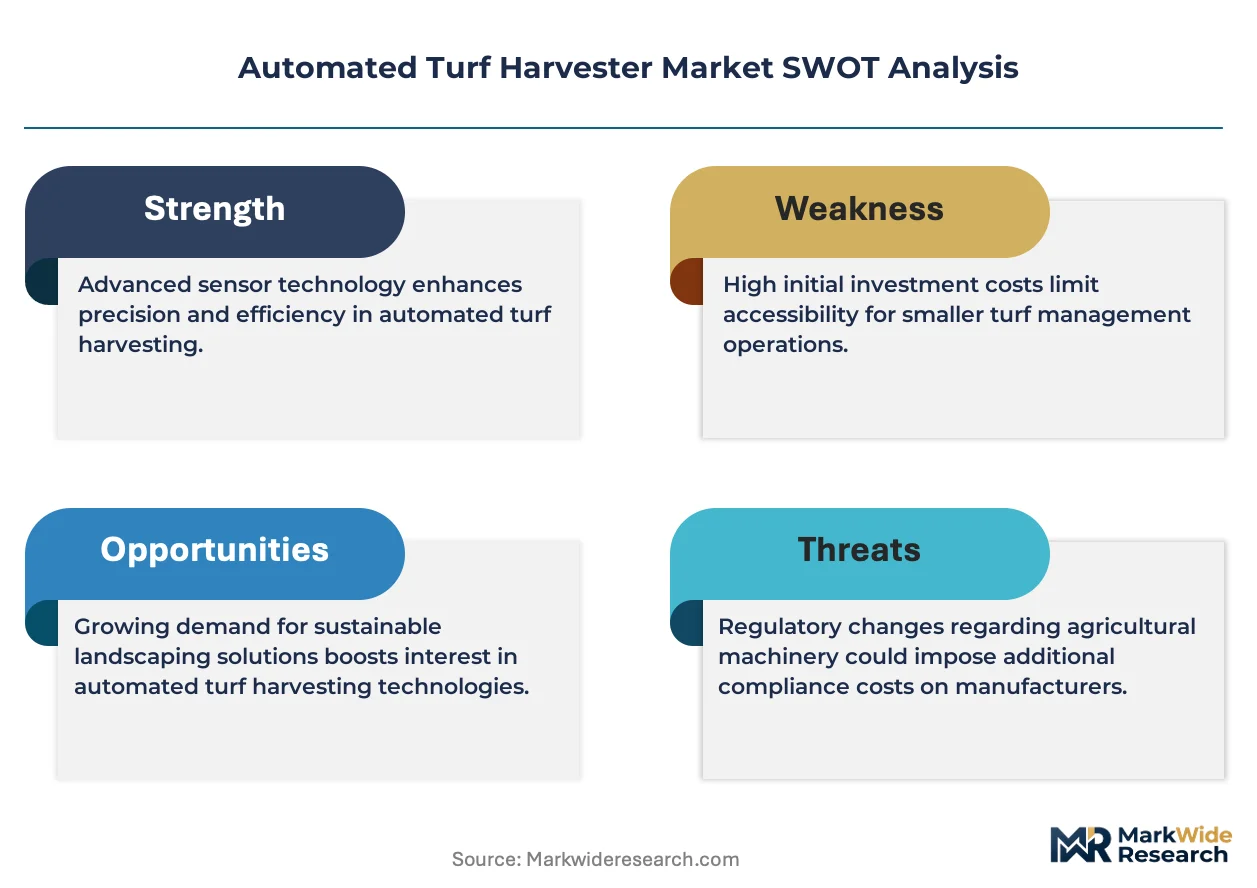
- Steel and Hydraulic Component Volatility:Precision blade assemblies and drive systems depend on alloy steel supply chains vulnerable to commodity price swings.
- Dealer Service Infrastructure Gaps:Rural sod production regions lack trained technicians for diagnostic repair of GPS navigation and robotic control modules.
- Manual Labor Substitution Economics:Seasonal migrant worker availability in Florida and Georgia temporarily reduces the payback calculus for capital-intensive automation.
Strategic Opportunities
- Battery-Electric Powertrain Transition:Pending zero-emission equipment mandates create first-mover advantages for manufacturers developing lithium-ion harvesting platforms.
- Residential and Municipal Job Sites:Compact harvester configurations address constrained access points where full-scale machines cannot operate.
- Fleet Management Software Subscriptions:Recurring revenue models for predictive maintenance dashboards and yield optimization analytics offset hardware margin pressure.
Industry Challenges
- Precision Agriculture Technician Scarcity:Sod farms struggle to hire operators capable of calibrating centimeter-level GPS field mapping and blade depth controls.
- CE Marking and EU Green Deal Compliance:North American manufacturers face extended certification timelines and documentation burdens for European sports turf market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Turf Harvester Market |
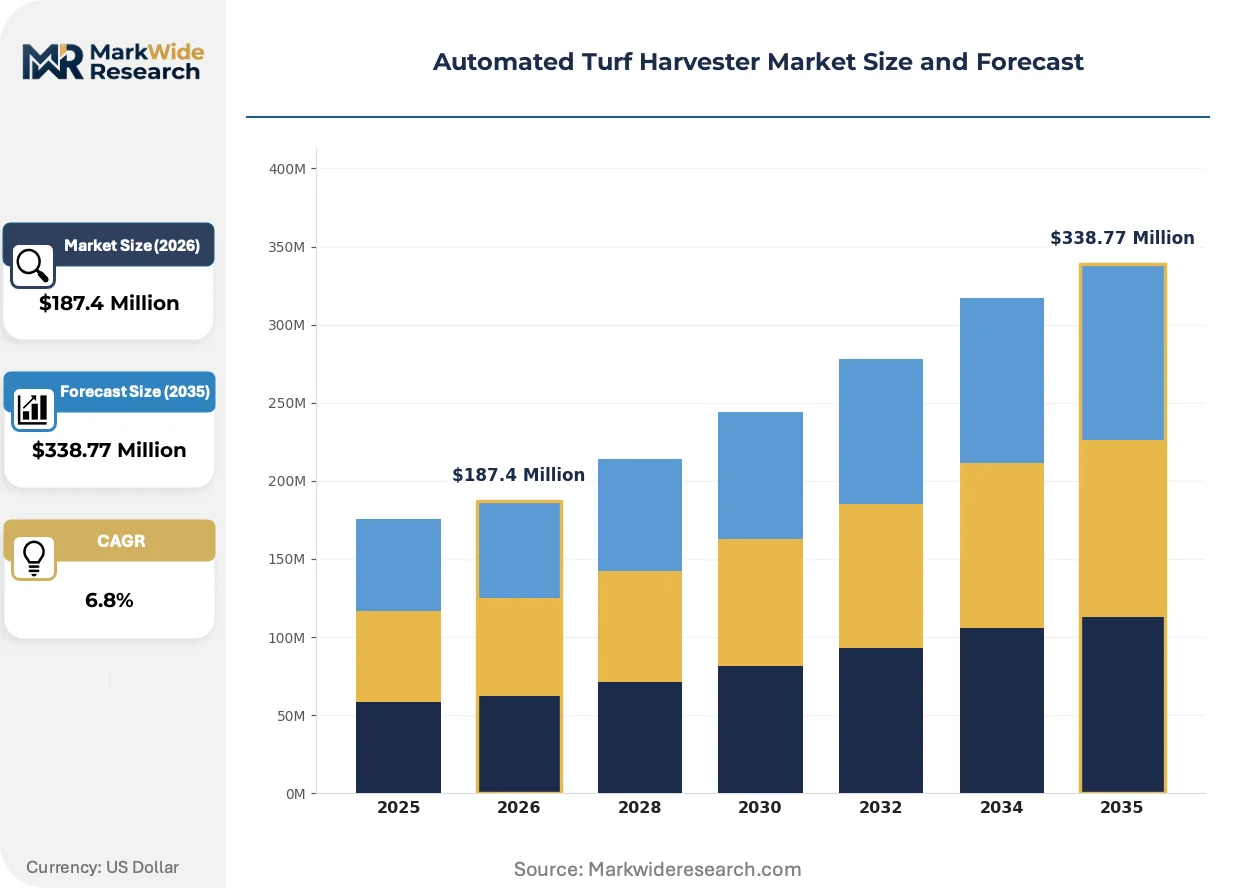
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Harvesters, Automatic Trimmers, Turf Collectors, Smart Mowers End User: Landscape Managers, Golf Courses, Sports Facilities, Residential Users Technology: GPS Navigation, AI Control, Sensor-Based Systems, Remote Monitoring Deployment: Ground-Based Systems, Autonomous Drones, Integrated Solutions, Hybrid Models |
| Companies Covered | FireFly Automatix, Inc., Kesmac Inc., KWMI Equipment, MAGNUM ENP, Trebro Manufacturing, Inc., Turf Tick Products B.V., Turf Star, Integrated Turf Solutions, Brookstone Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Turf Harvester Market Emerging Trajectories
Automation architectures are fragmenting into distinct performance tiers as sod producers demand specialized configurations for high-volume farms versus constrained residential sites.
GPS navigation systems with real-time kinematic correction are bifurcating the technology segment. High-volume sod farms in Georgia and Florida are adopting centimeter-level field mapping at accelerated rates. This precision is compressing overlap waste and fuel consumption while enabling variable-rate harvesting across heterogeneous soil zones.
OSHA agricultural equipment safety directives are mandating rollover protection structures and emergency stop protocols on new harvester designs. Manufacturers are redesigning operator stations and hydraulic lockout systems to preempt enforcement actions. The compliance burden falls heaviest on compact harvester lines where space constraints complicate protective structure integration.
Service contract unbundling is altering how sod producers acquire harvesting capability. Traditional bundled maintenance packages are giving way to à la carte remote diagnostics subscriptions and pay-per-use blade replacement programs. This shift is most pronounced among mid-scale operations in the southeastern United States seeking to convert fixed costs to variable spend during volatile turf demand cycles.
Automated Turf Harvester Market Segmentation
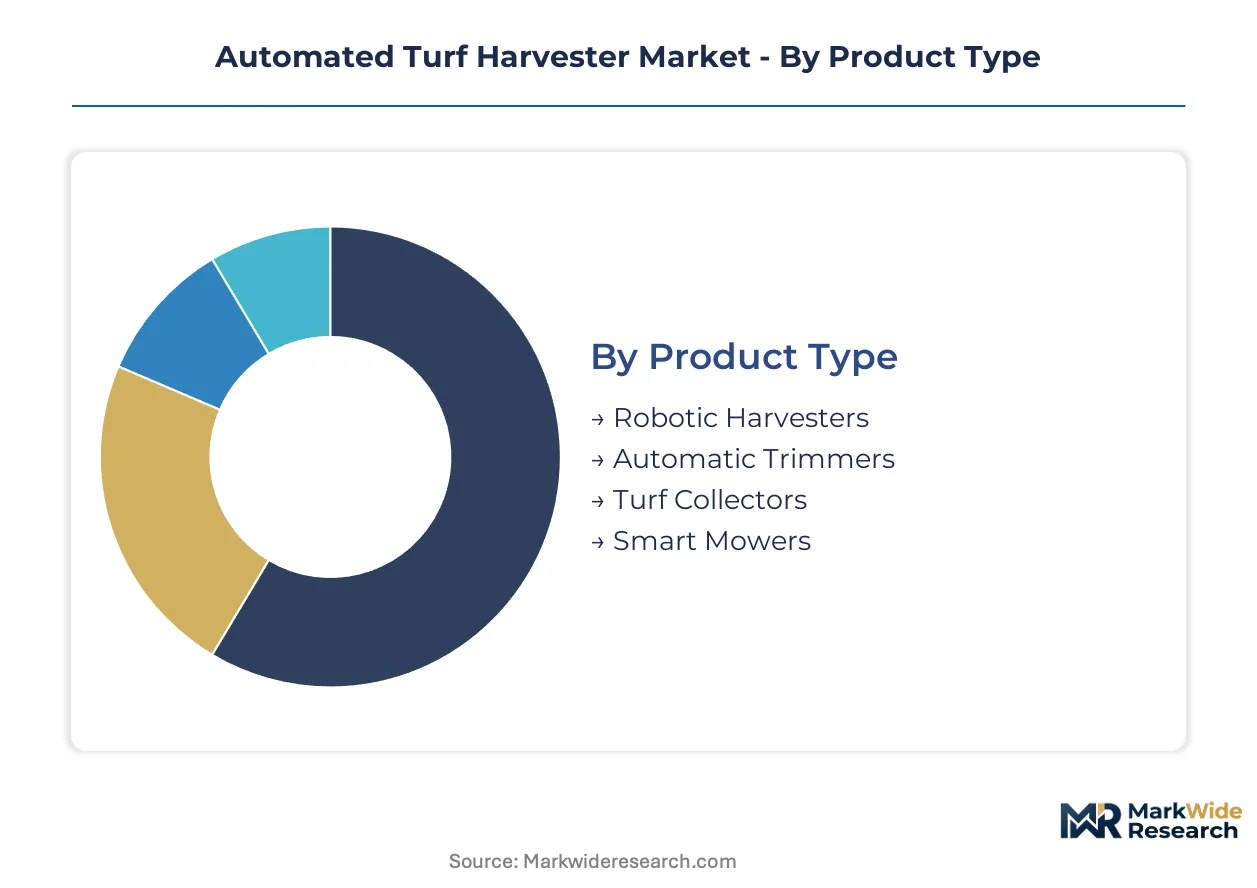
Automated turf harvester segmentation reveals divergent margin pools across hardware configurations, end-use applications, and control architectures. Understanding these splits enables capital deployment toward segments where technology premiums command sustainable pricing power.
Product Type:
Margin concentration sits with systems enabling unmanned overnight operation cycles where labor substitution economics prove most compelling.
- Robotic Harvesters:Self-propelled platforms execute cutting, rolling, and stacking sequences without operator presence. Demand clusters in Georgia and Florida sod farms seeking 24-hour production windows during peak warm-season grass growth periods.
- Automatic Trimmers:Precision blade assemblies maintain edge definitions and surface uniformity on established turf. Golf courses across the southeastern United States deploy these for fairway maintenance where hand-crew availability has collapsed.
- Turf Collectors:Vacuum-based debris removal systems clear clippings and organic matter from harvested strips. Municipal sports field contracts in constrained urban footprints drive specification requirements.
- Smart Mowers:GPS-guided cutting platforms occupy a mature adjacent position where recurring software subscriptions now capture value previously embedded in hardware margins.
Robotic Harvesters hold installed capacity. Smart Mowers is rotating up the share rankings through attach rate expansion.
End User:
Volume concentration tracks infrastructure investment cycles, with professional sports venue renovations commanding the largest per-unit deployments.
- Sports Facilities:Stadium and training ground operators require precision-cut sod volumes meeting FIFA and NFL surface certification standards. Professional venue renovations across the southeastern United States are compressing procurement timelines for GPS-guided harvesting platforms.
- Golf Courses:Private clubs and resort properties demand uniform turf quality for playable surfaces year-round. Florida and Georgia operations face acute seasonal labor shortages during overseeding transitions.
- Landscape Managers:Commercial contractors serving residential developments and corporate campuses seek compact configurations for constrained access points where full-scale machines cannot operate.
- Residential Users:High-net-worth property owners in estate markets deploy automated maintenance for grounds exceeding manual crew practical capacity.
Sports Facilities anchor current procurement volumes. Landscape Managers is climbing the fastest as mid-scale contractors automate.
Technology:
Control architecture differentiation determines service contract attach rates and aftermarket revenue durability.
- GPS Navigation:Real-time kinematic correction enables centimeter-level field mapping that eliminates overlap waste. High-volume sod farms in Georgia and Florida are adopting these systems at accelerated rates to compress fuel consumption across heterogeneous soil zones.
- AI Control:Machine learning modules optimize blade depth and cutting speed based on real-time turf density and moisture readings. Premium sports turf producers specify these for certification-grade surface consistency.
- Sensor-Based Systems:Proximity and terrain detection arrays prevent ground compaction and blade damage. Compact harvester lines integrate these where rollover protection structures constrain operator visibility.
- Remote Monitoring:Cloud-connected diagnostic platforms enable predictive maintenance and yield optimization analytics. Recurring subscription models are displacing traditional bundled service contracts among mid-scale southeastern operators.
GPS Navigation dominates current installed base. AI Control is gaining share fastest through premium sports turf specification.
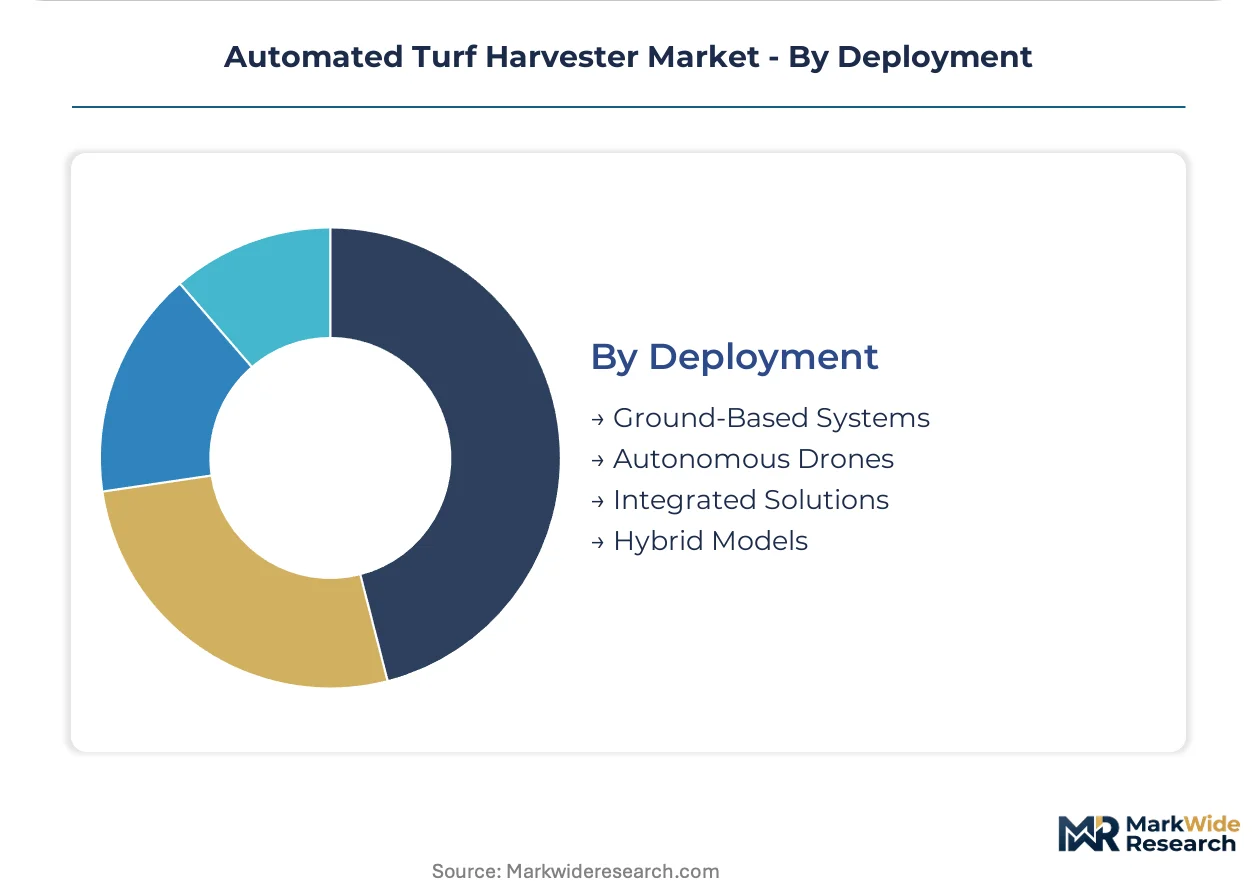
Deployment:
Physical system architecture shapes capital intensity and operational flexibility trade-offs across job site constraints.
- Ground-Based Systems:Conventional wheeled or tracked platforms handle standard sod farm and sports field applications. These configurations represent the reference design against which alternative architectures are evaluated.
- Autonomous Drones:Aerial platforms remain experimental for turf monitoring and limited maintenance tasks. Regulatory constraints from the FAA limit commercial deployment beyond visual line-of-sight operations.
- Integrated Solutions:Combined cutting, rolling, and stacking modules reduce labor touchpoints through single-pass operation. High-volume producers in Florida specify these for throughput maximization.
- Hybrid Models:Dual powertrain configurations bridge diesel and electric operation pending zero-emission mandate timelines. Manufacturers are positioning these for EPA Tier 4 Final compliance without full battery-electric infrastructure commitment.
Ground-Based Systems hold installed capacity. Integrated Solutions is rotating up the share rankings through labor substitution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions mandates and sod production economics anchor the United States as the dominant geography. Labor shortages across commercial turf operations are accelerating capital deployment toward autonomous harvesting platforms in concentrated warm-season grass belts.
United States
Professional stadium renovations and municipal field upgrades across Florida and Georgia are compressing procurement timelines for GPS-guided harvesting platforms. EPA Tier 4 Final compliance deadlines are forcing sod producers to retire diesel fleets ahead of schedule. The southeastern sod belt around Lake Okeechobee and coastal Georgia anchors high-volume warm-season grass production.
Canada
Golf course operators in Ontario and British Columbia face acute seasonal labor constraints during short growing windows. Health Canada's PMRA regulates pesticide application equipment used in turf maintenance adjacent to harvesting operations. The Niagara Peninsula and Lower Mainland Vancouver concentrate sod farm investment in automated roll-handling systems.
Germany
CE marking obligations and EU Green Deal machinery standards govern export market access for sports turf equipment. The country's national agricultural equipment safety regulator mandates rollover protection structures on grounds machinery entering European professional venues. Bavaria's sports infrastructure cluster around Munich drives specification requirements for precision-cut sod certification.
Netherlands
Randstad region landscape contractors seek compact harvester configurations for constrained urban job sites where full-scale machines cannot operate. ECHA chemical safety protocols affect hydraulic fluid specifications in equipment destined for municipal sports contracts. The country's greenhouse horticulture expertise is transferring to controlled-environment turf propagation automation.
Australia
New South Wales and Victoria sports councils are expanding automated turf maintenance programs amid water conservation mandates for grounds irrigation. The country's national agricultural equipment safety framework aligns with ISO standards for autonomous machinery deployment. Sydney's stadium precinct and Melbourne's sports park cluster command premium sod volumes meeting AFL and cricket surface certification standards.
Automated Turf Harvester Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with differentiation anchored in cutting automation depth and roll-handling integration. The market structure favors players controlling proprietary blade assembly designs and GPS calibration protocols. Three archetypes dominate: high-volume farm automation specialists, compact configuration providers for constrained sites, and integrated solution bundlers. Competitive moves concentrate on strategic partnerships for battery-electric powertrain development and geographic expansion through dealer network density.
Within the automation specialist tier, FireFly Automatix, Inc. and Kesmac Inc. exemplify contrasting approaches to labor substitution economics. FireFly Automatix anchors the high-volume sod farm segment through proprietary cutting and stacking automation, while Kesmac occupies a position defined by integrated roll-handling systems that compress labor touchpoints. KWMI Equipment represents the compact configuration archetype, serving residential and municipal job sites where access constraints exclude full-scale machinery.
| Leading Market Players |
|---|
| FireFly Automatix, Inc. |
| Kesmac Inc. |
| KWMI Equipment |
| MAGNUM ENP |
| Trebro Manufacturing, Inc. |
| Turf Tick Products B.V. |
| Turf Star |
| Integrated Turf Solutions |
| Brookstone Enterprises |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day blade assembly lead times concentrate pricing power with alloy steel suppliers serving Georgia and Florida sod farm clusters, while inventory carrying costs for hydraulic systems compress margins on compact harvester lines. This dynamic tethers equipment pricing to commodity volatility and regional production density.
Pricing Analysis
Georgia-to-Netherlands price spreads of 15-25% reflect CE marking compliance premiums and transatlantic logistics. Three-tier pricing structure across premium GPS-guided systems, standard sensor-based units, and economy manual-override configurations dominates transactional models. Price differentiation hinges on centimeter-level field mapping certification and bundled remote diagnostics subscriptions. Cost compression in the economy tier is intensifying because seasonal labor availability in Florida temporarily extends manual-equipment payback periods. Landscape managers exhibit highest price sensitivity due to constrained capital budgets, while professional sports facilities demonstrate lowest sensitivity given certification-grade surface requirements.
Supply Chain Analysis
Inventory cycles for precision blade assemblies stretch 45-75 days, exposing sod farm operators to alloy steel price swings from German and Japanese specialty mills. Manufacturing concentrates in the United States, Germany, and the Netherlands, with final assembly drawing from Taiwanese electronic components and South Korean hydraulic systems. Single-source vulnerability sits with GPS module suppliers facing semiconductor allocation constraints. Distribution runs through manufacturer-direct sales for high-volume farms and regional dealer networks for compact municipal configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet management software subscriptions are expanding at double the rate of hardware sales, converting fixed maintenance costs to recurring revenue streams for sod producers navigating volatile turf demand cycles.
For Market Incumbents: Secure proprietary blade calibration protocols against emerging robotic harvester entrants by deepening in-house production of precision cutting assemblies. Lock dealer service capacity in Georgia and Florida through exclusive technician certification programs, as rural diagnostic repair gaps threaten customer retention. Battery-electric powertrain development partnerships represent the critical R&D lever for EPA compliance beyond Tier 4 Final deadlines. For New Entrants and Emerging Players: Remote diagnostics subscription gaps among mid-scale southeastern operators offer immediate attach-rate expansion where FireFly Automatix and Kesmac under-serve. Municipal sports field contracts in constrained urban footprints present the most penetrable segment, as compact harvester specifications outpace incumbent product development. A hardware-as-a-service go-to-market angle bypasses capital-intensive procurement barriers for landscape contractors. For Investors and Strategic Acquirers: Long-term, this sits as a precision agriculture automation play because labor substitution economics in warm-season grass production are structurally irreversible. Target acquisition profiles center on compact configuration specialists with proprietary sensor integration and established municipal dealer relationships. Watch battery-electric harvester certification timelines as the inflection signal for powertrain transition capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Powertrain Development | EPA Tier 4 Final compliance positions manufacturers ahead of pending zero-emission mandates. |
| Dealer Service Network Expansion | Rural Georgia and Florida technician density gaps threaten customer retention for GPS-guided systems. |
| Fleet Management Software Launch | Recurring subscription models capture value migrating from hardware margins toward predictive analytics. |
| Compact Harvester Product Line Extension | Municipal job site constraints exclude full-scale machines, creating white-space for specialized configurations. |
| CE Marking Certification Investment | EU Green Deal machinery standards unlock European sports turf market access for North American producers. |
Methodological Framework
Operator-level perspectives from sod farm equipment managers, municipal sports field procurement officers, precision agriculture technicians, and regional dealer service heads anchored the qualitative base. These primary insights combined with secondary validation from EPA regulatory filings, EU machinery directive documentation, SEC equipment manufacturer disclosures, and agricultural trade association production surveys. Bottom-up unit economics from Georgia and Florida sod operations triangulated against top-down market sizing from machinery shipment data.
Sensitivity analysis across steel price volatility bands, labor availability scenarios, and battery-electric adoption curves shaped the analytical framework. Segmentation dimensions modeled include product architecture, control technology tier, end-use application, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and autonomous platform penetration assumptions. Forecast inputs incorporated EPA compliance deadline phasing and EU Green Deal implementation timelines.
Forecasts assume regulatory continuity in EPA Tier 4 Final and EU Green Deal machinery regimes; material policy shifts would require re-modeling. Outputs reflect assumptions about skilled operator scarcity persistence and alloy steel supply stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Rice Mill Machine Market