
 Wet Fertilizer Spreaders Market | 2026-2036
Wet Fertilizer Spreaders Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Fertilizer Spreaders Market Outlook
Premium-grade stainless steel hopper construction is bifurcating the competitive landscape as operators demand corrosion resistance for liquid urea-ammonium nitrate blends. Deere & Company leverages its integrated precision agriculture platform to bundle spreaders with variable-rate control systems. AGCO Corporation anchors its position through the Challenger and Fendt lines with dedicated wet application toolbars. Kuhn Group differentiates via European-designed centrifugal disc systems adapted for North American tank mixes.
Wet fertilizer spreaders are self-propelled, towed, or mounted machines engineered to distribute liquid or slurry nutrient solutions across calibrated swath widths, typically employing centrifugal discs, boom systems, or drip-line manifolds with flow rates regulated by pump-controlled metering valves. Trailer-mounted units dominate volume sales among mid-size agricultural cooperatives seeking seasonal equipment sharing across multiple member farms. Self-propelled platforms represent the fastest-expanding segment as high-acreage operators in the Corn Belt pursue autonomous-ready chassis with integrated ISOBUS task controllers. Tow-behind configurations retain share among landscaping and golf course end users prioritizing compact tractor compatibility over field capacity.
EPA agricultural engine emissions regulations under Tier 4 Final standards shape powertrain configurations for self-propelled units, while USDA NRCS Environmental Quality Incentives Program cost-share provisions accelerate adoption of precision application technologies that reduce nutrient runoff. State-level 4R Nutrient Stewardship frameworks in Illinois, Iowa, and Minnesota mandate documented application rates, creating compliance-driven replacement demand for calibrated equipment. Stakeholders must monitor evolving carbon intensity scoring for fertilizer production as downstream Scope 3 accounting begins influencing equipment procurement specifications.
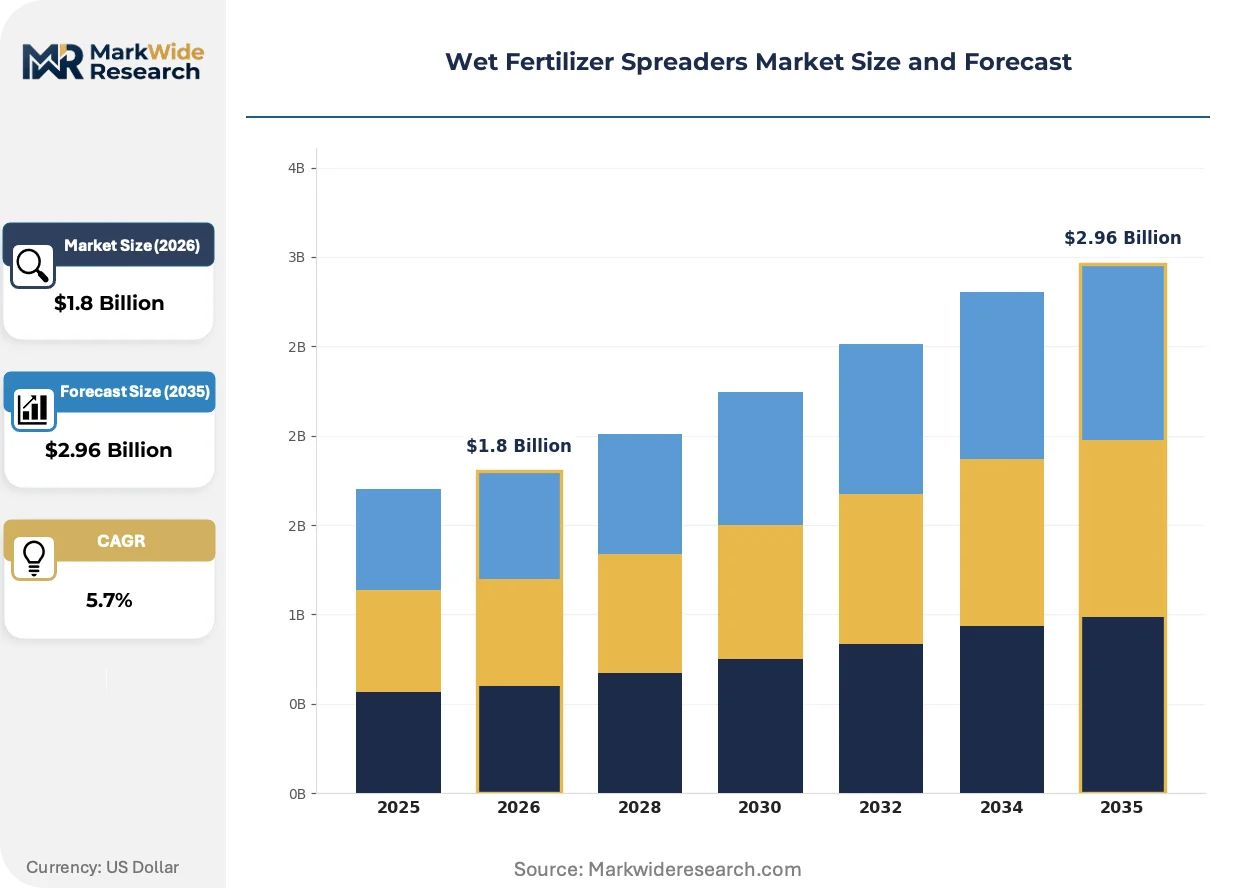
Market Dynamics
Precision agriculture adoption is compressing equipment replacement cycles across large-scale commercial farming operations, as variable-rate application systems displace fixed-rate legacy units in the Corn Belt and Midwestern grain belt states.
Growth Catalysts
- 4R Nutrient Stewardship frameworks:State-level mandates in Illinois, Iowa, and Minnesota require documented application rates, creating compliance-driven replacement demand for calibrated wet fertilizer spreaders with flow-controlled metering valves.
- Liquid urea-ammonium nitrate blends:Corn-soybean rotations in the Midwestern grain belt require intensive nutrient programs that favor wet application systems over dry spreaders for uniform distribution.
- USDA NRCS Environmental Quality Incentives Program:Cost-share provisions accelerate farmer adoption of precision application technologies that reduce nutrient runoff into watersheds.
Market Restraints
- Stainless steel input costs:Premium-grade hopper construction depends on corrosion-resistant alloys, exposing manufacturers to commodity price volatility in nickel and chromium markets.
- Tier 4 Final compliance costs:EPA agricultural engine emissions regulations add engineering complexity and powertrain expense to self-propelled platform development.
- Seasonal utilization rates:Trailer-mounted units face depreciation pressure from concentrated spring and fall application windows, limiting return on investment for mid-size cooperatives.
Strategic Opportunities
- Autonomous-ready chassis integration:High-acreage operators in Iowa and Illinois are specifying ISOBUS task controllers compatible with emerging autonomous tractor platforms.
- Golf course and landscaping segments:Compact tow-behind configurations retain growth potential among turf management professionals prioritizing tractor compatibility over field capacity.
- Carbon intensity scoring alignment:Downstream Scope 3 accounting for fertilizer production is beginning to influence equipment procurement specifications among sustainability-focused grain buyers.
Industry Challenges
- ISOBUS certification timelines:Manufacturers face extended validation periods for task controller compatibility across tractor OEM proprietary protocols.
- Precision agriculture technician shortage:Variable-rate system calibration and telemetry troubleshooting require specialized skill sets scarce in rural equipment dealer networks.
- Legacy fleet integration friction:Retrofitting flow-controlled metering valves onto existing tank architectures creates hydraulic and electrical compatibility complications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Fertilizer Spreaders Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trailer-Mounted, Truck-Mounted, Self-Propelled, Tow-Behind Application: Agriculture, Landscaping, Golf Courses, Recreational Areas End User: Farmers, Landscapers, Groundskeepers, Agricultural Cooperatives Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., Kubota Corporation, Kuhn Group, Amazone GmbH, Claas KGaA mbH, Mahindra & Mahindra Ltd., Adams Fertilizer Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Fertilizer Spreaders Market Strategic Shifts
Electronics and sensor architectures are reshaping competitive positioning in wet fertilizer spreaders, as real-time nutrient mapping and closed-loop control systems displace open-loop manual calibration.
Ultrasonic flow sensors are miniaturizing to replace mechanical turbine meters in pump-controlled metering valves. Large-scale operators in Minnesota and Illinois are specifying these solid-state alternatives for immunity to slurry viscosity variations. The technology is miniaturizing installation footprints, enabling dual-stream independent zone control within compact toolbar configurations previously limited to single-manifold designs.
EPA Tier 4 Final standards are forcing powertrain redesigns for self-propelled chassis above 25 horsepower. Engine manufacturers are integrating selective catalytic reduction and diesel particulate filters into compact agricultural blocks. Self-propelled platform OEMs absorb the steepest compliance burden, while tow-behind and mounted segments exploit exempted horsepower thresholds.
Cooperative equipment sharing arrangements are fragmenting traditional dealer-centric procurement patterns. Mid-size agricultural cooperatives in the Corn Belt are pooling capital for trailer-mounted wet spreader acquisitions with seasonal rotation schedules. This behavior concentrates demand into multi-unit fleet transactions, compressing margins for manufacturers accustomed to single-unit retail pricing.
Wet Fertilizer Spreaders Market Segmentation
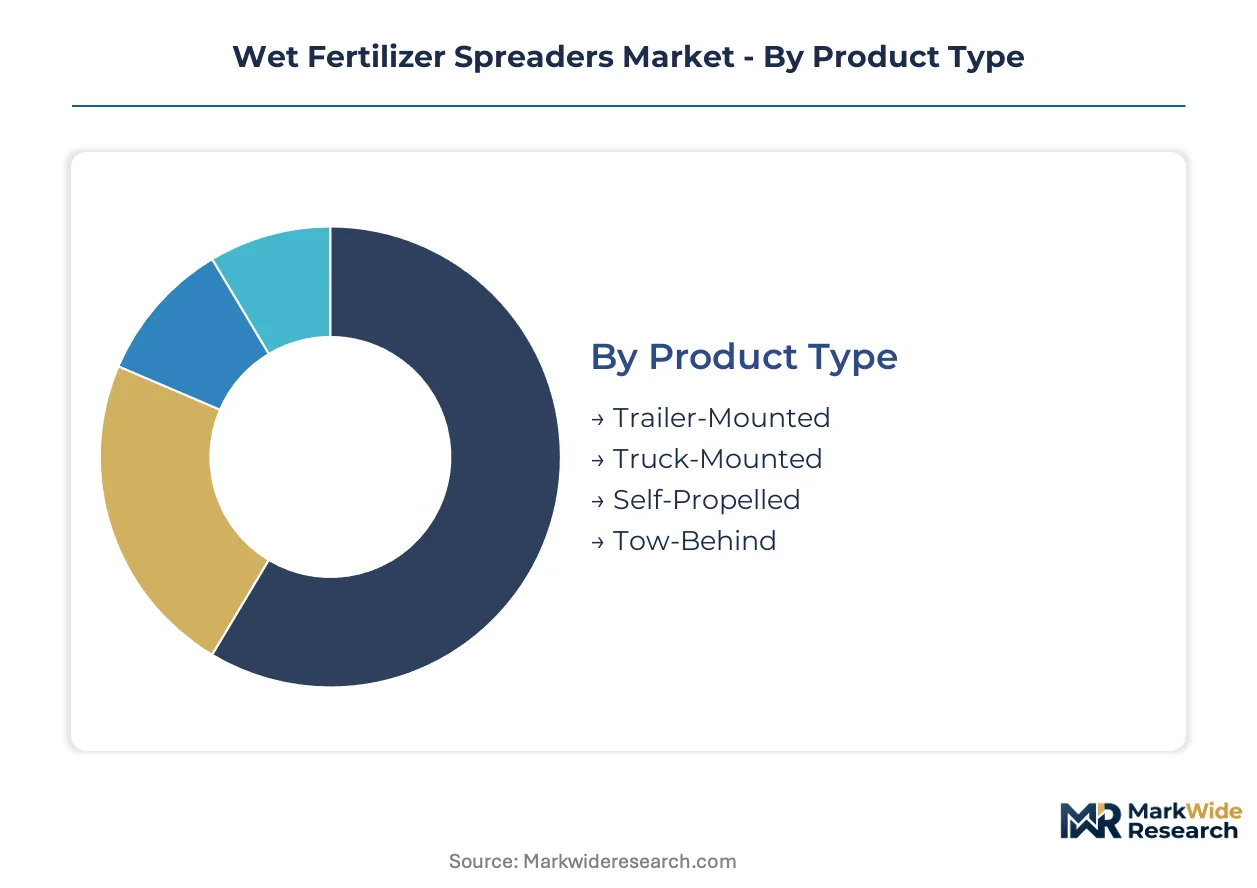
Wet fertilizer spreader procurement patterns diverge sharply across equipment configurations and end-use contexts. Substitution pressures from precision agriculture platforms and autonomous-ready chassis are fragmenting traditional category boundaries.
Product Type:
Trailer-mounted and self-propelled platforms face divergent substitution threats from autonomous tractor integration and cooperative equipment-sharing models.
- Trailer-Mounted:Modular tank architectures with centrifugal disc or boom manifold configurations dominate seasonal nutrient application across Iowa and Illinois corn-soybean operations. Mid-size agricultural cooperatives leverage shared ownership models to amortize capital costs across spring and fall windows, though depreciation pressure from limited annual utilization constrains replacement frequency.
- Self-Propelled:Integrated chassis designs with ISOBUS task controllers and variable-rate metering systems command premium positioning among high-acreage operators pursuing autonomous-ready specifications. EPA Tier 4 Final compliance adds engineering complexity and selective catalytic reduction costs, compressing margins for platform OEMs while accelerating displacement of tow-behind alternatives in the Corn Belt.
- Truck-Mounted:Highway-speed tank systems serve custom applicator fleets with rapid field-to-field mobility requirements.
- Tow-Behind:Compact configurations retain viability among landscaping professionals prioritizing sub-50 horsepower tractor compatibility over swath capacity.
Trailer-mounted configurations retain volume leadership; self-propelled platforms hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive agricultural deployments from maintenance-focused turf management segments.
- Agriculture:Large-scale commercial farming operations in the Midwestern grain belt drive specification intensity for corrosion-resistant stainless steel hoppers calibrated to liquid urea-ammonium nitrate blends. USDA NRCS Environmental Quality Incentives Program cost-share provisions accelerate precision application adoption, though seasonal concentration limits equipment utilization rates.
- Landscaping:Municipal and commercial turf maintenance programs favor compact tow-behind units with simplified hydraulic requirements. Golf course superintendents specify dedicated boom systems for fairway and rough zone differentiation, creating niche demand for dual-stream independent zone control previously limited to agricultural toolbars.
- Golf Courses:Precision nutrient management mandates from state-level watershed protection frameworks elevate calibration requirements for surface water adjacent properties.
- Recreational Areas:Parks departments and sports field operators prioritize equipment durability over application sophistication.
Agricultural applications dominate revenue concentration; golf course deployments are gaining share fastest.
End User:
Customer type fragmentation separates enterprise-scale cooperatives from individual operator procurement patterns.
- Farmers:Owner-operators above 2,000 cultivated acres specify self-propelled platforms with integrated telemetry and real-time nutrient mapping capabilities. Illinois and Minnesota 4R Nutrient Stewardship frameworks mandate documented application rates, creating compliance-driven replacement cycles for calibrated flow-controlled systems.
- Agricultural Cooperatives:Pooled capital structures enable multi-unit fleet transactions for trailer-mounted acquisitions with seasonal rotation schedules across member farms. This procurement behavior compresses manufacturer margins accustomed to single-unit retail pricing while concentrating demand into concentrated spring purchasing windows.
- Landscapers:Commercial turf maintenance contractors prioritize equipment transportability and rapid deployment.
- Groundskeepers:Institutional facility managers balance capital constraints against regulatory documentation requirements.
Agricultural cooperatives retain volume leadership; commercial farmers hold the steepest expansion curve.
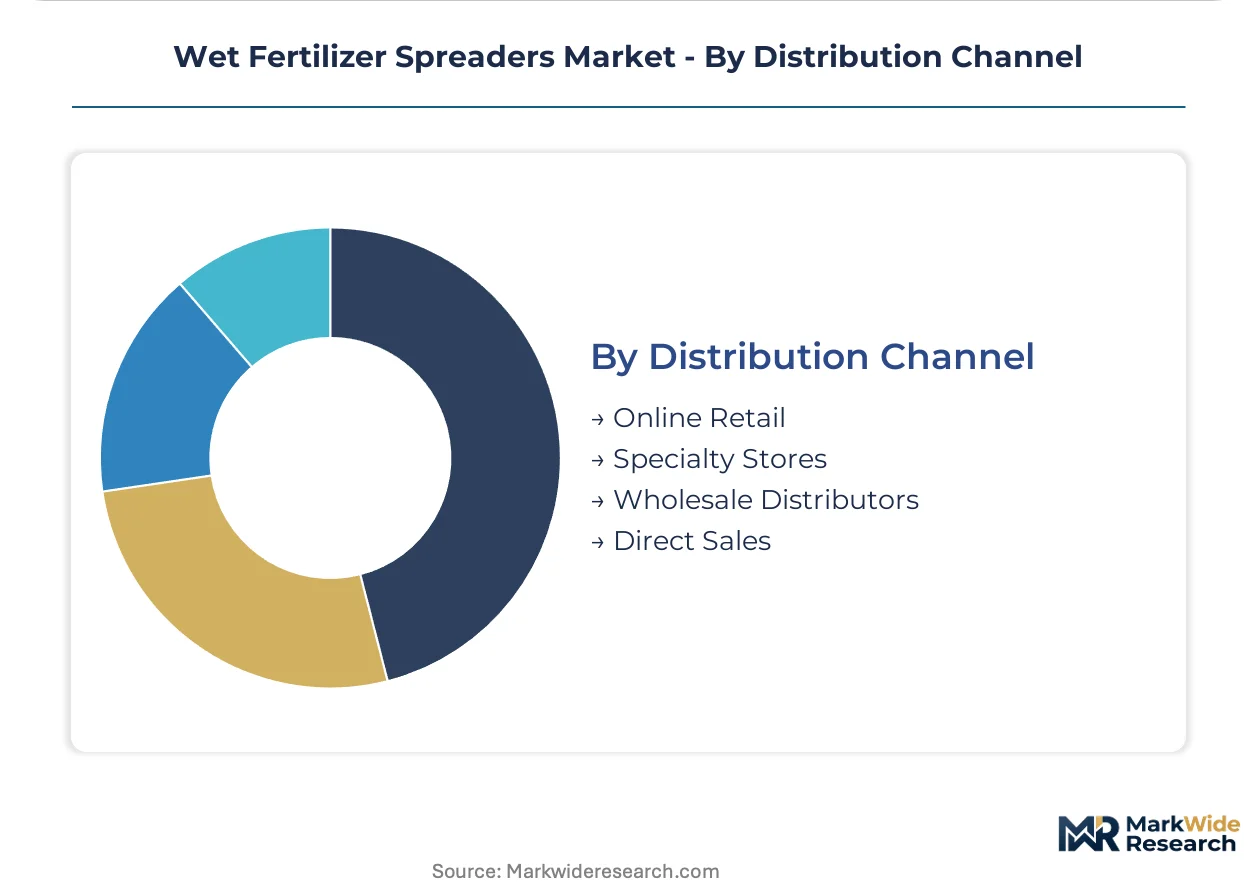
Distribution Channel:
Supply concentration among wholesale distributors shapes pricing transparency and service bundling across rural equipment networks.
- Wholesale Distributors:Regional dealer networks anchor wet spreader procurement through bundled financing, seasonal maintenance contracts, and ISOBUS certification support. Precision agriculture technician scarcity in rural markets elevates distributor technical service capabilities as a competitive differentiator beyond equipment specifications.
- Direct Sales:OEM captive channels serve high-volume cooperative fleet transactions with customized tank configurations and extended warranty structures. Self-propelled platform manufacturers leverage direct relationships to specify autonomous-ready chassis architectures ahead of general dealer availability.
- Specialty Stores:Local agricultural equipment retailers focus on tow-behind and compact trailer-mounted segments.
- Online Retail:E-commerce penetration remains limited to replacement parts and consumable accessories.
Wholesale distributors retain volume leadership; direct sales channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wet fertilizer spreader manufacturing clusters heavily in the Midwestern United States, where proximity to corn-soybean demand centers and established agricultural equipment supply chains create procurement advantages for regional fabricators.
United States
Illinois, Iowa, and Minnesota corn-soybean rotations drive specification intensity for stainless steel hoppers calibrated to liquid urea-ammonium nitrate blends. EPA Tier 4 Final emissions standards force selective catalytic retrofits on self-propelled chassis above 25 horsepower. Equipment dealerships in Des Moines and Peoria anchor regional distribution networks for precision application systems.
Brazil
Cerrado expansion and double-cropping intensification in Mato Grosso and Goiás generate demand for high-capacity trailer-mounted units with corrosion-resistant tank architectures. ANVISA agrochemical handling regulations intersect with state-level environmental licensing for nutrient application near watersheds. São Paulo-based cooperatives pool capital for seasonal equipment sharing across soybean-corn rotations.
Germany
Baden-Württemberg and Lower Saxony machinery clusters supply centrifugal disc systems adapted for European tank mix formulations. REACH chemical registration requirements shape material specifications for pump-controlled metering valves. Fendt and Claas manufacturing footprints in Marktoberdorf and Harsewinkel anchor precision agriculture R&D integration.
Canada
Prairie Provinces wheat-canola rotations in Saskatchewan and Alberta favor tow-behind configurations compatible with existing tractor fleets. Health Canada PMRA regulates fertilizer-pesticide co-application protocols affecting boom system specifications. Winnipeg and Regina dealerships concentrate seasonal demand into concentrated spring procurement windows.
Australia
Western Australia wheatbelt and New South Wales irrigation districts specify robust chassis for broad-acre dryland application. TGA-equivalent state agricultural departments enforce buffer zone mandates for surface water protection. Toowoomba and Perth equipment networks service dispersed farm operations with mobile technician support.
Wet Fertilizer Spreaders Market Competitive Environment
Concentration sits with diversified agricultural machinery conglomerates that leverage integrated precision agriculture platforms to bundle spreaders with variable-rate control systems. The competitive structure tiers across three archetypes: full-line OEMs with captive chassis production, specialized implement manufacturers focused on application toolbars, and regional fabricators serving cooperative fleet procurement. Dominant competitive moves include ISOBUS certification racing for task controller compatibility and stainless steel supply chain backward integration to hedge nickel and chromium price volatility.
Among the full-line OEM tier, Deere & Company and AGCO Corporation exemplify platform-integrated positioning, while Kuhn Group occupies a specialist position in European-designed centrifugal disc adaptations. These three anchors represent divergent geographic and technological positioning strategies without overlapping segment focus. Regional fabricators such as Adams Fertilizer Equipment sit within the cooperative-serving tier, emphasizing modular tank architectures for seasonal equipment sharing arrangements.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Kubota Corporation |
| Kuhn Group |
| Amazone GmbH |
| Claas KGaA mbH |
| Mahindra & Mahindra Ltd. |
| Adams Fertilizer Equipment |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 4 Final emissions certification gates both supplier qualification and price differentiation simultaneously, as only manufacturers with selective catalytic reduction engineering capabilities can access premium self-propelled platform tiers while commodity tank fabricators remain trapped in trailer-mounted price bands.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across wet fertilizer spreader configurations. Three-tier pricing stratifies across autonomous-ready chassis, precision-calibrated trailers, and basic tow-behind units. Stainless steel alloy grade and ISOBUS certification level separate premium from standard positioning. Cost compression in trailer-mounted segments intensifies as cooperative fleet purchasing aggregates demand. Mid-size agricultural cooperatives exhibit highest price sensitivity; high-acreage Corn Belt operators prioritize specification over cost.
Supply Chain Analysis
Just-in-time stainless steel procurement dominates tier-one manufacturing, though nickel price volatility pushes select fabricators toward strategic six-month alloy stockpiles. Supply concentrates in the United States, Germany, and Brazil. Production draws from corrosion-resistant steel mills, hydraulic component suppliers, and Tier 4 Final engine manufacturers. Single-source vulnerability sits with European-sourced centrifugal disc systems. Distribution runs through regional dealer networks with bundled service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wet fertilizer spreader markets sustain defensive moats through regulatory entrenchment, as EPA emissions certification and state-level 4R Nutrient Stewardship compliance create multi-year switching costs for installed precision agriculture platforms.
For Market Incumbents: Consolidate ISOBUS certification leadership through accelerated task controller validation timelines. Acquire regional stainless steel fabrication capacity to hedge nickel and chromium commodity exposure. Autonomous-ready chassis integration represents the critical capability gap; defend against emerging precision agriculture software entrants by embedding telemetry subscription bundles into equipment financing. For New Entrants and Emerging Players: Precision agriculture technician scarcity in rural dealer networks offers service-layer white space for independent calibration and telemetry troubleshooting providers. Golf course boom system retrofitting remains under-penetrated relative to agricultural toolbar saturation. Pursue OEM-agnostic ISOBUS compatibility certification as the primary go-to-market wedge against proprietary dealer networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across self-propelled platform development due to Tier 4 Final compliance and autonomous chassis R&D. Five-to-ten-year viability favors manufacturers with backward integration into stainless steel supply and captive precision agriculture software stacks. Acquisition targets should display established 4R Nutrient Stewardship compliance documentation capabilities. Monitor carbon intensity scoring adoption among grain buyers as the inflection signal for sustainability-linked equipment procurement.| Strategic Initiative | Industry Significance |
|---|---|
| ISOBUS Certification Acceleration | Task controller compatibility locks in dealer channel loyalty across Illinois and Iowa farm operations. |
| Stainless Steel Backward Integration | Captive alloy supply hedges nickel price volatility affecting premium hopper manufacturing costs. |
| Autonomous-Ready Chassis Development | ISOBUS architecture positions platforms for integration with emerging tractor automation protocols. |
| Precision Agriculture Technician Training | Dealer service capability scarcity elevates technical support as a competitive differentiator beyond hardware. |
| Carbon Intensity Scoring Alignment | Scope 3 accounting requirements from sustainability-focused grain buyers reshape equipment specification criteria. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of USDA NRCS program documentation, EPA emissions filings, state nutrient stewardship regulations, and agricultural equipment trade data. Primary interviews engaged precision agriculture directors at equipment dealerships, plant managers at stainless steel fabrication facilities, procurement leads at agricultural cooperatives, and aftermarket service heads at regional distributor networks. Secondary validation drew from SEC 10-K disclosures, customs import records, and cooperative capital expenditure reports. Bottom-up unit shipment estimates triangulate against top-down addressable acreage calculations.
Segmentation dimensions modeled include equipment configuration type, application context, end-user scale category, and distribution channel structure across the projection horizon. CAGRs derive from regression analysis of historical replacement cycle compression and precision agriculture adoption curves. Industry-specific forecast inputs incorporate EPA Tier 4 Final compliance cost trajectories and 4R Nutrient Stewardship mandate expansion timelines.
Underlying assumptions cover sustained corn-soybean rotation intensity in the Midwestern grain belt, with deviation risk concentrated in autonomous tractor platform commercialization delays and stainless steel alloy price spikes. Revision becomes warranted when carbon intensity scoring adoption crosses thresholds triggering accelerated equipment replacement specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Electric Pruning Shears Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Flexible Silos Market