
 Lawn Shredder Market | 2026-2036
Lawn Shredder Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn Shredder Market Analytics
Equipment leasing and rental financing is rewriting competitive access in the lawn shredder sector, allowing smaller landscaping contractors to deploy commercial-grade machines without capital purchase. Husqvarna Group leverages its captive finance arm to anchor fleet turnover cycles among municipal buyers. Stihl AG competes through specialized dealer networks that control service density in German-speaking European markets. MTD Products sustains volume leadership via mass retail channel positioning across North American home improvement chains.
A lawn shredder is a mechanical device designed to reduce organic yard debris—branches, leaves, and grass clippings—into smaller particles through cutting, grinding, or impact action, typically employing hardened steel blades or hammermill drums rotating at 2,000–3,600 RPM to achieve particle sizes suitable for composting or mulch application. Gas-powered shredders still dominate revenue pools in commercial settings where runtime and torque requirements exceed battery capacity, though electric shredders are capturing fastest growth in residential segments as lithium-ion energy density improves. Blade technology occupies the mature core of the installed base, while hammermill technology differentiates premium commercial units through superior processing of hardwood debris. Municipalities represent a concentrated end-user segment where procurement specifications increasingly mandate decibel limits and emission thresholds.
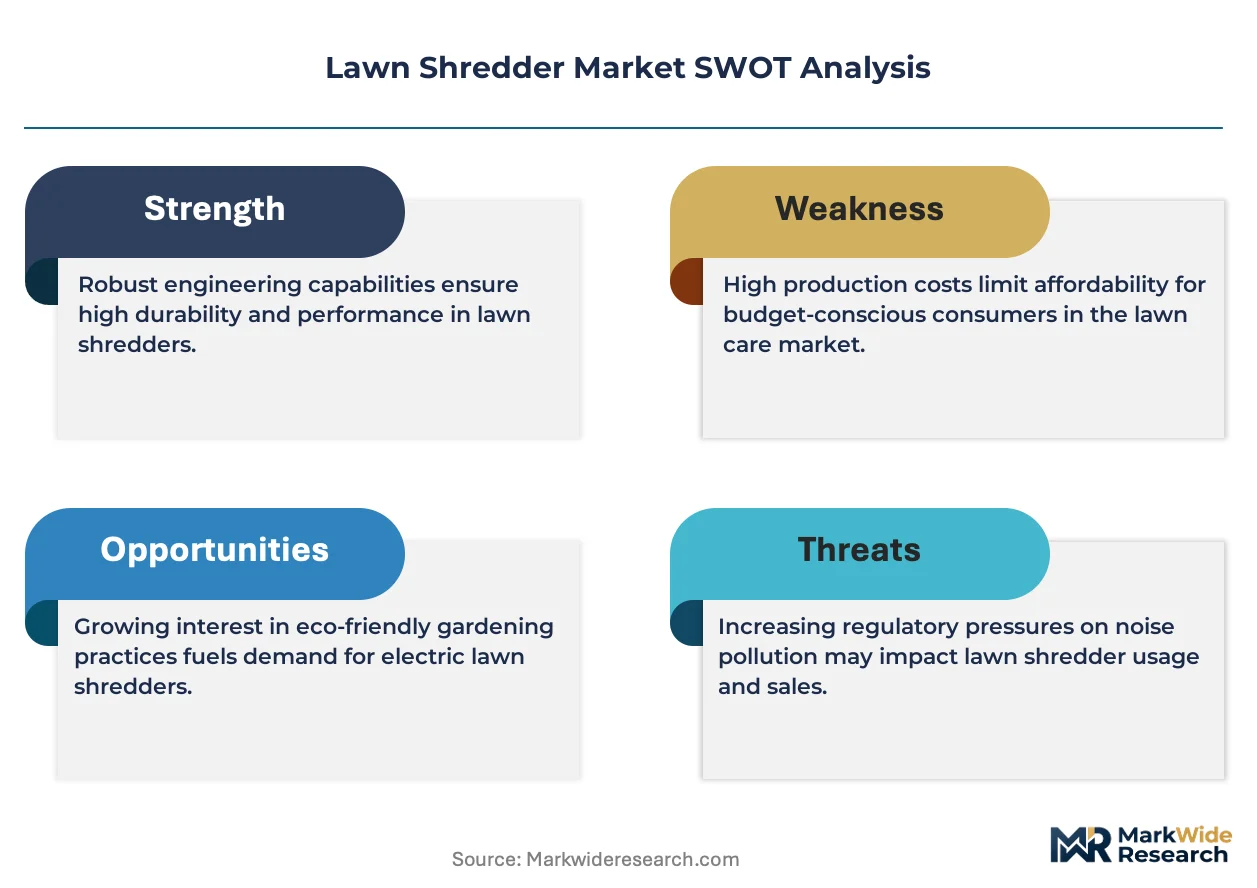
EPA small off-road engine standards and California Air Resources Board (CARB) tailpipe regulations are forcing gas-powered shredder redesigns or electrification pivots, with OSHA noise exposure limits additionally shaping operator cabin and shielding specifications. The EU Machinery Directive and CE marking requirements govern export access for North American and Asian manufacturers serving European commercial landscapers. Stakeholders must monitor battery recycling infrastructure development and local composting mandate expansions, as these determine whether shredder output qualifies for municipal organic waste streams and thus influences replacement demand timing.
Market Dynamics
EPA small off-road engine standards and California Air Resources Board tailpipe regulations are forcing gas-powered shredder redesigns or electrification pivots across the commercial equipment landscape. Equipment leasing and rental financing is rewriting competitive access in the sector, allowing smaller landscaping contractors to deploy commercial-grade machines without capital purchase.
Growth Catalysts
- EPA Emissions Compliance:Stricter small off-road engine standards are accelerating manufacturer investment in electric drivetrain development, expanding the addressable market for zero-emission equipment in municipal procurement.
- Composting Mandate Expansion:Local organic waste stream regulations in suburban municipalities across the United States Southeast and Midwest are creating replacement demand timing tied to shredder output qualification standards.
- Lithium-Ion Energy Density:Battery chemistry improvements are enabling electric shredders to capture residential segment growth previously blocked by runtime and torque limitations.
Market Restraints
- Gas-Powered Redesign Costs:EPA and CARB compliance investments are compressing margins on legacy engine platforms before electric volumes achieve scale economies.
- Battery Recycling Infrastructure:Underdeveloped end-of-life processing networks for lithium-ion cells create regulatory liability exposure and limit circular economy claims in municipal bidding.
- Hardwood Processing Limitations:Blade-based systems face technical constraints with dense branch material, forcing commercial buyers toward premium hammermill configurations at higher price points.
Strategic Opportunities
- Equipment-as-a-Service Models:Captive finance arms can anchor fleet turnover cycles among municipal buyers through usage-based contracts rather than capital sales.
- Dealer Network Service Density:Specialized distribution controlling maintenance proximity in concentrated geographic markets creates switching costs against mass retail competitors.
- OSHA Noise Compliance:Decibel limit mandates in procurement specifications are opening premium tiers for shielded operator cabins and low-RPM drivetrain configurations.
Industry Challenges
- Small Engine Technician Shortage:The transition from mechanical to electromechanical systems requires retraining dealer service networks at pace with product launches.
- CE Marking Complexity:EU Machinery Directive compliance timelines for North American exporters create certification bottlenecks when parallel development tracks diverge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn Shredder Market |
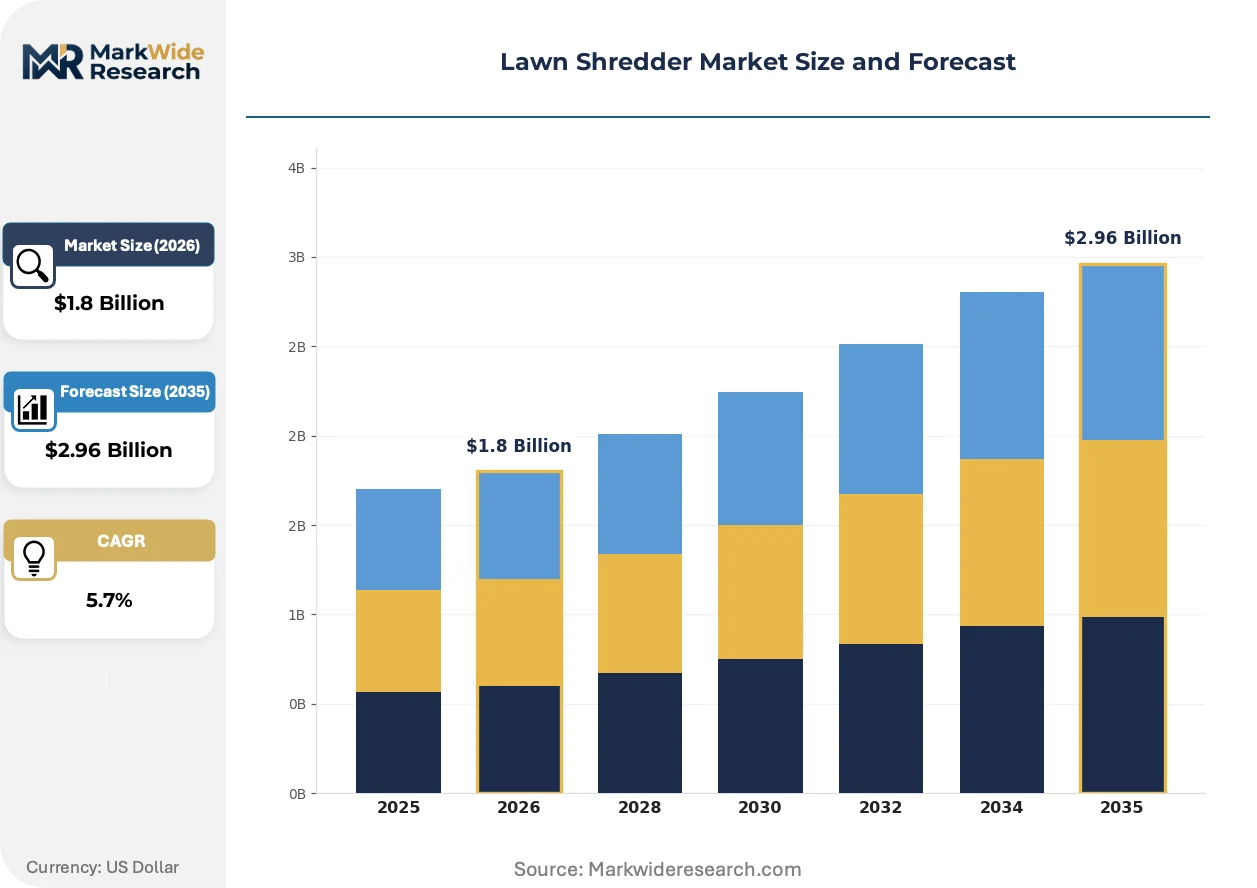
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
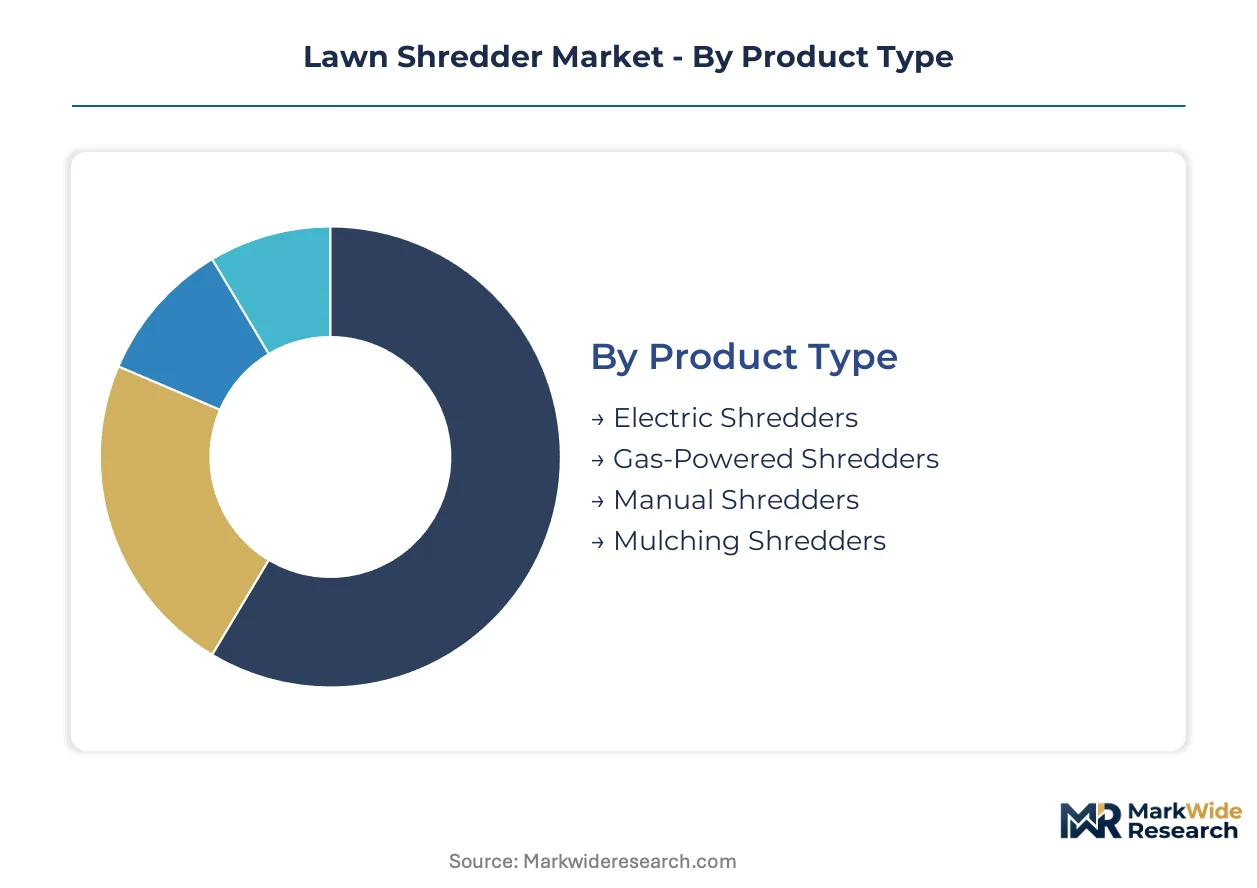
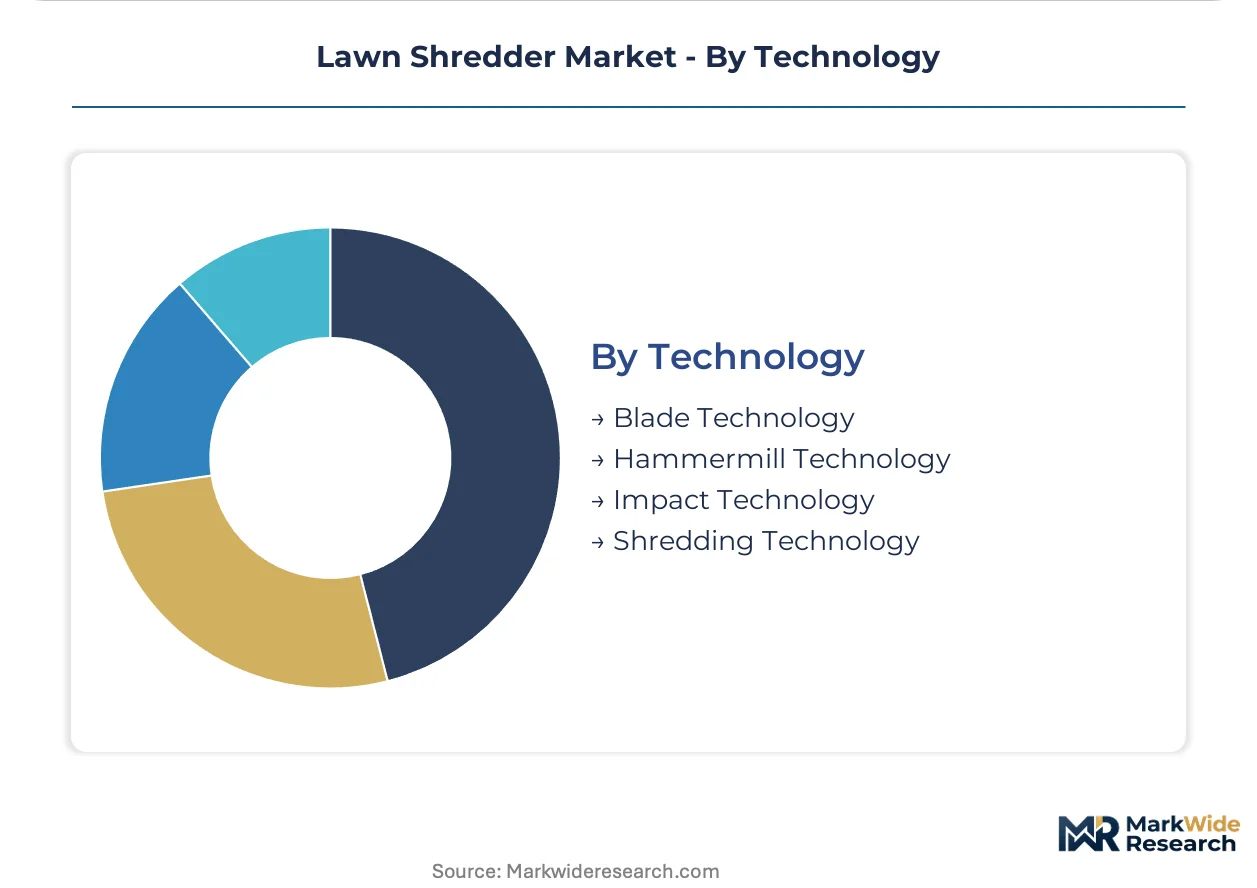
| Segmentation | Product Type: Electric Shredders, Gas-Powered Shredders, Manual Shredders, Mulching Shredders End User: Residential Users, Commercial Landscapers, Municipalities, Garden Centers Size: Small, Medium, Large, Extra Large Technology: Blade Technology, Hammermill Technology, Impact Technology, Shredding Technology |
| Companies Covered | MTD Products, Vermeer, Bandit, Stihl AG, Husqvarna Group, Champion Power Equipment, Patriot Products, Earthquake, Troy-Bilt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn Shredder Market Evolving Landscape
Telematics integration and predictive maintenance architectures are virtualizing the traditional equipment ownership experience. Three developments are compressing competitive differentiation cycles across the value chain.
Brushless DC motor controllers paired with lithium-ion battery management systems are virtualizing the torque delivery profiles previously locked to internal combustion engine characteristics. Commercial landscaping fleets in the United States are piloting these configurations for municipal contracts with strict emission thresholds. The technology is virtualizing maintenance scheduling through real-time vibration monitoring and automated parts replacement triggers.
The EU Machinery Directive and CE marking requirements are governing export access for North American manufacturers serving European commercial landscapers. Compliance documentation burdens are favoring larger producers with dedicated regulatory affairs functions. German-speaking European markets are responding through specialized dealer networks that bundle certification support with equipment sales.
Leasing penetration among smaller landscaping contractors is displacing traditional capital purchase patterns in equipment acquisition. Mass retail channels across North American home improvement chains are unbundling after-sales service from initial transactions. Suburban municipalities in the United States Southeast are concentrating procurement through cooperative purchasing agreements that favor standardized specifications over brand loyalty.
Lawn Shredder Market Segmentation
Equipment replacement cycles vary dramatically across lawn shredder segments, with commercial-grade gas units turning over every 5-7 years while residential electric models face 10-12 year lifespans. Procurement patterns in municipal and commercial channels concentrate demand in predictable replacement windows that manufacturers align with product launch calendars.
Product Type:
Replacement velocity separates this category, with commercial gas platforms cycling fastest due to runtime intensity while residential electric units stretch replacement intervals through lighter duty cycles.
- Electric Shredders:Brushless DC motor configurations paired with lithium-ion battery management systems deliver torque profiles previously locked to internal combustion engines. Demand concentrates in United States suburban municipalities where EPA emission thresholds and OSHA noise exposure limits restrict gas-powered alternatives on municipal contracts.
- Gas-Powered Shredders:Two-stroke and four-stroke small off-road engines still dominate commercial revenue pools where runtime requirements exceed current battery energy density. Fleet turnover concentrates among landscaping contractors handling large municipal contracts across the United States Southeast and Midwest.
- Manual Shredders:Hand-cranked or foot-operated mechanical units serve niche applications with minimal debris volumes.
- Mulching Shredders:Specialized blade geometries optimize particle size for direct composting application without secondary processing.
Gas-powered shredders dominate installed base. Electric shredders are where expansion concentrates fastest.
End User:
Customer acquisition cost tiers structure this segmentation, with municipalities demanding extensive certification documentation while residential buyers transact through mass retail with minimal sales touch.
- Residential Users:Homeowners processing seasonal yard debris through electric or manual configurations prioritize storage footprint and noise levels over throughput capacity. Demand clusters in United States suburban developments with municipal organic waste mandates requiring compostable particle output.
- Commercial Landscapers:Fleet operators deploy medium and large gas-powered or advanced electric units across multiple job sites daily, with equipment leasing penetration rewriting capital deployment patterns. Service density in dealer networks creates switching costs that protect incumbent suppliers.
- Municipalities:Public works departments specify decibel limits and emission thresholds in procurement contracts.
- Garden Centers:Retail-service hybrid operations rent shredders to seasonal users and sell to committed gardeners.
Commercial landscapers anchor revenue concentration. Municipalities drive specification escalation fastest.
Size:
Physical footprint correlates with price tier and application intensity, from countertop residential units to trailer-mounted commercial platforms.
- Small:Compact electric units under 50 pounds suit residential storage constraints and occasional use patterns.
- Medium:Wheeled configurations balance portability with throughput for serious gardeners and small landscaping crews.
- Large:Stationary or towable platforms with hardened steel hammermill drums process hardwood debris at 2,000-3,600 RPM for commercial composting operations.
- Extra Large:Industrial-scale equipment serves municipal yard waste facilities and commercial biomass processors with continuous-duty requirements.
Medium units dominate unit volume. Large configurations capture margin expansion.
Technology:
Engineering maturity separates blade-based systems from advanced mechanical processing architectures that command premium positioning.
- Blade Technology:Hardened steel rotary cutters represent the mature core of installed base, with straightforward maintenance protocols and established supply chains for replacement components. Commercial buyers face technical constraints with dense hardwood debris that force migration toward premium alternatives.
- Hammermill Technology:Rotating drum configurations with swinging flails or fixed hammers achieve superior particle uniformity across variable feedstock including branches and brush. Demand concentrates in premium commercial units serving United States municipalities with strict compost output specifications.
- Impact Technology:High-velocity collision mechanisms reduce fibrous material through kinetic energy transfer rather than cutting action.
- Shredding Technology:General category encompassing rotary shear and tear-based reduction systems.
Blade technology dominates installed base. Hammermill technology is where premium positioning concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial landscaping contractors and municipal public works departments concentrate equipment procurement in suburban municipalities with strict organic waste mandates. Demand clusters where EPA emission thresholds and OSHA noise limits restrict gas-powered alternatives. Financing accessibility determines competitive entry across contractor tiers.
United States
Southeast and Midwest suburban municipalities drive replacement demand through cooperative purchasing agreements. EPA small off-road engine standards and CARB tailpipe regulations force gas-powered redesigns or electrification pivots. Atlanta and Dallas-Fort Worth metropolitan clusters anchor fleet turnover cycles among landscaping contractors handling municipal contracts.
Germany
Commercial landscapers in German-speaking European markets prioritize specialized dealer networks bundling certification support with equipment sales. EU Machinery Directive and CE marking requirements govern export access for North American and Asian manufacturers. Bavaria and North Rhine-Westphalia industrial clusters concentrate distribution infrastructure for premium hammermill configurations.
China
Domestic manufacturers serve cost-sensitive segments through mass production of blade-based residential units. MIIT industrial standards and GB certification requirements shape product development for export markets. Yangtze River Delta manufacturing clusters supply global private-label demand while Pearl River Delta exporters target Southeast Asian commercial segments.
United Kingdom
Garden center retail-service hybrid operations rent shredders to seasonal users and sell to committed gardeners. REACH chemical compliance and waste electrical equipment directives influence material selection and end-of-life processing claims. Southeast England and Midlands distribution hubs connect Irish and Scandinavian export channels.
Canada
Municipal yard waste facilities in Ontario and Quebec specify decibel limits and emission thresholds in procurement contracts. Health Canada and PMRA environmental standards align with EPA frameworks while accommodating shorter seasonal operating windows. Toronto and Montreal metropolitan clusters concentrate commercial landscaping fleet deployment.
Lawn Shredder Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent access pathways. Mass retail chains and captive finance arms anchor volume leadership through fleet turnover programs, while specialized dealer networks protect premium positioning via service density. Three archetypes dominate: scale-driven manufacturers with retail penetration, technology specialists with hammermill differentiation, and finance-integrated suppliers with municipal contracting leverage. Competitive moves concentrate on strategic partnerships with battery system developers and geographic expansion through distribution acquisition.
Among North American equipment manufacturers, MTD Products, Vermeer, and Stihl AG occupy distinct positioning tiers. MTD Products exemplifies mass retail channel control through home improvement chain penetration. Vermeer represents commercial-grade specialization with towable platform configurations. Stihl AG anchors specialized dealer network density in European markets and North American premium residential segments. These three manufacturers illustrate how divergent channel strategies create non-overlapping competitive territories despite shared product category focus.
| Leading Market Players |
|---|
| MTD Products |
| Vermeer |
| Bandit |
| Stihl AG |
| Husqvarna Group |
| Champion Power Equipment |
| Patriot Products |
| Earthquake |
| Troy-Bilt |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese blade-manufacturing clusters is compressing supplier margins and forcing tiered pricing concessions to North American OEMs, while undercapacity in European hammermill forging capacity sustains premium pricing power for German and Italian producers.
Pricing Analysis
Cost-plus contracts with steel price indexation dominate commercial shredder procurement, with EPA compliance certification tiers creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on hammermill versus blade architecture and CARB emission certification status. Pricing pressure stems from lithium-ion battery pack cost deflation eroding gas-powered unit premiums. Municipal buyers exhibit lowest price sensitivity due to cooperative purchasing scale, while residential retail channels face acute margin compression.
Supply Chain Analysis
Contract manufacturing for electric drivetrains concentrates in Yangtze River Delta battery assembly plants and Shenzhen motor controller foundries, with legacy gas-engine fabrication anchored in Chongqing and Shandong small-engine clusters. Raw material dependencies span hardened steel alloys from Baosteel, lithium carbonate from Chilean-Argentine salares, and rare-earth magnets from Inner Mongolia processing facilities. Single-source vulnerability in semiconductor motor controllers creates supply chain risk. Distribution runs through specialized dealer networks in Germany and mass retail chains in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of technicians trained on electromechanical drivetrain diagnostics is constraining dealer service network expansion and creating bottlenecks for electric shredder rollouts.
For Market Incumbents: Entrench municipal fleet relationships through captive finance arms offering usage-based Equipment-as-a-Service contracts. Expand backward integration into lithium-ion battery pack assembly to offset supplier concentration risk. Invest in OSHA-compliant low-RPM drivetrain configurations to capture premium tiers in noise-restricted procurement specifications. For New Entrants and Emerging Players: Mid-market commercial landscaping contractors in the United States Midwest represent the most penetrable entry point, as equipment leasing penetration has already normalized non-capital acquisition patterns. Target garden center retail-service hybrid channels with rental-first positioning. Differentiate through telematics-enabled predictive maintenance bundles that incumbent mass-retail suppliers cannot match. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across residential electric shredder segments as battery chemistry commoditization reduces R&D burn rates. Long-term viability favors manufacturers with integrated finance arms and dealer service density rather than pure-play hardware producers. Monitor municipal composting mandate expansion velocity as the inflection signal for replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drivetrain Platform Standardization | Brushless DC motor controllers from Yangtze River Delta suppliers enable torque profiles matching gas engines for municipal contracts. |
| Captive Finance Arm Expansion | Husqvarna's fleet turnover programs anchor municipal procurement cycles through usage-based contracts rather than capital sales. |
| Hammermill Technology Licensing | Vermeer's hardened steel drum configurations achieve particle uniformity for strict EPA compost output specifications. |
| Dealer Network Service Density Investment | Stihl's German-speaking European distribution creates switching costs that mass retail competitors cannot replicate. |
| Battery Recycling Infrastructure Partnership | Li-Cycle and Redwood Materials processing networks reduce regulatory liability exposure for circular economy claims in municipal bidding. |
Research Methodology
Desk research of EPA certification databases, CARB executive orders, and EU Machinery Directive technical files preceded structured interviews with commercial landscaping fleet managers, municipal public works procurement officers, small-engine dealer service technicians, and lithium-ion battery supply chain specialists. Secondary validation drew from OSHA noise exposure compliance records, SEC 10-K filings of listed equipment manufacturers, and customs trade data for shredder component flows. Bottom-up unit shipment estimates triangulated against top-down equipment replacement cycle modeling.
Assumptions held fixed across the projection horizon include EPA small off-road engine standard stringency trajectories, lithium-ion energy density improvement curves, and municipal organic waste mandate adoption rates in the United States Southeast and Midwest. Segmentation dimensions encompassed product type, end-user archetype, size tier, and technology architecture. CAGRs derived from logistic diffusion curves fitted to electric drivetrain adoption patterns and replacement cycle compression in commercial fleets. Industry-specific inputs included hammermill versus blade technology mix shifts and telematics penetration rates.
Stress conditions across steel alloy price volatility, battery cell supply disruptions, and municipal budget contraction scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to EPA regulatory delays or accelerated CARB zero-emission mandates. Quarterly review of municipal procurement specification updates and battery recycling infrastructure deployment metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Plows Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Square Silos Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Automatic Composter Market
Agricultural Equipment
Cordless Handheld Cultivator Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Intelligent Milking Robot Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market