
 Wheelbarrow Market | 2026-2036
Wheelbarrow Market Size, Share, and Industry Trends Forecast 2026-2036
Wheelbarrow Market Outlook
Buyer concentration among professional landscaping contractors is hardening as regional maintenance companies expand their fleet purchases. Stanley Black & Decker leverages its retail distribution network to supply big-box hardware channels. Gorilla Carts differentiates through polymer-based designs that resist corrosion in humid climates. Qingdao Taifa Group anchors global volume through OEM relationships with European garden equipment distributors.
A wheelbarrow is a single- or multi-wheeled hand-propelled vehicle with a shallow or deep basin mounted between two handles, typically fabricated from steel, aluminum, or high-density polyethylene and rated by load capacity in kilograms or cubic feet for transporting bulk materials across uneven terrain. The single-wheel configuration dominates residential gardening due to maneuverability in tight spaces, while heavy-duty steel models capture the construction end-user segment where load ratings exceed 200 kilograms and impact resistance determines replacement intervals. Plastic and aluminum materials represent the fastest-growing material categories as users prioritize reduced weight for ergonomic handling during extended work sessions.
OSHA workplace ergonomics guidelines and EPA surface coating regulations shape product design requirements for commercial-grade wheelbarrows sold in the United States. The European Union's REACH framework restricts certain chemical treatments in corrosion-resistant steel finishes, pushing manufacturers toward powder-coating alternatives. Stakeholders must monitor how evolving sustainability certifications influence material specifications and channel access across their priority markets.
Market Dynamics
Steel tariff volatility and EPA corrosion-prevention standards are forcing manufacturers to reconfigure material sourcing strategies while suburban homeowners in the American Midwest drive replacement demand for heavy-duty models.
Growth Catalysts
- OSHA Ergonomics Guidelines:Workplace safety mandates for commercial landscaping fleets are accelerating adoption of lightweight aluminum and polymer designs that reduce operator strain during extended use cycles.
- Suburban Property Expansion:Large-lot residential development across Ohio, Indiana, and Illinois is generating sustained replacement demand for high-capacity wheelbarrows rated above 150 kilograms.
- Powder-Coating Technology:Advanced surface finishing processes that eliminate volatile organic compounds are enabling compliance with REACH restrictions while extending product lifespan in humid climates.
Market Restraints
- Steel Input Volatility:Tariff-adjusted steel pricing creates margin pressure for manufacturers dependent on domestic rolled steel for heavy-duty basin fabrication.
- Supply Concentration Risk:OEM volume production concentrates among Qingdao-based fabricators, exposing distributors to shipping cost fluctuations and extended lead times.
- Substitution Threat:Motorized utility carts and powered wheelbarrows are displacing manual models in commercial construction sites where labor costs exceed equipment amortization thresholds.
Strategic Opportunities
- Polymer Material Convergence:High-density polyethylene formulations are converging with reinforced composite handles to capture corrosion-resistant demand in coastal Florida and Gulf Coast markets.
- Big-Box Retail Expansion:Hardware superstore channels in Texas and Arizona are creating dedicated seasonal display space for premium residential-grade models with ergonomic grip systems.
- IRA-Aligned Sustainability:Federal domestic manufacturing incentives are enabling reshoring of aluminum component production for EPA-compliant surface coating operations.
Industry Challenges
- Welding Certification Bottlenecks:AWS-certified welders for structural steel basin fabrication remain scarce in Midwest manufacturing clusters, constraining production scaling.
- REACH Compliance Timeline:European garden equipment distributors demand accelerated documentation of chemical treatment alternatives, compressing product development cycles for export-bound OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheelbarrow Market |
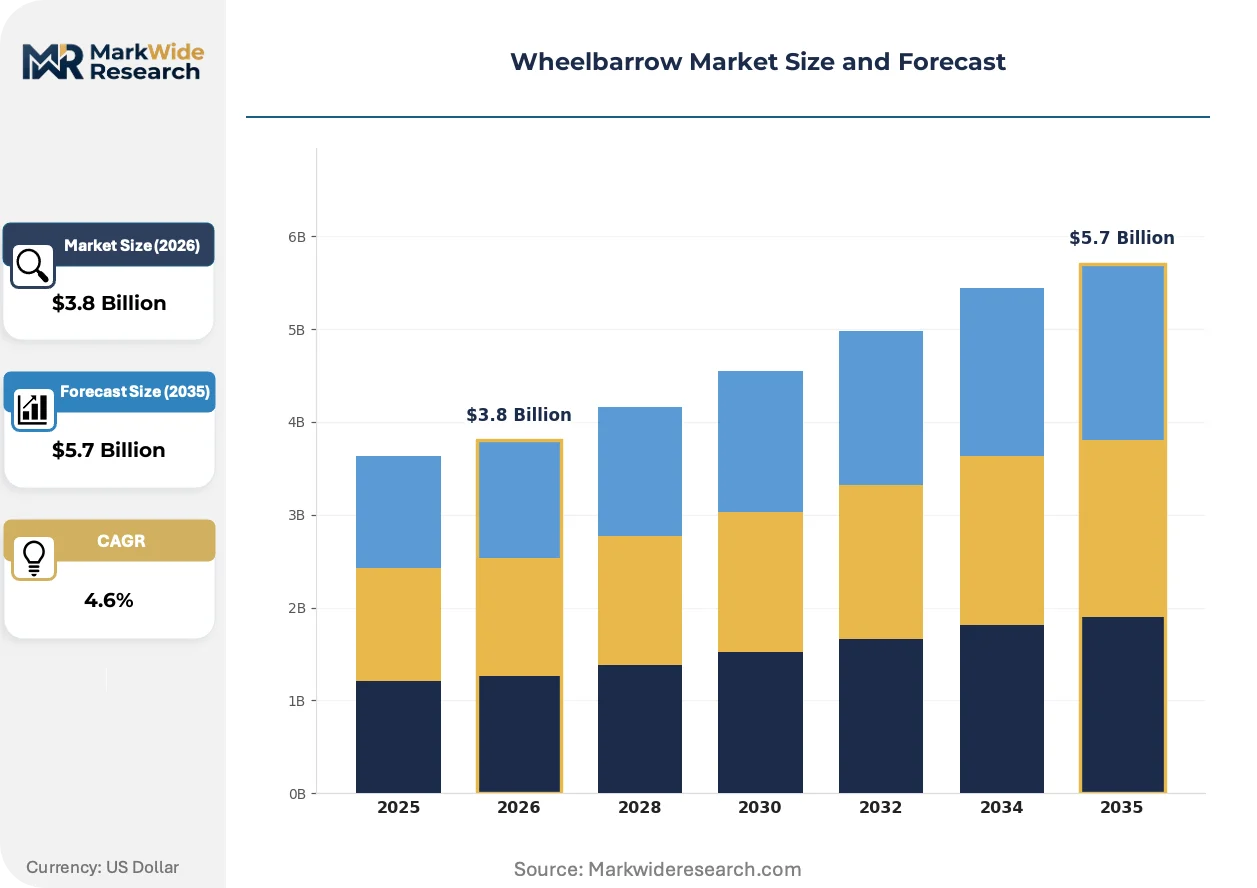
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wheel, Double Wheel, Foldable, Heavy Duty Material: Steel, Plastic, Aluminum, Wood End User: Construction, Gardening, Agriculture, Landscaping Distribution Channel: Retail Stores, Online Sales, Direct Sales, Wholesale |
| Companies Covered | Stanley Black & Decker, Gorilla Carts, Qingdao Taifa Group, The Walsall Wheelbarrow Co Ltd, Bullbarrow Products, Haemmerlin, Griffin Bros Truck & Equipment, Qingdao Xinjiang Handtruck Co., Ltd, Wolverine Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheelbarrow Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are reshaping how wheelbarrow manufacturers balance durability, weight reduction, and environmental compliance across residential and commercial segments.
High-density polyethylene formulations with UV stabilizers are converging with glass-fiber reinforcement to produce basins that match steel impact resistance at 40% reduced weight. Professional landscaping contractors in humid southeastern states are specifying these polymer models for fleet standardization to minimize corrosion-related replacement. The technology is converging with ergonomic handle design to compress total cost of ownership calculations for commercial buyers comparing lifecycle value against upfront steel pricing.
EPA surface coating regulations under the Clean Air Act are prohibiting solvent-based corrosion treatments for products sold through US retail channels. Manufacturers are responding with powder-coating investments that eliminate volatile organic compound emissions while achieving comparable salt-spray resistance ratings. Commercial-grade steel wheelbarrows destined for construction sites face the steepest compliance cost increases, pushing specification decisions toward pre-coated aluminum alternatives.
Buyer concentration among regional landscaping maintenance companies is consolidating fleet procurement through direct distributor relationships rather than retail hardware channels. Large property management firms in suburban Chicago and Minneapolis are negotiating annual volume contracts with specified load ratings and ergonomic certification requirements. This procurement centralization is most visible in the American Midwest, where seasonal maintenance contracts drive synchronized replacement cycles across contractor networks.
Wheelbarrow Market Segmentation
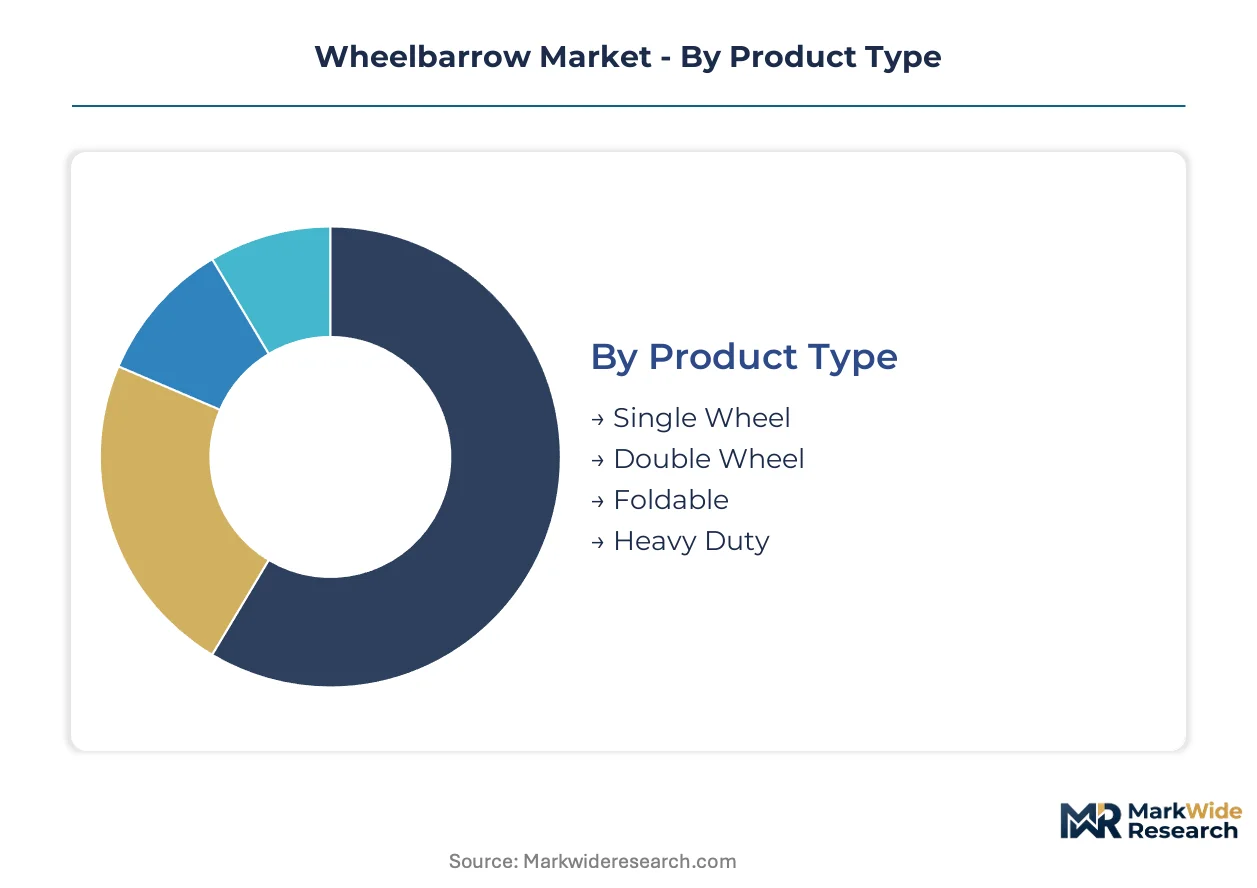
Wheelbarrow procurement decisions split across load-bearing requirements, surface durability needs, and fleet standardization mandates for commercial operators. Understanding how specifications cluster by use case enables manufacturers to align certification investments with revenue concentration.
Product Type:
OSHA ergonomics guidelines and EPA surface coating standards apply differentially across wheel configurations, with single-wheel designs facing lighter structural certification burdens than heavy-duty multi-wheel variants.
- Single Wheel:The classic pivot-steer configuration features a centered wheel beneath a shallow or deep basin, optimized for maneuverability in confined residential spaces. Demand concentrates among suburban homeowners in Ohio and Indiana executing seasonal landscaping tasks, with maneuverability in tight garden beds driving specification over load capacity. Leading the category by volume: Single Wheel. Growing fastest: Heavy Duty.
- Heavy Duty:Reinforced steel or aluminum basins with dual or wide-track wheel configurations rated above 200 kilograms for construction and commercial landscaping fleets. Regional maintenance companies across Illinois and Wisconsin specify these models for synchronized replacement cycles under annual volume contracts.
- Double Wheel:Twin-wheel stability systems reduce operator fatigue on uneven terrain through balanced load distribution. Commercial buyers in Texas favor these for material transport across graded construction sites.
- Foldable:Collapsible polymer or fabric basin designs with detachable handles for storage-constrained residential users. Urban gardeners in Arizona and Florida select these for balcony and small-lot applications.
Cost tiers separate premium welded-steel construction from standard stamped models and economy polymer alternatives.
Material:
REACH compliance timelines and EPA corrosion-prevention standards create divergent certification pathways, with steel requiring chemical treatment documentation that aluminum and polymer formulations bypass.
- Steel:Rolled or stamped carbon steel basins with powder-coated or solvent-based corrosion finishes, historically dominant in construction applications. Tariff-adjusted input pricing from domestic mills is compressing margins for Midwest fabricators serving heavy-duty demand. Leading the category by volume: Steel. Expanding most quickly: Plastic.
- Plastic:High-density polyethylene formulations with UV stabilizers and glass-fiber reinforcement achieving 40% weight reduction versus steel. Professional landscaping contractors in humid southeastern states specify these for fleet standardization to eliminate corrosion-related replacement.
- Aluminum:Extruded or cast alloy basins combining corrosion immunity with moderate weight reduction, increasingly specified for EPA-compliant commercial sales through retail channels. IRA-aligned domestic manufacturing incentives are enabling reshoring of component production.
- Wood:Traditional hardwood or plywood basin constructions for heritage aesthetic and specialty agricultural applications. Amish and Mennonite farming communities in Pennsylvania and Ohio sustain niche demand.
Application context determines material selection: construction prioritizes impact resistance, gardening favors weight reduction, coastal operations demand corrosion immunity.
End User:
Procurement centralization varies sharply across user categories, with landscaping contractors consolidating through direct distributor relationships while gardening and agriculture remain fragmented through retail channels.
- Construction:General contractors and specialty trades requiring load ratings above 200 kilograms with impact resistance determining replacement intervals. Motorized utility carts are displacing manual models where labor costs exceed equipment amortization thresholds. Leading the category by volume: Construction. Gaining share fastest: Landscaping.
- Landscaping:Regional maintenance companies and property management firms negotiating annual volume contracts with specified ergonomic certifications. Large-lot suburban contracts in Chicago and Minneapolis drive synchronized replacement cycles.
- Gardening:Individual homeowners and small-scale horticulturalists prioritizing maneuverability and storage efficiency over load capacity. Big-box hardware channels in Texas and Arizona capture seasonal demand through dedicated display space.
- Agriculture:Livestock operations and crop producers requiring corrosion-resistant models for manure handling and feed transport. Midwest grain and dairy operations sustain replacement demand for heavy-duty steel variants.
Customer type stratification shows commercial buyers capturing volume leadership while professional service segments climb fastest.
Distribution Channel:
Channel economics reflect fulfillment cost structures and buyer procurement sophistication, with wholesale and direct sales capturing commercial volume at lower per-unit margins than retail.
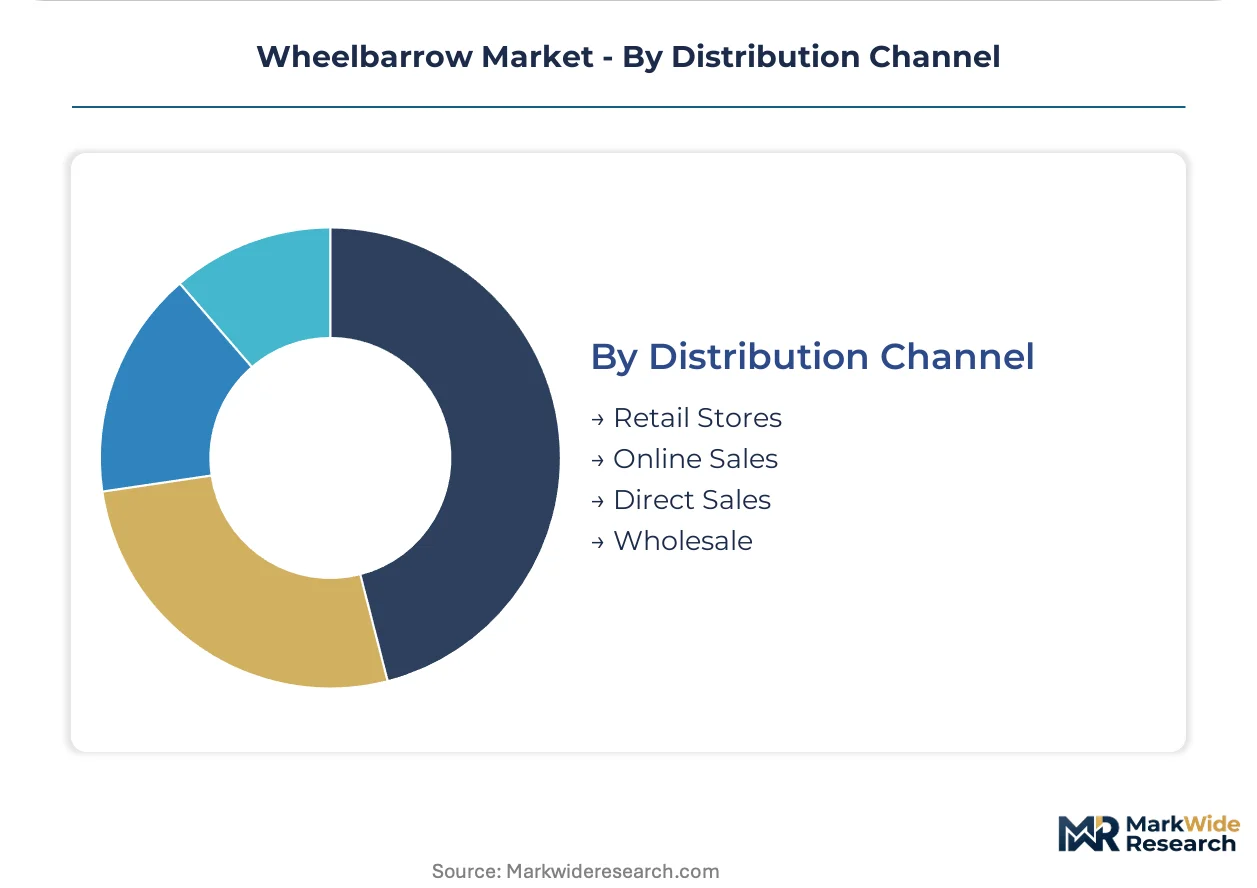
- Retail Stores:Hardware superstores and independent dealers supplying residential and light commercial demand through seasonal inventory builds. Stanley Black & Decker leverages this channel through established big-box relationships. Leading the category by volume: Retail Stores. Climbing fastest: Online Sales.
- Wholesale:Distributor networks supplying contractor yards and commercial landscaping fleets with bulk pricing and specification consistency. Qingdao-based OEM volume flows primarily through this channel to European garden equipment distributors.
- Direct Sales:Manufacturer-to-contractor relationships for fleet standardization and annual volume agreements. Regional maintenance companies in suburban Chicago and Minneapolis utilize this procurement path.
- Online Sales:E-commerce platforms capturing residential replacement demand and specialty configurations unavailable through physical retail. Foldable and polymer designs achieve disproportionate share here due to shipping weight advantages.
Supply concentration in Qingdao-based fabrication shapes channel lead times and cost structures across all four pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the American Midwest where large-lot property maintenance drives replacement cycles, while European distributors source volume through Qingdao-based OEM relationships and coastal US markets pivot toward corrosion-resistant polymer designs.
United States
Suburban homeowners across Ohio, Indiana, and Illinois execute synchronized replacement cycles for heavy-duty steel models rated above 150 kilograms. EPA surface coating regulations under the Clean Air Act prohibit solvent-based corrosion treatments for retail-channel products. Chicago-area regional maintenance companies negotiate annual volume contracts with specified ergonomic certifications and load ratings.
Germany
Professional landscaping contractors and construction fleets specify powder-coated steel and aluminum variants compliant with REACH chemical restrictions. The EU Green Deal accelerates documentation requirements for corrosion-resistant finishes exported to European garden equipment distributors. Industrial clusters in North Rhine-Westphalia host fabrication facilities serving domestic wholesale channels.
China
Qingdao-based OEM fabricators anchor global volume production for European and North American distributor networks. Domestic manufacturing incentives under dual carbon goals encourage aluminum component reshoring for EPA-compliant surface coating operations. Shandong Peninsula production clusters face shipping cost fluctuations affecting lead times to Western markets.
United Kingdom
Heritage hardwood wheelbarrow demand persists among specialty agricultural and aesthetic gardening segments. REACH framework alignment post-Brexit maintains chemical treatment documentation burdens for steel finish exporters. Midlands-based fabricators supply regional hardware retailers with traditional and polymer-based designs.
Australia
UV-stabilized polymer formulations capture share in humid coastal markets where corrosion resistance determines replacement intervals. National construction safety guidelines influence commercial fleet procurement for load-rated models. Queensland and New South Wales distribution networks prioritize lightweight designs for extended work sessions in landscaping applications.
Wheelbarrow Market Competitive Environment
Chinese producers anchor volume-tier supply through Qingdao-based OEM relationships; European and North American specialists hold premium positions through certified fabrication and retail channel access. The vendor base separates into three strategic tiers: scale-driven OEM exporters, brand-anchored hardware suppliers, and regional fabrication specialists serving contractor direct-sales channels. Competitive moves concentrate on powder-coating technology investments for EPA compliance and polymer material convergence for coastal corrosion resistance.
Among brand-anchored suppliers, Stanley Black & Decker exemplifies the retail-network archetype through established big-box hardware relationships. Gorilla Carts occupies a position within the polymer-specialist tier, representing corrosion-resistant design convergence for humid climate applications. Qingdao Taifa Group anchors the volume-export archetype, sitting within OEM supply chains serving European garden equipment distributors.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Gorilla Carts |
| Qingdao Taifa Group |
| The Walsall Wheelbarrow Co Ltd |
| Bullbarrow Products |
| Haemmerlin |
| Griffin Bros Truck & Equipment |
| Qingdao Xinjiang Handtruck Co., Ltd |
| Wolverine Products |
| Others |
Value Chain & Pricing Dynamics
Powder-coating technology adoption is compressing production economics for domestic fabricators while simultaneously redrawing competitive boundaries between EPA-compliant domestic operations and solvent-dependent offshore alternatives. This surface-finishing transition concentrates pricing power among manufacturers with captive coating capacity, forcing tiered sourcing decisions across retail and wholesale channels.
Pricing Analysis
Volume leadership sits with steel models sold through big-box retail at compressed margins, while premium aluminum and polymer variants command higher per-unit economics through direct contractor channels. Price differentiation rests on EPA compliance certification and ergonomic rating tier, with powder-coated steel carrying 15-20% cost premiums over solvent-finished imports. Pricing pressure stems from tariff-adjusted domestic steel input costs, particularly for Midwest fabricators serving heavy-duty construction demand. Residential gardening buyers through retail channels exhibit highest price sensitivity, while commercial landscaping contractors prioritize lifecycle cost calculations over upfront acquisition expense.
Supply Chain Analysis
AWS-certified welding qualifications and EPA surface-coating certifications gate entry for domestic producers, concentrating structural steel fabrication in Ohio-Indiana-Illinois manufacturing clusters while Qingdao-based OEMs anchor global polymer and standard steel volume. Raw material dependencies center on domestic rolled steel, high-density polyethylene resin, and aluminum extrusion feedstock. Supply chain risk manifests in shipping cost volatility affecting Qingdao-to-European distributor lead times. Distribution runs through three dominant pathways: hardware superstore retail for residential demand, wholesale distributor networks for contractor fleet procurement, and direct manufacturer relationships for annual volume agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel tariff volatility and REACH compliance documentation burdens are accelerating consolidation among mid-tier fabricators lacking captive powder-coating capacity or Qingdao sourcing relationships. Weaker players face exit pressure as certification investments and input cost hedging demands outstrip available capital.
For Market Incumbents: Deploy backward integration into aluminum component production to capture IRA-aligned domestic manufacturing incentives and insulate margin structures from steel input volatility. Incumbents must simultaneously lock long-term powder-coating capacity commitments to defend EPA-compliant channel access against emerging polymer specialists. The motorized utility cart substitution threat demands fleet-retention programs emphasizing total cost of ownership analytics for commercial landscaping contractors. For New Entrants and Emerging Players: Coastal property management firms in Florida and Gulf Coast markets represent an underserved buyer archetype with unmet corrosion-resistance requirements and limited incumbent polymer penetration. New entrants should prioritize UV-stabilized high-density polyethylene formulations with glass-fiber reinforcement, leveraging direct e-commerce distribution to bypass established retail gatekeepers. The foldable residential segment offers additional white-space opportunity through shipping-weight advantages unavailable to steel competitors. For Investors and Strategic Acquirers: Re-rating potential sits with polymer-specialist fabricators possessing Qingdao manufacturing relationships and EPA-compliant US finishing operations, given sustained steel tariff regimes and coastal corrosion-resistance demand expansion. Acquisition targets should demonstrate validated high-density polyethylene formulation capabilities and established European garden equipment distributor relationships. The inflection indicator to monitor is REACH documentation acceleration timelines compressing product development cycles for export-bound OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Powder-Coating Capacity Expansion | EPA Clean Air Act compliance enables retail channel access and eliminates volatile organic compound liability. |
| Polymer Material Convergence | High-density polyethylene with glass-fiber reinforcement captures humid climate replacement demand from corrosion-vulnerable steel. |
| Backward Integration into Aluminum | IRA-aligned domestic manufacturing incentives reduce tariff exposure and support EPA-compliant surface coating operations. |
| Direct Contractor Channel Development | Annual volume agreements with regional landscaping firms synchronize replacement cycles and reduce retail margin erosion. |
| REACH Compliance Documentation Investment | Accelerated chemical treatment alternatives documentation maintains European garden equipment distributor channel access. |
Study Parameters
Document review covered customs and trade flow databases, EPA regulatory filings, and European REACH compliance documentation, complemented by interviews with plant managers at Midwest steel fabrication facilities, procurement leads at regional landscaping maintenance companies, and distribution channel partners supplying hardware superstore networks. Secondary validation drew from SEC 10-K filings of listed equipment manufacturers, OSHA workplace ergonomics guideline publications, and aluminum industry association production statistics. Bottom-up demand modeling triangulated against top-down market sizing across material type, wheel configuration, and end-user segmentation dimensions.
Unit shipment and value projections emerged from integrated modeling of replacement cycle timing, new housing construction permits, and commercial landscaping fleet expansion patterns across the projection horizon. Segmentation dimensions included product type, material formulation, end-user category, and distribution channel structure. CAGRs derived from regression analysis of historical volume trends against macroeconomic indicators and regulatory implementation schedules. Industry-specific forecast inputs incorporated steel tariff adjustment trajectories and powder-coating technology adoption curves.
Revisions become necessary when steel tariff regimes shift substantially, REACH compliance timelines accelerate, or motorized utility cart substitution rates exceed modeled thresholds in commercial construction applications. Forecasts reflect assumptions regarding sustained suburban property expansion in the American Midwest and continued EPA enforcement of Clean Air Act surface coating restrictions. A model refresh is warranted upon material change in domestic manufacturing incentive structures or Qingdao-based OEM shipping cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Lawn Aerators Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Square Silos Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Food Bucket Elevators Market