
 Smart Plug Market | 2026-2036
Smart Plug Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Plug Market Intelligence
Online retail channels for smart home accessories is narrowing as platform algorithms prioritize certified brands with verified cybersecurity credentials. TP-Link Technologies leverages its router ecosystem to bundle smart plugs at checkout, sustaining repeat purchases through unified app control. Xiaomi Inc. competes on manufacturing scale, shipping millions of units annually through direct-to-consumer marketplace storefronts.
A smart plug is an electrical outlet adapter embedding microprocessor-controlled relays and wireless transceivers, typically rated between 10-16 amps at 120-240 volts, enabling remote on/off switching and real-time power metering for connected appliances. Wi-Fi smart plugs dominate volume shipments due to router-native compatibility eliminating hub requirements, while Zigbee smart plugs command higher margins among smart home enthusiasts seeking mesh-network reliability with local processing. Energy monitoring smart plugs represent the fastest-growing product type as electricity tariffs rise and users demand granular appliance-level consumption data.
The FCC in the United States certifies radio frequency emissions, while the EU Cyber Resilience Act imposes mandatory security update obligations for networked devices sold in Europe; China's MIIT enforces GB standards for wireless transmission power. These frameworks collectively elevate compliance costs for new entrants while rewarding incumbents with established certification laboratories and firmware update infrastructure. Stakeholders must monitor whether emerging battery-backup requirements and standby power limits in draft regulations force hardware redesigns before the next product cycle.
Market Dynamics
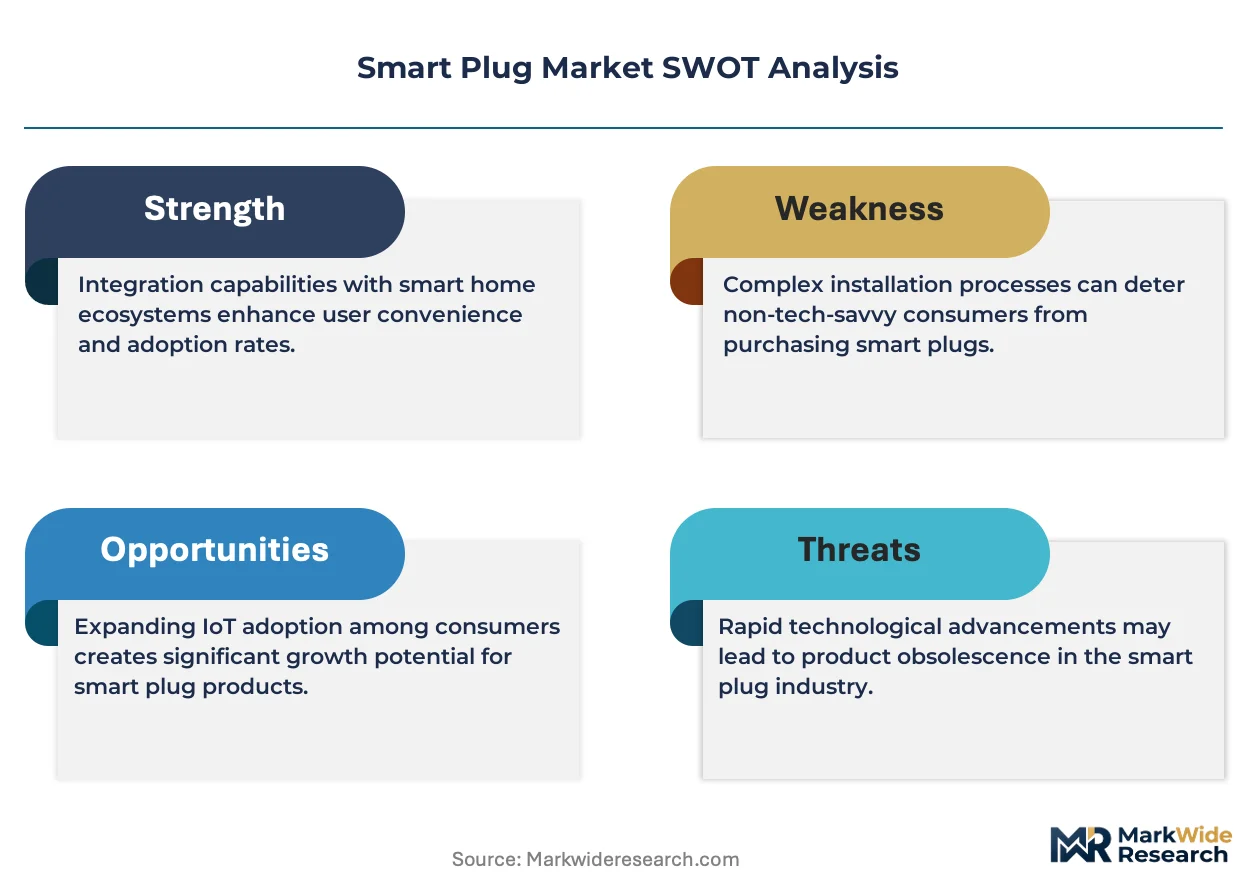
Smart plug manufacturers face mounting pressure from the EU Cyber Resilience Act's mandatory security update obligations, forcing firmware infrastructure investments that favor incumbents with established certification pipelines over new entrants lacking laboratory relationships.
Growth Catalysts
- Residential electrification mandates:Germany's Building Energy Act and similar frameworks in Japan accelerate replacement of conventional outlets with monitored alternatives in renovated housing stock.
- Time-of-use tariff structures:Utilities across multiple states deploy dynamic pricing that rewards consumers with granular appliance-level control, directly stimulating energy monitoring smart plug deployments.
- Router-native Wi-Fi compatibility:Elimination of proprietary hub requirements reduces friction for first-time smart home adopters, expanding the addressable base beyond enthusiast segments.
Market Restraints
- Semiconductor supply concentration:Microcontroller and RF transceiver fabrication clusters in East Asia create vulnerability to geopolitical trade restrictions and capacity constraints.
- Copper and rare earth input volatility:Relay components and PCB substrates face price swings that compress margins for manufacturers lacking long-term material hedges.
- Interoperability fragmentation:Competing wireless protocols (Zigbee, Z-Wave, Thread, Matter) force SKU proliferation and inventory complexity without clear standard consolidation.
Strategic Opportunities
- Commercial building retrofits:Small and medium enterprises in the United States seek plug-load management to meet municipal energy disclosure requirements without full BMS installation.
- Matter protocol convergence:Cross-ecosystem compatibility promises to collapse the current hub-versus-hub competition, enabling single-SKU strategies across Apple, Google, Amazon, and Samsung platforms.
- India's smart city infrastructure:Municipal demand for streetlight and public facility monitoring creates bulk procurement channels distinct from consumer retail.
Industry Challenges
- Cybersecurity talent scarcity:Firmware engineering teams with embedded security expertise command premium compensation, stretching R&D budgets at mid-tier manufacturers.
- Certification timeline compression:FCC Part 15 and CE marking procedures for radio equipment now run 14-20 weeks, delaying product launches behind seasonal demand windows.
- Legacy electrical infrastructure incompatibility:Aging residential wiring in established markets limits safe deployment of high-amperage monitoring units without electrician intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Plug Market |
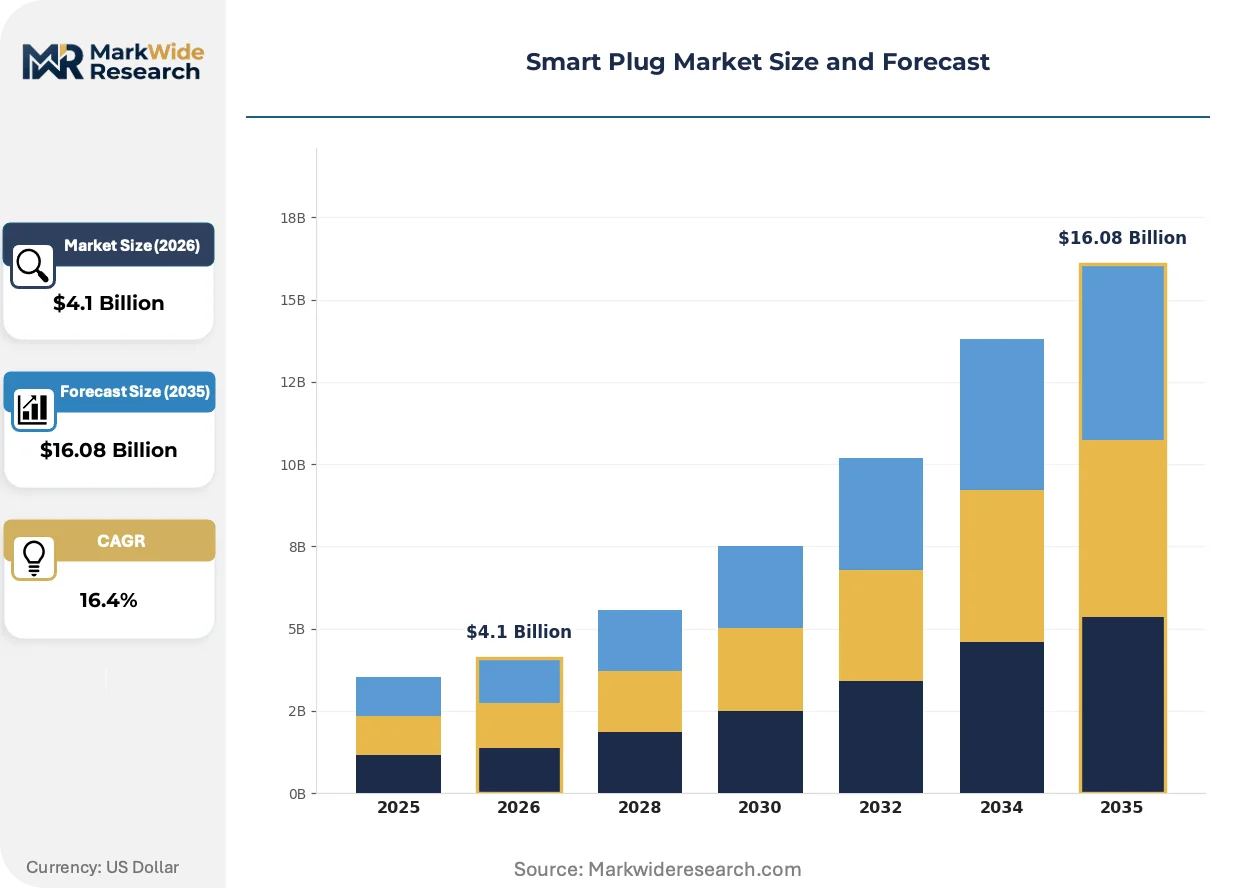
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $16.08 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Smart Plugs, Bluetooth Smart Plugs, Zigbee Smart Plugs, Energy Monitoring Smart Plugs End User: Residential Users, Commercial Users, Industrial Users, Smart Home Enthusiasts Connectivity: Wireless, Wired, Cloud-Controlled, App-Controlled Distribution Channel: Online Retailers, Brick-and-Mortar Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | TP-Link Technologies, Panasonic Corporation, Xiaomi Inc., Belkin International, D-Link Corporation, Leviton Manufacturing Co., Inc., Honeywell International, EDIMAX Technology Co. Ltd., Broadlink Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Plug Market Strategic Shifts & Innovations
Edge computing architectures and local inference capabilities are redrawing the boundary between cloud-dependent and autonomous smart home devices, with direct implications for latency, privacy, and manufacturer recurring revenue models.
Matter-over-Thread implementations with local execution engines are rendering obsolete the cloud-polling architectures that dominated first-generation Wi-Fi smart plugs. Early adopters in Germany and Japan now prioritize devices that maintain scheduling and automation logic during internet outages. This shift compresses server infrastructure requirements while raising firmware complexity and on-device memory specifications.
The EU Cyber Resilience Act imposes mandatory vulnerability disclosure and security update timelines for all networked devices sold in Europe, effective 2027. Manufacturers must maintain firmware support for minimum periods and document secure development lifecycles. Product lines lacking over-the-air update infrastructure face market withdrawal, with premium energy monitoring segments absorbing compliance costs most readily.
Appliance manufacturers now embed native connectivity, bypassing plug-level intermediation entirely. HVAC and white goods OEMs in the United States ship Wi-Fi-enabled units direct to consumers, shrinking the addressable market for retrofit smart plugs in high-wattage categories. This displacement concentrates remaining demand on legacy appliances and rental housing where permanent modification is prohibited.
Smart Plug Market Segmentation
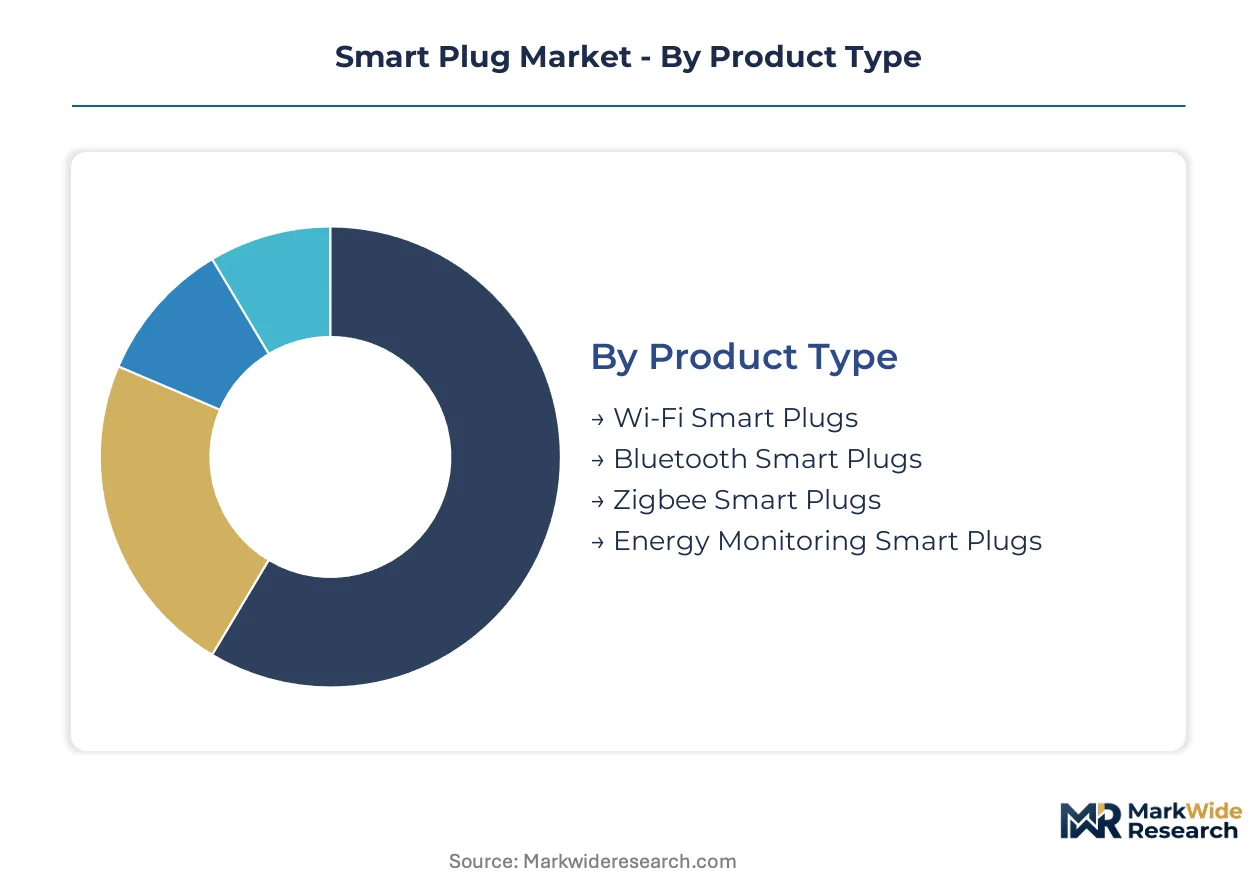
Smart plug manufacturers engineer distinct product variants around installation complexity, protocol compatibility, and data granularity. Each segment demands differentiated firmware architectures, certification pathways, and channel strategies that reshape margin profiles and customer lifetime value calculations.
Product Type:
After-sales-service intensity varies sharply across product types, with energy monitoring units requiring ongoing firmware support for tariff algorithm updates and security patches.
- Wi-Fi Smart Plugs:Router-native compatibility eliminates hub dependencies, making these the default entry point for first-time adopters. Demand concentrates in the United States among rental households seeking non-permanent automation solutions without landlord approval. TP-Link and Amazon bundle these at checkout with mesh router systems, capturing repeat purchases through unified app ecosystems.
- Energy Monitoring Smart Plugs:Embedded power measurement ICs track voltage, current, and power factor with sub-watt precision for appliance-level consumption analytics. Germany's Building Energy Act drives retrofit demand as homeowners seek granular data to optimize heat pump and EV charger scheduling. These units command premium pricing but require more intensive customer support for calibration and interpretation.
- Bluetooth Smart Plugs:Short-range connectivity suits localized control without internet dependency, appealing to privacy-conscious users.
- Zigbee Smart Plugs:Mesh networking reliability attracts smart home enthusiasts building integrated ecosystems.
Wi-Fi smart plugs hold the largest share; momentum sits with energy monitoring variants.
End User:
Cost tier differentiation separates hobbyist-grade hardware from enterprise deployments with centralized fleet management and API access requirements.
- Residential Users:Price-sensitive mass-market segment prioritizing plug-and-play simplicity over advanced automation. Japan's aging housing stock drives replacement demand as homeowners modernize electrical infrastructure during renovations. These users typically purchase single units or small multipacks through online marketplaces with minimal technical support expectations.
- Commercial Users:Small and medium enterprises seeking plug-load management for municipal energy disclosure compliance without full building management system investment. United States office retrofits concentrate demand in California and New York where local ordinances mandate granular consumption reporting. Procurement runs through IT resellers and facility management contractors rather than consumer retail.
- Industrial Users:Heavy-duty specifications for manufacturing equipment monitoring with higher amperage ratings.
- Smart Home Enthusiasts:Early adopters running multi-protocol hubs and demanding local processing with cloud failover.
Residential users dominate volume; commercial deployments are climbing the fastest.
Connectivity:
Volume concentration favors wireless architectures as wired installations require electrician labor that erodes the retrofit value proposition.
- Wireless:Dominant architecture spanning Wi-Fi, Zigbee, Z-Wave, and Thread protocols. Demand concentrates in app-controlled configurations where smartphone interfaces replace physical switches. The Matter protocol convergence promises to collapse hub fragmentation, enabling single-SKU strategies across Apple, Google, Amazon, and Samsung ecosystems.
- App-Controlled:Cloud-dependent or locally-executed automation through iOS and Android interfaces. Germany and Japan now prioritize edge-computing variants maintaining schedules during internet outages. These implementations compress server infrastructure costs while raising on-device memory requirements.
- Wired:Ethernet-connected units for commercial environments with strict RF emission controls.
- Cloud-Controlled:Legacy architectures facing displacement as privacy regulations tighten and users demand local execution.
Wireless connectivity commands the installed base; app-controlled configurations show the steepest expansion trajectory.
Distribution Channel:
Margin structure diverges sharply between direct-to-consumer storefronts and wholesale intermediaries with inventory risk and technical support obligations.
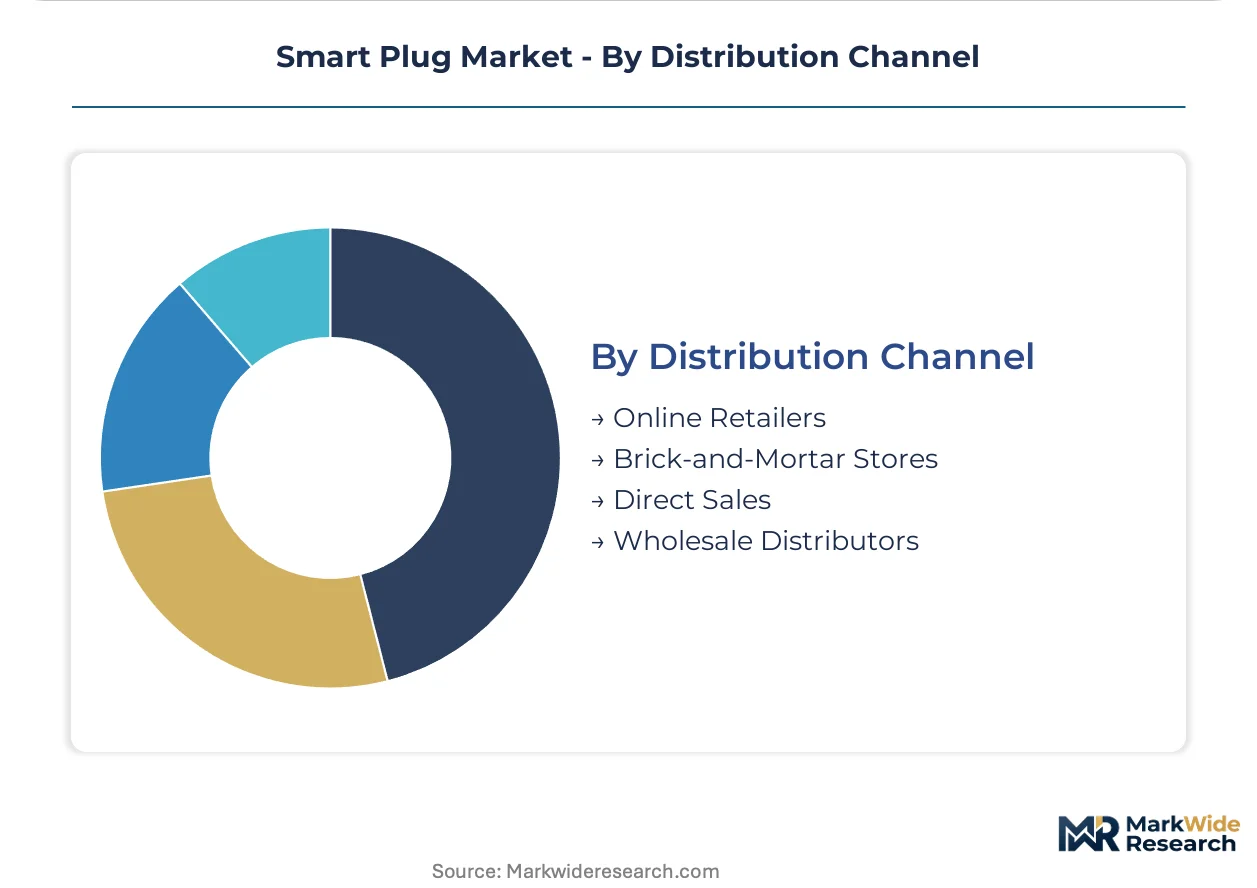
- Online Retailers:Amazon, Alibaba, and regional marketplaces dominate volume with algorithmic prioritization of certified brands. Xiaomi ships millions of units annually through direct-to-consumer storefronts, leveraging manufacturing scale for price positioning. Platform search rankings increasingly weight cybersecurity credentials and verified compliance documentation.
- Brick-and-Mortar Stores:Best Buy, B&Q, and home improvement chains serve last-minute purchasers and gift buyers seeking immediate availability. United States retail footprints concentrate in suburban markets where smart home adoption lags online-purchasing metros. Staff training limitations push these channels toward plug-and-play Wi-Fi units over complex multi-protocol offerings.
- Direct Sales:Manufacturer-owned storefronts capturing full margin but requiring logistics infrastructure investment.
- Wholesale Distributors:Ingram Micro and regional electrical supply houses serving commercial and industrial procurement with volume pricing.
Online retailers hold the largest share; direct sales channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Building Energy Act mandates granular energy monitoring in renovated housing, accelerating retrofit demand across the European Union's largest residential market. Japan's METI efficiency standards and time-of-use electricity tariffs stimulate connected outlet deployments. The United States, China, and India complete the geographic scope with distinct regulatory and infrastructure drivers.
United States
Dynamic electricity pricing across California, Texas, and New York utilities rewards consumers with appliance-level control capabilities. The FCC certifies radio frequency emissions under Part 15 rules, while municipal energy disclosure ordinances in Los Angeles and New York City drive commercial plug-load management. Silicon Valley hardware startups and Shenzhen supply chains converge in Los Angeles distribution hubs serving North American retail channels.
Germany
Homeowners modernizing aging electrical infrastructure during renovations seek monitored alternatives to conventional outlets. The EU Cyber Resilience Act imposes mandatory security update obligations effective 2027, forcing firmware infrastructure investments. Bavarian engineering clusters around Munich and Nuremberg host certification laboratories serving manufacturers targeting European compliance.
Japan
Aging housing stock replacement drives demand for non-permanent automation solutions in rental and owner-occupied units. METI efficiency standards and utility time-of-use tariffs reward granular consumption visibility. Tokyo-Osaka corridor electronics distributors maintain inventory for both domestic retail and re-export to Southeast Asian markets.
China
Manufacturing scale advantages concentrate microcontroller and RF transceiver production in Shenzhen and Dongguan clusters. MIIT enforces GB standards for wireless transmission power and cybersecurity compliance for networked devices. Shanghai and Beijing serve as test markets for premium energy monitoring variants before export scaling.
India
Municipal smart city infrastructure creates bulk procurement channels for streetlight and public facility monitoring distinct from consumer retail. BIS certification requirements and phased manufacturing programs under the PLI scheme shape local assembly strategies. Bangalore and Hyderabad technology corridors host firmware engineering teams serving domestic and export markets.
Smart Plug Market Key Industry Players
On the supply side, the industry is fragmented across router ecosystem bundlers, manufacturing-scale direct-to-consumer players, and specialist electrical component manufacturers. Strategic archetypes include ecosystem-integrated hardware vendors, vertically integrated Asian manufacturers, and legacy electrical infrastructure specialists. Competitive moves center on certification pipeline investments to satisfy tightening cybersecurity mandates and Matter protocol convergence to collapse hub fragmentation.
Among ecosystem-integrated hardware vendors, TP-Link Technologies leverages router-native bundling to sustain repeat purchases through unified app control. Xiaomi Inc. occupies a position exemplifying manufacturing-scale direct-to-consumer strategies, shipping millions of units annually through marketplace storefronts. Panasonic Corporation represents the legacy electrical infrastructure archetype, anchoring premium positioning through established industrial distribution relationships and compliance documentation depth.
| Leading Market Players |
|---|
| TP-Link Technologies |
| Panasonic Corporation |
| Xiaomi Inc. |
| Belkin International |
| D-Link Corporation |
| Leviton Manufacturing Co., Inc. |
| Honeywell International |
| EDIMAX Technology Co. Ltd. |
| Broadlink Technology Inc. |
| Others |
Cost & Logistics Intelligence
Microcontroller and RF transceiver fabrication clusters in East Asia concentrate upstream capacity, anchoring margin pools with contract manufacturers who command volume-based pricing leverage over mid-tier brands lacking captive silicon sourcing.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with three-tier pricing separating energy monitoring variants from basic Wi-Fi units from economy-grade Bluetooth models. Price differentiation hinges on certification depth—FCC Part 15 and CE marking tiers command premiums—and after-sales firmware support bundling. Cost compression in the economy tier is intensifying because Shenzhen manufacturing scale advantages erode regional competitor margins. Residential rental households exhibit highest price sensitivity, while commercial building operators absorbing plug-load management costs show lowest.
Supply Chain Analysis
Contract-manufacturing concentration sits with Foxconn, BYD Electronics, and Jabil holding capacity for consumer IoT assembly. Geographic supply concentration spans China, Vietnam, and Taiwan. Raw material dependencies include copper for relay contacts, rare earth elements for PCB substrates, and microcontroller silicon from TSMC and SMIC foundries. Single-source vulnerability in RF transceiver chipsets creates exposure to geopolitical trade restrictions. Distribution runs through Amazon and Alibaba marketplace algorithms that prioritize certified brands with cybersecurity documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as housing renovation cycles in Germany and Japan accelerate replacement demand for monitored electrical infrastructure.
For Market Incumbents: Harden firmware update infrastructure to satisfy EU Cyber Resilience Act obligations before mandatory compliance deadlines eliminate non-compliant product lines. Deepen certification laboratory relationships in Bavaria and Shenzhen to compress CE marking and MIIT approval timelines. Prioritize Matter protocol convergence to collapse current hub-fragmentation SKU proliferation. For New Entrants and Emerging Players: Build out white-space positions in India's municipal smart city procurement channels, where bulk streetlight and public facility monitoring contracts bypass saturated consumer retail. Target commercial building retrofit segments in California and New York municipal energy disclosure jurisdictions. Pursue direct-to-government sales angles with localized firmware engineering teams in Bangalore and Hyderabad. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with captive microcontroller sourcing and established OTA update infrastructure. Long-term viability across the five-to-ten year window favors archetypes with compliance documentation depth and router ecosystem bundling relationships. Monitor Matter certification pipeline velocity as the critical inflection signal for ecosystem consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-ecosystem compatibility collapses hub fragmentation across Apple, Google, Amazon, and Samsung platforms. |
| Firmware Infrastructure Investment | EU Cyber Resilience Act mandates security update obligations that eliminate non-compliant product lines from 2027. |
| Router Ecosystem Bundling | Checkout integration with mesh Wi-Fi systems captures repeat purchases through unified app control interfaces. |
| Energy Monitoring IC Integration | Sub-watt precision power measurement commands premium pricing in Germany's Building Energy Act retrofit demand. |
| Direct-to-Government Channel Development | India's smart city infrastructure creates bulk procurement channels distinct from algorithm-driven consumer retail. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with smart home hardware executives, regulatory compliance officers, firmware engineering directors, and Amazon marketplace category managers; and secondary validation against FCC equipment authorization databases, EU CE marking registries, MIIT GB standard filings, and customs trade records for microcontroller and RF component flows. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Forecast inputs considered protocol adoption curves, housing renovation permit volumes, and utility tariff restructuring timelines across the projection horizon. Segmentation dimensions modeled include product type, connectivity architecture, end-user category, and distribution channel. CAGRs derived from fitted growth curves applied to protocol-specific installed base projections and replacement cycle assumptions. Industry-specific inputs incorporated Matter certification pipeline data and EU Cyber Res Act implementation phasing.
Sensitivities concentrate around semiconductor supply disruptions, copper price volatility, and cybersecurity mandate enforcement intensity. Forecasts reflect assumptions on housing renovation cycle duration and protocol convergence velocity. Quarterly review of FCC certification backlogs, CE marking laboratory capacity, and Matter specification update releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Thailand Commercial Vehicles Lubricants Market
Others
Language Translation Device Market
Others
Computer on Module Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Global Hair Loss Treatment Products Market
Others
North America Halal Food and Beverage Market
Others
Linear Shaft Market
Others
Dry Washer Market
Others
Process Spectroscopy Market
Others
UK Cat Food Market
Others
Czech Republic Market
Others
Smart Home Platforms Market
Others
Internet of Things Testing Market
Others
North America Video Conferencing Hardware Market
Others
Vegan Confectionery Market
Others
US Automotive LED Lighting Market