
 Advertising Intelligence Solution Market | 2026-2036
Advertising Intelligence Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Advertising Intelligence Solution Market Outlook
First-party data is broadening the competitive moat for advertising intelligence vendors as cookie deprecation erodes legacy targeting economics. Kantar Media leverages its panel-based measurement heritage to sustain cross-platform comparability. Similarweb anchors its position through digital traffic intelligence that extends into competitive ad spend estimation. Adthena specializes in paid search intelligence, occupying a defensible niche in retail and financial services verticals.
An advertising intelligence solution is a technology platform that aggregates, processes, and visualizes competitive advertising data across channels, typically ingesting bid streams, creative repositories, and spend signals at latency thresholds under 100 milliseconds for real-time bidding applications. Its primary commercial purpose is to enable advertisers, agencies, and publishers to optimize media allocation and creative strategy against observable competitor behavior. Analytics tools command the deepest margin pools because clients treat competitive benchmarking as a recurring subscription necessity rather than a discretionary purchase. Cloud computing underpins the architecture that most vendors now deploy, though artificial intelligence capabilities are where product roadmaps differentiate fastest.
The EU AI Act and GDPR impose algorithmic transparency and consent-documentation burdens on any platform processing European consumer data for audience targeting. The FTC in the United States has intensified scrutiny of dark patterns and deceptive ad measurement, reshaping how platforms validate performance claims. Stakeholders must monitor whether emerging state-level privacy statutes fragment compliance requirements faster than vendor architectures can adapt.
Market Dynamics
Retail media networks are consolidating advertising intelligence demand as first-party data replaces deprecating third-party cookies, forcing vendors to rebuild attribution architectures around consent-verified identity graphs.
Growth Catalysts
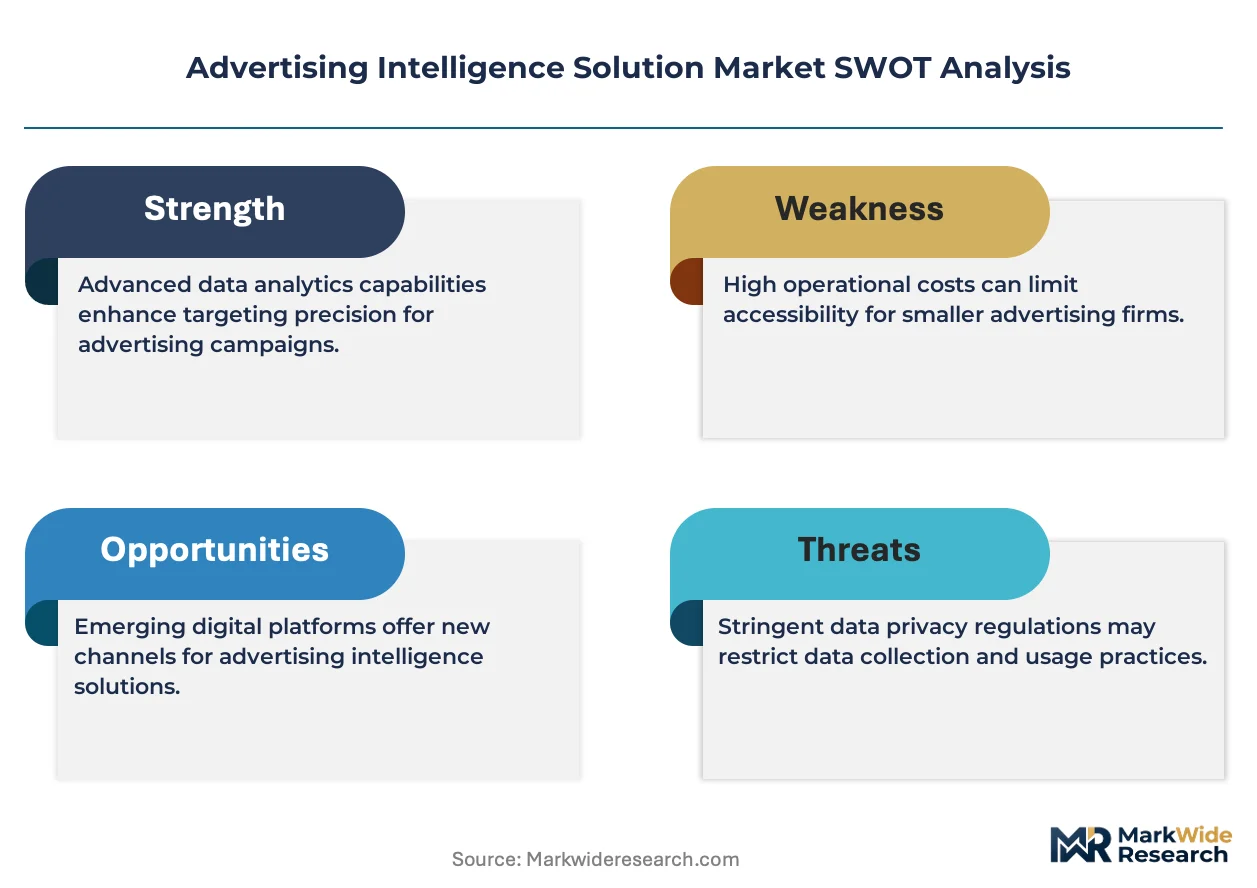
- EU AI Act compliance mandates:Algorithmic transparency requirements are compelling European advertisers to adopt third-party intelligence platforms that document decision logic and audit trails for automated bidding systems.
- Real-time bidding latency thresholds:Sub-100 millisecond processing demands are pulling cloud-native architectures into competitive parity with legacy on-premise installations.
- Financial services vertical expansion:Paid search intelligence adoption is accelerating among banking and insurance advertisers seeking competitive visibility into keyword auction dynamics.
Market Restraints
- GDPR consent-documentation burden:European data processing requires granular audit trails that inflate platform engineering overhead and slow product iteration cycles.
- Cloud infrastructure cost concentration:Compute-intensive AI model training ties vendor margins to hyperscaler pricing power in United States and European data center markets.
- Cross-platform measurement fragmentation:Walled-garden data policies prevent unified competitive benchmarking across Meta, Google, and Amazon advertising ecosystems.
Strategic Opportunities
- Connected TV ad intelligence:Streaming platform advertising growth creates unmet demand for competitive creative and spend visibility outside traditional digital channels.
- FTC transparency mandate tailwinds:United States regulatory pressure on dark patterns and deceptive measurement is accelerating advertiser migration to independently validated intelligence platforms.
- Retail media network convergence:Walmart, Target, and Instacart advertising platforms require specialized intelligence tools that bridge on-site and off-site attribution.
Industry Challenges
- Machine learning engineering scarcity:Bid stream processing and predictive modeling require specialized talent pools concentrated in San Francisco and London technology labor markets.
- Legacy system integration friction:Enterprise advertisers demand API compatibility with entrenched marketing cloud stacks from Salesforce and Adobe that resist modular replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advertising Intelligence Solution Market |
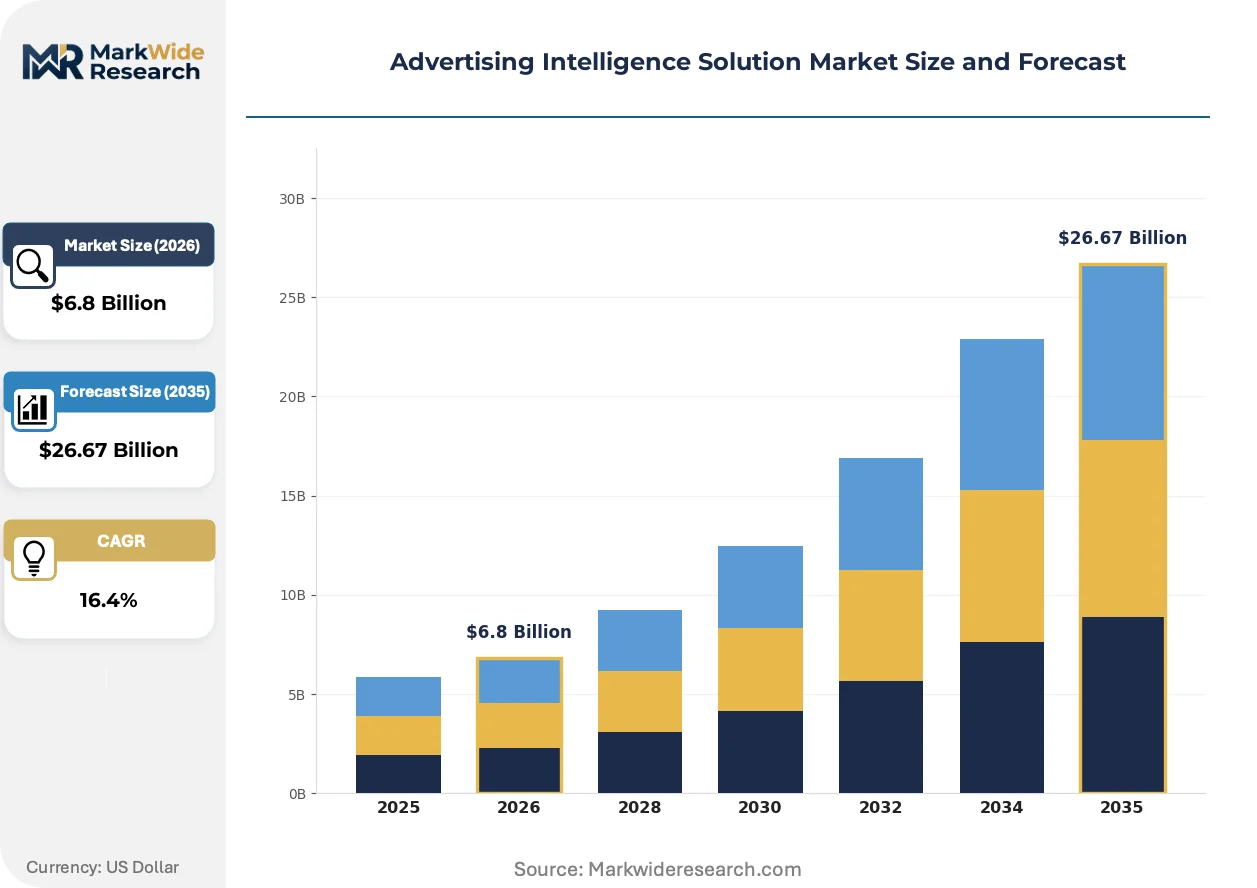
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Demand-Side Platforms, Supply-Side Platforms, Ad Exchanges, Analytics Tools Technology: Artificial Intelligence, Machine Learning, Big Data, Cloud Computing Usage Scenario: Real-Time Bidding, Audience Targeting, Campaign Management, Performance Analysis Client Type: Advertisers, Agencies, Publishers, Brands |
| Companies Covered | Sensor Tower Inc, Pathmatics Inc, Ebiquity plc, Kantar Media, The Nielsen Company LLC, SAS Institute Inc, Similarweb, AdClarity, Adthena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advertising Intelligence Solution Market Strategic Shifts
Artificial intelligence capabilities are differentiating advertising intelligence product roadmaps as cloud infrastructure commoditizes, with vendors racing to deploy predictive models that anticipate competitor moves before auction execution.
Generative AI for creative intelligence is electrifying competitive analysis workflows. The technology ingests competitor creative assets at scale to identify messaging patterns, visual hierarchies, and call-to-action strategies. Retail and financial services advertisers are deploying these tools to compress creative testing cycles from weeks to days. This capability is electrifying the shift from reactive competitive monitoring to proactive creative strategy formulation.
GDPR and the EU AI Act are tightening algorithmic accountability requirements for any platform processing European consumer data. Documentation burdens now extend to model training data provenance and automated decision explanations. Ad intelligence vendors serving multinational advertisers are restructuring data pipelines to isolate European processing from global operations, fragmenting product architectures.
Buyer concentration among retail media networks is compressing sales cycles and elevating procurement sophistication. Walmart and Amazon advertising teams now demand outcome-based pricing models tied to measurable competitive insights rather than seat-based subscriptions. This pattern is most visible in the United States, where retail media spend concentration exceeds other developed markets by significant margins.
Advertising Intelligence Solution Market Segmentation
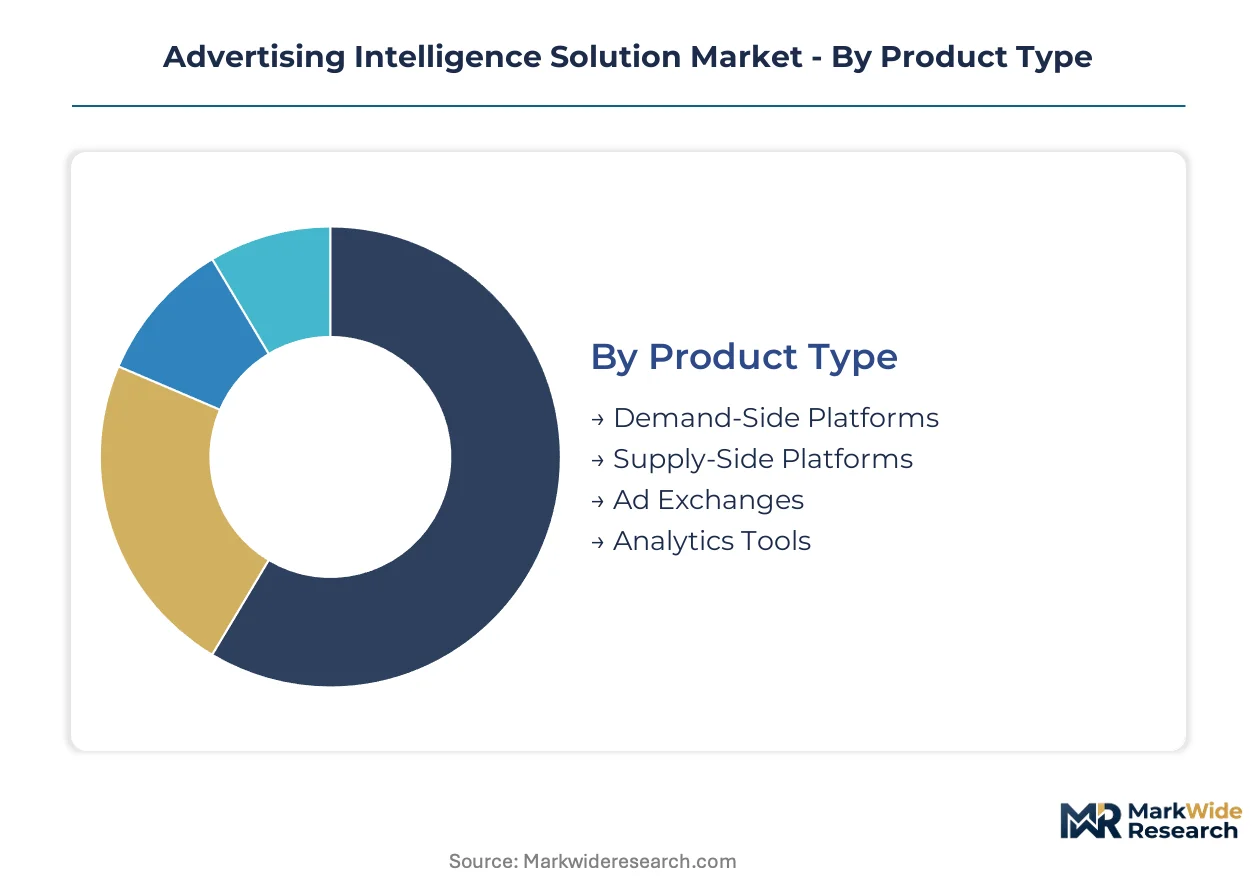
Segmentation in advertising intelligence solutions determines how vendors architect pricing, deployment complexity, and integration requirements. Buyers with disparate technical maturity and data sophistication demand fundamentally different product configurations.
Product Type:
Customization spans from fully configurable API-first stacks to standardized SaaS dashboards, with deployment overhead varying by an order of magnitude across the spectrum.
- Analytics Tools:Platforms delivering competitive benchmarking, spend estimation, and creative intelligence through visualization layers and automated reporting pipelines. Demand concentrates among mid-market agencies in the United States seeking subscription-based competitive visibility without engineering overhead. The FTC's transparency mandates accelerate migration from opaque legacy measurement toward independently validated analytics.
- Demand-Side Platforms:Buy-side technologies enabling programmatic media procurement with integrated bidding algorithms and audience segmentation capabilities. Retail media networks in the United States deploy these tools to manage first-party data activation across Walmart, Target, and Amazon advertising ecosystems. Cookie deprecation forces rebuilds around consent-verified identity graphs.
- Supply-Side Platforms:Publisher-facing technologies optimizing inventory yield through header bidding and real-time auction mechanics.
- Ad Exchanges:Neutral marketplaces matching buy-side demand with sell-side supply at sub-100 millisecond latency thresholds.
Leading the category by volume: Analytics Tools. Growing fastest: Demand-Side Platforms.
Technology:
Cost tiers separate capital-intensive infrastructure investments from margin-light commodity compute, with AI capabilities commanding premium pricing multiples.
- Artificial Intelligence:Predictive models anticipating competitor bidding patterns and automating creative optimization workflows. Financial services advertisers in the United States deploy these capabilities for keyword auction intelligence in banking and insurance verticals. Generative AI for creative analysis compresses testing cycles from weeks to days.
- Cloud Computing:Elastic infrastructure provisioning that scales bid stream processing and model training workloads dynamically. Vendors tie margin structures to hyperscaler pricing power in United States and European data center markets. EU AI Act compliance forces architectural fragmentation isolating European processing from global operations.
- Machine Learning:Statistical models trained on historical auction data to forecast performance outcomes.
- Big Data:Distributed storage and processing architectures handling petabyte-scale bid stream ingestion.
Capturing the largest investment share: Cloud Computing. Expanding most quickly: Artificial Intelligence.
Usage Scenario:
Application maturity separates established workflow automation from emerging predictive capabilities, with latency requirements dictating architectural choices.
- Real-Time Bidding:Sub-100 millisecond auction participation requiring edge-deployed decision engines and pre-cached audience segments. United States programmatic traders demand these capabilities for high-frequency retargeting and prospecting campaigns. Cloud-native architectures achieve parity with legacy on-premise installations on latency benchmarks.
- Performance Analysis:Post-campaign measurement and attribution reporting validating media effectiveness against competitive benchmarks. GDPR consent-documentation burdens inflate engineering overhead for European deployments, slowing product iteration cycles relative to United States markets.
- Audience Targeting:Identity resolution and segmentation activating first-party data against deprecating third-party cookies.
- Campaign Management:Workflow orchestration across creative trafficking, budget pacing, and cross-channel frequency capping.
Dominating transaction volume: Real-Time Bidding. Gaining share fastest: Performance Analysis.
Client Type:
Customer type determines procurement sophistication, with enterprise advertisers demanding outcome-based pricing and modular API integration.
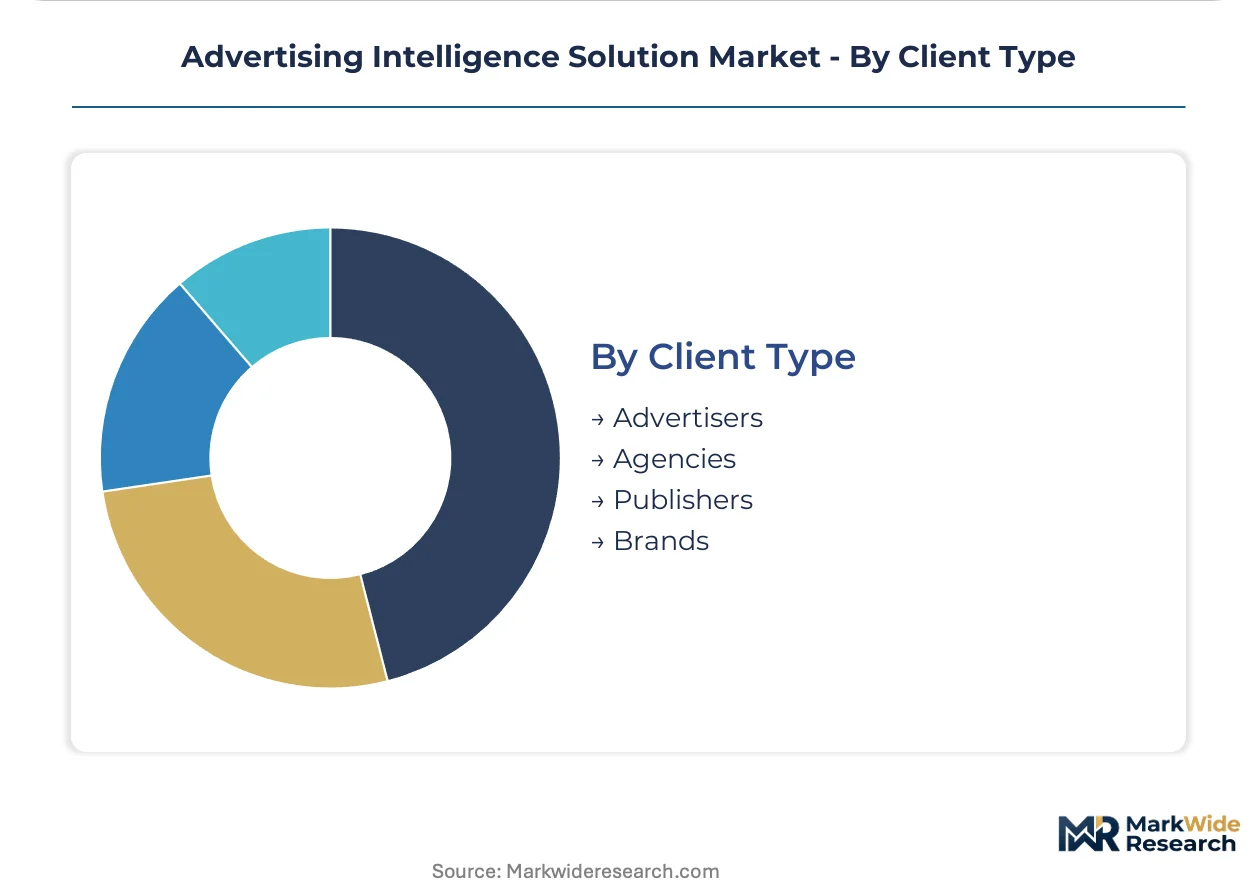
- Agencies:Intermediaries managing media investment across multiple advertiser clients, requiring multi-tenant dashboards and white-labeled reporting. United States holding companies consolidate vendor relationships, compressing sales cycles and elevating pricing pressure. FTC scrutiny of deceptive measurement accelerates adoption of independently validated intelligence platforms.
- Brands:Direct advertisers building in-house capabilities to reduce agency dependency and capture first-party data leverage. Retail media network convergence at Walmart, Target, and Instacart drives specialized tool procurement bridging on-site and off-site attribution.
- Advertisers:Performance-focused buyers optimizing conversion metrics across direct-response campaigns.
- Publishers:Inventory owners maximizing yield through competitive intelligence on prevailing CPM benchmarks.
Generating the largest revenue pool: Agencies. Climbing the fastest: Brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in the United States and Germany concentrate advertising intelligence R&D through tax-advantaged research facilities. These zones attract hyperscaler partnerships and vendor engineering centers. Regulatory divergence between jurisdictions fragments platform architectures.
United States
FTC transparency mandates on dark patterns and deceptive measurement accelerate advertiser migration to independently validated intelligence platforms. The CLOUD Act and state-level privacy statutes in California and Virginia create compliance complexity for cross-border data flows. New York and San Francisco host the densest concentrations of machine learning engineering talent for bid stream processing.
Germany
GDPR consent-documentation requirements inflate platform engineering overhead and slow product iteration cycles relative to North American markets. The EU AI Act imposes algorithmic transparency burdens on automated bidding systems processing European consumer data. Berlin and Munich anchor vendor data center operations serving DACH-region advertisers.
United Kingdom
Post-Brexit regulatory divergence from EU data protection frameworks creates dual compliance tracks for multinational platforms. The Competition and Markets Authority scrutinizes ad tech concentration, elevating demand for third-party competitive intelligence. London's financial services sector drives paid search intelligence adoption among banking and insurance advertisers.
France
CNIL enforcement actions on cookie consent mechanisms force attribution architecture rebuilds around verified identity graphs. The EU AI Act's risk-based classification system subjects high-stakes advertising algorithms to conformity assessment requirements. Paris hosts regional headquarters for major analytics vendors serving Southern European markets.
Japan
METI guidelines on data portability and interoperability reduce walled-garden friction for cross-platform competitive benchmarking. Privacy regulations lag European stringency, permitting faster product iteration cycles for global platforms. Tokyo's advertising technology corridor concentrates demand-side platform engineering for Asia-Pacific programmatic markets.
Advertising Intelligence Solution Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with analytics tool vendors commanding recurring subscription revenue pools while infrastructure providers compete on hyperscaler pricing. The vendor landscape organizes into three tiers: panel-based measurement incumbents, digital-native traffic intelligence platforms, and vertical-specialized search intelligence providers. Consolidation pressure intensifies as retail media networks demand outcome-based pricing tied to measurable competitive insights. Dominant competitive moves include M&A to capture first-party data assets and strategic partnerships with cloud hyperscalers to secure latency advantages.
Within the panel-based measurement tier, Kantar Media and Nielsen exemplify heritage research organizations adapting cross-platform comparability for programmatic environments. Among digital-native traffic intelligence providers, Similarweb occupies a position bridging competitive spend estimation with audience behavior analytics. Adthena represents the vertical-specialist archetype, anchoring paid search intelligence capabilities for retail and financial services advertisers. These three companies illustrate divergent strategic paths: heritage panel extension, digital signal aggregation, and vertical workflow depth.
| Leading Market Players |
|---|
| Sensor Tower Inc |
| Pathmatics Inc |
| Ebiquity plc |
| Kantar Media |
| The Nielsen Company LLC |
| SAS Institute Inc |
| Similarweb |
| AdClarity |
| Adthena |
| Others |
Value Chain & Pricing Dynamics
Cloud hyperscaler partnerships anchor supply positioning and pricing power for advertising intelligence vendors, with latency-sensitive bid stream processing tethering margin structures to Amazon Web Services, Microsoft Azure, and Google Cloud Platform pricing in United States and European data center markets. This captive infrastructure dependency forces vendors to absorb compute cost volatility while retail media networks compress pricing through outcome-based procurement models.
Pricing Analysis
Volume concentrates in seat-based SaaS subscriptions while margin pools deepen in API-first analytics tiers with customization overlays. Price differentiation hinges on real-time latency guarantees under 100 milliseconds and AI-powered predictive modeling depth. Pricing pressure stems from retail media network procurement sophistication demanding measurable competitive insights over fixed subscriptions. Mid-market agencies exhibit highest price sensitivity; enterprise advertisers with walled-garden transparency mandates show lowest.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale advertiser demand while agency intermediaries aggregate mid-market volume through holding company procurement frameworks. Bid stream data ingestion draws from United States, Germany, and United Kingdom data center clusters. Raw material dependencies span cloud compute instances, GPU clusters for model training, and consent-verified identity graph licensing. Single-source vulnerability concentrates in hyperscaler pricing power. Distribution runs through vendor-direct sales, agency channel partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning engineering scarcity props pricing power for vendors with captive talent pipelines, constraining supply expansion faster than retail media network demand growth.
For Market Incumbents: Deepen first-party data asset integration to defend against vertical-specialist entrants exploiting retail media network convergence. Expand Berlin and San Francisco engineering centers to capture scarce bid stream processing talent. Lock in cloud hyperscaler capacity reservations to neutralize infrastructure cost volatility. For New Entrants and Emerging Players: Capture connected TV ad intelligence white space where competitive creative visibility remains underdeveloped relative to digital channels. Target financial services paid search intelligence as the most penetrable vertical given banking and insurance advertisers' auction dynamics complexity. Pursue outcome-based pricing alignment with Walmart and Target advertising teams as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by cloud hyperscalers seeking vertical AI capabilities and by holding companies consolidating agency technology stacks. Long-term viability favors vendors with defensible data moats around panel-based measurement heritage or proprietary traffic signal aggregation. Watch FTC enforcement intensity on dark patterns as inflection indicator for independent validation platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Partnership | Secures consent-verified identity graph access for cookie-deprecating attribution architectures. |
| Generative AI Creative Intelligence | Compresses competitor creative testing cycles from weeks to days for retail advertisers. |
| EU AI Act Compliance Architecture | Isolates European processing to satisfy algorithmic transparency and audit trail mandates. |
| Connected TV Intelligence Expansion | Captures unmet competitive spend visibility demand outside traditional digital channels. |
| Cloud Hyperscaler Strategic Partnership | Secures sub-100 millisecond latency advantages through edge-deployed infrastructure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with programmatic traders, agency procurement directors, platform engineers, and retail media network advertising leads validated demand-side assumptions. SEC 10-K disclosures, FTC enforcement records, EU AI Act implementation guidance, and cloud hyperscaler capex reports supplied quantitative benchmarks. Bottom-up vendor revenue triangulation against top-down advertising spend allocation models reconciled market sizing.
Data-stream reconciliation across real-time bidding transaction volumes, competitive intelligence platform subscriptions, and retail media network advertising revenues informed the analytical framework. Segmentation dimensions spanned product type, underlying technology, usage scenario latency requirements, and client procurement sophistication. CAGRs derived from trend extrapolation of first-party data adoption curves and regulatory compliance cost trajectories. Bid stream processing latency benchmarks and generative AI creative intelligence deployment rates served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GDPR enforcement variance, EU AI Act conformity assessment timelines, and hyperscaler pricing power consolidation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Turkey Health and Medical Insurance Market
Others
Global Phablets and Superphones Market
Others
Aboveground Storage Tanks Market
Others
Data Center CPU Market
Others
Short Video Applications Market
Others
Language Translation Device Market
Others
India Home Automation Market
Others
Server Market
Others
Belt Loader Market
Others
Disposable Non Woven Sponge Market
Others
Moveable Water Tap Market
Others
Bicycle Panniers Market
Others
APAC Machine Vision Systems Market
Others
Animal Feed Alternative Protein Market
Others
Middle East and Africa Home Care Packaging Market
Others
Signal Transformer Market