
 Operator Training Simulator Market | 2026-2036
Operator Training Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Operator Training Simulator Market Analysis
Cloud-native rendering is decoupling training fidelity from dedicated hardware investments. Siemens leverages its industrial automation installed base to anchor simulator deployments in European manufacturing. AVEVA Group Limited sustains competitive positioning through deep integration with asset performance management platforms. Aspen Technology Inc. specializes in process-specific models for downstream energy clients.
An operator training simulator replicates industrial control room environments through mathematical process modeling and human-machine interface emulation, typically achieving real-time response latencies below 50 milliseconds to ensure physiological fidelity. These systems enable risk-free rehearsal of abnormal scenarios including emergency shutdowns and equipment failures. Virtual reality simulators represent the fastest-expanding product category as hardware costs decline and field-of-view resolutions improve. Machine learning technology enables adaptive difficulty scaling that personalizes competency progression, concentrating margin pools in subscription-based training-as-a-service offerings.
The US Occupational Safety and Health Administration mandates documented operator qualification programs for hazardous energy control, directly stimulating recurring simulator-based assessment demand. The EU Machinery Directive's safety training requirements, enforced through CE marking conformity assessments, shape product design standards for European deployments. Stakeholders must monitor evolving AI governance frameworks that could impose explainability requirements on adaptive training algorithms.
Market Dynamics
Cloud-native rendering architectures are dismantling the hardware-dependency model that historically gated simulator fidelity, compressing deployment timelines from months to weeks and enabling subscription-based commercialization across mid-market industrial operators previously priced out of capital-intensive systems.
Growth Catalysts
- OSHA Operator Qualification Mandates:Documented competency requirements for hazardous energy control under US regulations force utilities toward recurrent simulator-based assessment protocols.
- EU Machinery Directive CE Marking:Safety training conformity assessments embedded in European industrial automation standards mandate recurrent certification cycles.
- AI-Driven Scenario Generation:Machine learning algorithms replacing static scripted modules enable adaptive difficulty scaling that personalizes competency progression.
Market Restraints
- High-Fidelity Hardware Costs:Specialized motion platforms and field-of-view display arrays for virtual reality deployments require substantial upfront capital allocation.
- Process Model Calibration Complexity:Mathematical fidelity demands for real-time response latencies below 50 milliseconds necessitate extensive domain-specific engineering.
- Legacy Control System Integration:Proprietary communication protocols in installed industrial automation bases create technical friction during simulator deployment.
Strategic Opportunities
- Training-as-a-Service Subscriptions:Cloud delivery models concentrate margin pools in recurring revenue streams rather than perpetual license sales.
- Downstream Energy Process Specialization:Refinery and petrochemical operators seek simulator modules tailored to specific unit operations and emergency scenarios.
- German Industrial Automation Standards:Recurrent certification mandates under national industrial safety frameworks create predictable replacement cycles.
Industry Challenges
- Control Systems Engineering Talent Scarcity:The intersection of process modeling, human factors design, and real-time software engineering limits deployment velocity.
- Explainability Requirements for Adaptive Algorithms:Emerging AI governance frameworks threaten to impose auditability constraints on machine learning-driven training personalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operator Training Simulator Market |
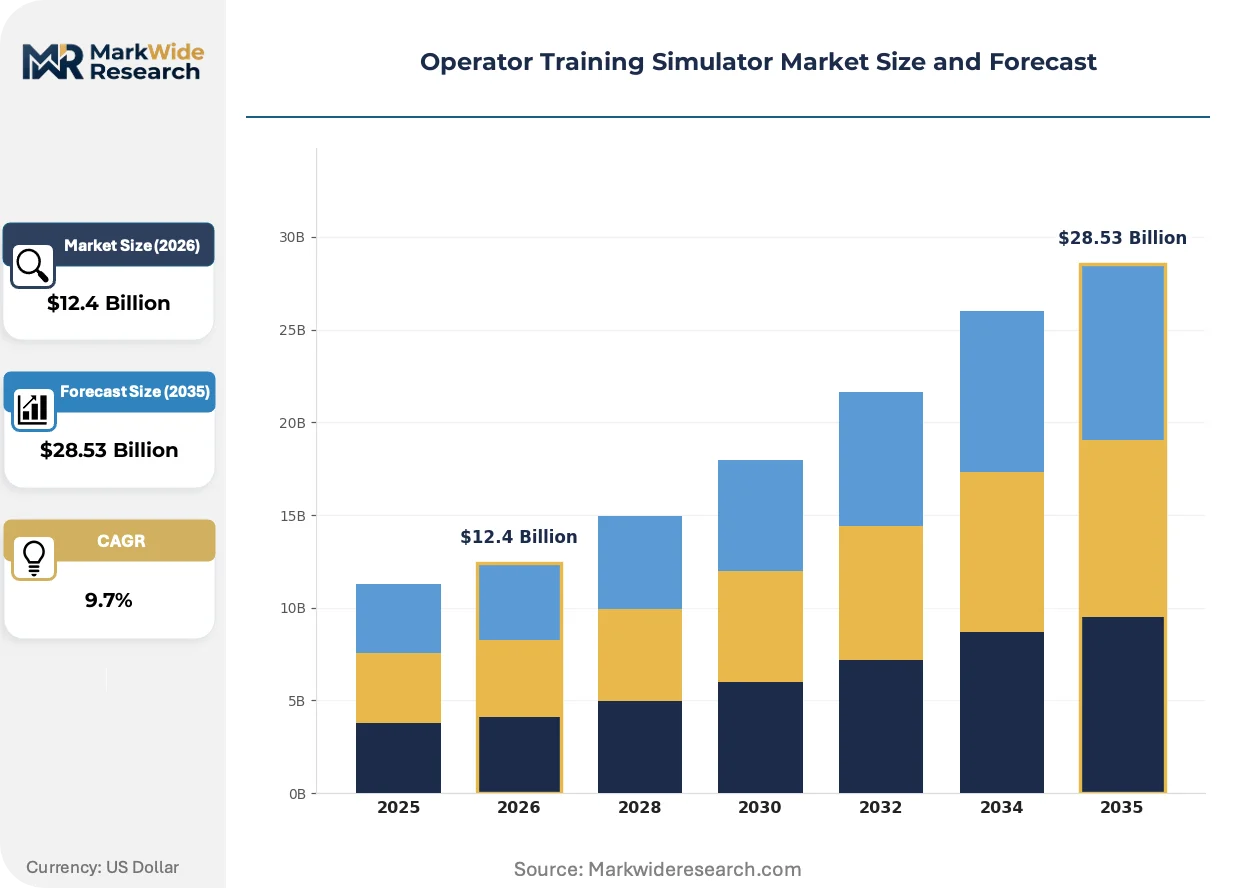
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PC-Based Simulators, Desktop Simulators, Virtual Reality Simulators, Web-Based Simulators Technology: Augmented Reality, Machine Learning, 3D Graphics, Gamification End User: Aerospace, Energy Sector, Manufacturing, Healthcare Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | ANDRITZ, AVEVA Group Limited, Aspen Technology Inc., ABB Ltd., Tecnatom, TRAX Energy Solutions, Schneider Electric, Siemens, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operator Training Simulator Market Emerging Trajectories
Immersive technologies are compressing the hardware cost barrier that historically segmented the simulator market, while regulatory pressure on documented operator competency accelerates replacement of classroom-based training protocols.
Virtual reality simulators are overtaking projection-based cave automatic virtual environments as the dominant immersive platform. Power grid operators across North America are deploying head-mounted displays with improved field-of-view resolutions for emergency scenario rehearsal. This shift is overtaking the dedicated projection room model that required permanent facility allocation.
The EU AI Act's risk classification framework for algorithmic decision systems is reshaping product roadmaps for adaptive training platforms. Simulator vendors must now architect explainability features into machine learning modules that personalize difficulty progression. European manufacturing deployments face the most immediate compliance pressure, with conformity assessment timelines extending procurement cycles.
Buyers are unbundling after-sales service from initial system procurement, pressuring vendors toward standalone maintenance contracts and remote technical support subscriptions. Industrial automation end-users in Germany and the United States now expect cloud-based scenario library updates separate from platform licensing. This purchasing pattern shift is most pronounced among energy utilities with distributed control room networks requiring synchronized training content deployment.
Operator Training Simulator Market Segmentation
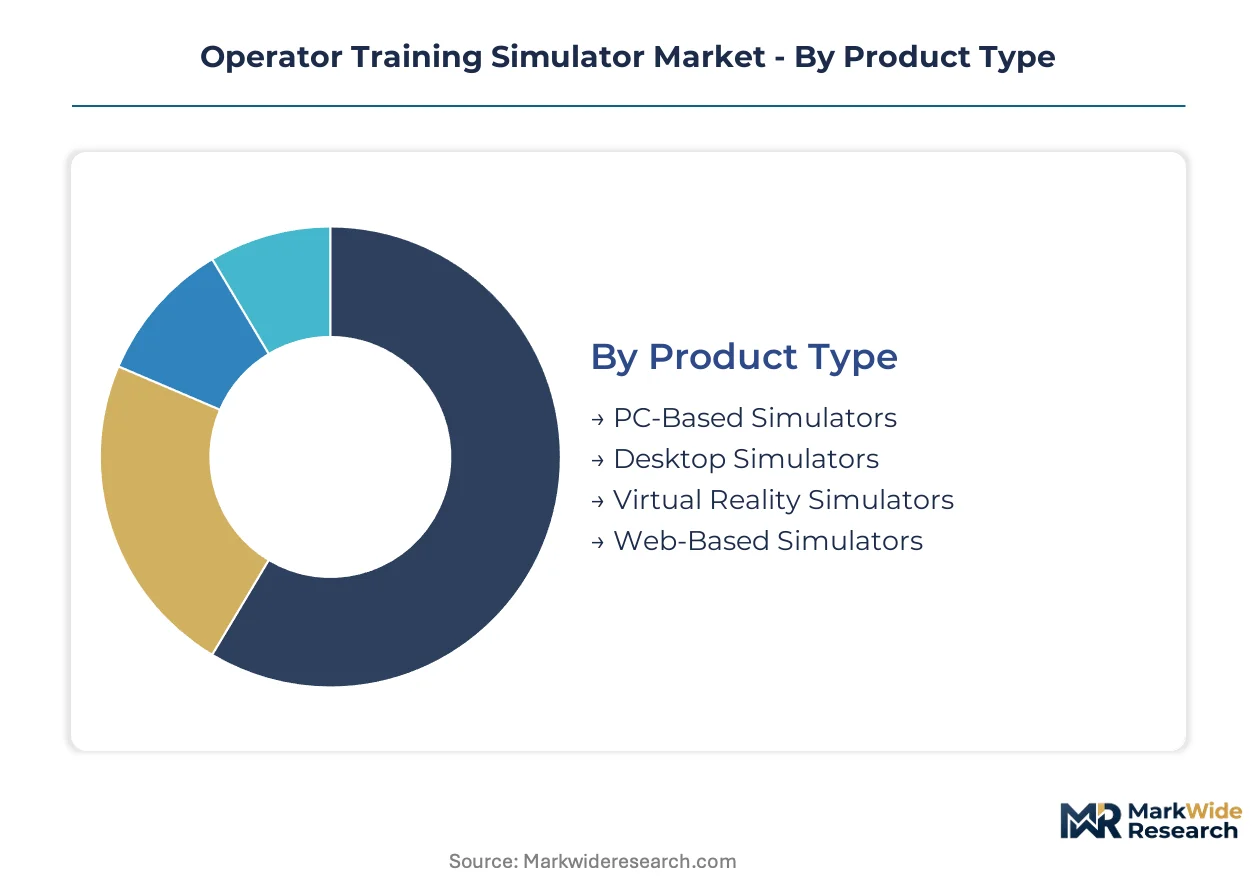
Simulator architecture choices determine capital intensity and recurring revenue potential. Training fidelity requirements diverge sharply between safety-critical energy applications and routine manufacturing protocols. Procurement patterns reveal a decisive shift from perpetual licenses toward consumption-based commercialization.
Product Type:
Volume deployments favor low-cost entry points, while premium positioning concentrates in immersive hardware configurations.
- PC-Based Simulators:These systems run on standard computing hardware with software-emulated control interfaces, achieving response latencies sufficient for procedural training without specialized motion platforms. Manufacturing facilities in Germany deploy these for recurrent certification cycles under national industrial safety frameworks, constrained by limited physiological fidelity during emergency scenario rehearsal.
- Virtual Reality Simulators:Head-mounted displays with expanded field-of-view resolutions replicate control room spatial relationships through stereoscopic rendering. Power grid operators across the United States adopt these for OSHA-mandated hazardous energy control qualification, driven by declining hardware costs and eliminated facility construction requirements.
- Desktop Simulators:Compact form factors integrate multiple display panels with simplified input devices for space-constrained training environments.
- Web-Based Simulators:Browser-delivered platforms enable distributed access without local installation, serving remote workforce populations.
Mature deployment sits with PC-Based Simulators. Newer deployment is concentrated in Virtual Reality Simulators.
Technology:
Adaptive algorithms command pricing premiums against static content libraries, reshaping vendor margin structures.
- Machine Learning:Algorithmic modules analyze operator performance patterns to dynamically adjust scenario difficulty and failure injection timing. European deployments face extended procurement cycles as vendors architect explainability features for EU AI Act conformity assessments, with risk classification frameworks imposing auditability requirements on personalized training pathways.
- 3D Graphics:Real-time rendering engines process mathematical process models into visually coherent industrial environments, maintaining sub-50 millisecond response latencies essential for physiological fidelity. Energy utilities prioritize these systems for control room replication accuracy, constrained by specialized engineering talent scarcity at the intersection of process modeling and real-time software development.
- Augmented Reality:Overlay graphics integrate digital information with physical equipment views for field maintenance training.
- Gamification:Achievement mechanics and competitive scoring structures accelerate engagement in routine competency drills.
Established integration sits with 3D Graphics. Expanding most quickly is Machine Learning.
End User:
Regulatory enforcement intensity determines replacement cycle predictability and contract duration.
- Energy Sector:Power generation, transmission, and distribution operators deploy high-fidelity replicas of distributed control systems for emergency shutdown rehearsal and abnormal scenario response. US utilities face recurring assessment mandates under OSHA operator qualification requirements for hazardous energy control, creating predictable demand for simulator-based competency validation.
- Manufacturing:Industrial automation environments utilize training platforms for robot programming, assembly line coordination, and safety protocol adherence. German manufacturing bases drive replacement cycles through recurrent certification requirements embedded in national industrial safety frameworks and CE marking conformity assessments.
- Aerospace:Flight crew and maintenance personnel training demands extreme scenario fidelity for certification credit.
- Healthcare:Surgical and diagnostic procedure simulation emphasizes haptic feedback and patient-specific anatomical variation.
Regulatory pressure concentrates in Energy Sector. Technology transfer accelerates in Healthcare.
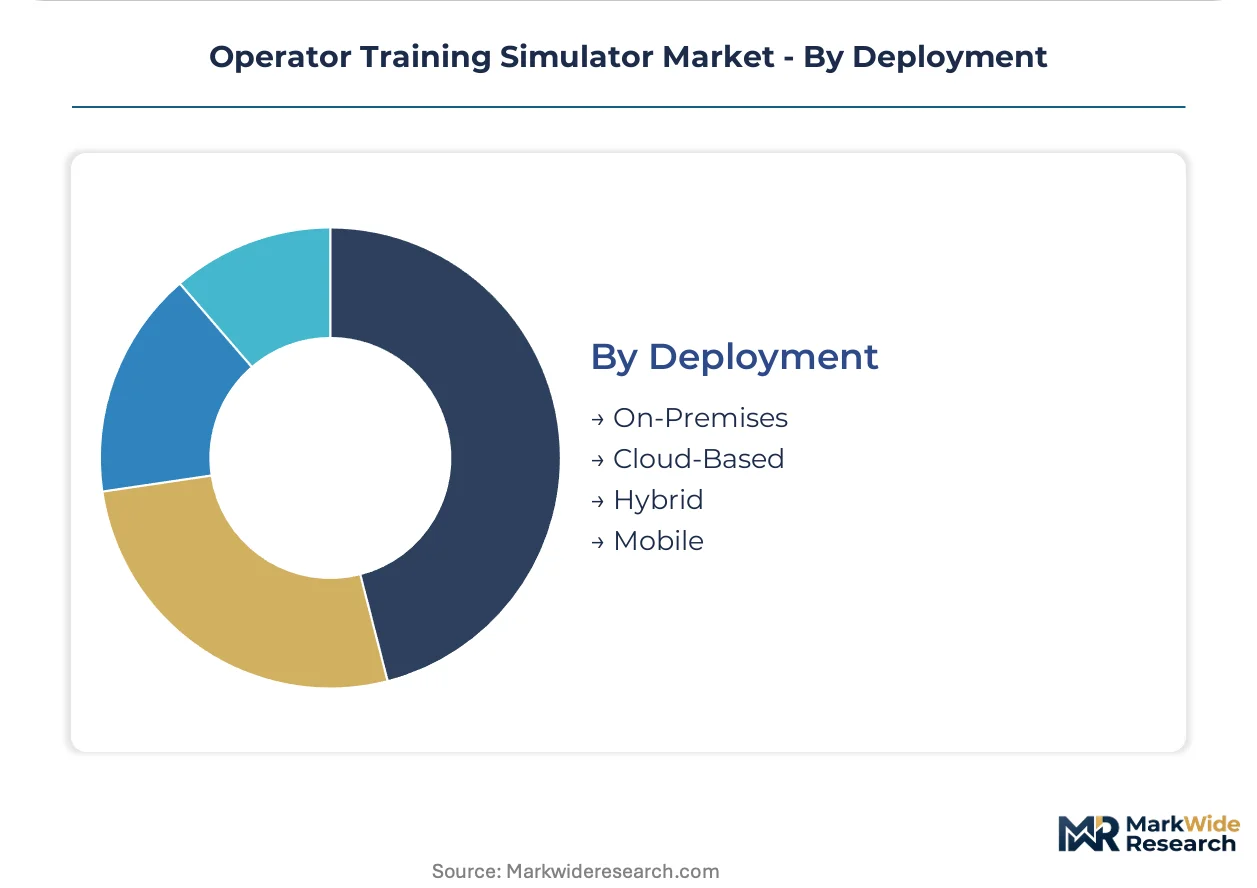
Deployment:
Cloud architectures are dismantling hardware-dependency models that historically gated market access.
- Cloud-Based:Remote rendering and scenario library hosting compress deployment timelines from months to weeks, enabling subscription-based commercialization across mid-market operators previously excluded by capital-intensive procurement. Energy utilities with distributed control room networks now expect synchronized training content deployment without on-site infrastructure construction.
- On-Premises:Local installation maintains data sovereignty and network isolation for classified or critical infrastructure environments. Aerospace and defense contractors mandate these configurations for flight simulator deployments, constrained by substantial upfront capital allocation for dedicated motion platforms and display arrays.
- Hybrid:Split architectures process sensitive control system interfaces locally while hosting scenario content remotely.
- Mobile:Tablet and smartphone delivery supports just-in-time procedural reference and abbreviated skill reinforcement.
Legacy dominance persists in On-Premises. Steepest expansion trajectory belongs to Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in industrial automation clusters where regulatory mandates enforce recurrent operator certification cycles, with Germany, the United States, and Japan anchoring procurement volumes through safety-critical energy and manufacturing protocols.
United States
Power grid operators drive simulator deployment for emergency scenario rehearsal and abnormal response training. OSHA mandates documented operator qualification programs for hazardous energy control, forcing utilities toward recurrent assessment protocols. The Texas Gulf Coast petrochemical corridor sustains demand for process-specific training modules tailored to refinery unit operations.
Germany
Industrial automation standards mandate recurrent certification cycles across manufacturing facilities. The EU Machinery Directive's CE marking conformity assessments shape product design requirements for European deployments. Bavaria's automotive and machinery clusters anchor premium-tier simulator installations for robot programming and assembly line coordination training.
Japan
Power utilities and heavy manufacturing bases deploy high-fidelity control room replicas for safety-critical operations. METI industrial safety frameworks enforce documented competency validation for energy sector personnel. The Chubu region around Nagoya concentrates demand from automotive and aerospace manufacturing requiring precision motion platform installations.
China
State-owned power generation and petrochemical operators expand simulator procurement for grid modernization and refinery safety protocols. National energy regulators impose documented training requirements for hazardous process control. The Yangtze River Delta industrial corridor drives volume deployment of PC-based systems for manufacturing certification cycles.
South Korea
Semiconductor and shipbuilding industries adopt immersive training platforms for cleanroom operations and vessel control systems. The country's national industrial safety regulator mandates recurrent competency assessment for hazardous energy environments. The Busan-Ulsan manufacturing belt anchors demand for virtual reality deployments in heavy industrial applications.
Operator Training Simulator Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors integrate simulator platforms with adjacent asset performance and industrial automation systems. The vendor base fragments across specialized process modelers, immersive hardware providers, and control system integrators. Three archetypes occupy distinct positions: industrial automation conglomerates leveraging installed base relationships, pure-play software specialists concentrating subscription-based training-as-a-service, and energy sector engineering firms with captive process expertise. M&A activity and technology licensing agreements constitute the primary competitive vectors as incumbents acquire machine learning capabilities and cloud delivery infrastructure.
Among industrial automation conglomerates, Siemens and ABB Ltd. exemplify the installed-base-leverage archetype through deep integration with existing control system deployments. AVEVA Group Limited occupies a position within the software specialist tier, anchoring competitive positioning through platform integration with asset performance management systems. Aspen Technology Inc. represents the process-specific specialization vector, concentrating downstream energy modeling expertise for refinery and petrochemical clients.
| Leading Market Players |
|---|
| ANDRITZ |
| AVEVA Group Limited |
| Aspen Technology Inc. |
| ABB Ltd. |
| Tecnatom |
| TRAX Energy Solutions |
| Schneider Electric |
| Siemens |
| Yokogawa Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up software specialists anchor pricing discipline through recurring revenue concentration, while their fragmented component sourcing across Asian electronics hubs compresses hardware margins and extends procurement cycles for immersive display arrays.
Pricing Analysis
Volume deployments of PC-based simulators run on thin margins, while premium VR configurations capture expanded margins through motion platform bundling. Pricing stratifies across certification-grade fidelity tiers, with OSHA-mandated assessment protocols commanding premium positioning against routine manufacturing drills. Cost compression in entry-level hardware is intensifying because cloud-native rendering eliminates dedicated facility construction. Mid-market industrial operators in Germany exhibit acute price sensitivity, whereas US energy utilities prioritize compliance-grade documentation over unit economics.
Supply Chain Analysis
Freight cost volatility from Asian electronics corridors is elevating landed costs for head-mounted display assemblies and real-time rendering chipsets. Component manufacturing concentrates in Taiwan, South Korea, and China, with specialized motion platform fabrication anchored in Germany and Japan. The supply chain draws from precision optical sensors, high-refresh-rate panels, and industrial-grade compute modules. Single-source vulnerability sits with advanced GPU allocations for real-time process modeling. Distribution runs through direct vendor relationships with industrial automation conglomerates and certified system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
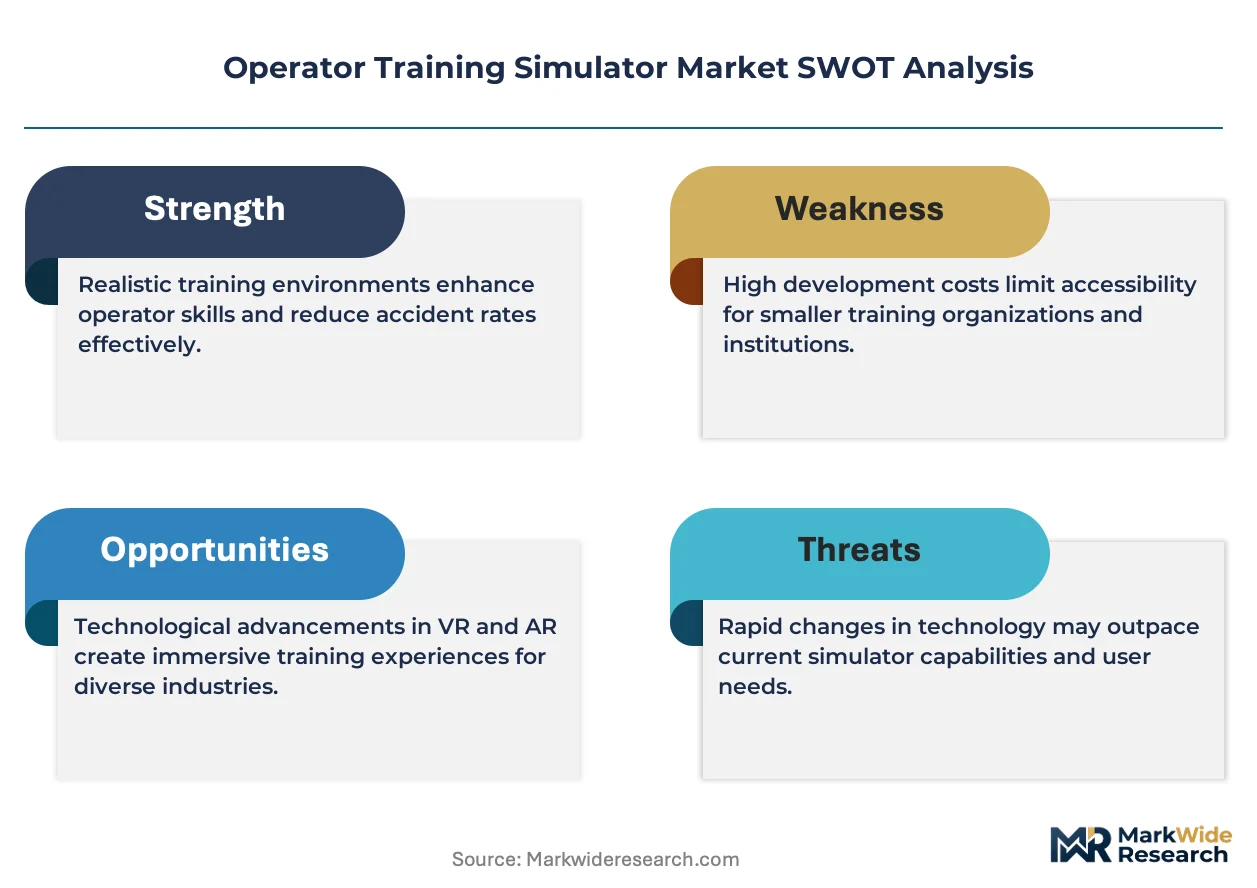
Control systems engineering talent scarcity constrains deployment velocity, propping pricing power for vendors with captive process modeling expertise and cloud delivery infrastructure.
For Market Incumbents: Deepen integration with asset performance management platforms to lock in switching costs against pure-play SaaS entrants. Prioritize explainability architecture investments ahead of EU AI Act enforcement timelines. Acquire machine learning specialists to close capability gaps in adaptive difficulty algorithms. For New Entrants and Emerging Players: Industrial automation channel partners offer the lowest-friction path to qualified manufacturing leads in Germany and the US Gulf Coast. White-space concentrates in mid-market energy utilities previously excluded by capital-intensive on-premises procurement. Target cloud-based subscription positioning against perpetual license incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor process-specific engineering firms with downstream energy captive relationships in the Texas petrochemical corridor. Long-term viability hinges on recurring revenue mix and AI governance compliance infrastructure. Monitor EU AI Act conformity assessment timeline extensions as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens switching costs through asset performance management coupling with Siemens and AVEVA deployments. |
| Acquisition of Specialist Firm | Secures captive process modeling expertise for refinery and petrochemical scenario libraries. |
| Geographic Expansion | Captures German recurrent certification cycles under Machinery Directive CE marking requirements. |
| Product Launch | Positions cloud-native VR simulators for OSHA-mandated hazardous energy control assessment. |
| Strategic Partnership | Accelerates machine learning explainability compliance ahead of EU AI Act risk classification enforcement. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with control room operators, industrial automation procurement leads, EPC contractors, and simulator platform engineers. OSHA enforcement databases, EU Machinery Directive conformity assessment registers, FERC utility filings, and hyperscaler cloud infrastructure disclosures provided demand-side validation. Bottom-up deployment tracking across energy utilities and manufacturing facilities triangulated against top-down industrial automation spend estimates.
Data-stream reconciliation across product architecture, technology module, and end-user vertical dimensions informed the analytical framework throughout the projection horizon. Segmentation modeling captured deployment mode, fidelity tier, and regional regulatory cluster variations. CAGRs derived from installed base replacement cycles, certification mandate frequencies, and cloud adoption elasticity parameters. Scenario library update frequencies and adaptive algorithm penetration curves served as industry-specific forecast inputs.
Caveats apply where AI governance explainability requirements, control systems engineering talent availability, or cloud infrastructure cost curves could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fluorapatite Market
Others
GCC Health and Wellness Market
Others
Lepidolite Market
Others
Fresh Pears Market
Others
Biopharma Plastics Market
Others
Europe Street Lighting Market
Others
Stand-Up Pouch Valves Market
Others
Digital Media Adaptor (DMA) Market
Others
Europe Refrigerated Display Cases Market
Others
Europe Astrology Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
Inflight Entertainment Solutions Market
Others
Reusable Wine Bags Market
Others
Managed Testing Services Market
Others
Handheld Mobile Computers Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market