
 Global Optical Coordinate Measuring Machine Market | 2026-2036
Global Optical Coordinate Measuring Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Coordinate Measuring Machine Market Foresight
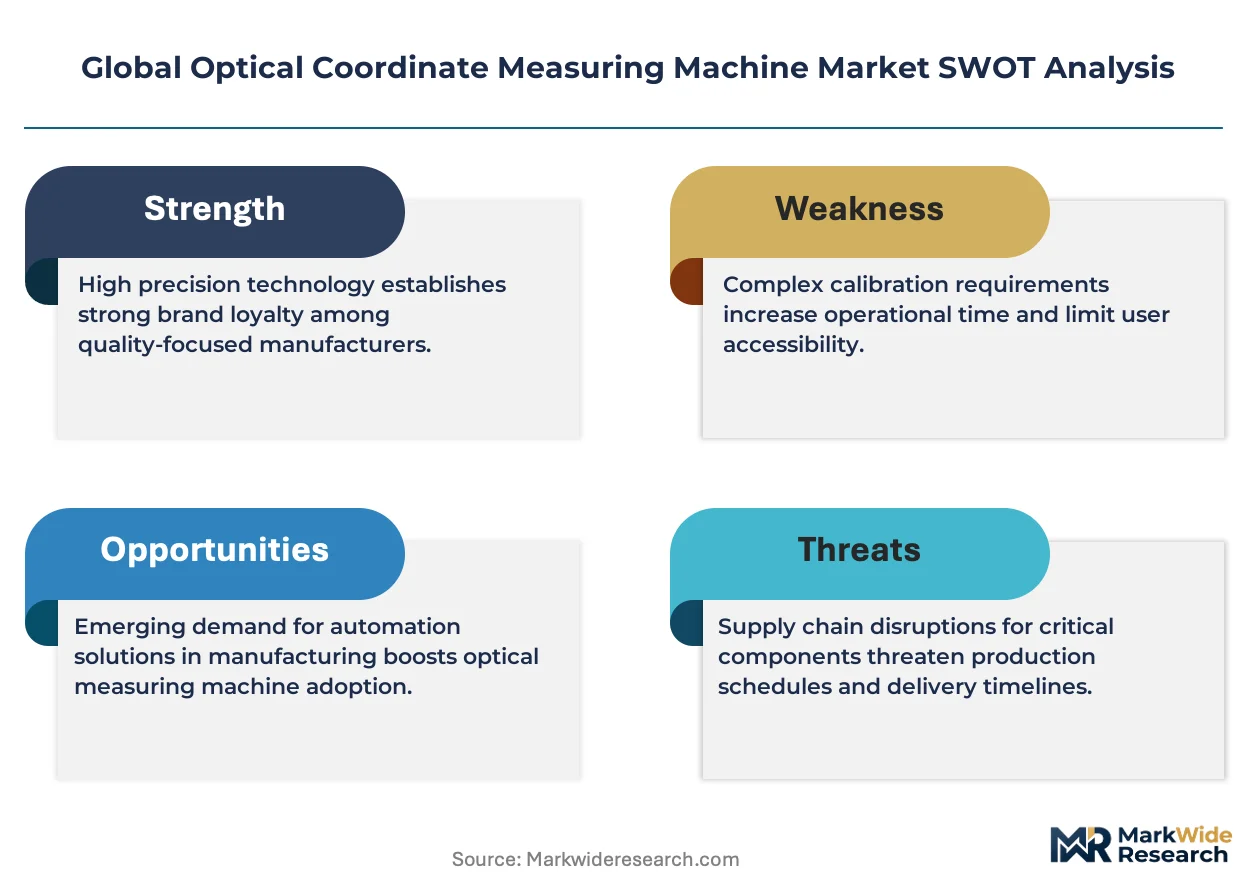
ISO 10360 calibration certification is collapsing the supplier base into a handful of qualified vendors. Carl Zeiss AG leverages its interferometer heritage to dominate high-end optical CMM architectures. Mitutoyo Corp. anchors volume production through its Japanese manufacturing scale and dense Asian distribution. Keyence Corporation differentiates via embedded software workflows that compress inspection cycle times for electronics clients.
An optical coordinate measuring machine employs vision systems, laser triangulation, or structured light to capture sub-micron dimensional data without mechanical probe contact, typically achieving resolutions from 0.1 µm across measuring volumes spanning 200 mm to 2 meters. Vision Measuring Machines lead unit shipments due to maturity in electronics inspection, while Laser Scanning Systems capture the fastest expansion as automotive lightweighting demands freeform surface validation. White Light Scanning commands premium pricing in medical implant metrology where chromatic confocal sensors resolve complex geometries that fringe projection cannot map reliably.
FDA 21 CFR Part 820 quality system regulations mandate traceable dimensional validation for US medical device suppliers, while EU MDR strengthens metrology documentation requirements for implantable component manufacturers. China's SAMR enforces GB/T 16857 series standards that gate market access for imported optical CMM platforms. Stakeholders must monitor how NIST's emerging quantum-based dimensional standards reshape calibration hierarchies and equipment refresh timelines.
Market Dynamics
EUV lithography node shrinkage below 3 nm is compressing tolerance windows across semiconductor packaging workflows, forcing fabs to retire mechanical probe systems in favor of optical CMM architectures that resolve sub-micron geometries without contact damage.
Growth Catalysts
- GB/T 16857 Series Mandates:China's SAMR enforcement gates market access for imported metrology platforms, accelerating replacement cycles among domestic electronics manufacturers seeking compliant certification.
- Multi-sensor Inspection Demand:Chip packaging complexity in Taiwan and South Korea drives simultaneous vision, laser, and chromatic confocal deployment within single measurement routines.
- White Light Interferometry:Medical implant manufacturers adopt chromatic confocal sensors for complex geometry mapping that fringe projection cannot resolve reliably.
Market Restraints
- Qualified Vendor Concentration:ISO 10360 calibration certification collapses the supplier base to a handful of vendors capable of traceable dimensional validation.
- Optical Component Supply Risk:Precision interferometer optics concentrate in German and Japanese specialty glass supply chains vulnerable to export licensing delays.
- Mechanical Probe Substitution:Touch-trigger CMMs retain cost advantage below 50 µm tolerance requirements in automotive stamping and heavy machinery fabrication.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor assembly and test facilities create first-mover positioning for optical CMM vendors establishing local calibration laboratories.
- Quantum-Based Calibration:NIST's emerging dimensional standards reshape hierarchy verification, opening equipment refresh timelines for early adopters seeking traceability advantages.
- Embedded Software Workflows:Inspection cycle compression through automated feature extraction and GD&T automation addresses electronics sector throughput pressures.
Industry Challenges
- Metrology Engineer Scarcity:Optical CMM programming and multi-sensor fusion expertise concentrates in East Asian electronics corridors, limiting deployment velocity elsewhere.
- Legacy System Integration:Brownfield semiconductor fabs face mechanical-to-optical CMM transition friction requiring custom fixturing and measurement routine revalidation.
- Calibration Timeline Compression:PTB and NIST queue congestion extends ISO 10360 recertification intervals, risking production continuity for medical device suppliers under FDA 21 CFR Part 820.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Coordinate Measuring Machine Market |
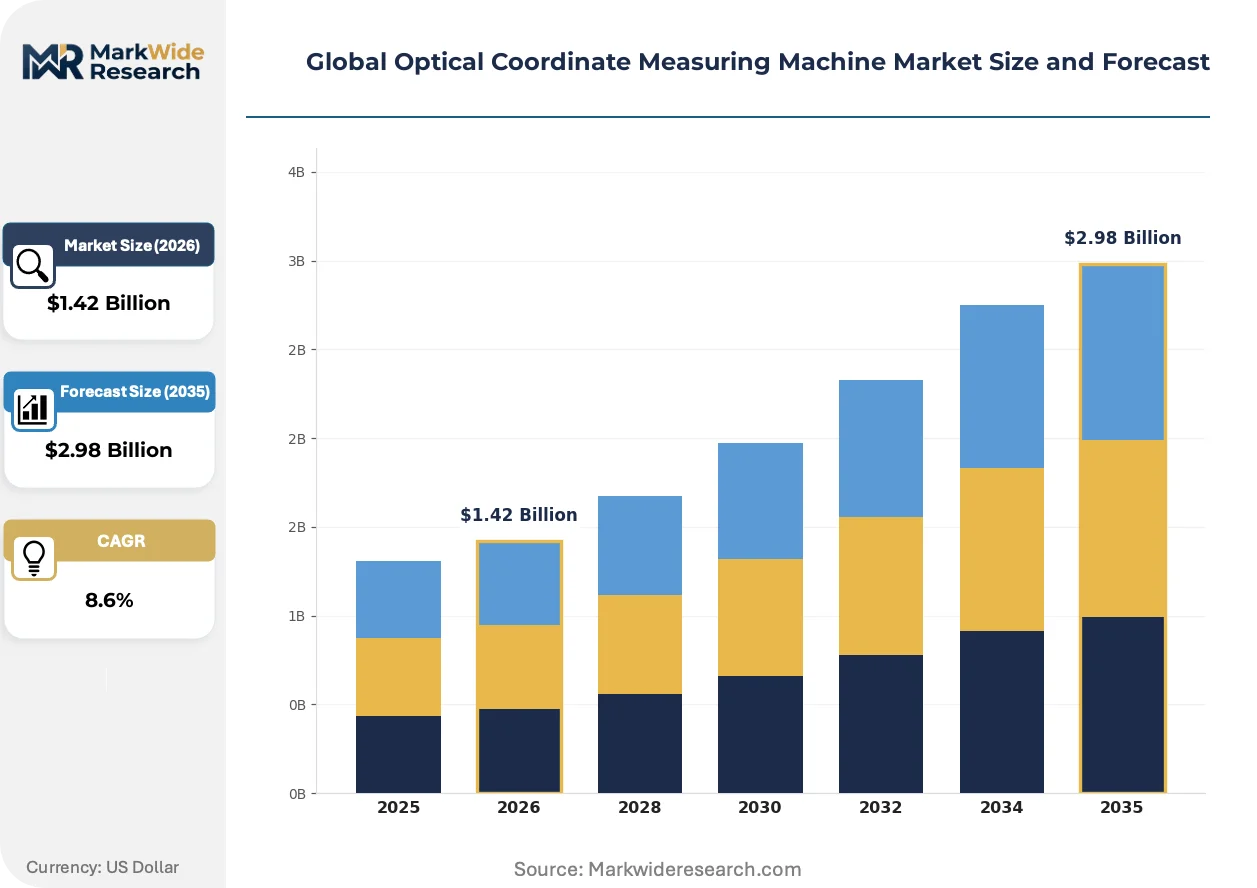
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
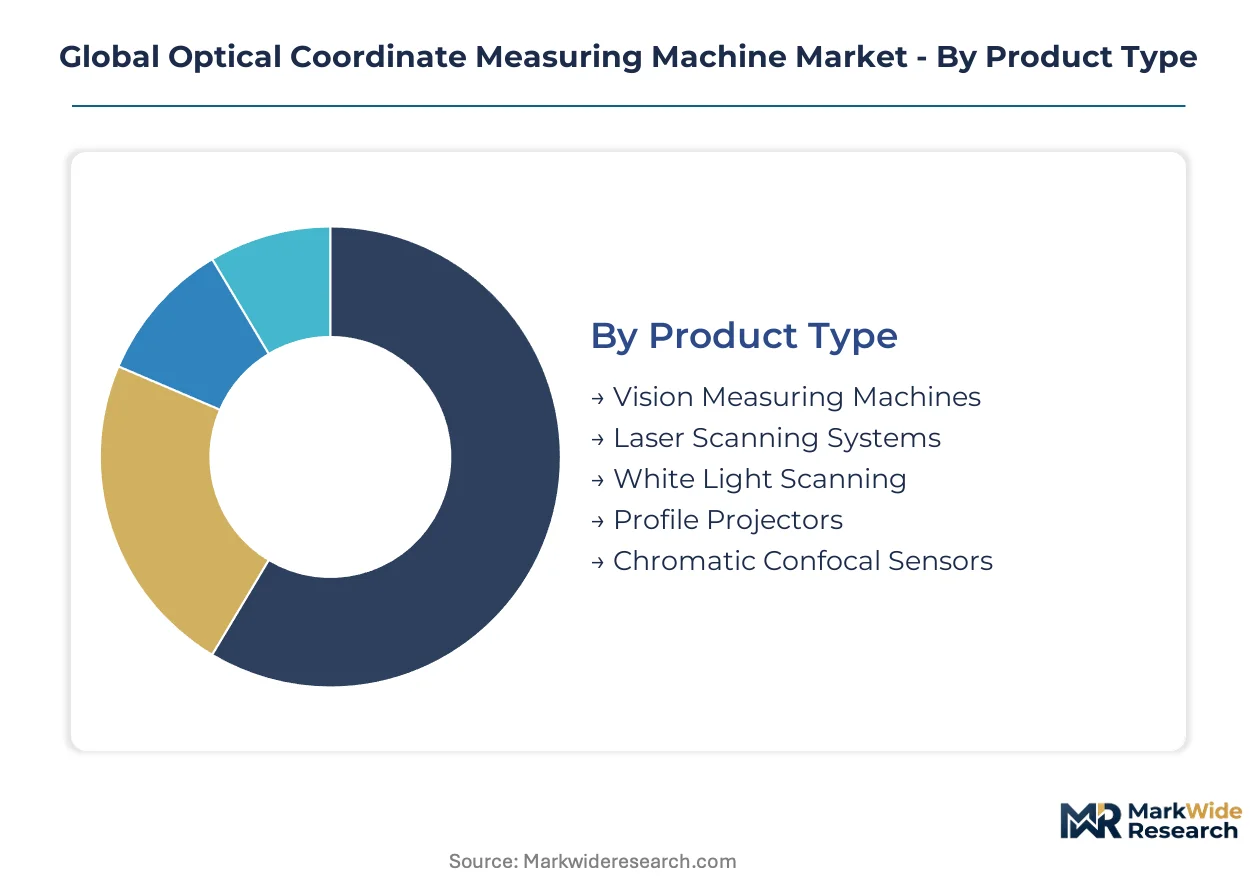
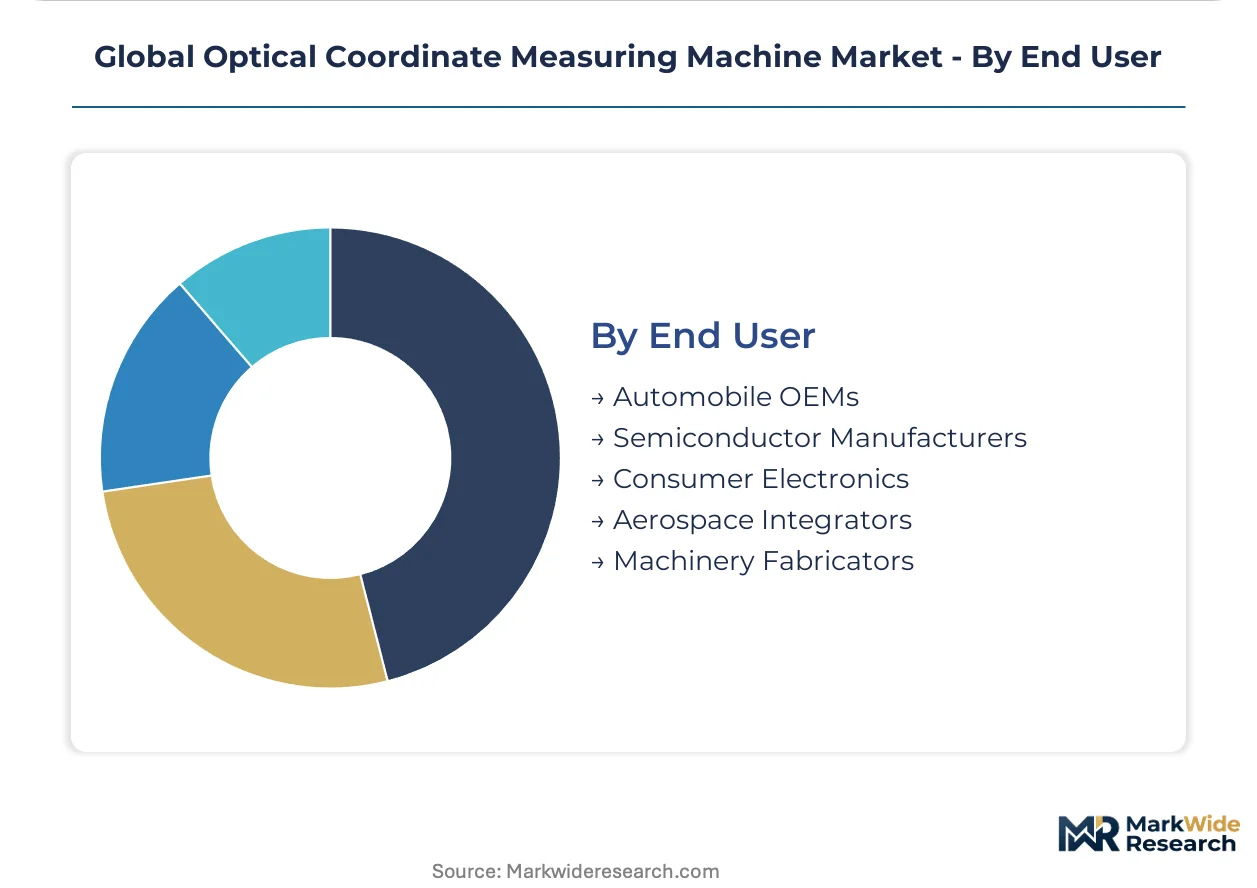
| Segmentation | Product Type: Vision Measuring Machines, Laser Scanning Systems, White Light Scanning, Profile Projectors, Chromatic Confocal Sensors Technology: Non-Contact, Laser Triangulation, Photogrammetry, Fringe Projection, Structured Light Application: Precision Engineering, Aerospace Assembly, Electronics Inspection, Tool Manufacturing, Optical Components End User: Automobile OEMs, Semiconductor Manufacturers, Consumer Electronics, Aerospace Integrators, Machinery Fabricators |
| Companies Covered | Hexagon AB, Carl Zeiss AG, Mitutoyo Corp., Nikon Metrology NV, Werth Messtechnik GmbH, OGP, FARO Technologies, Keyence Corporation, Renishaw plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Coordinate Measuring Machine Market Shifts & Advancements
Multi-sensor fusion architectures are collapsing the boundary between vision, laser, and structured light modalities, creating measurement platforms that auto-select sensing modality based on surface characteristics rather than operator configuration.
Structured light scanning is fragmenting application ownership across metrology workflows. The technology projects fringe patterns onto freeform surfaces for full-field capture without mechanical rastering. Automotive lightweighting programs in Germany and Japan adopt white light variants for carbon fiber composite validation. This modality compression is fragmenting the traditional separation between quality lab and production floor inspection, enabling in-line deployment that bypasses centralized metrology departments.
EU MDR documentation requirements for implantable component manufacturers strengthen metrology traceability mandates across European medical device supply chains. The regulation demands dimensional validation records linking each implant to calibration certificates. Swiss and German orthopedic manufacturers respond by embedding optical CMM stations within cleanroom production cells rather than segregated inspection labs. This regulatory pressure accelerates capital allocation toward chromatic confocal architectures capable of titanium lattice geometry verification.
Electronics assemblers in Taiwan and South Korea compress supplier qualification cycles from months to weeks. Tier-one chip packaging houses now mandate on-site measurement correlation studies before vendor approval, displacing traditional sample-ship-to-lab protocols. This acceleration favors optical CMM vendors with regional application engineering density capable of rapid fixture design and measurement routine deployment. The behavioral shift concentrates procurement influence among buyers with demonstrated multi-site standardization capabilities.
Global Optical Coordinate Measuring Machine Market Segmentation
Segmentation in optical CMM markets reveals where substitute technologies threaten incumbent architectures and where regulatory mandates enforce premium-tier adoption. Understanding these pressure gradients helps vendors allocate R&D and calibration infrastructure.
Product Type:
Substitution pressure varies sharply across sensing modalities, with legacy architectures facing displacement from multi-sensor platforms that collapse discrete measurement functions into unified workflows.
- Vision Measuring Machines:CCD/CMOS array-based systems with telecentric optics capture 2D geometries across 200-500 mm fields at sub-micron resolution. Electronics assemblers in Taiwan and South Korea deploy these for PCB fiducial alignment and BGA pitch verification under compressed cycle-time targets. Touch-trigger CMMs retain cost advantage below 50 µm tolerances, constraining vision system expansion into automotive stamping.
- Laser Scanning Systems:Triangulation-based line scanners map freeform surfaces at 0.1 µm Z-axis resolution without mechanical rastering. Automotive OEMs in Germany validate carbon fiber composite layups for lightweighting programs. White light interferometry encroaches on sub-micron medical applications, fragmenting laser scanning's addressable market at the precision boundary.
- White Light Scanning:Chromatic confocal sensors resolve complex implant geometries that fringe projection cannot map reliably.
- Profile Projectors:Optical comparators with silhouette illumination remain cost-effective for 2D tolerance verification in tool rooms.
- Chromatic Confocal Sensors:Axial chromatism techniques measure high-slope surfaces without mechanical contact.
Vision Measuring Machines anchors the volume base while White Light Scanning gains share at the steepest rate.
Technology:
Cost tier stratification separates commodity sensing approaches from premium architectures requiring specialized glass supply chains and interferometer heritage.
- Non-Contact:Generic vision and laser architectures avoid probe-induced damage on delicate semiconductor wafers and polished optical surfaces. Fabs in Taiwan retire mechanical systems as EUV nodes tighten tolerance windows below 3 nm.
- Laser Triangulation:Active illumination with position-sensitive detectors enables high-speed surface mapping for in-line automotive inspection.
- Photogrammetry:Multi-camera correlation reconstructs large-volume geometries without fixed CMM infrastructure. Aerospace integrators in France validate airframe assemblies spanning multiple meters.
- Fringe Projection:Phase-shifting patterns capture full-field 3D data for reverse engineering and tooling validation.
- Structured Light:Encoded illumination collapses the boundary between quality lab and production floor deployment.
Non-Contact dominates capital deployment in electronics corridors while Structured Light expands most quickly into brownfield manufacturing floors.
Application:
Customer type concentration determines where multi-sensor fusion justifies premium pricing versus where single-modality systems suffice.
- Precision Engineering:Sub-micron tolerance verification for medical devices and aerospace components demands traceable calibration chains. Swiss orthopedic manufacturers embed optical CMMs within cleanroom cells under EU MDR documentation mandates.
- Aerospace Assembly:Large-volume metrology for composite structures and turbine blade alignment. German integrators adopt white light scanning for carbon fiber validation.
- Electronics Inspection:High-throughput PCB and chip packaging verification. South Korean memory fabs drive multi-sensor inspection requirements.
- Tool Manufacturing:Cutting edge geometry and die validation for metal forming.
- Optical Components:Lens surface figure and coating thickness measurement.
Electronics Inspection commands the densest installed base while Precision Engineering climbs the fastest on regulatory documentation requirements.
End User:
Procurement authority concentrates among buyers with multi-site standardization capabilities and demonstrated measurement correlation protocols.
- Semiconductor Manufacturers:Taiwan and South Korean fabs expand metrology budgets as EUV lithography nodes compress tolerance windows. On-site correlation studies now displace traditional sample-ship-to-lab vendor qualification.
- Automobile OEMs:Lightweighting programs drive freeform surface validation demand. German and Japanese manufacturers adopt structured light for composite inspection.
- Consumer Electronics:Assembly houses in China face GB/T 16857 compliance gates for imported metrology platforms.
- Aerospace Integrators:Airframe and engine component validation with NIST-traceable dimensional standards.
- Machinery Fabricators:Heavy equipment and industrial tooling measurement.
Semiconductor Manufacturers anchor the volume base while Automobile OEMs gain share at the steepest rate on lightweighting program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforcement of GB/T 16857 series standards gates market access for imported metrology platforms, accelerating replacement cycles among domestic electronics manufacturers seeking compliant certification. Taiwan and South Korean semiconductor fabs expand metrology budgets as EUV lithography nodes compress tolerance windows below 3 nm. Germany's PTB calibration mandates and the United States' FDA 21 CFR Part 820 quality system regulations reshape equipment refresh timelines across precision manufacturing corridors.
China
Domestic electronics manufacturers in Shenzhen and Dongguan drive demand for vision measuring machines under GB/T compliance pressure. SAMR's enforcement of precision measurement equipment standards accelerates retirement of non-certified imported platforms. Yangtze River Delta chip packaging houses now mandate ISO 10360 certification for all incoming metrology assets.
Taiwan
Hsinchu Science Park fabs deploy multi-sensor optical CMM architectures for sub-micron BGA pitch verification. The island's semiconductor equipment import regulations prioritize traceable dimensional validation for advanced packaging workflows. Tainan-based memory manufacturers compress supplier qualification cycles from months to weeks through on-site measurement correlation studies.
South Korea
Seoul Capital Area memory giants expand chromatic confocal sensor deployment for EUV node metrology. MFDS-aligned documentation requirements for medical device subcontractors strengthen calibration chain mandates. Pyeongtaek semiconductor clusters retire mechanical probe systems in favor of non-contact architectures that eliminate wafer damage risk.
Germany
Bavarian automotive OEMs adopt structured light scanning for carbon fiber composite validation in lightweighting programs. PTB calibration mandates enforce ISO 10360 recertification intervals that concentrate procurement among qualified vendors. Stuttgart-area precision engineering clusters embed optical CMM stations within production cells rather than segregated quality labs.
United States
FDA 21 CFR Part 820 regulations mandate traceable dimensional validation for orthopedic implant suppliers in Warsaw, Indiana. NIST's emerging quantum-based dimensional standards reshape hierarchy verification for early-adopting aerospace integrators. Greater Boston medical device manufacturers face calibration timeline compression as national metrology queue congestion extends recertification intervals.
Global Optical Coordinate Measuring Machine Market Competitive Landscape
Player mix skews toward precision optics heritage firms and Japanese manufacturing scale specialists, creating a tiered structure where interferometer expertise commands premium positioning. The supplier base concentrates around vendors capable of ISO 10360 calibration certification, collapsing viable participants to a handful of qualified platforms. Two strategic archetypes dominate: European heritage firms leveraging metrology institute relationships, and Asian volume producers optimizing manufacturing scale. Competitive moves center on regional calibration laboratory expansion and embedded software workflow differentiation.
Within the heritage optics tier, Carl Zeiss AG and Werth Messtechnik GmbH occupy positions anchored by German interferometer expertise and PTB-aligned calibration chains. Mitutoyo Corp. exemplifies the Japanese manufacturing scale archetype, with Yokohama-based production density supporting volume deployment across Asian electronics corridors. Keyence Corporation sits within the embedded software differentiation vector, where automated feature extraction capabilities address compressed inspection cycle demands. These three represent the strategic positioning spectrum: European precision heritage, Asian manufacturing scale, and software-driven workflow compression.
| Leading Market Players |
|---|
| Hexagon AB |
| Carl Zeiss AG |
| Mitutoyo Corp. |
| Nikon Metrology NV |
| Werth Messtechnik GmbH |
| OGP |
| FARO Technologies |
| Keyence Corporation |
| Renishaw plc |
| Others |
Supply & Pricing Matrix
ISO 10360 calibration certification gates both supplier qualification and price differentiation simultaneously, collapsing viable vendors to a handful of qualified platforms while creating three distinct cost tiers based on traceability depth and interferometer heritage. Electronics manufacturers in Taiwan and South Korea absorb premium pricing for multi-sensor architectures that compress BGA pitch verification cycles, while automotive stampers in Germany retain mechanical probe systems where tolerances exceed 50 µm and cost sensitivity dominates procurement decisions.
Pricing Analysis
Certification level creates the primary spread across optical CMM price tiers, with ISO 10360-traceable platforms commanding substantial premiums over non-certified alternatives in medical device and semiconductor corridors. Three-tier pricing structure across premium, standard, and economy levels reflects the divergence between chromatic confocal sensor architectures for implant metrology and vision-based systems for electronics assembly. Pricing pressure stems from qualified vendor concentration as PTB and NIST queue congestion extends recertification intervals, forcing medical device suppliers under FDA 21 CFR Part 820 to absorb expedited calibration surcharges. Semiconductor manufacturers in East Asia exhibit lowest price sensitivity, prioritizing multi-sensor throughput over capital expenditure constraints, while machinery fabricators in heavy industry segments drive hardest bargain for single-modality systems.
Supply Chain Analysis
Precision interferometer optics concentrate in German and Japanese specialty glass supply chains, creating single-source vulnerability for chromatic confocal sensor architectures that medical implant manufacturers depend on for complex geometry verification. Schott AG and Hoya Corporation anchor the precision glass substrate layer, while laser diode arrays draw from South Korean and Taiwanese semiconductor foundries. Tariff exposure runs through EU-China technology transfer restrictions on metrology-grade optical components, threatening calibration chain continuity for platforms requiring PTB-traceable certification. Distribution runs through regional calibration laboratories in Hsinchu, Stuttgart, and Boston that anchor vendor qualification protocols for semiconductor and medical device end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EUV lithography node shrinkage below 3 nm is reshaping competitive positioning, compressing tolerance windows that force mechanical-to-optical CMM substitution across semiconductor packaging workflows and creating first-mover advantages for vendors with established multi-sensor fusion expertise.
For Market Incumbents: Shield market position by deepening regional calibration laboratory density in India's PLI-subsidized electronics corridors before competitor infrastructure hardens. Acquire chromatic confocal sensor specialists to close technology gaps in medical implant metrology where EU MDR documentation mandates accelerate capital allocation. Certification investment in NIST quantum-based dimensional standards preparation captures early-adopter traceability premiums as hierarchy verification protocols shift. For New Entrants and Emerging Players: Lead with embedded software workflow differentiation targeting electronics assemblers in Vietnam and Indonesia where supplier qualification cycles compress from months to weeks and regional application engineering density remains thin. White-space concentration in India's semiconductor assembly and test facilities offers penetrable entry before incumbent calibration laboratories achieve local certification capability. Go-to-market angle centers on automated GD&T extraction that compresses inspection cycle times without requiring legacy mechanical CMM operator retraining. For Investors and Strategic Acquirers: NIST's emerging quantum-based dimensional standards reshape the acquisition landscape, favoring targets with interferometer heritage and existing PTB-aligned calibration chains over pure software plays. Long-term viability concentrates in vendors capable of spanning medical device regulatory documentation and semiconductor throughput compression simultaneously. Acquisition target archetype: mid-scale European metrology specialists with ISO 10360 certification infrastructure and dormant Asian distribution partnerships. Signal to watch is calibration queue congestion duration at national metrology institutes as indicator of pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Calibration Laboratory Expansion | On-site certification capability in Hsinchu and Pyeongtaek accelerates vendor qualification cycles for memory fabs. |
| Multi-Sensor Fusion Platform Development | Unified vision-laser-confocal architectures capture chip packaging complexity premiums in Taiwan and South Korea. |
| Embedded Software Workflow Integration | Automated feature extraction addresses electronics sector throughput pressures without operator retraining burden. |
| Quantum-Standard Calibration Preparation | Early NIST hierarchy alignment positions vendors for equipment refresh timelines as traceability protocols evolve. |
| India Electronics Corridor Partnership | PLI scheme incentives for semiconductor assembly create first-mover positioning before competitor infrastructure hardens. |
Research Methodology
A spread of perspectives from metrology engineers at Taiwan semiconductor fabs, calibration laboratory directors at PTB-affiliated institutes, procurement managers at German automotive OEMs, and regulatory affairs leads at FDA-registered medical device manufacturers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings of listed metrology equipment vendors, customs records for precision optical component trade flows, and ISO 10360 certification registry databases. Bottom-up triangulation across sensing modality shipment data and top-down reconciliation against capital expenditure disclosures from memory manufacturers anchored volume estimates.
Segmentation dimensions modeled span product type across vision, laser, and white light architectures; technology modality including non-contact and structured light approaches; application concentration in electronics inspection versus precision engineering; and end-user segmentation separating semiconductor manufacturers from automotive OEMs. CAGRs derived from regression analysis of historical replacement cycle data against EUV lithography node roadmaps and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated GB/T 16857 compliance enforcement intensity and NIST quantum standard development progression across the projection horizon.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820, EU MDR, and China's SAMR enforcement regimes; material policy shifts would require re-modeling equipment refresh timelines and calibration chain requirements. Specific risks that could revise projections include export licensing delays on precision interferometer optics, PTB queue congestion extending beyond current intervals, and mechanical probe substitution persistence in automotive segments if lightweighting programs stall. Practitioners should keep alternative scenarios live as EUV node transition pacing and quantum standard commercialization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Space Power Supply Market
Others
Running Apparel Market
Others
Egg and Egg Products Market
Others
Enterprise Video Market
Others
Global Video Processing Platform Market
Others
Metal Air Battery Market
Others
Global Pregnancy Tracker Apps Market
Others
Coalescing Filter Market
Others
Global Telemetry Market
Others
Asia-Pacific Adtech Market
Others
Global Computer Graphics Market
Others
Europe Indoor LBS Market
Others
Europe Astrology Market
Others
Architectural Fabrics Market
Others
Level Measuring Instrument Market
Others
North America Cashew Market