
 Global Telemetry Market | 2026-2036
Global Telemetry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telemetry Market Outlook
Buyer concentration in the utilities sector is expanding as regional power grids consolidate procurement of smart metering infrastructure. General Electric Company leverages its turbine monitoring heritage to dominate industrial telemetry deployments. Siemens sustains competitive positioning through deep integration of edge analytics into factory automation systems.
Telemetry encompasses the automated collection, transmission, and measurement of data from remote or inaccessible sources using sensors, wireless transceivers, and data loggers operating across radio frequencies from 400 MHz to 2.4 GHz. The technology serves critical functions in real-time equipment health monitoring, environmental surveillance, and fleet coordination across distributed geographies. Satellite communication captures premium value in aerospace and maritime applications where terrestrial networks fail. Cloud-based deployment is accelerating fastest among healthcare providers seeking scalable cardiac and respiratory monitoring. Industrial automation applications anchor mature margin pools in factory telemetry where sensor density and protocol standardization reduce deployment friction.
The FAA mandates specific telemetry protocols for unmanned aircraft systems operating beyond visual line of sight. EASA's expanding cybersecurity certification requirements for connected aviation equipment are forcing European suppliers to harden data link architectures. FDA digital health pre-certification pathways shape how healthcare telemetry vendors validate algorithm-driven diagnostic outputs. Stakeholders must weigh spectrum allocation battles between cellular and RF communication technologies when placing long-term bets on hardware refresh cycles.
Market Dynamics
Healthcare providers in the United States, Germany, and Japan are consolidating remote patient monitoring procurement around cloud-native telemetry stacks, compressing hardware refresh cycles and forcing vendors to validate algorithm outputs against tightening FDA and EU AI Act data integrity mandates.
Growth Catalysts
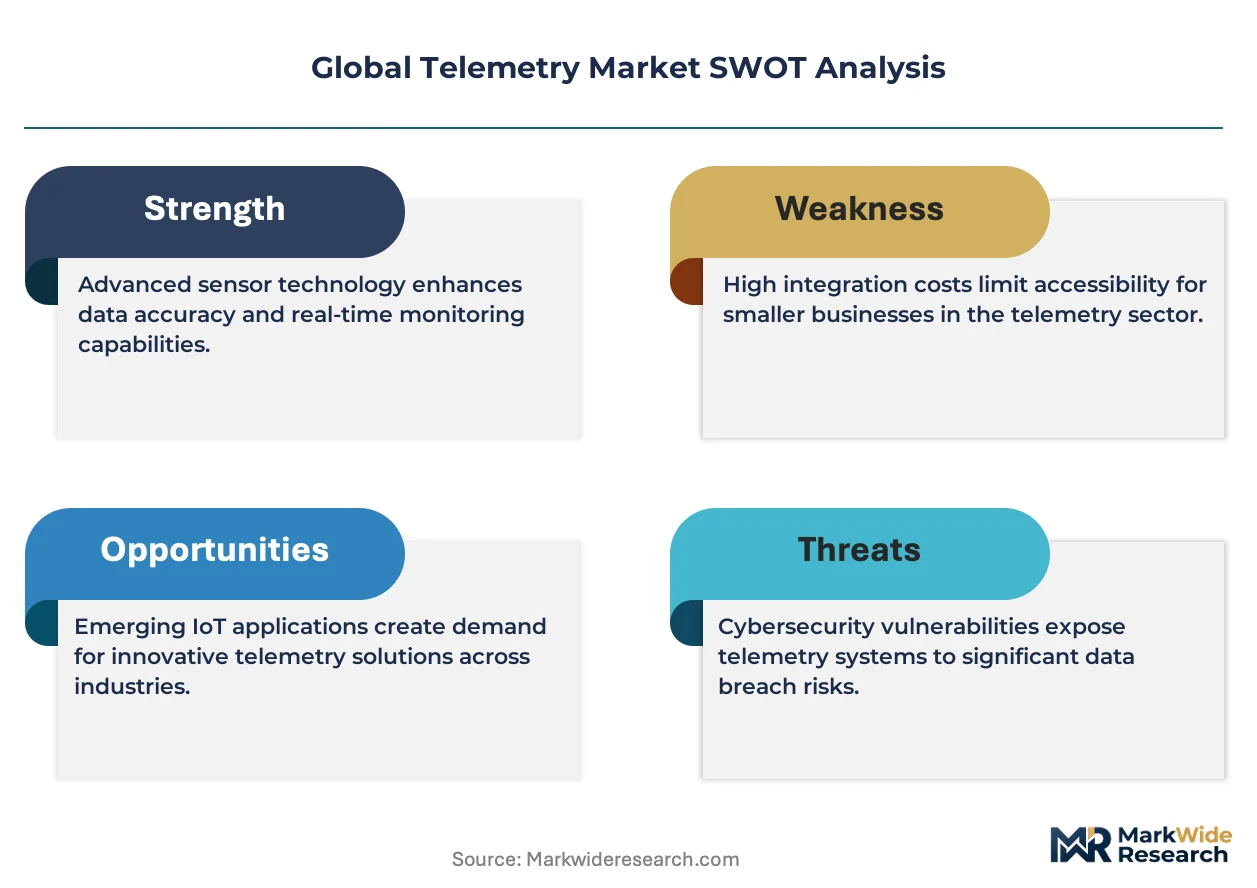
- EU AI Act compliance mandates:European healthcare telemetry vendors must harden data link architectures and algorithm validation protocols, creating pull for certified edge analytics platforms.
- Critical infrastructure modernization:Regional power grids in the United States and Japan are consolidating smart metering procurement, expanding addressable demand for industrial telemetry sensor networks.
- Satellite communication premiums:Aerospace and maritime applications where terrestrial networks fail are capturing sustained value for specialized RF transceiver hardware operating across 400 MHz to 2.4 GHz bands.
Market Restraints
- Semiconductor input volatility:RF transceiver and sensor microcontroller supply concentrates in East Asian foundry networks, exposing telemetry hardware margins to wafer allocation disruptions.
- Spectrum allocation friction:FCC and national telecom regulators are arbitrating cellular versus dedicated RF band assignments, extending hardware certification timelines for multi-protocol devices.
- Legacy protocol entrenchment:Factory automation systems rely on proprietary industrial Ethernet variants, creating technical drag on standardized telemetry deployment across brownfield manufacturing sites.
Strategic Opportunities
- Cardiac monitoring cloud migration:Healthcare providers in Germany are accelerating scalable respiratory and cardiac telemetry deployment, favoring subscription-based platform economics over capital-intensive hardware sales.
- Edge-to-cloud convergence:Integration of factory-floor edge analytics with centralized telemetry dashboards is opening white space for hybrid deployment models in Japanese automotive manufacturing.
- FAA UAS protocol mandates:Beyond-visual-line-of-sight drone regulations are creating certified telemetry module demand for unmanned aircraft system manufacturers serving precision agriculture and infrastructure inspection.
Industry Challenges
- Embedded cybersecurity engineering scarcity:Telemetry vendors face acute hiring pressure for firmware architects capable of implementing EASA-grade data link hardening and FDA pre-certification algorithm validation.
- Multi-jurisdiction certification complexity:Simultaneous FDA digital health pre-certification, EU MDR conformity assessment, and FCC RF equipment authorization is compressing product launch windows and inflating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telemetry Market |
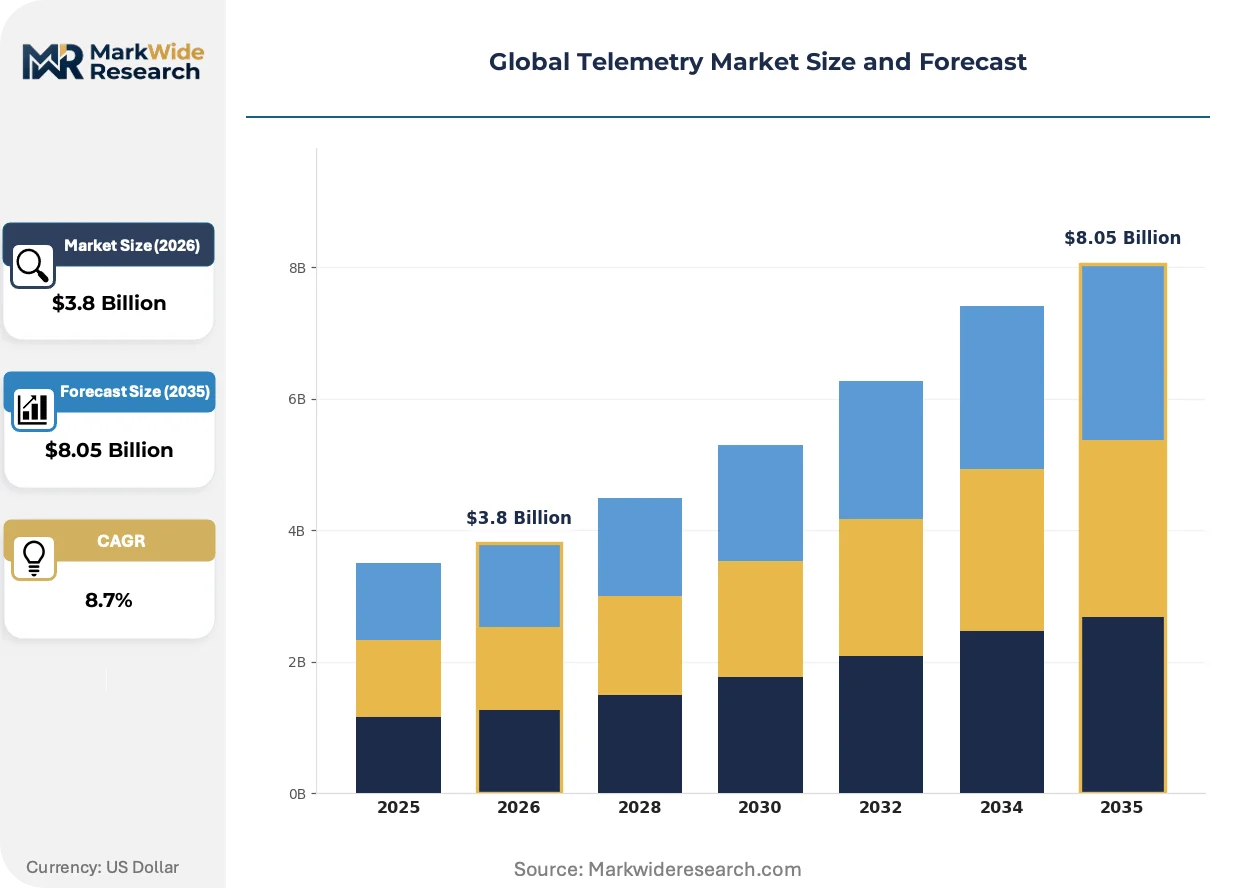
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Satellite Communication, Cellular Networks, RF Communication, Zigbee End User: Aerospace, Automotive, Healthcare, Utilities Application: Environmental Monitoring, Asset Tracking, Remote Sensing, Industrial Automation Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | General Electric Company, Siemens, Honeywell International Inc., Koninklijke Philips N.V., L3Harris Technologies, Inc., Schneider Electric, AstroNova, Inc., Rogers Communications, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telemetry Market Strategic Shifts
Telemetry architecture is pivoting from hardware-centric sensor deployment toward software-defined data orchestration, with cloud-native platforms and AI-driven edge analytics compressing traditional value capture points across healthcare and industrial verticals.
Low-earth-orbit satellite constellations are rewriting connectivity economics for maritime and aerospace telemetry applications previously dependent on geostationary bandwidth premiums. Shipping operators and commercial aviation fleets are adopting flat-panel phased-array terminals at accelerating pace. This technology is collapsing the cost barrier for real-time engine health monitoring across transoceanic routes, enabling predictive maintenance contracts that were structurally uneconomical under legacy satellite economics.
The EU AI Act's risk-based classification system for algorithmic medical devices is forcing European telemetry suppliers to rearchitect data pipelines for explainability and auditability. Industrial consequence includes mandatory human-in-the-loop safeguards for diagnostic algorithms processing cardiac and respiratory telemetry streams. Cardiac monitoring vendors serving German and French hospital networks are responding by segregating inference workloads between edge devices and cloud substrates to satisfy traceability requirements.
Hospital procurement departments are consolidating telemetry vendor relationships around integrated platform contracts that bundle hardware, connectivity, and clinical decision support. Traditional device distributors are losing position to direct manufacturer engagements and health system-owned procurement consortiums. This pattern is most visible in United States IDN structures where Mayo Clinic and Kaiser Permanente-style organizations are negotiating enterprise telemetry agreements spanning multiple facilities and service lines.
Global Telemetry Market Segmentation
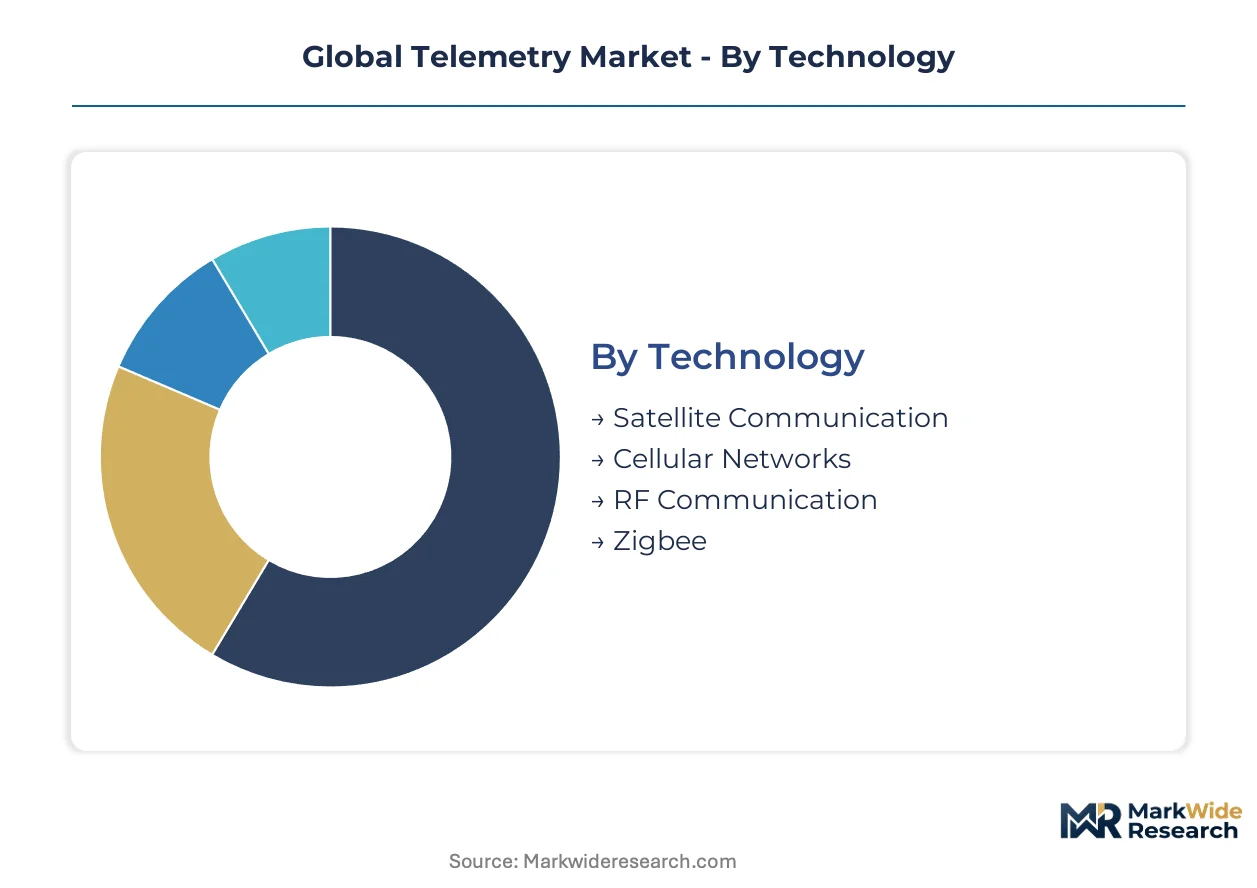
Telemetry buyers prioritize connectivity reliability, regulatory compliance, and integration depth when selecting technology stacks. Segmentation reveals how vendor positioning varies across mission-critical applications versus cost-sensitive deployments.
Technology:
Procurement teams evaluate spectrum licensing costs, coverage gaps, and hardware refresh cycles when committing to communication infrastructure.
- Satellite Communication:Geostationary and low-earth-orbit constellations deliver connectivity across maritime routes and transoceanic flight corridors where terrestrial infrastructure fails. Shipping operators in Japan and commercial aviation fleets in the United States are adopting flat-panel phased-array terminals to enable real-time engine health monitoring under predictive maintenance contracts.
- Cellular Networks:4G LTE and 5G NR modules support high-bandwidth telemetry streams for connected vehicle fleets and remote patient monitoring devices. Healthcare providers in Germany are consolidating procurement around cellular-native cardiac monitoring platforms that satisfy EU AI Act data integrity mandates.
- RF Communication:License-free 400 MHz to 2.4 GHz bands power industrial sensor networks with minimal recurring connectivity costs.
- Zigbee:Mesh topology protocols serve low-power environmental monitoring applications in smart building and utility metering deployments.
Satellite communication leads on scale; cellular networks lead on momentum.
End User:
Vertical-specific certification requirements and procurement consolidation patterns reshape competitive access across buyer categories.
- Aerospace:FAA mandates specific telemetry protocols for unmanned aircraft systems operating beyond visual line of sight. Precision agriculture and infrastructure inspection drone manufacturers in the United States face compressed certification timelines for multi-protocol RF equipment.
- Healthcare:Cloud-native cardiac and respiratory monitoring platforms dominate hospital procurement in Germany, France, and the United States. FDA digital health pre-certification pathways and EU MDR conformity assessments are forcing vendors to validate algorithm-driven diagnostic outputs against hardened data link architectures.
- Automotive:Connected vehicle telematics and over-the-air diagnostic systems rely on cellular and satellite hybrid connectivity for fleet coordination.
- Utilities:Regional power grids in the United States and Japan are consolidating smart metering infrastructure procurement around standardized sensor networks.
Healthcare leads on margin contribution; aerospace leads on technical specification intensity.
Application:
Use-case complexity determines whether buyers prioritize edge processing latency or centralized analytics depth.
- Industrial Automation:Factory telemetry systems anchor mature margin pools where sensor density and protocol standardization reduce deployment friction. Japanese automotive manufacturers are integrating edge analytics with centralized dashboards through hybrid deployment models.
- Asset Tracking:Real-time location systems for fleet and equipment coordination span cellular, satellite, and RF communication layers depending on geographic coverage requirements.
- Environmental Monitoring:Distributed sensor networks track air quality, water levels, and meteorological conditions across remote geographies.
- Remote Sensing:Satellite-linked data loggers capture geospatial intelligence for agriculture, defense, and climate research applications.
Industrial automation leads on deployment volume; asset tracking leads on technology integration complexity.
Deployment:
Data sovereignty requirements and latency sensitivity drive architecture selection between localized processing and cloud scalability.
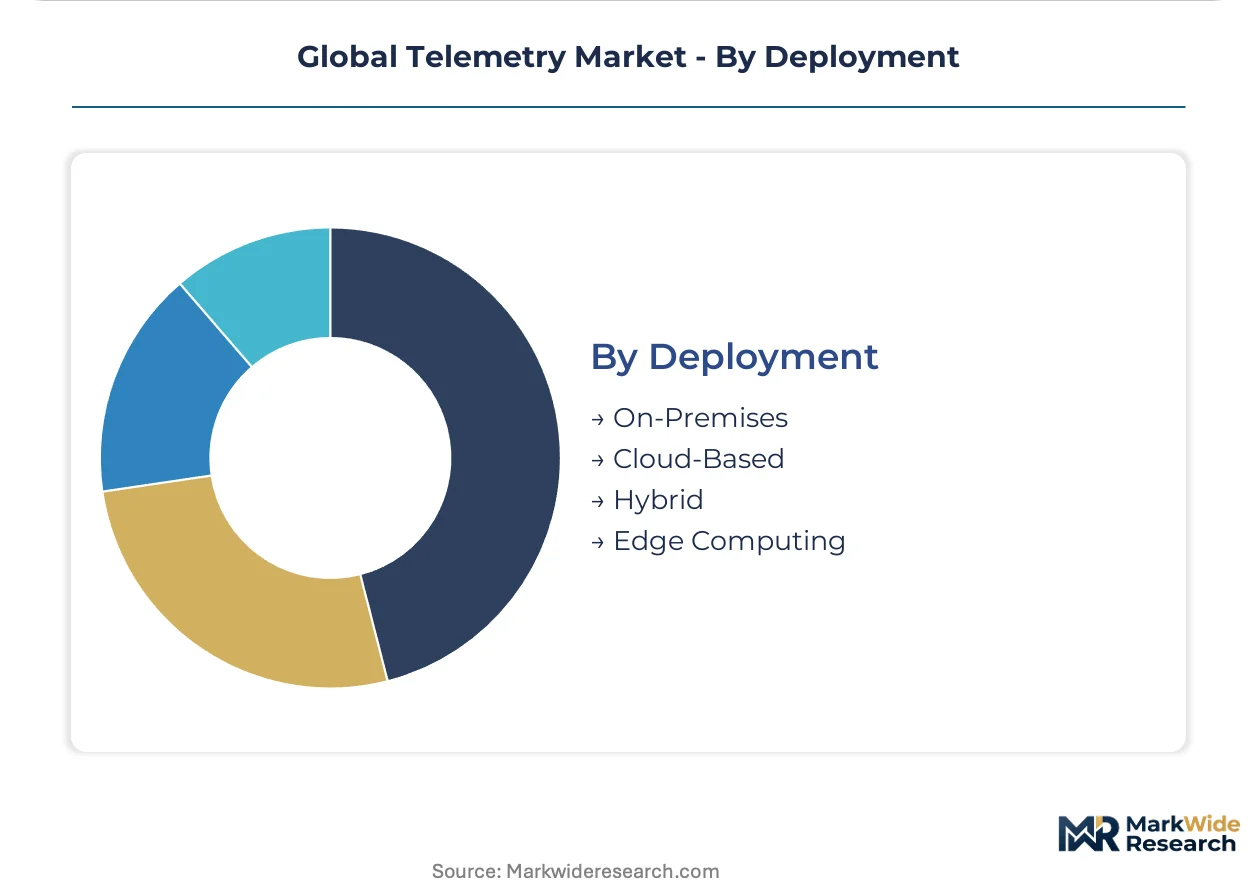
- Cloud-Based:Scalable telemetry platforms dominate healthcare procurement as United States integrated delivery networks negotiate enterprise agreements spanning multiple facilities. Subscription economics are displacing capital-intensive hardware sales for cardiac monitoring vendors serving Mayo Clinic and Kaiser Permanente-style organizations.
- Edge Computing:Factory-floor inference engines process telemetry streams locally to satisfy EU AI Act traceability requirements for algorithmic medical devices. German and French hospital networks are segregating diagnostic workloads between edge devices and cloud substrates.
- On-Premises:Air-gapped deployments serve defense and critical infrastructure operators with stringent cybersecurity requirements.
- Hybrid:Combined edge-to-cloud architectures balance real-time responsiveness with centralized analytics for complex industrial environments.
Cloud-based deployment leads on commercial momentum; edge computing leads on regulatory compliance intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded firmware engineers cluster around aerospace corridors in the United States, medical technology hubs in Germany, and precision manufacturing centers in Japan, anchoring regional telemetry development capabilities.
United States
Integrated delivery networks in Minnesota and California are consolidating enterprise telemetry contracts spanning cardiac monitoring and respiratory surveillance. FDA digital health pre-certification pathways compress algorithm validation timelines for cloud-native platform vendors. The Mayo Clinic procurement consortium in Rochester, Minnesota negotiates multi-facility agreements that displace traditional device distributors.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are migrating cardiac telemetry to subscription-based cloud platforms. EU AI Act risk classifications mandate human-in-the-loop safeguards for diagnostic algorithms processing patient data streams. Siemens anchors industrial telemetry deployment from its Nuremberg automation headquarters, integrating edge analytics into factory-floor sensor networks.
Japan
Automotive manufacturers in Toyota City and Yokohama are adopting hybrid edge-to-cloud architectures for factory telemetry systems. METI industrial modernization programs subsidize sensor network deployment across brownfield manufacturing sites. Regional power grids in Tokyo and Osaka are consolidating smart metering procurement around standardized RF communication infrastructure.
United Kingdom
Defense contractors in Bristol and aerospace clusters around Farnborough are developing air-gapped telemetry systems for critical infrastructure operators. EASA cybersecurity certification requirements for connected aviation equipment force data link architecture hardening. The Civil Aviation Authority mandates specific protocols for unmanned aircraft systems operating beyond visual line of sight in agricultural inspection applications.
France
Hospital procurement departments in Paris and Lyon are segregating diagnostic inference workloads between edge devices and cloud substrates to satisfy EU AI Act traceability mandates. ANSM conformity assessments for algorithmic medical devices extend validation timelines for telemetry vendors serving French healthcare networks. Thales anchors satellite communication development from its Toulouse aerospace campus for maritime and aviation applications.
Global Telemetry Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology layers, creating a tiered structure where scale advantages in certification and procurement access separate market positions. Industrial automation heritage anchors defensive positioning in factory telemetry, while healthcare cloud platforms reward software-defined data orchestration capabilities. Three archetypes dominate: diversified industrial conglomerates with turbine and automation legacies, medical technology specialists with diagnostic algorithm expertise, and satellite communication pure-plays serving aerospace and maritime verticals. Competitive moves concentrate on M&A to acquire embedded cybersecurity engineering talent and strategic partnerships to accelerate multi-jurisdiction certification timelines.
Among diversified industrial conglomerates, General Electric Company and Siemens occupy positions that exemplify the industrial automation archetype, leveraging turbine monitoring heritage and factory-floor integration capabilities respectively. Honeywell International Inc. represents the diversified technology conglomerate model spanning aerospace and building automation telemetry. Koninklijke Philips N.V. anchors the healthcare-focused specialist tier, with L3Harris Technologies, Inc. and Schneider Electric occupying positions across defense-industrial and energy infrastructure segments respectively.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens |
| Honeywell International Inc. |
| Koninklijke Philips N.V. |
| L3Harris Technologies, Inc. |
| Schneider Electric |
| AstroNova, Inc. |
| Rogers Communications |
| IBM |
| Others |
Value Chain & Pricing Dynamics
RF transceiver wafer pricing indices from East Asian foundry networks cascade through telemetry hardware tiers, compressing margins on cellular-native modules while satellite communication platforms retain premium positioning through specialized phased-array component scarcity.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for cellular telemetry modules, forcing three-tier pricing structure across premium, standard, and economy levels. FDA pre-certification tier and EASA cybersecurity grade separate premium cardiac monitoring platforms from utility-grade sensor networks. Pricing pressure stems from semiconductor input volatility as RF microcontroller allocation tightens. Hospital procurement committees in Germany exhibit lowest price sensitivity due to EU AI Act compliance mandates, while brownfield manufacturing sites in Japan face acute cost compression.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for telemetry hardware fulfillment. Manufacturing concentrates in China, South Korea, and Japan for RF transceivers, sensor microcontrollers, and satellite phased-array components. The supply chain draws from silicon wafer substrates, rare-earth magnet materials for antenna assemblies, and lithium-ion cells for remote data loggers. Single-source vulnerability concentrates in East Asian foundry networks. Distribution runs through authorized industrial distributors and direct manufacturer engagements with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Telemetry Market represents a late-cycle quality story as healthcare procurement shifts toward FDA pre-certified and EU AI Act-compliant platforms that command specification premiums over commodity sensor hardware.
For Market Incumbents: Acquire embedded cybersecurity engineering talent to harden data link architectures against EASA certification requirements and FDA algorithm validation protocols. Consolidate factory automation telemetry positions through edge-to-cloud integration partnerships with Japanese automotive manufacturers. Cloud-native platform entrants threaten industrial incumbents through subscription economics displacement. For New Entrants and Emerging Players: Hospital procurement consortiums offer channel access for cardiac monitoring specialists seeking enterprise contracts with United States integrated delivery networks. White space concentrates in FAA-certified telemetry modules for beyond-visual-line-of-sight drone manufacturers serving precision agriculture. Target German hospital networks migrating respiratory surveillance to subscription platforms with algorithm explainability guarantees. For Investors and Strategic Acquirers: Asymmetric upside sits with satellite communication pure-plays serving maritime and aerospace verticals as low-earth-orbit constellations collapse connectivity cost barriers. Five-to-ten year viability favors vendors with multi-jurisdiction certification capabilities spanning FDA, EU MDR, and FCC RF authorization. Monitor FCC spectrum allocation rulings between cellular and dedicated RF bands as inflection indicator for hardware refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Cybersecurity Talent Acquisition | EASA-grade data link hardening satisfies tightening aviation certification requirements for connected equipment. |
| Cloud-Native Platform Migration | Subscription economics displace capital-intensive hardware sales for cardiac monitoring vendors serving Mayo Clinic-scale IDNs. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA pre-certification and EU MDR conformity assessment compresses product launch windows against competitors. |
| Satellite Phased-Array Terminal Deployment | Flat-panel terminals enable predictive maintenance contracts for transoceanic shipping operators previously priced out of real-time monitoring. |
| Edge-to-Cloud Hybrid Architecture Development | Factory-floor integration with centralized dashboards captures Japanese automotive manufacturing modernization subsidies under METI programs. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital GPO contracts managers, FAA certification specialists, and industrial automation procurement leads with secondary validation against FDA 510(k) filings, FCC equipment authorization databases, EASA certification records, and hospital procurement consortium contract disclosures. Bottom-up telemetry hardware shipment estimates triangulated against top-down healthcare IT spending and industrial automation capex allocations.
Historical reference periods anchored the projection horizon through documented smart metering deployment waves, cardiac monitoring platform adoption curves, and satellite communication terminal installation rates across maritime fleets. Segmentation dimensions modeled include connectivity technology, end-user vertical, deployment architecture, and regional regulatory cluster. CAGRs derived from regression analysis against infrastructure modernization program timelines and healthcare digitization policy trajectories. Forecast inputs incorporated EU AI Act implementation phases and FAA beyond-visual-line-of-sight regulatory expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry allocation disruptions, spectrum licensing arbitrations, and multi-jurisdiction certification timeline extensions. Outputs reflect documented assumptions regarding regulatory implementation schedules and infrastructure subsidy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Infant Fever Stickers Market
Others
Air Separation Unit Market
Others
Coconut Activated Carbon Market
Others
Synthetic Leather Market
Others
Tripod Market
Others
Magnetic Stripe Readers Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Boston Round Bottle Market
Others
Mini Personal Computer Market
Others
Vegan Confectionery Market
Others
Shear Testing Equipment Market
Others
Global Animal Feed Protein Ingredients Market
Others
Diamond Mining Market
Others
Global Sports and Fitness Wears Market
Others
Middle East Paper Making Machine Market
Others
Global Essential Oils and Plant Extracts for Livestock Market