
 Latin America Smart Home Market | 2026-2036
Latin America Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Smart Home Market Insights
ANATEL certification requirements in Brazil are broadening the cost-of-entry calculus for device manufacturers seeking market access. Schneider Electric leverages its regional manufacturing footprint to sustain compliance advantages across Mercosur trade corridors. Intelbras anchors domestic production with localized R&D facilities in São Paulo state, while Amazon competes through voice-integrated ecosystem control over third-party hardware partnerships.
A smart home ecosystem comprises interconnected devices, sensors, and control platforms that automate environmental, security, and energy functions through protocols such as Zigbee mesh networking and Wi-Fi 6 backhaul. These systems reduce household energy consumption through automated HVAC and lighting optimization while enabling remote monitoring via cloud-connected mobile interfaces. Smart Security Systems command premium positioning due to elevated urban crime concerns in São Paulo and Mexico City, whereas Energy Management applications gain structural momentum from utility-tier demand response programs. Wi-Fi technology dominates connectivity architecture given existing residential infrastructure, though Z-Wave occupies niche positions in high-end developer projects seeking dedicated low-bandwidth reliability.
Brazil's ANATEL enforces electromagnetic compatibility and cybersecurity standards for connected devices, while Mexico's IFETEL governs spectrum allocation for IoT transmissions and Colombia's CRC regulates data privacy frameworks for residential monitoring systems. These overlapping compliance regimes elevate product development costs for entrants lacking regional legal expertise. Stakeholders must monitor evolving data localization requirements and interoperability mandates that will determine which platform ecosystems achieve sustainable lock-in across Latin American households.
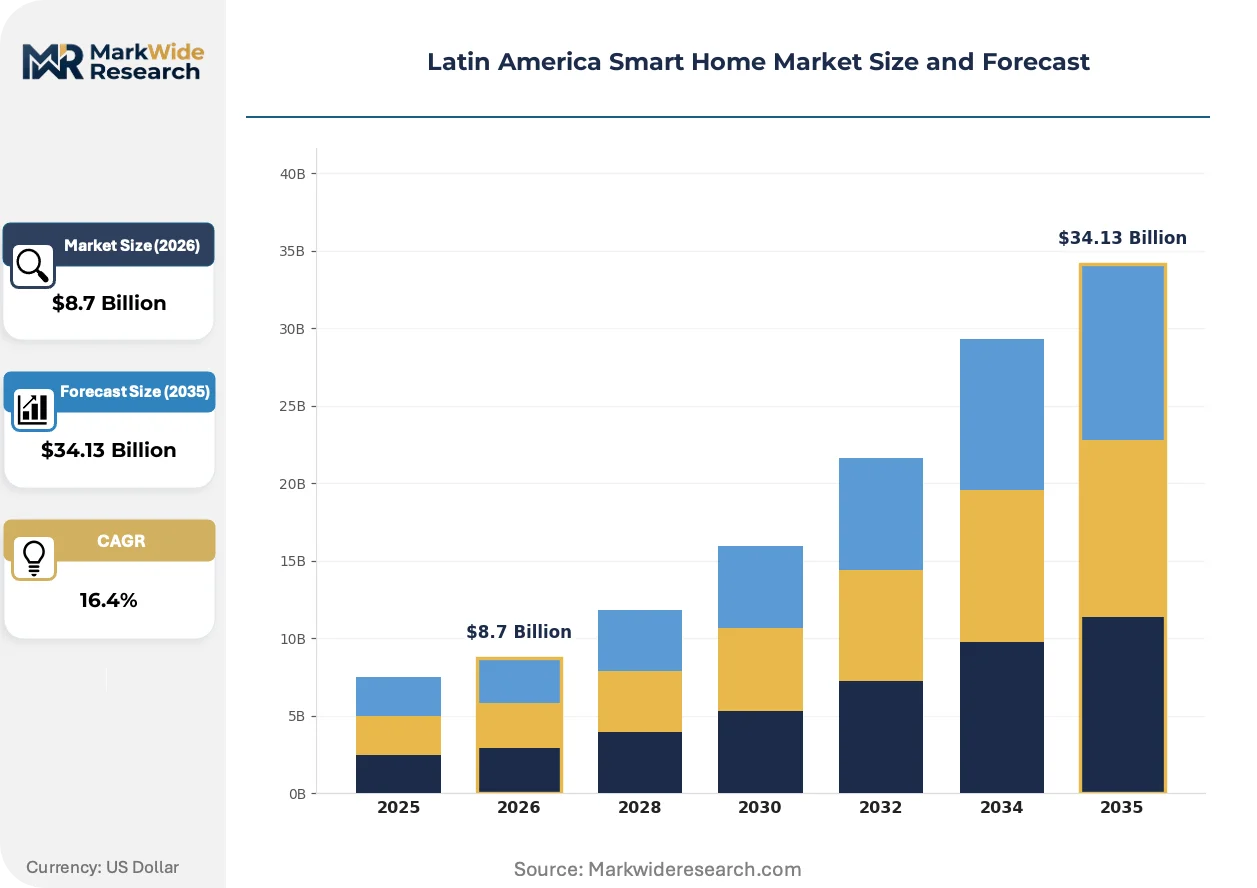
Market Dynamics
Wi-Fi 6 mesh infrastructure deployment across Brazilian metropolitan corridors is compressing installation timelines for whole-home automation systems while simultaneously elevating cybersecurity compliance burdens under ANATEL's evolving certification framework.
Growth Catalysts
- Energy efficiency mandates:Brazil's national utility regulators require demand-response compatibility in new residential construction, forcing smart thermostat and load-management adoption across São Paulo and Rio de Janeiro metropolitan zones.
- Property developer pre-installation:Mexico City's vertical residential tower boom embeds integrated security and lighting control as standard amenities, capturing buyer preference before retail channel engagement.
- Zigbee mesh networking:Low-power protocol standardization reduces hardware interoperability friction, enabling cross-brand sensor integration that lowers consumer switching costs.
Market Restraints
- Semiconductor input volatility:Memory chip and RF module cost swings compress hardware margins for device manufacturers lacking captive foundry relationships.
- Supply concentration in East Asian assembly:Final device production clusters in Shenzhen and Taipei create 45-60 day lead time exposure for Latin American distributors.
- ANATEL electromagnetic compatibility testing:Extended certification queues delay product launches by 8-14 weeks versus comparable FCC or CE marking timelines.
Strategic Opportunities
- Colombia's secondary cities:Medellín and Cali exhibit sub-15% smart device penetration versus Bogotá's 34%, creating whitespace for localized Spanish-language platform deployment.
- Matter protocol convergence:Unified application-layer standard bridging Wi-Fi, Thread, and Zigbee eliminates ecosystem lock-in, enabling multi-brand retail bundling.
- Utility-tier demand response incentives:Mexican CFE's time-of-use tariff restructuring subsidizes smart meter and load-controller installation in Monterrey industrial-residential corridors.
Industry Challenges
- Cybersecurity firmware talent scarcity:Embedded systems security engineering commands 40% salary premiums in São Paulo, constraining vendor R&D scaling.
- Legacy electrical infrastructure retrofit complexity:Neutral-wire absence in 1970s-era Brazilian housing stock complicates smart switch installation without rewiring.
- Interoperability certification backlog:Thread Group and Connectivity Standards Alliance testing queue delays extend platform launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Smart Home Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lights, Smart Thermostats, Smart Security Systems, Smart Appliances Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Application: Home Automation, Energy Management, Security Monitoring, Health Monitoring End User: Residential, Renters, Homeowners, Property Managers |
| Companies Covered | Schneider Electric, Honeywell International, ABB, Siemens, Amazon, Google, Bosch, Intelbras, Positivo Casa Inteligente, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Smart Home Market Trends and Innovations
Protocol unification and voice-interface integration are compressing the competitive window for standalone device manufacturers while elevating platform-level control battles.
Thread wireless networking is overtaking Z-Wave in high-end developer specifications across Mexico City's Polanco and Condesa districts. Property managers specify Thread-native devices for their IPv6-native architecture and reduced gateway dependency. This technology shift is overtaking dedicated low-bandwidth installations, collapsing the addressable market for proprietary hub ecosystems.
Brazil's ANATEL cybersecurity certification expansion now mandates firmware update transparency and encrypted local storage for residential monitoring cameras. The regulation forces hardware redesigns costing 12-18% of BOM for non-compliant legacy architectures. Security system vendors serving São Paulo's gated communities face the steepest compliance recalibration.
Subscription monetization is displacing upfront hardware margins as the dominant revenue architecture. Colombian consumers now favor $8-14 monthly monitoring fees over $400-600 capital outlays for professional installation. This preference rotation concentrates in Bogotá's rental-dominant housing stock where tenant turnover accelerates device depreciation cycles.
Latin America Smart Home Market Segmentation
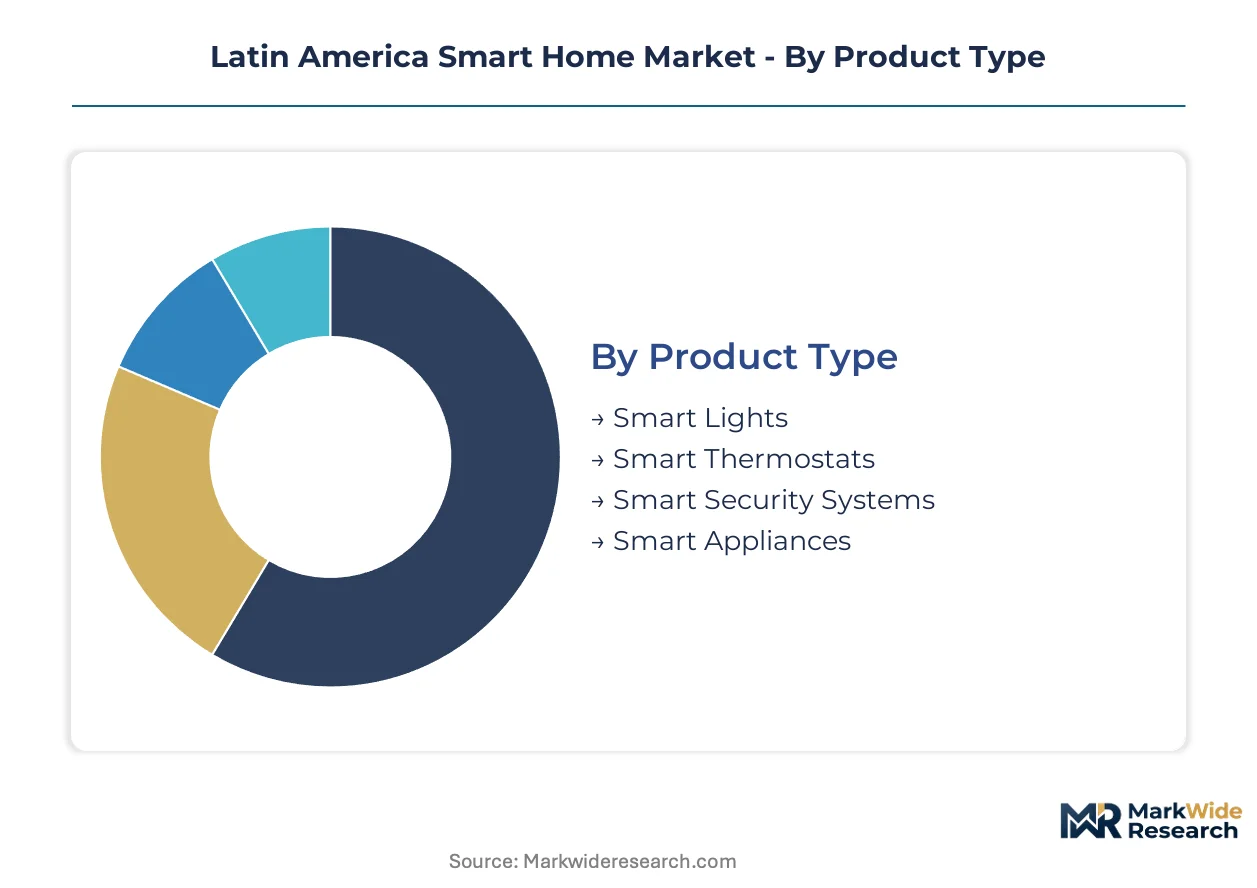
Smart home segmentation in Latin America reflects divergent infrastructure realities across metropolitan corridors and income tiers. Product and technology choices cluster around installation complexity, connectivity reliability, and regulatory compliance burdens that vary sharply between São Paulo high-rises and Colombian secondary cities.
Product Type:
Buyer differentiation in this category hinges on upfront capital tolerance versus recurring subscription preference across Brazil's gated communities and Mexico's rental-dominant towers.
- Smart Security Systems:Camera networks, motion sensors, and cloud-connected monitoring platforms dominate São Paulo and Mexico City demand. Property developers in Polanco and Condesa districts pre-install these as standard amenities, while ANATEL's cybersecurity certification mandates force firmware redesigns for residential monitoring cameras.
- Smart Thermostats:HVAC automation devices with utility-tier demand response integration gain structural momentum from Brazil's national energy efficiency mandates. São Paulo and Rio de Janeiro metropolitan zones require compatibility in new construction, compressing adoption timelines for load-management hardware.
- Smart Lights:Automated lighting controls with dimming and scheduling functionality appeal to Bogotá's rental market where tenant turnover accelerates device depreciation cycles.
- Smart Appliances:Connected refrigerators, washing machines, and cooking equipment with remote monitoring capabilities concentrate in Brazil's upper-middle-class metropolitan households with robust Wi-Fi mesh infrastructure.
Smart Security Systems lead volumes today; Smart Thermostats are gaining share fastest.
Technology:
Protocol selection tracks existing residential infrastructure density and developer specifications for gateway dependency versus mesh autonomy.
- Wi-Fi:Dominates connectivity architecture through existing residential infrastructure penetration. Wi-Fi 6 mesh deployment across Brazilian metropolitan corridors compresses installation timelines for whole-home automation while elevating ANATEL cybersecurity compliance burdens.
- Zigbee:Low-power mesh networking standard reduces hardware interoperability friction through cross-brand sensor integration. Zigbee's protocol standardization lowers consumer switching costs across multi-vendor deployments.
- Z-Wave:Dedicated low-bandwidth protocol occupies niche positions in high-end developer projects seeking reliability without IP congestion, though Thread is displacing this specification in Mexico City's premium districts.
- Bluetooth:Short-range protocol serves point-to-point device commissioning and temporary control interfaces rather than persistent whole-home networks.
Wi-Fi anchors installed base; Zigbee shows steepest expansion trajectory as interoperability demands intensify.
Application:
Use-case prioritization splits between crime-driven security spending in urban centers and efficiency mandates pressuring new construction specifications.
- Security Monitoring:Remote surveillance and alert systems command premium positioning due to elevated urban crime concerns in São Paulo and Mexico City. Subscription monetization now dominates revenue architecture over upfront hardware margins.
- Energy Management:Automated HVAC and lighting optimization reduces household consumption through demand response program integration. Mexican CFE's time-of-use tariff restructuring subsidizes smart meter installation in Monterrey industrial-residential corridors.
- Home Automation:Integrated environmental control through centralized platforms concentrates in new vertical residential towers where property developers capture buyer preference before retail channel engagement.
- Health Monitoring:Elder care sensors and emergency response systems remain nascent outside Brazil's aging metropolitan demographics with private healthcare integration.
Security Monitoring commands revenue concentration; Energy Management is climbing the fastest on regulatory tailwinds.
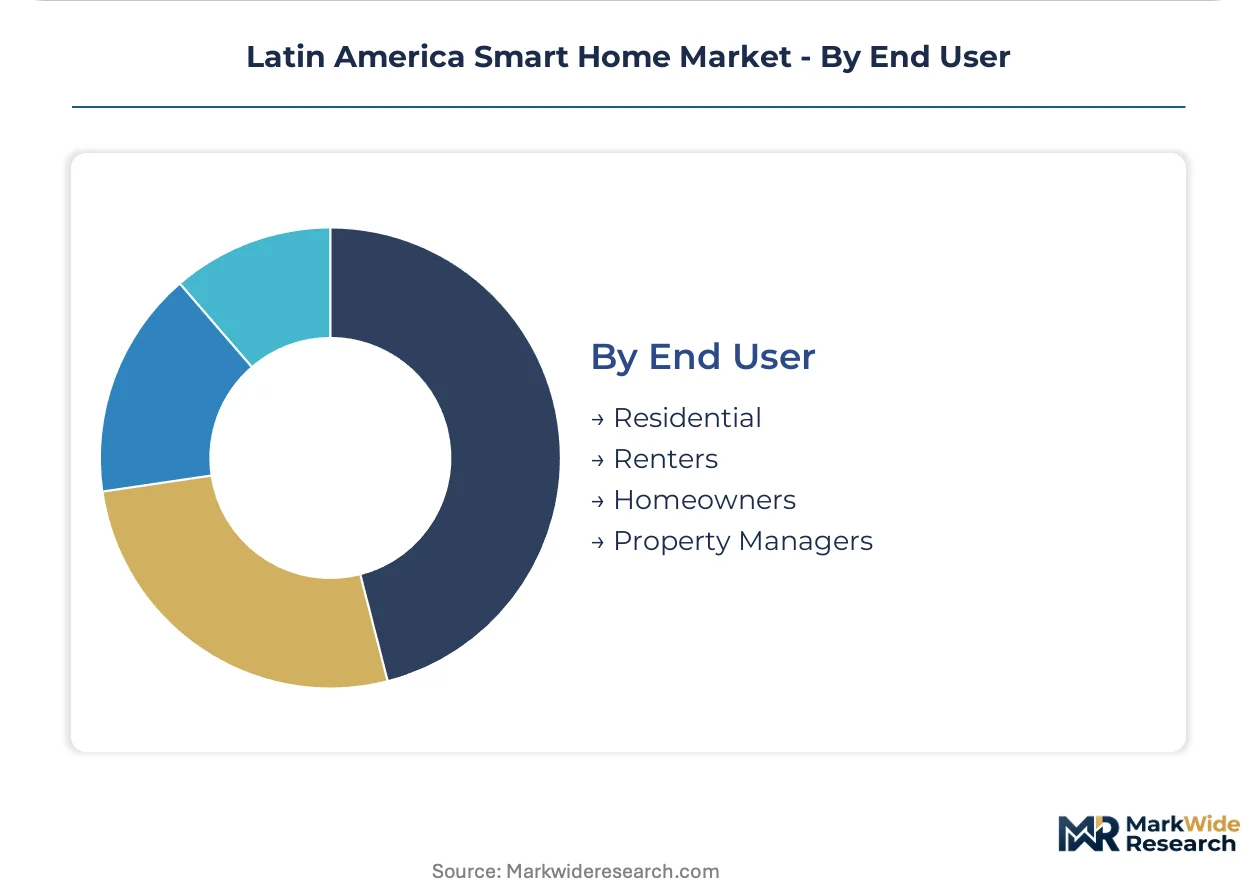
End User:
Customer type stratification reflects tenure security, installation authority, and depreciation risk tolerance across Latin America's divergent housing stock.
- Property Managers:Institutional buyers specifying Thread-native devices for IPv6 architecture and reduced gateway dependency in Mexico City's vertical tower boom. Pre-installation as standard amenities captures tenant preference before individual purchase decisions.
- Homeowners:Permanent residents with rewiring authority and long depreciation horizons drive retrofit demand in Brazil's 1970s-era housing stock despite neutral-wire absence complicating smart switch installation.
- Renters:Bogotá's rental-dominant housing stock favors $8-14 monthly monitoring fees over $400-600 capital outlays, accelerating subscription preference rotation.
- Residential:Aggregate household category spanning owned and leased dwellings with varying infrastructure readiness across metropolitan Brazil and Colombian secondary cities.
Property Managers drive specification authority; Homeowners deliver highest lifetime value per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems security engineers command 40% salary premiums in São Paulo, constraining vendor R&D scaling across Latin America's smart home corridor. Brazil's ANATEL certification queues and Mexico's IFETEL spectrum governance create divergent compliance calendars. Colombia's CRC data privacy frameworks add a third regulatory layer for residential monitoring systems.
Brazil
São Paulo and Rio de Janeiro metropolitan zones drive security monitoring and energy management hardware demand through utility-tier demand response mandates. ANATEL enforces electromagnetic compatibility testing that extends certification timelines by 8-14 weeks versus FCC or CE equivalents. Intelbras anchors domestic production with localized R&D facilities in São Paulo state, while Schneider Electric leverages regional manufacturing for Mercosur trade corridor advantages.
Mexico
Mexico City's vertical residential tower boom embeds integrated security and lighting control as standard amenities, capturing buyer preference before retail channel engagement. IFETEL governs spectrum allocation for IoT transmissions across industrial-residential corridors in Monterrey. Thread wireless networking overtakes Z-Wave in Polanco and Condesa district developer specifications, collapsing addressable markets for proprietary hub ecosystems.
Colombia
Bogotá's rental-dominant housing stock accelerates subscription monetization over upfront hardware margins, with consumers favoring $8-14 monthly monitoring fees. CRC regulates data privacy frameworks for residential monitoring systems, elevating product development costs for entrants lacking regional legal expertise. Medellín and Cali exhibit sub-15% smart device penetration versus Bogotá's 34%, creating whitespace for localized Spanish-language platform deployment.
Argentina
Buenos Aires metropolitan households concentrate demand for Wi-Fi 6 mesh infrastructure that compresses whole-home automation installation timelines. The country's national communications regulator enforces electromagnetic compatibility standards for connected devices entering through Mercosur trade corridors. Córdoba and Rosario secondary cities lag capital-region penetration, presenting channel expansion opportunities for cross-brand Zigbee sensor integration.
Chile
Santiago's upper-middle-class residential towers prioritize energy management applications through utility restructuring programs. The national telecommunications regulator oversees spectrum coordination for IoT mesh networks in dense urban corridors. Valparaíso and Concepción metropolitan zones exhibit infrastructure readiness gaps that delay smart thermostat adoption despite national efficiency policy alignment.
Latin America Smart Home Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive compliance expertise across overlapping regulatory regimes. Tiered concentration separates integrated platform operators from component specialists and regional distributors. Two strategic archetypes dominate: multinational electrical equipment manufacturers with localized certification capabilities, and domestic technology conglomerates with government relationship advantages. Competitive moves cluster around ANATEL pre-certification investments and Thread protocol native development for premium developer specifications.
Among multinational electrical equipment manufacturers, Schneider Electric and ABB exemplify the compliance-anchored archetype through regional manufacturing footprints that sustain Mercosur trade advantages. Siemens occupies a comparable position with industrial automation heritage translating into residential platform control. Amazon represents the voice-integrated ecosystem vector, competing through third-party hardware partnerships rather than captive device manufacturing. These three anchors illustrate divergent pathways to market access: regulatory compliance depth, industrial system integration, and consumer platform aggregation.
| Leading Market Players |
|---|
| Schneider Electric |
| Honeywell International |
| ABB |
| Siemens |
| Amazon |
| Bosch |
| Intelbras |
| Positivo Casa Inteligente |
| Others |
Pricing and Supply Chain Analysis
Subscription preference rotation across Bogotá's rental-dominant housing stock forces supply chains to pivot toward recurring-revenue hardware architectures with embedded cellular connectivity modules rather than upfront retail SKUs.
Pricing Analysis
Bundled subscription-plus-hardware packages versus unbundled device-only sales define the pricing architecture across Latin American metropolitan corridors. Three-tier pricing structure across premium, standard, and economy levels separates ANATEL-certified Thread-native systems from Zigbee mesh intermediates and basic Wi-Fi point solutions. Price differentiation rests on certification tier and after-sales monitoring service depth. Pricing pressure stems from semiconductor input volatility compressing hardware margins for distributors lacking captive foundry relationships. Renters in Mexico City's vertical towers exhibit highest price sensitivity; property managers specifying pre-installed amenities in Polanco and Condesa districts show lowest.
Supply Chain Analysis
Freight cost exposure from East Asian assembly clusters in Shenzhen and Taipei creates 45-60 day lead time vulnerability for Latin American distributors managing just-in-time inventory. Final device production concentrates in China, Taiwan, and South Korea, with RF modules and memory chips drawing from concentrated foundry capacity. Raw material dependencies span silicon wafers, lithium-ion cells for battery-backed sensors, and rare-earth magnets for actuator motors. Single-source vulnerability in RF semiconductor supply chains threatens production continuity during geopolitical trade disruptions. Distribution runs through authorized distributor networks serving electrical contractor channels and direct developer procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ANATEL's cybersecurity certification expansion for residential monitoring cameras creates mandatory hardware redesign demand across São Paulo's gated communities.
For Market Incumbents: Lock in compliance advantages by accelerating ANATEL pre-certification investments before queue backlogs extend further. Deepen backward integration into firmware development capabilities to offset embedded systems security engineering salary premiums in São Paulo. Threat of Matter protocol convergence eliminating ecosystem lock-in demands defensive platform integration moves. Certification investment represents the critical lever for sustaining Mercosur trade corridor positioning against Schneider Electric and ABB manufacturing footprints. For New Entrants and Emerging Players: Capture whitespace in Medellín and Cali's sub-15% smart device penetration zones through localized Spanish-language platform deployment. Target utility-tier demand response program integration in Monterrey's industrial-residential corridors where Mexican CFE tariff restructuring subsidizes smart meter adoption. Go-to-market angle should emphasize Zigbee mesh interoperability to lower consumer switching costs against incumbent proprietary ecosystems. For Investors and Strategic Acquirers: Asymmetric upside sits with compliance-anchored regional manufacturers possessing ANATEL certification expertise and Thread-native development capabilities. Long-term viability over the projection horizon favors acquisition targets with government relationship advantages in São Paulo state and captive R&D facilities. Signal to watch is ANATEL electromagnetic compatibility testing queue lengths as inflection indicator for product launch window compression.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Pre-Certification Investment | Compresses product launch windows by 8-14 weeks versus reactive certification pathways. |
| Thread Protocol Native Development | Captures Polanco and Condesa district developer specifications displacing Z-Wave installations. |
| Subscription Monetization Pivot | Aligns revenue architecture with Bogotá rental market preference for $8-14 monthly fees. |
| Utility Partnership Integration | Secures CFE demand response program eligibility in Monterrey industrial corridors. |
| Regional Manufacturing Footprint | Sustains Mercosur trade advantages through São Paulo state production anchoring. |
Research Methodology
Coverage spans Brazil, Mexico, Colombia, Argentina, and Chile, with primary inputs from each market's metropolitan corridor stakeholders. Primary interviews engaged smart home platform engineering directors, property developer procurement leads, electrical contractor channel managers, and ANATEL certification consultants. Secondary validation drew from ANATEL regulatory filings, IFETEL spectrum allocation records, CRC data privacy framework updates, customs import databases for connected device categories, and utility demand response program documentation. Bottom-up unit economics modeling triangulated against top-down market sizing across technology protocol segments.
Granularity-level modeling deployed country-by-country protocol adoption curves, with Wi-Fi, Zigbee, Z-Wave, and Thread connectivity architectures tracked separately. Product type segmentation captured Smart Security Systems, Smart Thermostats, Smart Lights, and Smart Appliances with divergent installation complexity profiles. Application-level modeling distinguished Security Monitoring, Energy Management, Home Automation, and Health Monitoring use cases with varying regulatory tailwinds. End user archetypes stratified property managers, homeowners, renters, and aggregate residential demand with distinct depreciation horizons. CAGR derivation synthesized historical certification queue data, utility mandate implementation timelines, and developer pre-installation contract flows.
Regulatory enforcement variance, semiconductor supply disruption events, and currency fluctuation in Mercosur trade corridors are the dominant revision risks to modeled outputs. Forecasts embed assumptions regarding ANATEL cybersecurity certification expansion timelines and Matter protocol adoption velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
China Online Gambling Market
Others
Brazil Cane Sugar Market
Others
Middle East and Africa Cocoa Products Market
Others
Rugged Devices Market
Others
Nuclear Power Cables Market
Others
Cashew Kernel Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Deep Sea Mining Market
Others
Bulgur Market
Others
Snus Market
Others
Lychee Market
Others
Global Aircraft Sensors Market
Others
Programmatic Display Market
Others
Language Translation Device Market
Others
Smart Home Platforms Market
Others
LAMEA Astrology Market