
 Global Sportswear Market | 2026-2036
Global Sportswear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sportswear Market Outlook
The capital-intensity divergence between vertically integrated manufacturers and asset-light brand licensors is bifurcating competitive returns across the industry. Nike sustains its lead through proprietary Flyknit manufacturing scale and direct-to-consumer channel control. Anta Sports anchors its position through backward integration into textile production and dominant retail distribution across Greater China. On Running differentiates via Swiss-engineered performance footwear and limited SKU discipline.
Global sportswear encompasses engineered apparel, footwear, and accessories designed for athletic performance, recovery, and physical activity, typically incorporating moisture-wicking synthetic fibers, compression weaves, or responsive cushioning systems with specified breathability and durability parameters. The primary commercial purpose centers on enhancing biomechanical efficiency, thermoregulation, and injury prevention during exercise while extending product lifecycles through technical material construction. Footwear commands the largest value pool due to complex midsole chemistry and brand premiumization, while activewear grows fastest as athleisure dissolves boundaries between gym and casual wardrobes. The accessories segment remains fragmented with lower barriers, though smart wearable integration is elevating average selling prices.
The EU Green Deal and REACH chemical restrictions are mandating recycled content minimums and eliminating per- and polyfluoroalkyl substances from water-repellent finishes, forcing reformulation across European supply chains. China's SAMR enforces GB standards for textile safety and labeling, while the US FTC monitors green marketing claims under its Green Guides to prevent deceptive environmental assertions. Stakeholders must monitor how diverging chemical compliance regimes between Europe and Asia reshape supplier qualification costs and regional sourcing footprints.
Market Dynamics
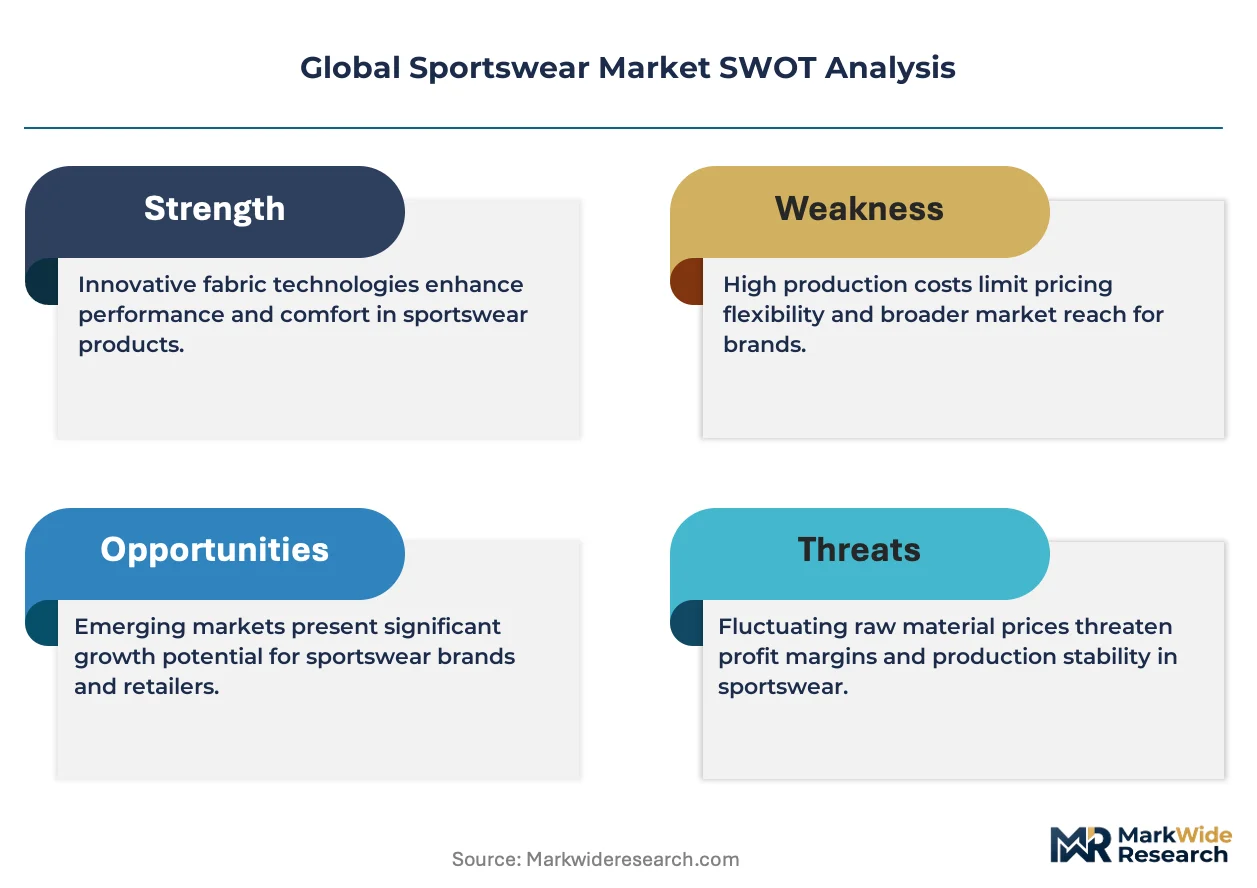
Recycled polyester fiber innovations and REACH chemical compliance mandates are bifurcating material sourcing strategies, forcing suppliers to rebuild European supply chains while Asian producers exploit cost-advantaged virgin feedstock.
Growth Catalysts
- REACH chemical restrictions:The EU Green Deal's elimination of per- and polyfluoroalkyl substances from water-repellent finishes is accelerating reformulation investment across textile chemistry, opening first-mover advantages for compliant suppliers.
- Women's activewear segments:Rising middle-class fitness participation in China, India, and Brazil is expanding addressable demand beyond traditional male-skewed athletic categories into lifestyle-integrated performance apparel.
- Direct-to-consumer channel control:Proprietary manufacturing scale in engineered knit uppers and responsive midsole chemistry is capturing margin pools previously extracted by wholesale intermediaries.
Market Restraints
- Petrochemical feedstock volatility:Synthetic fiber production remains tethered to oil price swings, compressing margin predictability for polyester-dependent activewear suppliers without backward integration into polymer production.
- Supplier concentration in Greater China:Textile dyeing and finishing capacity clusters in Zhejiang and Guangdong provinces, creating geographic risk exposure that compliance divergence between European and Asian chemical regimes amplifies.
- Biomechanical performance ceiling:Midsole energy return metrics in performance footwear are approaching asymptotic limits from conventional ethylene-vinyl acetate and thermoplastic polyurethane chemistries.
Strategic Opportunities
- Smart wearable integration:Embedded biometric sensors and haptic feedback systems in performance apparel are elevating average selling prices in the accessories segment where barriers remain lowest.
- PLI scheme incentives:India's production-linked incentive framework for textile manufacturing is attracting greenfield investment in technical fiber capacity serving domestic and export demand.
- Biomechanical efficiency convergence:Compression weave engineering and responsive cushioning system development are dissolving category boundaries between recovery apparel and active performance wear.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists capable of substituting fluorinated water repellents with silicone or hydrocarbon alternatives command premium compensation, constraining R&D throughput.
- Dual certification timelines:Simultaneous compliance with EU REACH and China's GB standards requires parallel testing protocols that extend product development cycles by six to nine months.
- Legacy dyeing infrastructure:Water-intensive conventional textile finishing in South Asian supply chains faces stranded asset risk as zero-liquid-discharge mandates proliferate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sportswear Market |
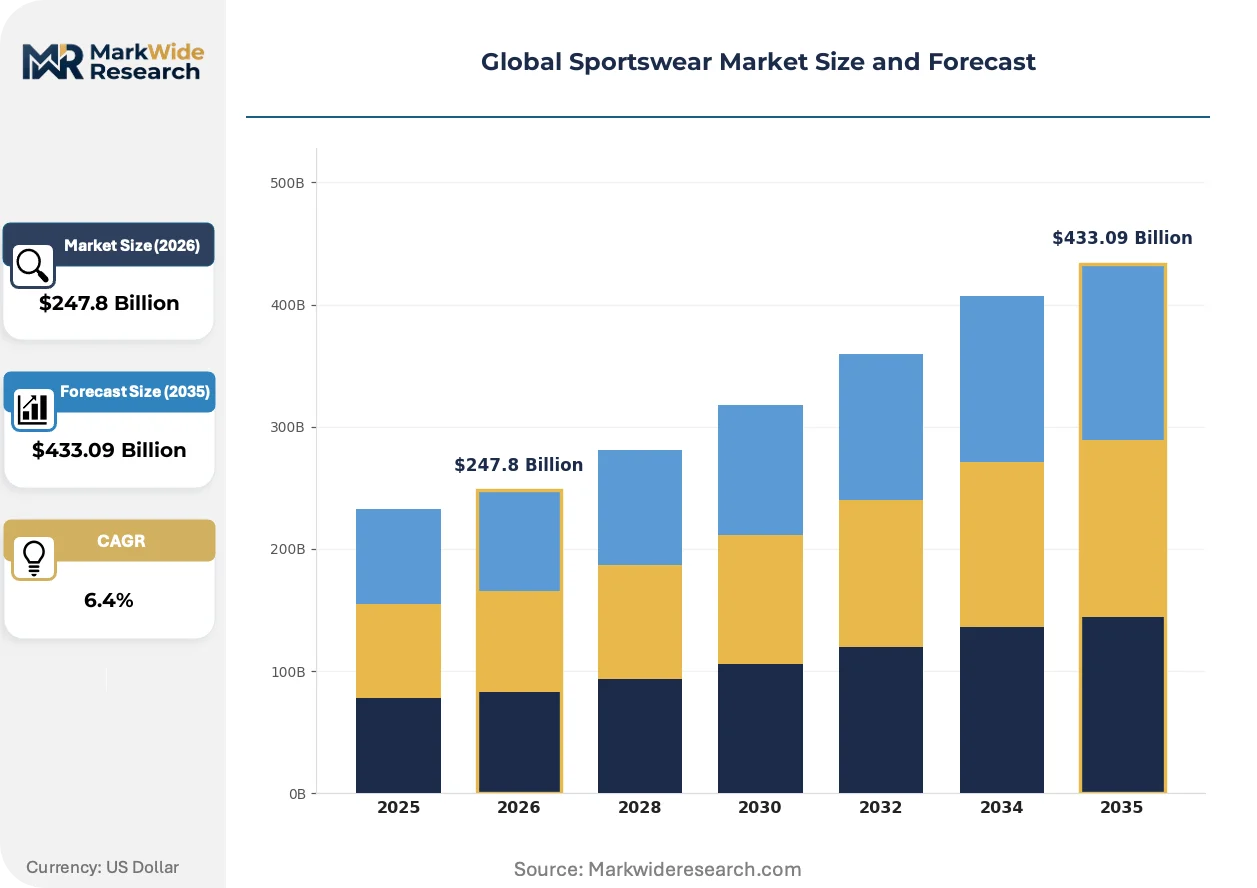
| Market Size in 2026 | $247.8 Billion |
| Market Size in 2035 | $433.09 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footwear, Activewear, Accessories, Equipment Customer Type: Men, Women, Kids, Athletes Distribution Channel: Online, Retail Stores, Specialty Stores, Distributors End Use: Fitness, Outdoor Activities, Competitive Sports, Leisure |
| Companies Covered | Lululemon Athletica, Puma, Nike, New Balance, Under Armour, Adidas, On Running, Salomon, Anta Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sportswear Market Strategic Shifts
Material science breakthroughs and regulatory chemical phase-outs are converging to restructure competitive advantage around sustainable feedstock security rather than brand equity alone.
Biodegradable polyester alternatives derived from agricultural waste streams are decomposing the virgin petroleum feedstock lock-in that has defined synthetic activewear economics since the 1970s. Performance brands in Germany and Switzerland are piloting these materials in limited capsule collections at 40-60% price premiums. The technology is decomposing the historical cost barrier between mass-market and sustainable positioning, enabling mid-tier suppliers to capture eco-premium positioning without legacy brand investment.
China's SAMR enforcement of GB standards for textile safety and labeling is tightening import requirements for foreign sportswear brands accessing domestic retail channels. The industrial consequence is mandatory in-country testing partnerships that add 8-12% to landed cost structures. European and North American suppliers with established Shanghai or Shenzhen quality assurance infrastructure are absorbing this friction more efficiently than newer entrants.
After-sales service unbundling is disrupting the traditional warranty-replacement model for performance footwear. Subscription-based resoling and midsole refresh programs in urban fitness clusters across London, New York, and Tokyo are replacing unit-sales dependence with recurring revenue streams. This pattern is most visible among trail running and CrossFit practitioner segments where equipment durability expectations exceed standard product lifecycles.
Global Sportswear Market Segmentation
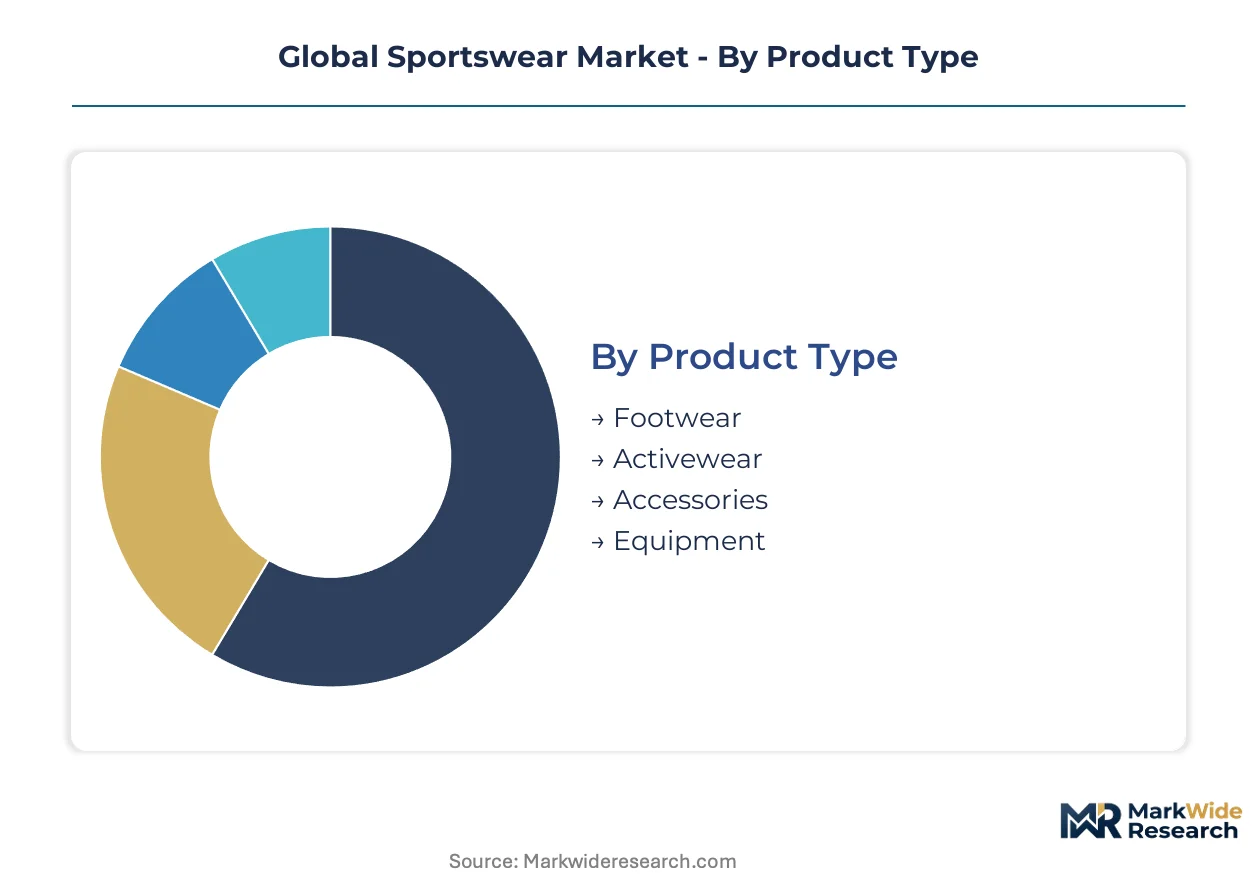
Segmentation in sportswear separates margin capture from volume throughput. Product architecture, customer physiology, channel control, and use-case intensity each create distinct competitive battlegrounds with divergent investment requirements.
Product Type:
Margin pools concentrate in categories where material chemistry and biomechanical engineering create defendable technical differentiation.
- Footwear:Complex midsole formulations incorporating thermoplastic polyurethane and ethylene-vinyl acetate blends command premium positioning through energy-return metrics. Demand clusters in urban running communities across the United States, Germany, and Japan where gait analysis and injury prevention drive replacement cycles.
- Activewear:Engineered knit constructions with moisture-wicking synthetic fibers and compression weave architectures serve CrossFit practitioners and yoga practitioners in London, Sydney, and São Paulo. Athleisure boundary dissolution extends wear occasions beyond gym environments.
- Accessories:Headbands, socks, and training aids carry lower technical barriers but integrate smart biometric sensors in premium tiers.
- Equipment:Resistance bands, weights, and mats face commoditization pressure from unbranded Asian suppliers.
The dominant share belongs to Footwear, while Activewear is closing the gap fastest.
Customer Type:
Physiological differences and participation patterns split addressable demand into distinct product development tracks with varying SKU complexity.
- Women:Expanded size grading, maternity-adaptive compression, and lifestyle-integrated aesthetics target middle-class fitness adopters in China, India, and Brazil. Social fitness class participation in Mumbai and Jakarta drives category-specific bra and legging demand.
- Men:Traditional performance metrics around durability and sweat management dominate purchasing criteria in established markets.
- Kids:Growth-adjusted sizing and school-sport compliance requirements create replacement-driven demand cycles.
- Athletes:Elite-tier certification and federation approval standards limit supplier qualification to established technical specialists.
Women's segments are expanding most quickly, while Athletes retain the highest per-unit margin capture.
Distribution Channel:
Channel control determines margin retention versus wholesale extraction, with digital infrastructure investments reshaping competitive economics.
- Online:Direct-to-consumer platforms with virtual try-on and subscription replenishment models capture full retail margin in urban digital-native populations across the United States, United Kingdom, and South Korea.
- Retail Stores:Flagship experiential locations in Paris, Milan, and New York serve brand positioning and community building rather than pure transaction volume.
- Specialty Stores:Running shops and outdoor retailers provide technical fitting expertise that reduces return rates for complex footwear purchases.
- Distributors:Regional wholesale partners remain essential for market access in regulatory-complex emerging economies.
Online channels are climbing the fastest, though Specialty Stores defend the highest conversion rates for technical footwear.
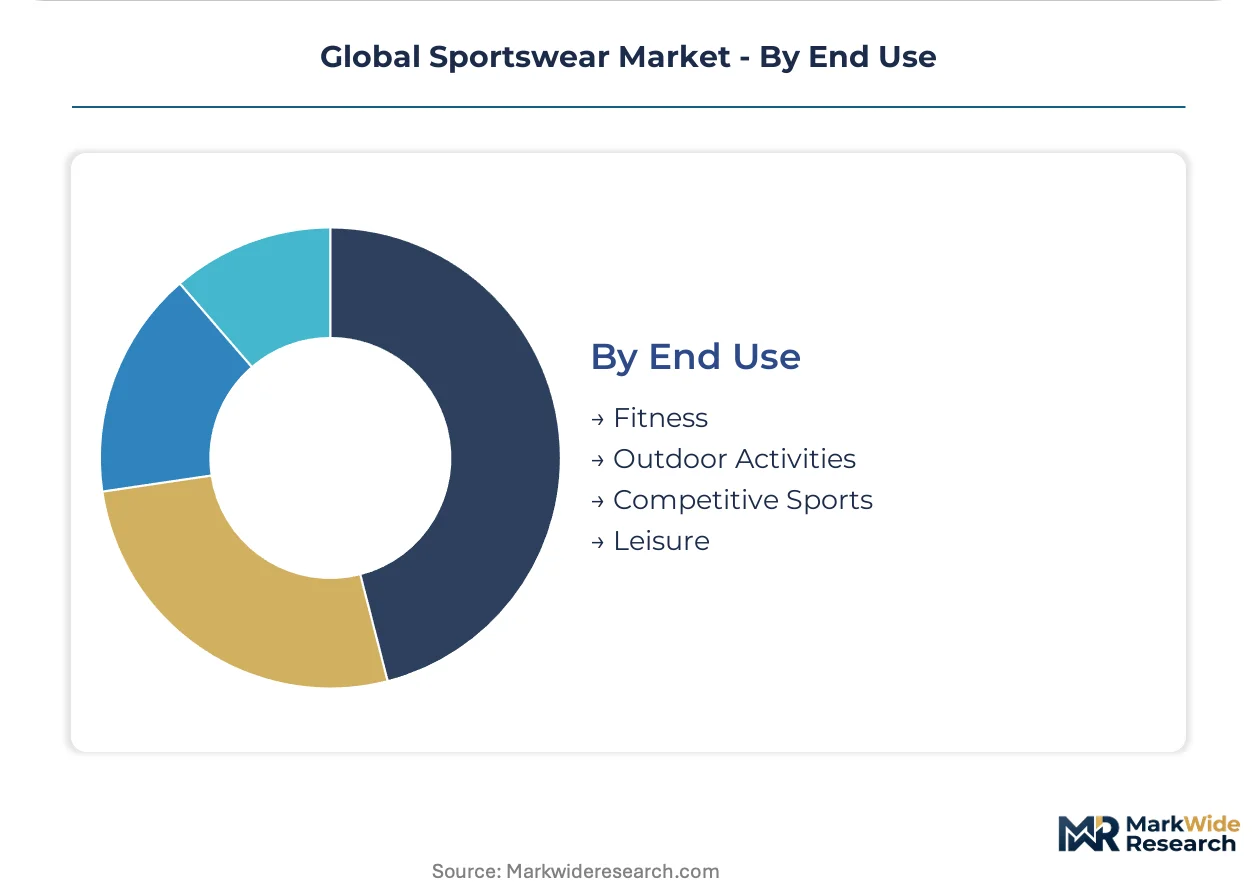
End Use:
Use-case intensity dictates material durability specifications and replacement frequency, separating premium performance from entry-level casual positioning.
- Fitness:Gym-based resistance training and studio cycling require sweat-resistant fabrics and stable cushioning systems. Demand concentrates in metropolitan fitness club memberships across Germany, Australia, and the United Arab Emirates.
- Outdoor Activities:Trail running, hiking, and climbing demand weather-resistant membranes and aggressive outsole traction. Technical requirements limit supplier qualification.
- Competitive Sports:Federation-regulated equipment standards and team uniform contracts create institutional procurement cycles with multi-year visibility.
- Leisure:Athleisure positioning prioritizes aesthetic versatility over technical performance, opening entry points for fast-fashion competitors.
Fitness holds the dominant share, while Outdoor Activities shows the steepest expansion trajectory as trail participation rises in Alpine and Pacific Northwest markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss technical footwear while cost-advantaged Asian manufacturing captures volume share. Divergent chemical compliance regimes between European REACH mandates and Asian feedstock economics are redrawing supplier qualification costs. Middle-class fitness participation in emerging economies is redirecting brand investment toward Asia-Pacific distribution infrastructure.
United States
Urban running communities in Austin and Boulder drive premium footwear replacement cycles through gait analysis services. The FTC enforces Green Guides standards that penalize deceptive environmental marketing claims. Portland and Boston host concentrated brand headquarters that anchor direct-to-consumer platform development.
China
SAMR enforcement of GB textile safety standards tightens import requirements for foreign brands accessing domestic retail channels. Zhejiang and Guangdong provinces cluster dyeing and finishing capacity that faces compliance divergence risk with European chemical regimes. Shanghai quality assurance infrastructure absorbs regulatory friction more efficiently than newer market entrants.
Germany
EU Green Deal REACH restrictions eliminate per- and polyfluoroalkyl substances from water-repellent finishes, accelerating reformulation investment. Bavaria and Baden-Württemberg host technical fiber R&D clusters piloting biodegradable polyester alternatives. Stuttgart and Munich serve as European headquarters for performance footwear engineering.
India
Mumbai and Jakarta social fitness class participation drives category-specific women's activewear demand. The PLI scheme for textile manufacturing attracts greenfield technical fiber investment serving domestic and export markets. Maharashtra and Gujarat industrial corridors concentrate emerging cut-and-sew capacity.
Brazil
Rio de Janeiro and São Paulo metropolitan fitness club memberships expand addressable demand beyond traditional male-skewed athletic categories. ANVISA pharmaceutical-adjacent regulatory frameworks influence sportswear safety labeling expectations. São Paulo state anchors Latin American distribution hub development for regional brand expansion.
Global Sportswear Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with proprietary manufacturing scale separating premium positioning from volume-driven suppliers. The market structure consolidates around three strategic tiers: vertically integrated manufacturers with captive textile production, asset-light brand licensors extracting design and marketing margins, and specialist engineering houses focused on biomechanical performance. Dominant competitive moves include backward integration into polymer and fiber production and direct-to-consumer channel control that captures wholesale margin pools.
Within the vertically integrated tier, Anta Sports exemplifies upstream control over textile production combined with dominant retail distribution. Among Swiss-engineered specialists, On Running occupies a position defined by limited SKU discipline and performance footwear innovation. Nike and Adidas anchor the brand-licensor archetype, representing scale-driven marketing investment and global sponsorship portfolio management.
| Leading Market Players |
|---|
| Lululemon Athletica |
| Puma |
| Nike |
| New Balance |
| Under Armour |
| Adidas |
| On Running |
| Salomon |
| Anta Sports |
| Others |
Value Chain & Pricing Dynamics
Polymer production scale in Zhejiang province anchors global synthetic fiber cost floors, compressing margin capture for non-integrated brands while elevating pricing power for suppliers with captive textile operations. This concentration bifurcates competitive economics between asset-light licensors and vertically integrated manufacturers.
Pricing Analysis
Configured-to-order pricing for custom-fitted performance footwear commands spreads against standard SKUs, with three-tier pricing structure across premium, standard, and economy levels stratifying by midsole chemistry tier and federation certification status. Price differentiation rests on Flyknit-style engineered knit complexity and REACH-compliant water-repellent finish reformulation costs. Pricing pressure stems from petrochemical feedstock volatility compressing polyester-dependent activewear margins. Entry-level leisure buyers exhibit highest price sensitivity; elite athletes and trail runners demonstrate lowest sensitivity due to injury-prevention prioritization.
Supply Chain Analysis
Inventory cycles extending six to nine months for dual-certified product lines strain working capital for suppliers navigating parallel EU REACH and China GB testing protocols. Manufacturing gravity centers on China, Vietnam, and Bangladesh for cut-and-sew assembly, with Taiwan and South Korea anchoring technical fiber and midsole chemistry innovation. Raw material dependencies draw from petroleum-derived polyester, thermoplastic polyurethane, and ethylene-vinyl acetate feedstocks. Single-source vulnerability concentrates in Zhejiang and Guangdong dyeing clusters facing zero-liquid-discharge mandate compliance costs. Distribution runs through direct-to-consumer platforms capturing wholesale margin pools alongside specialty running retailers providing gait-analysis services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical phase-outs and biodegradable fiber breakthroughs are disrupting feedstock economics, creating first-mover advantages for compliant suppliers while stranding conventional polyester-dependent capacity.
For Market Incumbents: Compound defensive positioning through backward integration into recycled polymer production and captive REACH-compliant finishing capacity in Portugal or Turkey to offset Asian regulatory divergence risk. Prioritize direct-to-consumer channel control to extract wholesale margin pools threatened by specialty retail consolidation. Accelerate smart wearable integration in accessories to elevate average selling prices in the lowest-barrier segment. For New Entrants and Emerging Players: Subscription-based after-sales service unbundling in urban fitness clusters represents an underserved white-space where incumbents cling to unit-sales dependence. Trail running and CrossFit practitioner segments in London, New York, and Tokyo offer penetrable demand with durability expectations exceeding standard product lifecycles. Pursue partnership-based go-to-market models with specialty retailers providing technical fitting expertise rather than competing for wholesale shelf space. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive textile production and established quality assurance infrastructure in Shanghai or Shenzhen. Long-term viability across the projection horizon hinges on feedstock security rather than brand equity alone. Acquisition targets should demonstrate compliant supplier status under both EU REACH and China GB standards. Monitor biodegradable polyester pilot scale-up in Germany and Switzerland as inflection indicator for sustainable feedstock cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Polymer Production | Captures margin pools threatened by petrochemical volatility and REACH compliance costs. |
| Direct-to-Consumer Platform Expansion | Eliminates wholesale extraction while capturing gait-analysis data for product development. |
| Dual Certification Infrastructure Investment | Absorbs SAMR and ECHA regulatory friction more efficiently than competitor entrants. |
| Smart Wearable Accessories Development | Elevates average selling prices in the lowest-technical-barrier segment through biometric integration. |
| Subscription-Based Resoling Programs | Replaces unit-sales dependence with recurring revenue in durability-focused outdoor segments. |
Study Parameters
A standing panel of brand sourcing directors, textile plant managers, specialty retail buyers, and polymer procurement leads provided ongoing calibration across primary fieldwork. Secondary validation drew from customs trade databases, SEC apparel and footwear filings, GB standards documentation, and ECHA REACH substance restriction updates. Bottom-up SKU-level demand modeling triangulated against top-down macroeconomic consumption indicators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by product architecture, customer physiology, channel control, and use-case intensity, with regional regulatory clusters modeled separately. CAGRs derived from historical elasticity patterns applied to projected middle-class fitness participation rates in China, India, and Brazil, with petrochemical feedstock pricing and compliance cost inflation as key sensitivity inputs.
Forecasts assume regulatory continuity in EU REACH, China GB, and US FTC Green Guides enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Space Power Supply Market
Others
Refractometer Market
Others
Process Instrumentation Equipment Market
Others
Latin America Travel Retail Market
Others
Programmatic Display Market
Others
Content Experience Platforms Market
Others
Buchner Funnels Market
Others
Global Video Processing Platform Market
Others
Security Envelopes Market
Others
Reduced-Risk Products (Rrps) Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Industrial Tablet PC Market
Others
North America Halal Food and Beverage Market
Others
Underwater Communication System Market
Others
Hypermarket Market
Others
Technical Films Market