
 Asia-Pacific Intercom Devices Market | 2026-2036
Asia-Pacific Intercom Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Intercom Devices Market Outlook
Cloud-managed software subscription layers is realigning how intercom vendors monetize hardware deployments across the Asia-Pacific. Dahua Technology Co. Ltd. leverages its video surveillance ecosystem to bundle AI-enabled intercom analytics with recurring service fees. Aiphone Corporation anchors its position through stringent Japanese manufacturing standards and premium channel partnerships across East Asia. Hangzhou Hikvision Digital Technology Co. Ltd. dominates project-scale tenders by integrating intercom modules with broader building security platforms.
Intercom devices in the Asia-Pacific region encompass electronic communication terminals that transmit audio, video, or data signals between fixed entry points and interior stations, typically operating across twisted-pair copper, Cat 5e/6 Ethernet, or wireless RF protocols with power-over-Ethernet compatibility. These systems serve primary functions of access verification, visitor screening, and emergency communication in multi-tenant dwellings, commercial offices, and industrial perimeters. Video intercom systems command the dominant share of value as residential developers in China and India spec visual verification as standard in mid-tier housing projects. IP-based technology segments expand fastest where fiber broadband infrastructure enables cloud connectivity and mobile app integration, while analog installations persist in retrofit markets across aging urban stock in Japan and Australia.
China's MIIT enforces network equipment cybersecurity review for IP-connected building devices, compelling firmware hardening and domestic data residency. Japan's METI promotes interoperability through JIS standards for residential automation interfaces, reducing vendor lock-in risks. India's BIS certification mandates electromagnetic compatibility testing for imported intercom electronics, filtering non-compliant suppliers from government and institutional tenders. Stakeholders must weigh certification pathway complexity against addressable market depth when prioritizing country entry sequences.
Market Dynamics
IP-to-analog migration pressure is compressing vendor margins while expanding addressable service revenue pools across residential and commercial building portfolios in the Asia-Pacific.
Growth Catalysts
- Smart city infrastructure mandates:China's MIIT network equipment cybersecurity review accelerates firmware-hardened IP intercom deployment in tier-one municipal housing projects.
- Fiber broadband penetration:India's metropolitan corridors now enable cloud-connected video verification as standard in mid-tier residential developments.
- Building automation convergence:Japanese developers specify JIS-standardized residential automation interfaces that reduce vendor lock-in and expand interoperability.
Market Restraints
- Semiconductor input volatility:Image sensor and SoC cost fluctuations compress hardware margins for video intercom manufacturers.
- Supply concentration risk:Tier-one city project tenders favor established platform vendors with integrated building security ecosystems.
- Analog retrofit persistence:Aging urban stock in Japan and Australia sustains legacy twisted-pair installations that delay full IP transition.
Strategic Opportunities
- Southeast Asia greenfield deployment:Vietnam and Indonesia residential complexes lack legacy infrastructure, enabling native IP architecture from inception.
- Cloud-managed service layering:Subscription-based mobile app integration and remote access management unlock recurring revenue streams.
- India BIS certification pathway:Electromagnetic compliance filtering creates protected market access for certified suppliers in government tenders.
Industry Challenges
- Cybersecurity firmware expertise gap:MIIT-mandated hardening requires specialized engineering talent scarce among mid-tier hardware vendors.
- Multi-protocol integration complexity:Hybrid deployments spanning analog, IP, and wireless RF demand interoperability testing that extends project timelines.
- Certification timeline compression:India's BIS electromagnetic compatibility testing creates six-to-nine month approval delays for imported electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Intercom Devices Market |
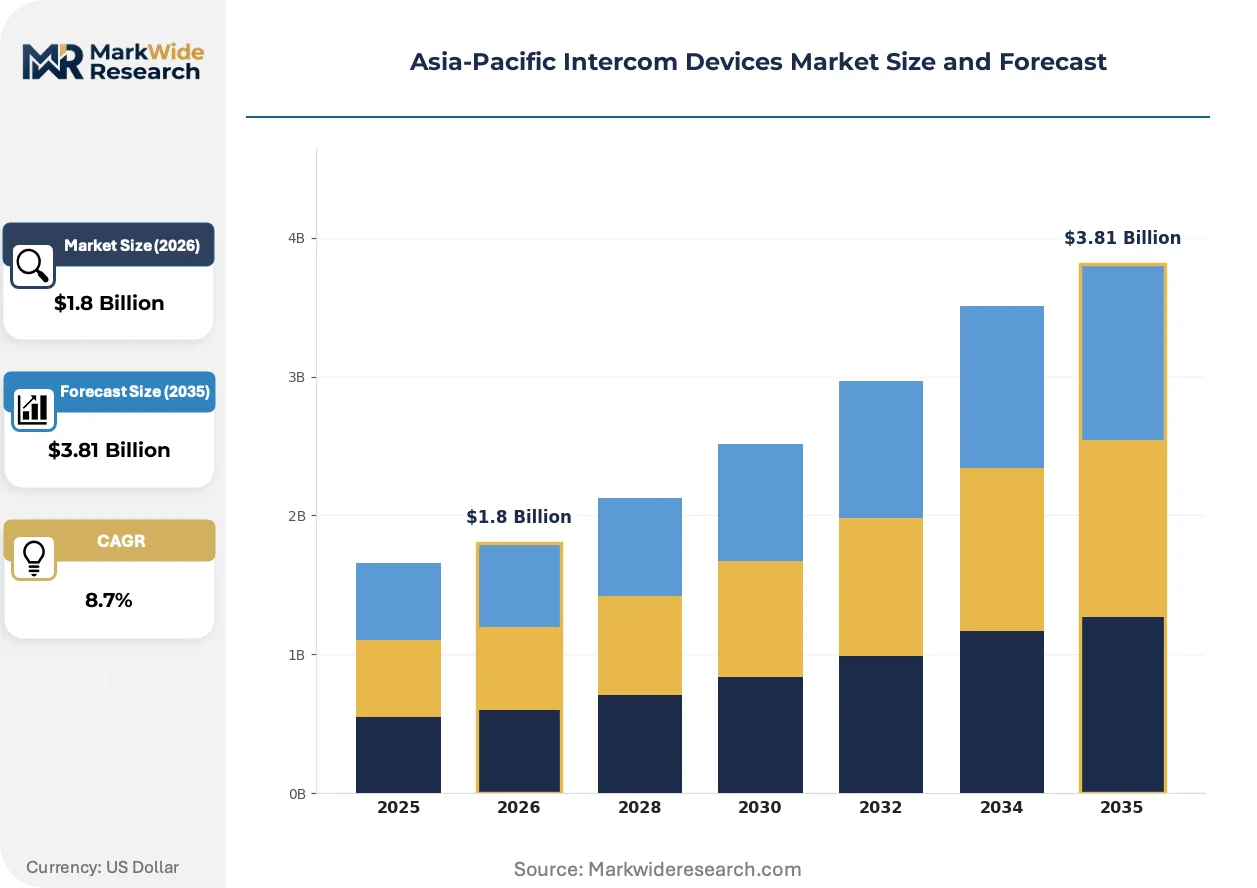
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Intercom, Wireless Intercom, Video Intercom, Audio Intercom End User: Residential, Commercial, Industrial, Institutional Technology: IP-Based, Analog, Digital, Hybrid Installation Type: Standalone, Integrated, Built-in, Surface-Mount |
| Companies Covered | Commax Co. Ltd., Dahua Technology Co. Ltd., Aiphone Corporation, Fermax Electronica S.A.U., TOA Corporation, Panasonic Corporation, Hangzhou Hikvision Digital Technology Co. Ltd., Legrand SA, Honeywell International Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Intercom Devices Market Strategic Shifts
Edge AI inference and mobile-first access management are redefining how intercom systems authenticate visitors and manage building entry workflows across the Asia-Pacific.
Facial recognition algorithms running on-device are integrating visitor identity verification with access control databases without cloud latency. Property managers in Shanghai and Shenzhen deploy these systems for contactless lobby entry. The technology is integrating tenant experience platforms with building management systems, compressing the vendor stack from three layers to one.
Japan's METI JIS standards for residential automation interfaces mandate open API specifications that reduce proprietary protocol dominance. Developers in Osaka and Tokyo now specify interoperable intercom modules that swap across three vendor ecosystems. Multi-tenant commercial projects face compressed procurement cycles as standardization eliminates custom integration testing.
Facility managers now bundle hardware capex into ten-year service contracts that include firmware updates and cybersecurity patching. This consumption-pattern shift displaces traditional equipment procurement in Singapore and Hong Kong commercial towers. Japanese residential developers pilot similar arrangements for new condominium projects, transferring obsolescence risk to vendors.
Asia-Pacific Intercom Devices Market Segmentation
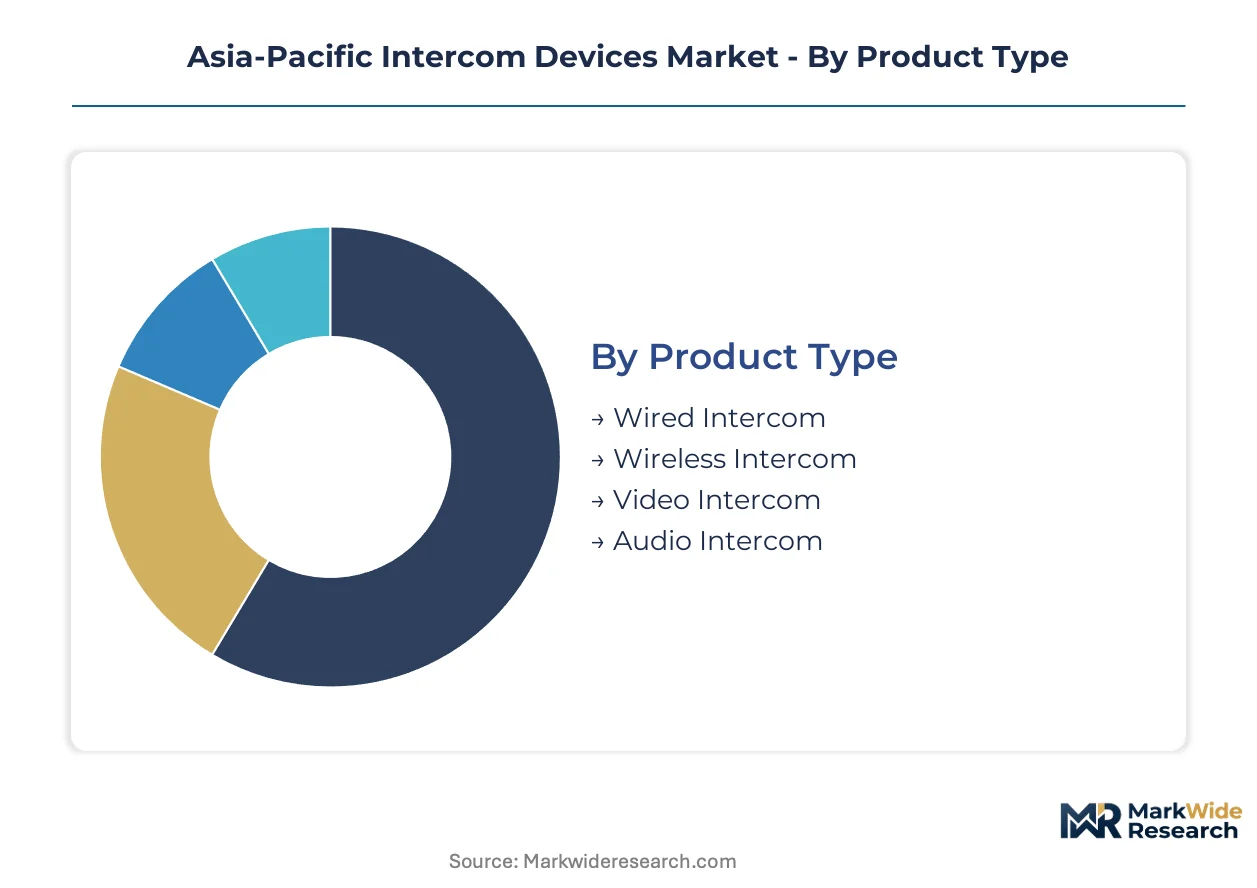
Segmentation in the Asia-Pacific intercom devices market reveals how certification burdens, infrastructure maturity, and end-use requirements fragment procurement patterns across product tiers. Buyers in China and India face divergent compliance pathways that reshape vendor selection and technology adoption curves.
Product Type:
Video intercom systems carry the heaviest certification load under China's MIIT cybersecurity review and India's BIS electromagnetic compatibility mandates, while audio-only variants navigate lighter approval pathways.
- Video Intercom:Systems integrate CMOS image sensors with H.265 compression and Power-over-Ethernet delivery. Demand concentrates in Shanghai and Shenzhen residential towers where visual verification is standard specification. China's MIIT network equipment review adds firmware hardening costs that filter mid-tier suppliers.
- Wired Intercom:Twisted-pair copper and Cat 5e/6 Ethernet architectures dominate retrofit projects across aging Japanese and Australian urban stock. Property managers in Osaka and Melbourne specify these for reliability in buildings lacking fiber infrastructure.
- Wireless Intercom:RF-based systems with Wi-Fi 6 or proprietary protocols serve greenfield Southeast Asian developments lacking structured cabling.
- Audio Intercom:Voice-only terminals persist in cost-sensitive Indian institutional tenders and legacy commercial installations.
Video intercom sits at the top of the volume ranking, with wireless intercom climbing the fastest.
End User:
Cost tiers separate premium integrated systems in commercial towers from economy standalone units in residential retrofit.
- Residential:Multi-tenant dwellings in China's tier-one cities and India's metropolitan corridors specify IP-connected video entry as standard in mid-tier projects. Developers in Bengaluru and Mumbai bundle intercom costs into overall construction budgets.
- Commercial:Office towers in Singapore and Hong Kong demand cloud-managed platforms with mobile app integration and ten-year service contracts.
- Industrial:Manufacturing perimeters in Vietnam and Indonesia require ruggedized audio systems with emergency broadcast capabilities.
- Institutional:Government buildings and healthcare facilities across India face BIS certification delays that extend procurement cycles.
Residential captures the largest addressable base, though commercial applications are gaining share fastest through service contract conversion.
Technology:
Application requirements drive technology selection, with cloud connectivity mandates pushing IP adoption in new construction while analog persists where infrastructure constraints dominate.
- IP-Based:Ethernet-delivered systems with edge AI inference enable facial recognition and mobile credentialing without cloud latency. Fiber broadband penetration in India's metropolitan corridors accelerates deployment.
- Analog:Legacy twisted-pair architectures sustain replacement demand across Japan's aging condominium stock and Australia's established urban centers.
- Digital:Proprietary digital protocols serve mid-market residential developers seeking upgrade paths from analog without full IP complexity.
- Hybrid:Mixed analog-IP installations bridge infrastructure gaps in phased retrofit projects across multi-building campuses.
IP-based technology commands the steepest expansion trajectory, while analog retains residual volume in replacement markets.
Installation Type:
Customer type separates project-scale integrated deployments from aftermarket standalone purchases.
- Integrated:Building management system convergence in Japanese commercial towers under METI JIS standards reduces vendor stack layers from three to one.
- Standalone:Self-contained units serve small residential retrofits and cost-sensitive institutional tenders across Southeast Asia.
- Built-in:Flush-mounted designs align with premium condominium aesthetics in Seoul and Taipei luxury developments.
- Surface-Mount:Exposed installations dominate quick-turn commercial retrofits and industrial perimeter applications.
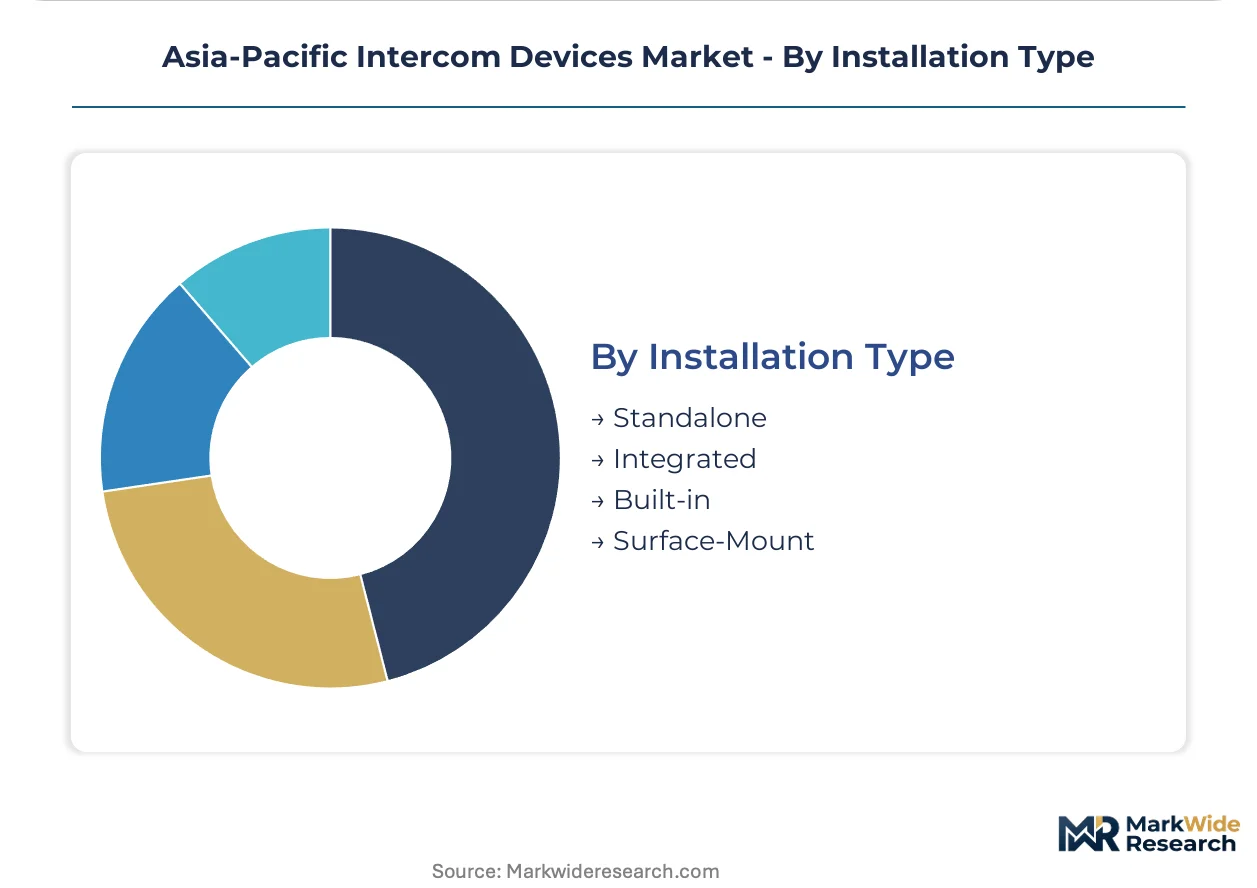
Integrated installations lead project value, with built-in variants expanding most quickly in premium residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT cybersecurity mandates propel IP intercom deployment at scale, while India's BIS certification delays create protected niches for compliant suppliers. Divergent regulatory timelines fragment procurement patterns across the region.
China
Tier-one municipal housing projects in Shanghai and Shenzhen specify firmware-hardened video entry systems as standard. MIIT network equipment cybersecurity review filters mid-tier hardware vendors from government tenders. Pearl River Delta manufacturers accelerate edge AI integration for facial recognition deployments.
India
Metropolitan corridors in Bengaluru and Mumbai drive cloud-connected video verification in mid-tier residential developments. BIS electromagnetic compatibility testing creates six-to-nine month approval delays for imported electronics. Government and institutional tenders favor certified domestic suppliers.
Japan
Aging condominium stock in Osaka and Tokyo sustains twisted-pair copper retrofit demand alongside new JIS-standardized automation interfaces. METI interoperability mandates reduce vendor lock-in across residential automation ecosystems. Kansai developers pilot ten-year service contracts transferring obsolescence risk to vendors.
Australia
Established urban centers in Melbourne and Brisbane delay full IP transition due to legacy infrastructure constraints. Commercial towers in Sydney adopt cloud-managed platforms with mobile credentialing. Fiber penetration gaps sustain analog replacement cycles in older residential stock.
Southeast Asia
Greenfield residential complexes in Vietnam and Indonesia deploy native IP architectures without legacy retrofit burdens. Wireless RF systems serve developments lacking structured cabling infrastructure. Singapore and Hong Kong commercial towers lead service contract conversion to subscription-based models.
Asia-Pacific Intercom Devices Market Competitive Environment
Top-tier vendors anchor integrated building security ecosystems, while mid-tier specialists compete on certification compliance and regional channel depth. Platform players bundle intercom modules with broader surveillance and access control portfolios. Component suppliers and pure-play intercom manufacturers represent distinct strategic archetypes. Dominant competitive moves include cloud-managed service layering and firmware hardening for cybersecurity certification.
Within the integrated platform tier, Hangzhou Hikvision Digital Technology Co. Ltd. and Dahua Technology Co. Ltd. exemplify Chinese vendors leveraging video surveillance ecosystems to bundle AI-enabled analytics with recurring service fees. Aiphone Corporation occupies a position representing stringent Japanese manufacturing standards and premium channel partnerships across East Asia. These three anchors illustrate how geographic origin and corporate structure correlate with competitive positioning archetypes in this market.
| Leading Market Players |
|---|
| Commax Co. Ltd. |
| Dahua Technology Co. Ltd. |
| Aiphone Corporation |
| Fermax Electronica S.A.U. |
| TOA Corporation |
| Panasonic Corporation |
| Hangzhou Hikvision Digital Technology Co. Ltd. |
| Legrand SA |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
CMOS image sensor and SoC procurement costs cascade through three distinct pricing tiers, with firmware-hardened video intercom systems commanding premiums under China's MIIT cybersecurity mandates while analog replacement units compete on component cost alone.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for wireless RF intercom modules, compressing margins for legacy wired manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified edge AI systems from JIS-standardized interoperability modules and basic audio terminals. Price differentiation hinges on cybersecurity certification tier and after-sales service bundling. Cost compression in mid-tier video intercoms is intensifying because semiconductor input volatility persists. Government and institutional tenders across India exhibit highest price sensitivity, while Singapore commercial towers show lowest sensitivity due to ten-year service contract preferences.
Supply Chain Analysis
Image sensor supply rests on Japanese and South Korean specialty semiconductor foundries, with Power-over-Ethernet controller ICs drawing from Taiwan and mainland China packaging houses. Raw material dependencies span CMOS wafers, copper twisted-pair cabling, and RF antenna substrates. Single-source vulnerability concentrates in edge AI inference chipsets where NVIDIA and Qualcomm architectures dominate. Distribution runs through building automation integrators in tier-one Chinese cities, electrical wholesalers across India's metropolitan corridors, and direct OEM relationships with Japanese condominium developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in cloud-managed service layering, where recurring revenue streams offset hardware commoditization pressure from IP-to-analog migration.
For Market Incumbents: Deploy firmware hardening capabilities as a defensive moat against mid-tier vendors lacking MIIT cybersecurity engineering depth. Deepen backward integration into edge AI chip design to reduce Qualcomm and NVIDIA dependency. Control channel relationships with Japanese METI-standardized automation integrators to lock out emerging platform competitors. Counter threat from Hangzhou Hikvision and Dahua Technology's bundled surveillance-intercom ecosystems through certification exclusivity in Indian BIS-mandated tenders. For New Entrants and Emerging Players: Native IP architecture without legacy retrofit burdens offers the clearest technology-first wedge in Vietnam and Indonesian greenfield residential complexes. Target wireless RF intercom deployments where structured cabling infrastructure remains absent. Pursue cloud-managed mobile app integration as primary go-to-market angle, bypassing hardware margin compression entirely through subscription revenue models. Avoid China's tier-one city tender markets where platform vendor concentration blocks access. For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification delays and MIIT cybersecurity mandates filter non-compliant suppliers from government procurement pools. Long-term viability favors vendors with integrated building security ecosystems and captive cloud service platforms over pure-play hardware manufacturers. Acquisition target archetype: mid-tier intercom specialists with established Indian certification pathways and Southeast Asian channel presence. Watch MIIT enforcement intensity as inflection indicator for Chinese market access barriers tightening further.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Managed Service Layering | Transforms hardware capex into recurring SaaS revenue across Singapore and Hong Kong commercial towers. |
| MIIT Cybersecurity Certification Investment | Creates protected market access in Chinese government tenders while filtering mid-tier competitors. |
| Edge AI Inference Integration | Enables facial recognition deployment in Shanghai and Shenzhen without cloud latency dependencies. |
| JIS Standardization Compliance | Reduces vendor lock-in across Japanese residential automation ecosystems, expanding addressable integrator base. |
| Southeast Asian Channel Expansion | Captures greenfield IP-native deployment in Vietnam and Indonesia without legacy retrofit competition. |
Study Parameters
Coverage spans China, India, Japan, Australia, and Southeast Asia, with primary inputs from each market cluster combined with secondary validation. Primary interviews engaged building automation integrators, residential property developers, electrical procurement officers at commercial tower operators, and cybersecurity compliance consultants. Secondary sources included MIIT equipment certification databases, BIS electromagnetic compatibility filings, METI JIS standard publications, and customs trade records for intercom device imports. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts.
Rate-of-change decomposition anchored volume projections to fiber broadband penetration curves, smart city infrastructure mandates, and residential construction permit flows across the analysis window. Segmentation dimensions modeled encompass product type, end-use sector, technology architecture, and installation category, with additional granularity on certification tier and service contract attachment rates. CAGRs derived from fitted adoption curves incorporating infrastructure readiness thresholds and regulatory enforcement timelines. Industry-specific inputs included MIIT cybersecurity review approval velocities and BIS testing queue durations.
The model holds under stable regulatory enforcement and infrastructure investment continuity; deviation in semiconductor supply shocks or cybersecurity mandate acceleration would shift trajectory. Forecasts reflect documented assumptions on technology substitution rates and certification pathway efficiency. A small set of triggers warrants ongoing watch: MIIT enforcement intensity, India's BIS backlog fluctuations, and fiber rollout pace in Indonesian and Vietnamese metropolitan corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart-Connected Power Plug Socket Market
Others
Global Cosmetovigilance Market
Others
Nyerereite Market
Others
Magnesite Market
Others
Global Augmented Reality in Retail Market
Others
Exosome Technologies Market
Others
North America Flexographic Printing Market
Others
Asia-Pacific Legal Services Market
Others
Industrial Gauges Market
Others
Asia Pacific Contract Packaging Market
Others
China Packaging Primers Market
Others
Gas Holders Market
Others
Europe Aircraft Lighting Systems Market
Others
Global Hardware Acceleration Market
Others
Smart Home Controller Market
Others
Cloud Gaming Baas Market