
 Football Market | 2026-2036
Football Market Size, Share, and Industry Trends Forecast 2026-2036
Football Market Intelligence
Broadcast and streaming distribution is fragmenting as leagues negotiate direct-to-consumer platforms alongside traditional rights holders. FC Barcelona leverages its in-house production studio to control content distribution across digital channels. Real Madrid CF anchors its revenue base through premium subscription tiers on its streaming service. Manchester City FC competes by integrating data analytics into fan engagement tools that sustain viewing loyalty.
Football encompasses the organized sport, its equipment, and commercial services governed by standardized rules, with match balls regulated to specific circumference, weight, and pressure tolerances set by FIFA and national federations. The sport serves as both mass entertainment and structured competition infrastructure across amateur and professional tiers. Apparel and footwear command the deepest margin pools among product segments due to brand premiums and kit refresh cycles. Event management within service types attracts escalating investment as clubs seek to monetize matchday experiences beyond ticket sales. Online retailers are displacing sporting goods stores as the primary channel for fan merchandise, though wholesale distributors still dominate institutional procurement for schools and amateur leagues.
FIFA, national federation standards, and EU Green Deal stadium requirements collectively shape facility investment and product compliance across major markets. The EU Green Deal mandates carbon accounting for large sporting venues, altering construction materials and energy systems in new stadium builds. Stakeholders must monitor how emerging broadcast rights models and sustainability compliance costs redistribute profitability across clubs, equipment suppliers, and service providers.
Market Dynamics
Streaming fragmentation is redistributing broadcast economics as leagues bypass traditional aggregators for direct fan relationships, compressing intermediary margins while elevating content production costs for clubs.
Growth Catalysts
- EU Green Deal stadium mandates:Carbon accounting requirements for venues above 50,000 capacity are accelerating retrofit cycles and procurement of low-emission construction materials across Germany, Spain, and Italy.
- Brazilian municipal league expansion:State-level competitions in São Paulo and Minas Gerais are driving equipment turnover at volume, with youth academies requiring standardized kit refreshes every 18-24 months.
- Sensor-embedded match balls:FIFA's semi-automated offside technology is rendering traditional ball manufacturing obsolete, forcing suppliers to integrate chip fabrication capabilities.
Market Restraints
- Synthetic polymer cost volatility:Thermoplastic polyurethane feedstock prices fluctuate with crude oil indices, squeezing margin pools for football manufacturers in Asia-Pacific production zones.
- Referee certification bottlenecks:National federation training pipelines produce insufficient qualified officials for expanded league calendars, capping match volume growth in secondary tiers.
- Grass pitch maintenance labor scarcity:Specialized turf management expertise concentrates in Western Europe, limiting stadium quality standardization in emerging football markets.
Strategic Opportunities
- India's Khelo India school infrastructure:Central government allocation for synthetic pitch installation in government schools creates institutional procurement volume for mid-tier equipment suppliers.
- Biodegradable boot materials:Convergence of mycelium leather substitutes and 3D-knitted uppers offers premium positioning for brands targeting EU circular economy compliance.
- Direct-to-consumer streaming subscriptions:Club-owned platforms bypass broadcaster revenue shares, capturing full fan monetization value in Brazil and Mexico.
Industry Challenges
- Video assistant referee integration complexity:Stadiums must synchronize multiple camera angles with centralized review hubs, requiring fiber infrastructure upgrades that strain municipal permitting timelines.
- Grassroots coach credential standardization:UEFA's coaching license framework lacks equivalence recognition with CONMEBOL and AFC pathways, fragmenting talent development pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Football Market |
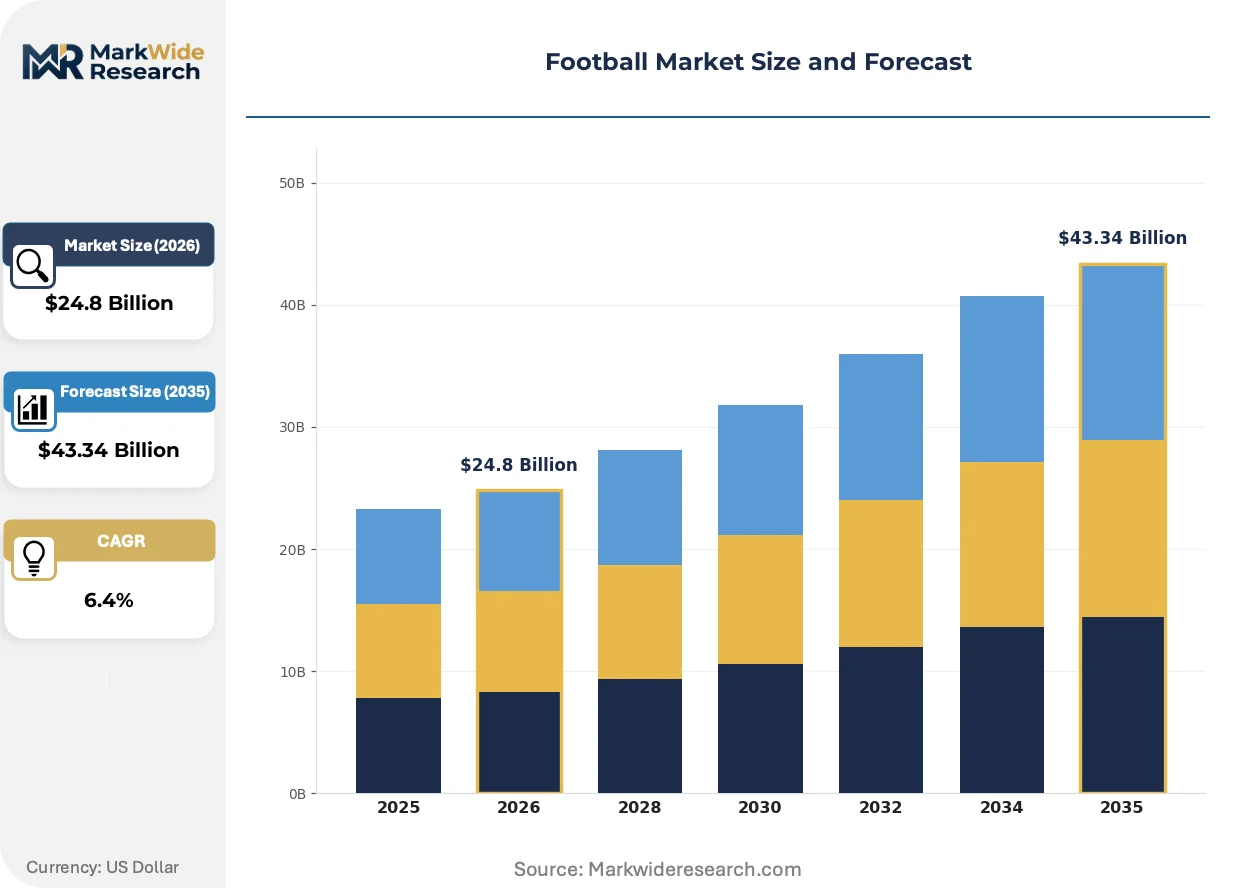
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footballs, Training Equipment, Apparel, Footwear End User: Schools, Amateur Players, Professional Teams, Fans Distribution Channel: Online Retailers, Sporting Goods Stores, Wholesale Distributors, Supermarkets Service Type: Coaching, Refereeing, Event Management, Sports Marketing |
| Companies Covered | FC Barcelona, Bayern Munich, Real Madrid CF, Arsenal FC, Liverpool FC, Manchester City FC, Manchester United FC, Chelsea FC, Paris Saint-Germain FC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Football Market Strategic Shifts & Innovations
Digital twin stadium modeling is compressing construction timelines and operational commissioning phases, while sustainability mandates are rewriting material specifications across the equipment supply chain.
Semi-automated offside detection systems are rendering obsolete the traditional linesman role in elite competitions. Bundesliga and Serie A clubs adopted the technology for the 2024-25 season. The shift is compressing staffing models while elevating capital requirements for camera infrastructure.
REACH chemical restrictions on per- and polyfluoroalkyl substances are eliminating water-repellent treatments from synthetic pitch infill. Manufacturers in the Netherlands and Belgium are pivoting to cork-rubber hybrid alternatives. The transition elevates raw material costs for municipal procurement in Flanders and North Rhine-Westphalia.
Fan merchandise purchasing has migrated decisively toward mobile-first marketplaces operated by clubs and leagues. Sporting goods retailers in France and England are ceding volume to authenticated resale platforms. Brazil and Argentina exhibit the sharpest channel displacement, where informal street commerce previously dominated kit distribution.
Football Market Segmentation
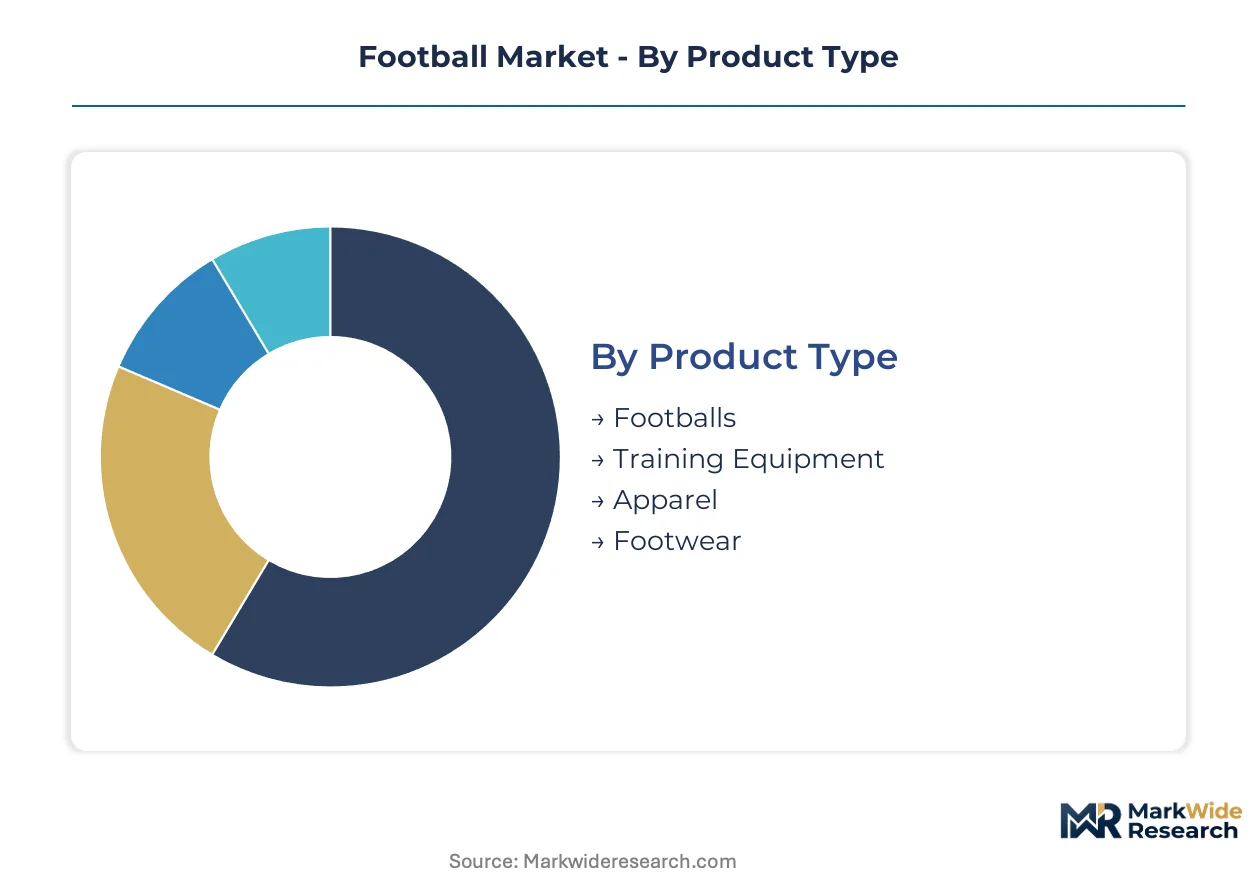
Segmentation in football markets reveals how procurement authority, consumption frequency, and channel access fragment revenue pools across equipment, services, and media rights. Understanding these fault lines exposes where margin capture concentrates and where supplier consolidation pressures build fastest.
Product Type:
Cost tier determines margin architecture across football's physical goods, with premium positioning commanding disproportionate returns relative to manufacturing input costs.
- Footballs:Match-grade balls integrate sensor arrays for semi-automated offside technology compliance, elevating unit costs while rendering basic construction obsolete. FIFA's chip fabrication mandates are forcing supplier capability upgrades in Pakistan and Thailand production zones.
- Footwear:Biodegradable mycelium leather and 3D-knitted uppers are capturing EU Green Deal positioning premiums, with kit refresh cycles every 18-24 months sustaining replacement demand in Brazilian youth academies.
- Apparel:Licensed replica kits generate recurring revenue through seasonal design rotations.
- Training Equipment:Cones, goals, and resistance gear serve institutional procurement at thinner margins.
Footwear holds installed capacity. Footballs are rotating up the share rankings.
End User:
Application context shapes specification requirements and purchasing authority, from municipal procurement committees to individual discretionary spending.
- Professional Teams:Elite clubs demand FIFA-certified equipment with embedded tracking technology, negotiating direct supplier relationships that bypass wholesale markups. Real Madrid CF and Manchester City FC anchor volume through centralized kit procurement.
- Schools:India's Khelo India program is driving synthetic pitch installation tenders across government institutions, creating institutional volume for mid-tier equipment suppliers with BIS certification compliance.
- Amateur Players:Recreational demand concentrates in weekend leagues with lower specification tolerance.
- Fans:Merchandise purchasing has migrated decisively to mobile-first club marketplaces.
Professional Teams command specification authority. Schools are climbing the fastest as a procurement volume source.
Distribution Channel:
Customer type and purchase urgency dictate channel selection, with digital migration accelerating where authentication and convenience converge.
- Online Retailers:Club-operated platforms and authenticated resale marketplaces are displacing traditional sporting goods retailers in France and England, with Brazil and Argentina exhibiting the sharpest channel displacement from informal street commerce.
- Wholesale Distributors:Institutional procurement for schools and amateur leagues still flows through established distributor networks with credit terms and bulk fulfillment capabilities.
- Sporting Goods Stores:Foot traffic-dependent retailers are ceding volume to digital channels.
- Supermarkets:Mass-market entry-level equipment serves impulse and gift purchasing occasions.
Wholesale Distributors hold installed capacity. Online Retailers are gaining share fastest.
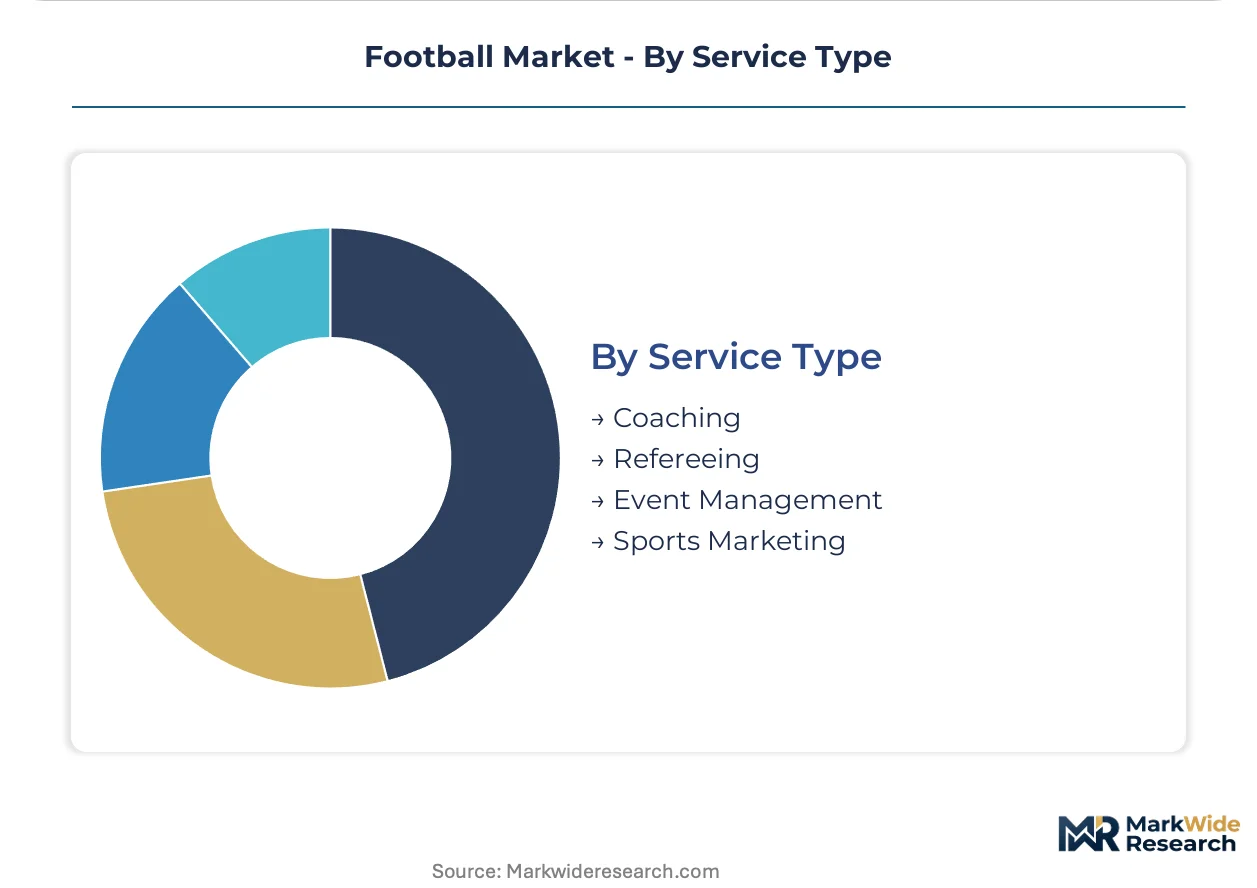
Service Type:
Margin maturity varies across intangible offerings, with technology integration elevating capital requirements in historically labor-intensive segments.
- Event Management:Stadium experience monetization beyond ticket sales is attracting escalating investment from Bundesliga and Serie A clubs, with digital twin modeling compressing construction timelines for venue upgrades.
- Coaching:UEFA's license framework lacks equivalence recognition with CONMEBOL and AFC pathways, fragmenting talent development pipelines and creating credential arbitrage opportunities.
- Refereeing:Certification bottlenecks constrain match volume growth in secondary league tiers.
- Sports Marketing:Data analytics integration into fan engagement tools is sustaining viewing loyalty for streaming subscription retention.
Event Management holds installed capacity. Coaching is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European clubs extract premium pricing from broadcast rights while Brazilian municipalities drive volume procurement at compressed margins. This asymmetry shapes where equipment suppliers concentrate manufacturing versus where they chase margin expansion.
Brazil
São Paulo and Minas Gerais state leagues drive equipment turnover through youth academy kit refreshes every 18-24 months. ANVISA regulates synthetic pitch materials for municipal installations. Suppliers cluster in São Paulo's industrial belt to serve institutional procurement committees with BIS-equivalent certification compliance.
Germany
Bundesliga clubs anchor demand for FIFA-certified sensor-embedded match balls and semi-automated offside infrastructure. EU Green Deal mandates carbon accounting for venues above 50,000 capacity, accelerating retrofit cycles in Munich and Dortmund stadiums. KBA-aligned construction standards reshape procurement of low-emission materials across North Rhine-Westphalia.
India
Khelo India program allocations for synthetic pitch installation in government schools create institutional volume for mid-tier equipment suppliers. BIS certification requirements govern football and footwear procurement for educational institutions. Manufacturing concentrates in Jalandhar and Meerut sports goods clusters serving northern state tenders.
United States
MLS expansion franchises and collegiate athletic programs sustain demand for training equipment and field infrastructure. NCAA equipment standards and state-level procurement rules shape supplier qualification requirements. Synthetic turf installation concentrates in Texas and Florida metropolitan markets with year-round playable conditions.
Spain
La Liga clubs leverage in-house production studios for direct-to-consumer streaming, compressing traditional broadcaster intermediary margins. EU Green Deal stadium requirements apply to Camp Nou renovations and Madrid venue upgrades. Barcelona and Madrid anchor supplier relationships for premium-tier kit and equipment procurement.
Football Market Key Industry Players
Elite football clubs and specialized equipment manufacturers split the market into distinct value-capture zones. Club-owned media operations and direct streaming platforms concentrate margin in vertically integrated franchises. Three archetypes dominate: legacy European clubs with global brand licensing power, Asian production clusters serving institutional volume, and technology-integrated suppliers capturing FIFA mandate premiums. Competitive moves center on backward integration into content production and upstream control over sustainable material supply chains.
Among European football institutions, FC Barcelona, Real Madrid CF, and Manchester City FC exemplify divergent strategic positioning. FC Barcelona anchors a content-production archetype through its in-house studio controlling digital distribution. Real Madrid CF occupies a premium-subscription tier focused on direct fan monetization. Manchester City FC represents the data-analytics integration path, embedding engagement tools to sustain streaming loyalty. These three clubs illustrate how geographic origin and organizational structure shape competitive approach without requiring identical resource allocation.
| Leading Market Players |
|---|
| FC Barcelona |
| Bayern Munich |
| Real Madrid CF |
| Arsenal FC |
| Liverpool FC |
| Manchester City FC |
| Manchester United FC |
| Chelsea FC |
| Paris Saint-Germain FC |
| Others |
Cost & Logistics Intelligence
Overcapacity in Pakistan's football manufacturing belt is compressing unit economics while elevating quality differentiation premiums. Sialkot's production zones operate below optimal utilization, forcing suppliers to absorb FIFA chip-fabrication upgrade costs or exit match-grade certification tiers entirely.
Pricing Analysis
Configured-to-order pricing for sensor-embedded match balls commands spreads of 3-4x against standard training-tier products. Pricing stratifies across FIFA Pro certification tiers, volume procurement scales, and customization depth for club-specific designs. Cost compression in economy-tier synthetic balls is intensifying because thermoplastic polyurethane feedstock tracks crude oil indices. Brazilian municipal leagues exhibit highest price sensitivity, while Bundesliga clubs absorb premium positioning with minimal procurement friction.
Supply Chain Analysis
Tariff exposure between Thailand and EU member states dominates supplier location decisions for chip-integrated ball assembly. Manufacturing concentrates in Pakistan, Thailand, and China's Guangdong province, drawing from thermoplastic polyurethane, semiconductor chips, and synthetic leather inputs. Single-source vulnerability in FIFA-certified chip fabrication creates bottleneck risk for match-grade compliance. Distribution runs through wholesale distributors for institutional procurement and club-operated platforms for fan merchandise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Football's value capture is shifting toward platform economics as streaming fragmentation and direct-to-consumer subscriptions restructure fan relationships around recurring revenue rather than transactional broadcast rights.
For Market Incumbents: Entrench specification authority by capturing FIFA certification mandates for sensor-embedded equipment before chip-fabrication capabilities commoditize. Deepen backward integration into sustainable material supply chains to preempt EU Green Deal compliance cost pass-through. Defend against streaming platform disintermediation by building proprietary content production infrastructure that bypasses traditional broadcaster revenue shares.
For New Entrants and Emerging Players: Build out white-space positions in India's Khelo India institutional procurement pipeline, where BIS certification requirements create defendable qualification moats. Target biodegradable boot materials convergence in EU markets, where mycelium leather substitutes command circular economy positioning premiums. Enter through certified resale platform partnerships that authenticate against counterfeit infiltration in Brazil and Argentina.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among clubs with direct-to-consumer streaming infrastructure and premium subscription tier architectures. Long-term viability over the projection horizon favors vertically integrated franchises with content production capabilities and sustainable supply chain control. Acquisition target archetype: mid-tier equipment suppliers with FIFA chip-fabrication certification and exposure to Brazilian municipal league volume. Signal to watch: consolidation pace in Pakistan's manufacturing belt as overcapacity forces capability upgrades or exit.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chip Fabrication | FIFA's semi-automated offside mandates render traditional ball manufacturing obsolete, forcing captive sensor production. |
| Direct-to-Consumer Platform Launch | La Liga and Bundesliga clubs bypass broadcaster revenue shares, capturing full fan monetization value in Brazil and Mexico. |
| Sustainable Material Supply Chain Certification | EU Green Deal carbon accounting requirements for venues above 50,000 capacity elevate low-emission construction material premiums. |
| Synthetic Pitch Installation Tender Capture | India's Khelo India program allocates central government funding for government school infrastructure, creating institutional volume. |
| Content Production Studio Buildout | FC Barcelona's in-house studio model controls digital distribution, compressing traditional broadcaster intermediary margins. |
Research Approach
Findings reconcile primary fieldwork against secondary review of federation procurement databases, customs trade records, and stadium construction permit filings. Primary interviews engaged equipment procurement directors at Bundesliga and Serie A clubs, synthetic pitch installation contractors in São Paulo state, and BIS certification officers at Indian sports goods clusters. Secondary validation drew from FIFA equipment standards documentation, EU Green Deal regulatory texts, and ANVISA synthetic material specifications. Bottom-up demand modeling triangulated against top-down revenue estimates across product type, end user, and distribution channel segmentation.
Forecast inputs include equipment refresh cycle frequencies, streaming subscription penetration trajectories, and stadium retrofit capital allocation patterns. Segmentation dimensions modeled span product type tier, end user procurement authority, channel digital migration rates, and regional regulatory compliance clusters. CAGRs derive from volume-price elasticity analysis and capacity utilization trends across manufacturing zones. Industry-specific inputs incorporate FIFA technology mandate adoption curves and EU carbon accounting implementation timelines.
Practitioners should monitor crude oil index volatility, federation certification pipeline bottlenecks, and streaming rights model fragmentation for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
North America Stand-Up Paddleboard Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
Sports and Athletic Insoles Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Wetsuits Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Athletic Mask Market