
 Food Grade Bottles Market | 2026-2036
Food Grade Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Bottles Market Foresight
The EU Green Deal is repositioning food-grade packaging procurement across European bottling operations. Amcor plc leverages its integrated rPET supply chain to secure long-term contracts with dairy processors. Berry Global anchors North American beverage packaging through high-volume HDPE bottle production. ALPLA Group specializes in lightweight PET engineering for edible oil and condiment applications.
Food grade bottles are rigid or semi-rigid containers manufactured from virgin or recycled polymers, glass, or aluminum, engineered to meet migration limits and barrier specifications for direct food contact. These vessels prevent oxidation, moisture ingress, and microbial contamination across liquid and semi-solid food distribution. Polyethylene Terephthalate dominates beverage packaging due to clarity, recyclability, and oxygen barrier performance. High-Density Polyethylene leads dairy and condiment segments where chemical resistance and dairy fat compatibility matter. Glass retains premium positioning in sauces and edible oils where inertness and shelf aesthetics command margin premiums.
FDA migration testing protocols, EFSA food-contact material evaluations, and EU REACH substance restrictions collectively shape material selection and supplier qualification timelines. BIS certification requirements in India and China's GB standards for food-contact plastics add compliance layers for exporters serving multiple jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled-content mandates that will determine competitive positioning in procurement decisions ahead.
Market Dynamics
Recycled-content mandates from the EU Green Deal are forcing bottlers to requalify entire supply chains around rPET traceability and EFSA migration compliance, compressing supplier consolidation timelines.
Growth Catalysts
- EU Green Deal packaging rules:Mandatory recycled-content thresholds for food-contact plastics are pulling rPET capacity expansion across European dairy and beverage operations.
- Lightweight PET engineering:Downgauging technologies reduce resin consumption per unit while maintaining barrier performance for edible oil bottlers.
- Germany:The country's extended producer responsibility framework incentivizes closed-loop collection systems that feed food-grade rPET back into bottle production.
Market Restraints
- rPET feedstock scarcity:Bottle-to-bottle recycling infrastructure concentrates in Germany, France, and Italy, creating geographic supply bottlenecks for processors elsewhere.
- EFSA authorization timelines:Novel recycling process approvals for food-contact applications stretch 18-24 months, freezing capacity deployment.
- Glass substitution in premium segments:Inertness and shelf aesthetics in sauces and edible oils limit polymer penetration at the high-margin tier.
Strategic Opportunities
- India BIS certification gap:Domestic food-grade bottle capacity lags behind FSSAI-mandated packaging safety upgrades, creating import substitution potential.
- Digital watermark traceability:Integration of blockchain verification with recycling sortation systems enables premium pricing for certified circular content.
- China GB standards alignment:Dual carbon goals and SAMR food-contact rules are accelerating demand for compliant rPET in condiment and cooking oil segments.
Industry Challenges
- Migration testing capacity:FDA and EFSA protocol backlogs delay new material qualifications, extending time-to-revenue for novel barrier coatings.
- Legacy blow-molding equipment:Retrofitting lines for rPET processing requires capital outlays that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Bottles Market |
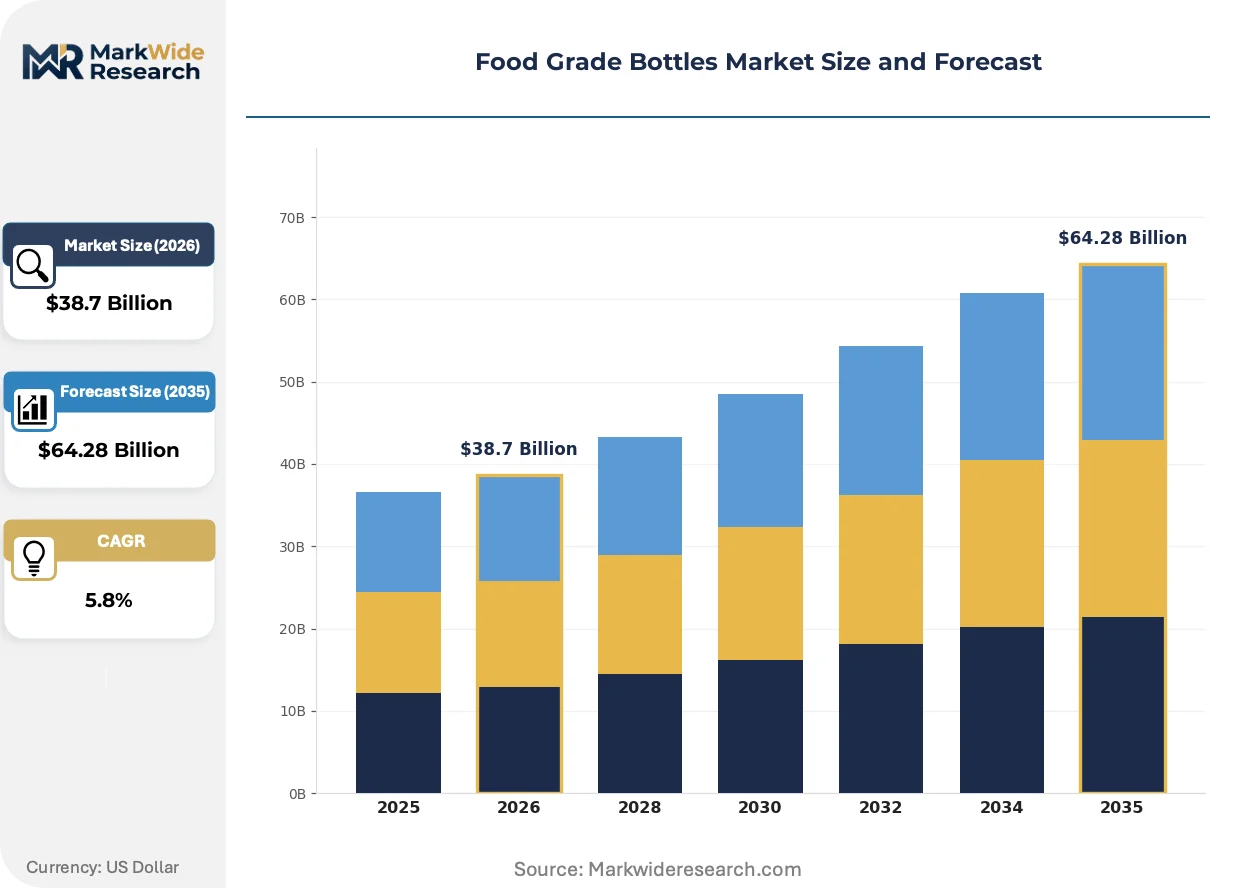
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Glass, Aluminum Application: Beverages, Dairy Products, Sauces & Condiments, Edible Oils, Personal Care Packaging Type: Screw Cap Bottles, Flip Top Bottles, Dispensing Bottles, Spray Bottles, Dropper Bottles End User: Food Processing Units, Bottling Plants, Retail Chains, Catering Services, Exporters |
| Companies Covered | Amcor plc, Berry Global, ALPLA Group, Graham Packaging Company, Plastipak Holdings, Silgan Holdings, Ardagh Group, Owens-Illinois, Gerresheimer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Bottles Market Shifts & Advancements
Material science advances and regulatory traceability requirements are converging to reshape how food-grade bottles are engineered, sourced, and recovered across liquid food supply chains.
Barrier-coated PET is modularizing the functional separation between structural and protective layers in beverage packaging. Dairy processors and juice bottlers are adopting plasma-enhanced chemical vapor deposition at pilot scale. This technology is modularizing what previously required multi-material laminates into single-substrate solutions with tunable oxygen and light protection.
REACH substance restrictions on intentionally added microplastics are tightening material disclosure requirements for European converters. ECHA evaluations now demand granular polymer additive reporting across food-contact applications. Small and mid-sized Italian and French bottlers are consolidating procurement to access centralized compliance documentation.
Direct-to-retailer bulk dispensing is compressing primary packaging intensity for condiments and cooking oils. German and Dutch supermarket chains are installing refill stations that bypass conventional bottle formats entirely. This channel shift is most visible in urban centers where packaging-as-a-service models displace single-use bottle purchases.
Food Grade Bottles Market Segmentation
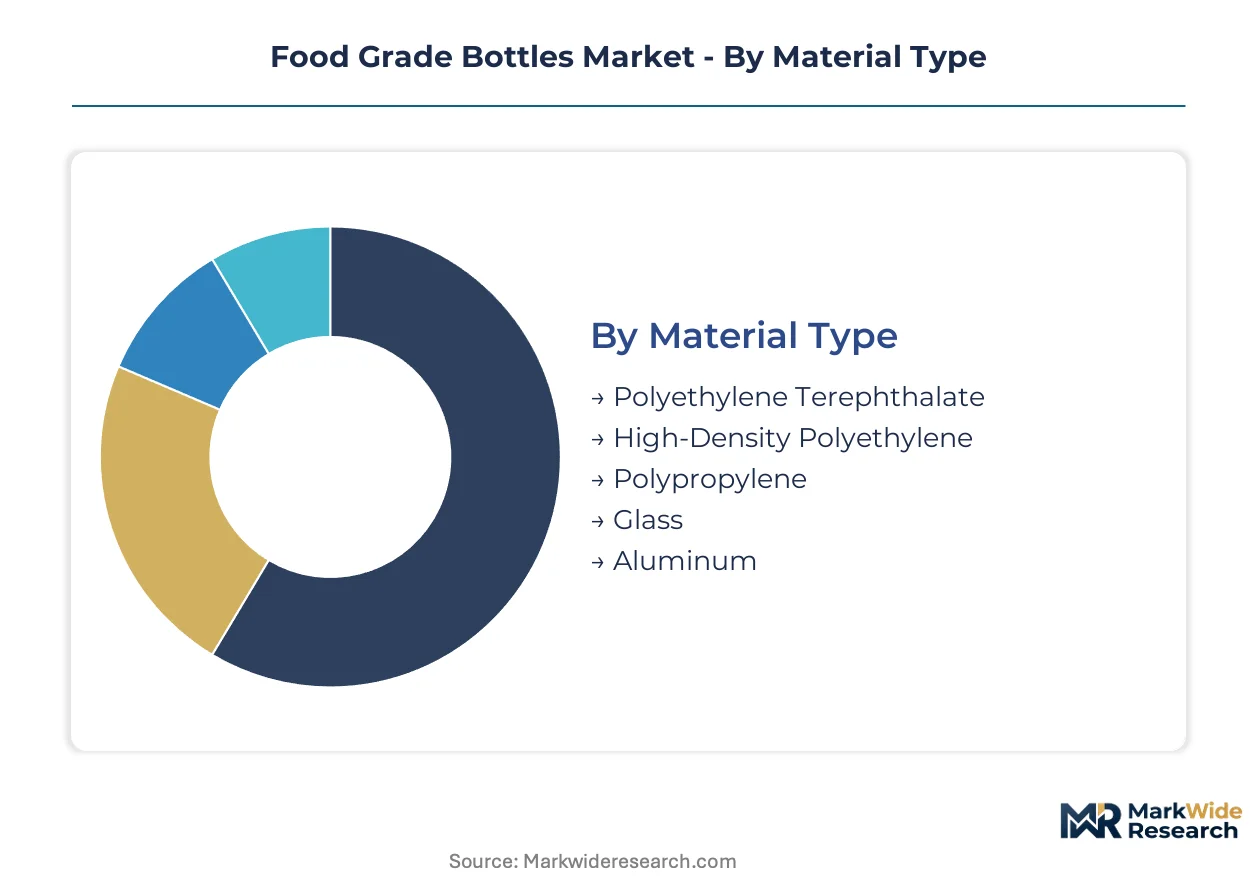
Material selection and closure engineering determine compliance pathways and capital deployment for food-grade bottle converters. Procurement patterns diverge sharply between mass-market beverage bottlers and premium edible oil exporters, reshaping how suppliers configure production footprints.
Material Type:
Capital intensity peaks with glass furnace operations and plasma-enhanced barrier coating lines, while commodity polymer extrusion requires lower upfront investment but demands continuous rPET traceability compliance.
- Polyethylene Terephthalate:Virgin and recycled PET delivers clarity, oxygen barrier performance, and EFSA-compliant migration profiles for beverage bottlers. German dairy processors are locking in long-term rPET supply contracts ahead of EU Green Deal recycled-content mandates, compressing supplier qualification windows.
- High-Density Polyethylene:HDPE resists dairy fat permeation and chemical attack from acidic condiments, making it indispensable for yogurt containers and sauce bottles. French bottling plants are retrofitting blow-molding lines for post-consumer HDPE streams to meet extended producer responsibility targets.
- Polypropylene:PP withstands hot-fill temperatures and microwave reheating cycles for ready-meal sauces. Italian converters dominate European PP bottle output for pesto and tomato-based condiments.
- Glass:Soda-lime and borosilicate formulations command premium positioning in olive oil and specialty vinegar segments where shelf aesthetics justify higher unit costs. Portuguese and Spanish glassworks feed Mediterranean edible oil exporters.
- Aluminum:Lightweight, infinitely recyclable metal bottles penetrate energy drink and premium water niches where differentiation from plastic matters. Austrian and Swiss aluminum bottle producers serve Alpine beverage brands.
Polyethylene Terephthalate absorbs the bulk of installed capacity; Aluminum is expanding most quickly.
Application:
Volume concentration and margin structure vary dramatically across liquid food categories, with beverage bottlers demanding scale economies and edible oil processors prioritizing oxygen barrier precision.
- Beverages:Carbonated soft drinks, juices, and bottled water drive PET bottle demand at multi-billion-unit scale. German retailers are imposing reverse logistics requirements that force bottlers to integrate collection infrastructure.
- Dairy Products:Milk, yogurt drinks, and cultured beverages require HDPE or barrier-coated PET with fat-compatibility certification. French dairy cooperatives are consolidating procurement around rPET-qualified suppliers.
- Sauces & Condiments:Ketchup, mayonnaise, and mustard bottles demand chemical resistance and controlled dispensing features. Italian tomato sauce bottlers dominate European condiment packaging innovation.
- Edible Oils:Olive, sunflower, and seed oil bottles prioritize oxygen exclusion and UV light protection. Spanish and Greek exporters specify dark glass or multilayer PET for premium positioning.
- Personal Care:Food-grade certification extends to cosmetic and pharmaceutical bottles sharing production lines with edible products. Swiss and German converters specialize in dual-use compliant packaging.
Beverages command the greatest production volume; Edible Oils generate the steepest margin premiums per unit.
Packaging Type:
Closure engineering determines line speed compatibility and consumer convenience positioning, with tamper-evident features now mandatory across European retail channels.
- Screw Cap Bottles:Standard threaded closures dominate beverage and oil segments where resealability matters. German machinery suppliers lead high-speed capping equipment integration.
- Flip Top Bottles:Hinged closures enable single-handed dispensing for condiments and sauces. Dutch supermarket chains are specifying flip-top formats for refill station compatibility.
- Dispensing Bottles:Pump and valve mechanisms control portion delivery for thick sauces and cooking oils. Italian designers specialize in viscous-liquid dispensing engineering.
- Spray Bottles:Aerosol and trigger systems penetrate cooking oil mist and vinegar spray niches. French culinary packaging houses dominate this precision segment.
- Dropper Bottles:Pipette closures serve premium edible oil and flavoring extract markets where dosing precision commands price premiums. Swiss precision molders anchor European dropper bottle supply.
Screw Cap Bottles retain the largest installed equipment base; Flip Top Bottles are climbing the fastest on refill-format adoption.
End User:
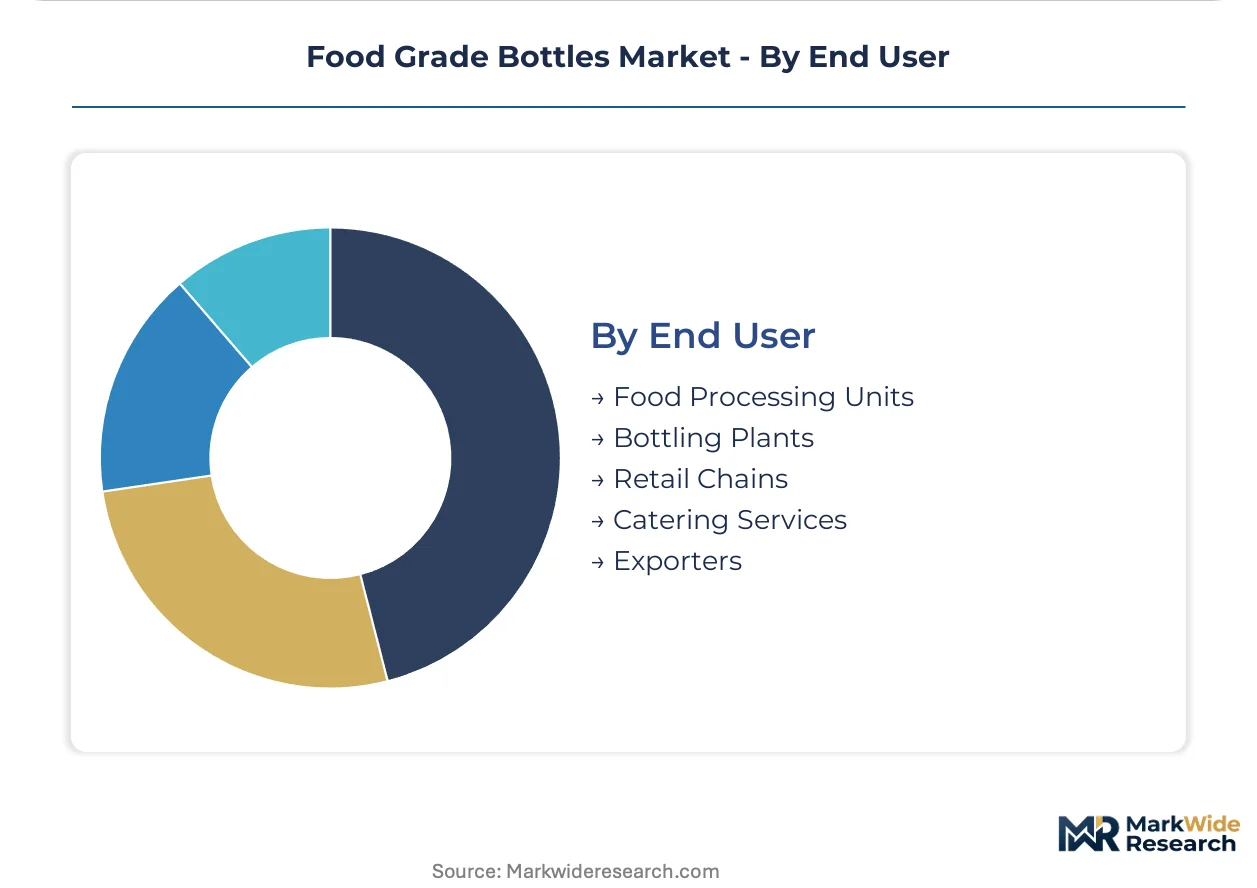
Customer scale and technical sophistication determine supplier engagement models, with multinational bottlers demanding integrated rPET supply chains and regional caterers prioritizing flexibility.
- Food Processing Units:Integrated manufacturers bottle on-site for private-label and branded distribution. German meat and dairy processors are bringing blow-molding in-house to control rPET provenance.
- Bottling Plants:Dedicated contract packagers serve multiple brand owners with rapid format changeover capability. Italian co-packers specialize in short-run premium edible oil formats.
- Retail Chains:Private-label programs at Aldi, Lidl, and Carrefour dictate specifications across European markets. French and German retailers are imposing harmonized recycled-content requirements on suppliers.
- Catering Services:Foodservice distributors demand bulk formats and dispensing compatibility for commercial kitchens. Dutch and Belgian catering suppliers lead refill-system adoption.
- Exporters:Cross-border shippers require compliance documentation for FDA, BIS, and GB standard destinations. Greek and Spanish olive oil exporters navigate the most complex multi-jurisdiction requirements.
Retail Chains concentrate procurement leverage; Exporters are gaining share fastest on premium edible oil demand from Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany, France, and Italy while consumption spreads across broader European markets. Bottlers in importing regions face extended lead times and rPET qualification bottlenecks. Regulatory fragmentation across national extended producer responsibility schemes compounds supply chain complexity.
Germany
Dairy processors in Bavaria and North Rhine-Westphalia are locking in multi-year rPET supply contracts ahead of EU Green Deal mandates. The country's extended producer responsibility framework funds closed-loop collection infrastructure that feeds bottle-to-bottle recycling plants. Berlin-based converters are retrofitting blow-molding lines to process higher recycled-content feedstocks.
France
French dairy cooperatives are consolidating procurement around EFSA-qualified rPET suppliers to meet 2025 recycled-content thresholds. ANSM enforces migration testing protocols that stretch qualification timelines for novel barrier coatings. The Lyon-Turin industrial corridor hosts specialized converters serving condiment bottlers with hot-fill compatible PET engineering.
Italy
Tomato sauce and pesto bottlers in Emilia-Romagna dominate European condiment packaging innovation with lightweight polypropylene formats. ECHA substance disclosure requirements are forcing small converters to consolidate procurement for centralized compliance documentation. Bologna-area machinery suppliers lead high-speed capping equipment integration for flip-top dispensing formats.
Spain
Olive oil exporters in Andalusia specify dark glass and multilayer PET for premium positioning in Asian markets. Spain's national packaging waste law transposes EU Green Deal requirements into regional enforcement frameworks. Seville and Málaga glassworks serve Mediterranean edible oil processors with borosilicate capacity for high-margin segments.
United States
Midwestern dairy processors are expanding HDPE bottle production to capture extended producer responsibility credits in emerging state frameworks. FDA migration testing backlogs delay new material qualifications for barrier-coated formats. Wisconsin and Illinois bottling plants are piloting digital watermark traceability systems to verify recycled-content claims.
Food Grade Bottles Market Competitive Landscape
The competitive structure tilts toward integrated polymer converters with captive rPET supply chains. Tier-one suppliers leverage EFSA pre-qualification databases to compress customer onboarding timelines. Three archetypes dominate: multinational packaging conglomerates with integrated recycling assets, regional specialists in premium glass formats, and mid-tier converters consolidating around co-packing contracts. M&A activity concentrates on rPET recycling capacity acquisitions, while strategic partnerships target digital traceability platform integration.
Among the integrated packaging conglomerates, Amcor plc and Berry Global exemplify scale-driven archetypes with backward integration into recycling infrastructure. ALPLA Group occupies a specialist position within the lightweight PET engineering tier. These three entities anchor the competitive landscape through differentiated approaches to regulatory compliance and material qualification timelines.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| ALPLA Group |
| Graham Packaging Company |
| Plastipak Holdings |
| Silgan Holdings |
| Ardagh Group |
| Owens-Illinois |
| Gerresheimer |
| Others |
Supply & Pricing Matrix
Multinational dairy processors and beverage bottlers command pricing leverage through long-term rPET offtake agreements, compressing margin structures for mid-tier converters lacking backward integration into recycling infrastructure.
Pricing Analysis
Margin tightening in virgin PET grades reflects rPET feedstock scarcity and EFSA qualification bottlenecks that stretch supplier onboarding timelines. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified rPET from virgin polymer and non-food-grade recycled streams. Cost-down pressure on standard-tier converters accelerates because German and French retailers are harmonizing recycled-content specifications. Private-label beverage bottlers exhibit highest price sensitivity; premium edible oil exporters absorb certification premiums with least resistance.
Supply Chain Analysis
rPET feedstock supply rests on German, French, and Italian bottle-to-bottle recycling clusters where collection infrastructure concentrates. Virgin PET resin draws from Belgian and Dutch petrochemical complexes; barrier coatings hinge on Austrian specialty chemical producers. Single-source vulnerability runs through EFSA-approved recycling process licensors whose authorization timelines freeze capacity deployment. Distribution runs through converter-direct relationships with dairy cooperatives and retail private-label programs, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Grade Bottles Market functions as a cost-of-compliance arena where EU Green Deal recycled-content mandates erect steep barriers to entry, rewarding incumbents with pre-qualified rPET supply chains and freezing out undercapitalized challengers.
For Market Incumbents: Hedge against feedstock scarcity by locking multi-year rPET supply contracts with German and French recycling operators before qualification windows compress. Deepen upstream control over collection infrastructure to defend margin position against emerging converters armed with digital watermark traceability platforms. For New Entrants and Emerging Players: The gap between premium EFSA-certified rPET and economy-tier virgin polymer pricing creates white-space opportunity in India BIS certification and China GB standards alignment. Target Indian dairy processors facing FSSAI-mandated packaging upgrades with import-substitution positioning. Lead with blockchain-verified circular content claims to command pricing premiums in sustainability-sensitive European retail channels. For Investors and Strategic Acquirers: The window for entry favors converters with captive rPET recycling assets and pre-qualified EFSA migration profiles. Five-to-ten year viability hinges on exposure to EU Green Deal compliance rather than commodity polymer cyclicality. Watch ECHA substance disclosure enforcement intensity as the inflection signal for consolidation acceleration among small Italian and French bottlers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Recycling | Captive feedstock supply secures margin stability under EU Green Deal mandates. |
| EFSA Pre-Qualification Investment | Compressed customer onboarding timelines accelerate revenue recognition for compliant suppliers. |
| Digital Watermark Traceability Deployment | Blockchain verification enables premium pricing for certified circular content claims. |
| Lightweight PET Engineering Scale-Up | Downgauging technologies reduce resin consumption while maintaining barrier performance specifications. |
| India BIS Certification Entry | Domestic capacity lag behind FSSAI mandates creates import substitution opportunity for qualified exporters. |
Research Methodology
Document review covered EFSA food-contact material evaluations, EU Green Deal implementation texts, and BIS certification protocols, complemented by interviews with polymer procurement directors at dairy processors, blow-molding line engineers at German converters, and sustainability officers at French retail chains. Secondary sources included customs trade data on rPET resin flows, SEC filings from integrated packaging conglomerates, and ECHA substance restriction notices. Bottom-up capacity modeling and top-down demand estimation were triangulated against migration testing protocol backlogs.
Cross-referencing historical qualification timelines with panel input from recycling plant operators shaped the analytical framework across the analysis window. Segmentation dimensions modeled included material type, application category, packaging format, end-user scale tier, and regional regulatory cluster. CAGRs were derived from installed capacity expansion schedules and recycled-content mandate trajectories. Forecast inputs incorporated EFSA authorization pipeline status and extended producer responsibility credit pricing in German state frameworks.
Inputs from EFSA pre-submission consultations and German packaging waste registry data were available through the study window; gaps in real-time rPET spot pricing and mid-tier converter financial disclosures introduce uncertainty bands around margin compression assumptions. Forecasts reflect documented assumptions on regulatory enforcement intensity and recycling technology deployment rates. A small set of triggers—ECHA microplastic restriction finalization, India BIS enforcement acceleration, and China SAMR rule alignment—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Correx Trays Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
VCI Bags Market
Packaging Containers
Non-Corrugated Boxes Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Pump Dispenser Market