
 Monobloc Aerosol Cans Market | 2026-2036
Monobloc Aerosol Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Monobloc Aerosol Cans Market Outlook
Food-grade and pharmaceutical-compatible specification tiers is unwinding across the monobloc aerosol cans landscape as buyers demand higher purity standards. Ball Corporation leverages its North American manufacturing footprint to supply beverage and personal care converters with certified aluminum monobloc capacity. TUBEX GmbH anchors European demand through precision-extruded aluminum cans engineered for high-pressure applications. Tecnocap S.p.A. competes on metal decorating technology, offering customized lithography that differentiates shelf presence for cosmetics brands.
Monobloc aerosol cans are single-piece pressure vessels, typically extruded from aluminum slugs or drawn from steel, designed to contain propellants and active formulations under internal pressures reaching bar ratings suitable for consumer and industrial dispensing. The aluminum product type dominates value contribution due to its corrosion resistance, lightweight properties, and compatibility with water-based and solvent-based formulations. Among end users, personal care applications occupy the largest volume share, though industrial cleaning products represent the fastest-expanding margin pool as manufacturers seek durable, chemically resistant packaging for solvent-dispensing systems.
EPA regulations in the United States restrict volatile organic compound emissions from aerosol products, directly shaping propellant selection and can lining requirements for domestic manufacturers. REACH and the EU F-Gas Regulation in Europe impose material disclosure obligations and limit hydrofluorocarbon propellants, compelling reformulation investments across the supply base. Stakeholders must monitor evolving propellant chemistry and lining material approvals, as regulatory divergence between jurisdictions threatens to fragment product specifications and complicate cross-border sourcing strategies.
Market Dynamics
REACH and EPA volatile organic compound restrictions are compressing propellant formulation flexibility while concentrating compliant manufacturing capacity among slug-to-can integrated suppliers.
Growth Catalysts
- Personal care volume expansion:Deodorant and dry shampoo brands in Germany and the United States are specifying aluminum monobloc formats for shelf differentiation and pressure-rated dispensing reliability.
- F-Gas Regulation phase-down:The EU framework is accelerating hydrofluorocarbon propellant replacement, driving can lining investments compatible with hydrocarbon and compressed gas alternatives.
- Industrial solvent packaging conversion:Cleaning product manufacturers are abandoning multi-component steel assemblies for corrosion-resistant aluminum monoblocs in high-pressure solvent systems.
Market Restraints
- Aluminum slug supply concentration:Premium-grade extrusion feedstock availability tightens around integrated smelter-to-rolling mill complexes in Germany and Austria.
- REACH disclosure burden:ECHA substance registration requirements extend to can interior coatings and propellant residuals, extending product development timelines.
- Steel substitution persistence:Two-piece tinplate aerosol formats retain cost advantage in economy-tier personal care segments where pressure ratings permit.
Strategic Opportunities
- Pharmaceutical-grade specification tier:Inhaler and topical spray drug delivery systems in the United States demand certified cleanroom extrusion and validated coating chemistries.
- Direct-to-contractor channel development:Industrial maintenance aerosol brands are bypassing traditional distribution through integrated e-procurement platforms serving facility management.
- EU Green Deal circularity mandates:Recycled aluminum content thresholds and extended producer responsibility frameworks reward closed-loop slug sourcing capabilities.
Industry Challenges
- Coating chemistry validation timelines:FDA and EMA pharmaceutical contact material approvals require 18-24 month stability testing, compressing product launch windows.
- Extrusion die refurbishment capacity:Precision tooling for high-pressure can geometries faces maintenance backlogs at specialized European machine shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monobloc Aerosol Cans Market |
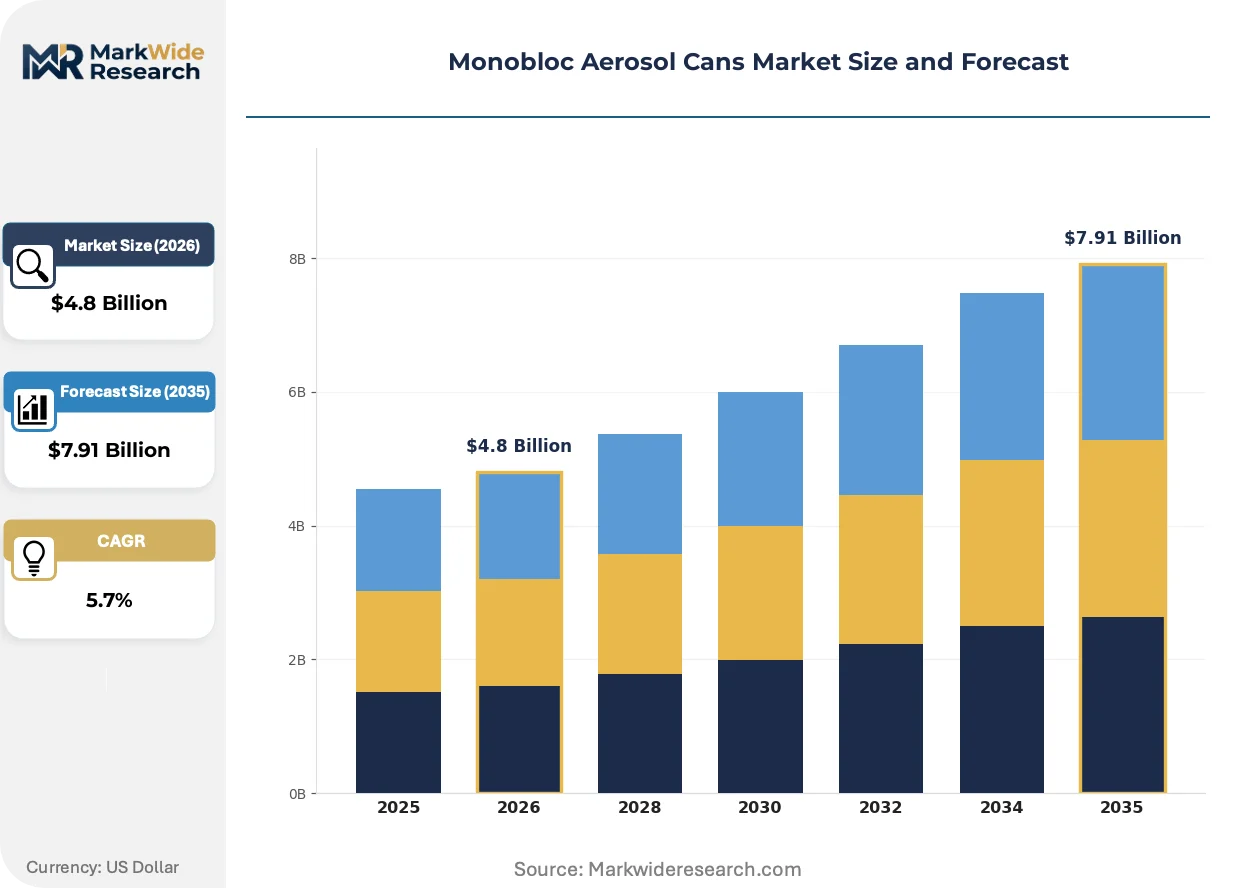
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Plastic, Composite End User: Personal Care, Household Products, Automotive, Industrial Application: Spray Paint, Air Fresheners, Deodorants, Cleaning Products Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Bharat Containers, PIONEER GROUP, Ball Corporation, TUBEX GmbH, Aryum Aerosol Cans Ltd, Tecnocap S.p.A., Euro Asia Packaging (Guangdong) Co. Ltd., ALUCON Public Co. Ltd., Moravia Cans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monobloc Aerosol Cans Market Strategic Shifts
Active and intelligent packaging integration is redefining functional expectations for aerosol dispensing systems beyond passive containment.
Polymer-lined aluminum monobloc technology is bifurcating the pharmaceutical and food-grade segments from standard personal care applications. Inhaler manufacturers in the United States and Switzerland are specifying epoxy-phenolic and nylon-based interior coatings to eliminate aluminum-ion migration into sensitive formulations. This specification tier is compressing margin pools for undifferentiated commodity can production while enabling premium positioning for validated clean-extrusion suppliers.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing coating reformulation across European production lines. ECHA substance evaluation processes have flagged specific fluoropolymer linings used in corrosion-resistant aerosol cans, compelling suppliers to qualify silicone-modified polyester and ceramic-impregnated alternatives. Personal care brands with pan-European distribution are consolidating procurement around converters with dual-approach coating capabilities to hedge regulatory uncertainty.
Brand-led sustainability scorecards are restructuring supplier selection criteria for cosmetics and personal care multinationals. Procurement teams in Germany and France are weighting recycled aluminum content, renewable energy certificates from extrusion facilities, and transport emissions in vendor qualification matrices. This behavioral shift is displacing pure unit-cost competition in favor of verified environmental product declarations and blockchain-tracked material provenance.
Monobloc Aerosol Cans Market Segmentation
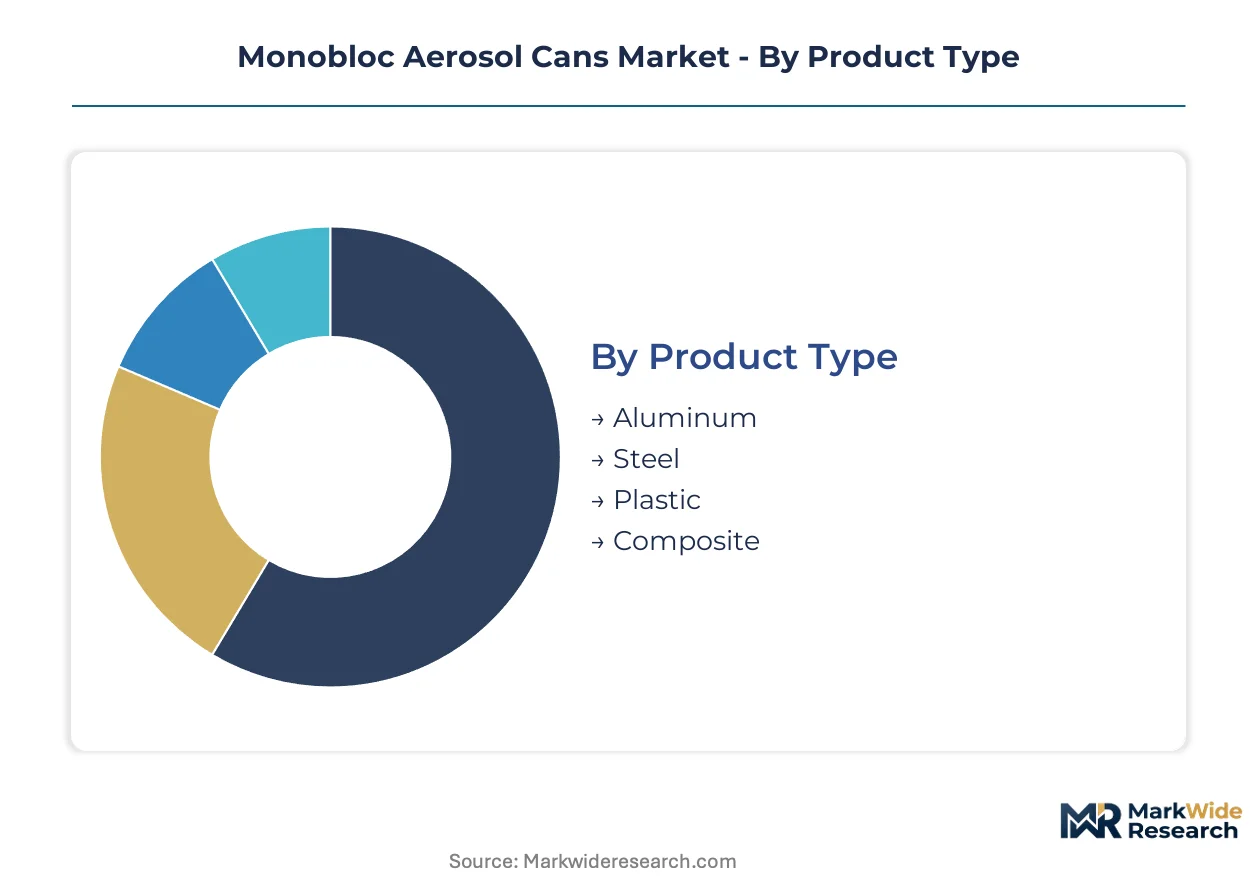
Monobloc aerosol can segmentation reveals how material specifications, end-use pressure ratings, and regulatory compliance tiers fragment procurement strategies across consumer and industrial buyers. Understanding these divides exposes where converters can escape commodity pricing through certified production capabilities.
Product Type:
Margin pools concentrate in corrosion-resistant formulations that command pharmaceutical and food-grade certification premiums.
- Aluminum:Extruded from high-purity slugs, aluminum monoblocs deliver lightweight pressure containment compatible with water-based and solvent formulations alike. REACH and EPA volatile organic compound restrictions favor aluminum's inert surface chemistry for propellant systems under reformulation.
- Steel:Drawn tinplate constructions retain cost positioning in economy-tier personal care segments where internal pressures remain moderate. German and Austrian integrated steel suppliers maintain feedstock advantages for high-volume deodorant and hair spray contracts.
- Plastic:Polymer monoblocs serve niche applications requiring transparency or squeeze-actuated dispensing below traditional aerosol pressure thresholds.
- Composite:Hybrid material systems combine barrier layers with structural substrates for specialized pharmaceutical inhaler specifications.
The dominant share belongs to aluminum, while composite formulations are closing the gap fastest through inhaler validation pipelines.
End User:
Volume concentration tracks personal care procurement, though industrial applications reward chemical resistance specifications with expanded margin structures.
- Personal Care:Deodorant, dry shampoo, and hair spray brands specify aluminum monoblocs for shelf differentiation and reliable high-pressure dispensing. German converters supply pan-European cosmetics multinationals with lithographed surface finishes.
- Industrial:Solvent-dispensing systems for maintenance and manufacturing operations demand corrosion-resistant aluminum constructions capable of withstanding aggressive chemical contact. REACH Annex XVII coating restrictions accelerate lining investments for this segment.
- Household Products:Air freshener and surface cleaner brands balance cost pressures against pressure-rated reliability for trigger and continuous-spray formats.
- Automotive:Brake cleaner, lubricant, and touch-up paint aerosols require chemical compatibility with petroleum distillates and brake fluid formulations.
Personal care commands the largest procurement volumes, yet industrial end users are expanding most quickly as maintenance aerosol brands bypass traditional distribution channels.
Application:
Specification complexity escalates with formulation sensitivity, creating tiered entry barriers between commodity and validated production tiers.
- Deodorants:High-pressure aluminum monoblocs dominate antiperspirant dispensing where propellant compatibility and actuator precision determine consumer experience. F-Gas Regulation phase-downs in Europe are forcing hydrocarbon propellant conversions requiring revised lining specifications.
- Cleaning Products:Industrial solvent aerosols for degreasing and precision cleaning demand epoxy-phenolic interior coatings to prevent aluminum-ion migration into aggressive formulations.
- Spray Paint:Automotive and decorative coatings require pressure ratings supporting atomization consistency across temperature ranges.
- Air Fresheners:Continuous-spray and metered-dose formats prioritize cost efficiency over extreme pressure ratings in household deployment.
Deodorant applications anchor procurement volumes, while cleaning products are climbing the fastest on industrial maintenance conversion trends.
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with direct relationships dominating validated pharmaceutical and industrial tiers.
- Direct Sales:Pharmaceutical inhaler manufacturers and industrial solvent brands negotiate direct converter relationships for cleanroom-certified extrusion and validated coating chemistries. FDA and EMA contact material approvals require 18-24 month stability testing that favors long-term supply partnerships.
- Wholesale:Personal care and household product brands leverage distributor networks for volume procurement across multiple SKUs and regional markets.
- Retail:Smaller cosmetics and automotive aftermarket brands source through packaging distributors offering consolidated material and decoration services.
- Online:E-procurement platforms serve facility management contractors with industrial maintenance aerosol requirements, enabling direct-to-contractor channel development.
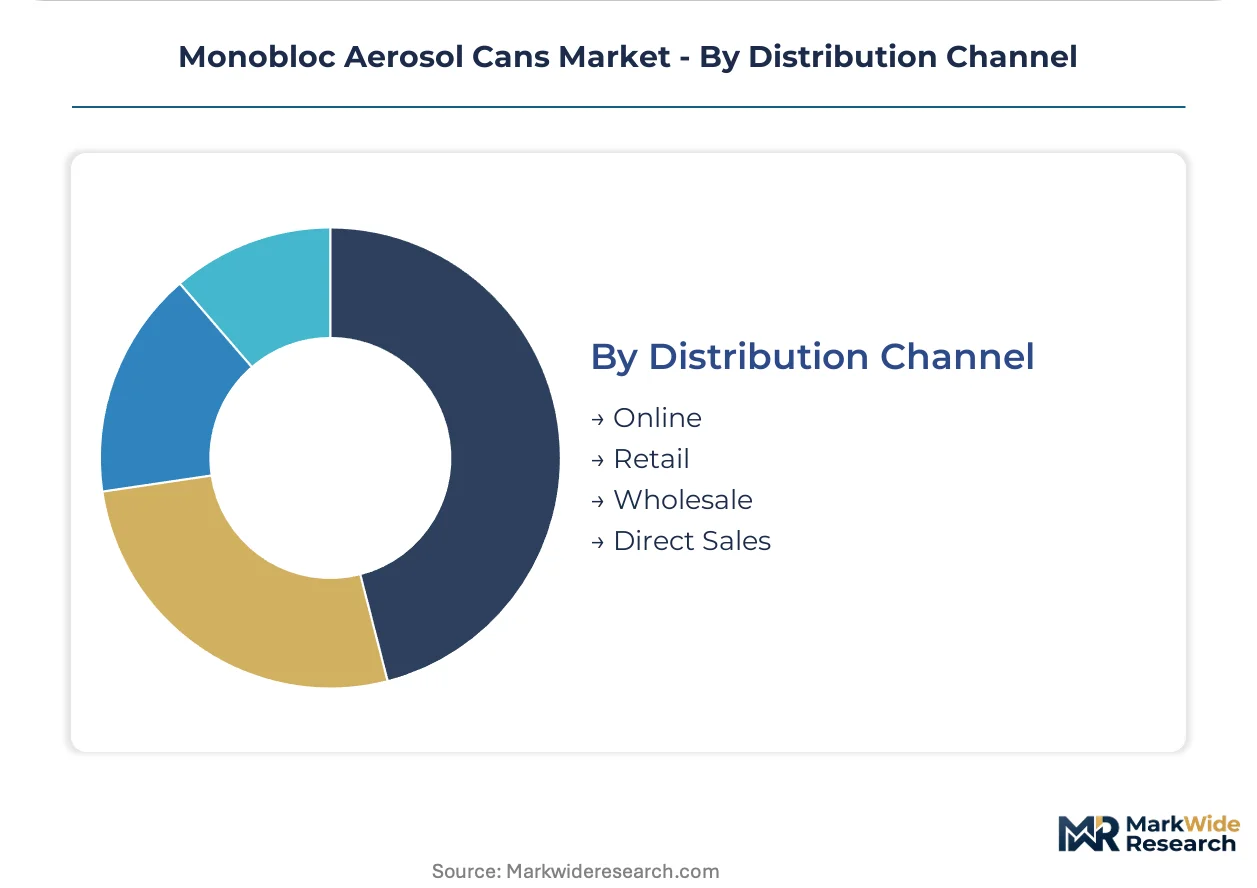
Direct sales capture the premium specification tier, while online channels are gaining share fastest through integrated e-procurement platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German extruders supply aluminum slugs to cosmetics converters across France and the United Kingdom, establishing a north-south trade corridor that dominates European procurement patterns for high-pressure personal care packaging.
Germany
Deodorant and dry shampoo brands specify precision-extruded aluminum monoblocs for shelf differentiation and actuator reliability. REACH compliance obligations and F-Gas Regulation phase-downs force continuous coating chemistry investments. TUBEX GmbH anchors production in the Rhineland-Palatinate region, supplying pan-European cosmetics multinationals with lithographed surface finishes.
United States
Pharmaceutical inhaler manufacturers demand certified cleanroom extrusion for topical spray drug delivery systems. EPA volatile organic compound restrictions compress propellant formulation flexibility and reshape can lining requirements. Ball Corporation leverages its North American manufacturing footprint to supply beverage and personal care converters with certified aluminum monobloc capacity.
France
Cosmetics procurement teams weight recycled aluminum content and renewable energy certificates in vendor qualification matrices. EU Green Deal circularity mandates reward closed-loop slug sourcing capabilities. The Île-de-France region hosts formulation laboratories that validate coating chemistries for pan-European distribution.
Switzerland
Inhaler manufacturers specify epoxy-phenolic and nylon-based interior coatings to eliminate aluminum-ion migration into sensitive formulations. Swissmedic pharmaceutical contact material approvals require extended stability testing that favors long-term supply partnerships. Basel-area precision engineering clusters support tooling maintenance for high-pressure can geometries.
China
Industrial cleaning product manufacturers convert from multi-component steel assemblies to corrosion-resistant aluminum monoblocs for solvent-dispensing systems. GB standards and evolving environmental regulations tighten material specifications for domestic and export markets. Guangdong Province hosts integrated extrusion and decorating facilities serving Asia-Pacific personal care brands.
Monobloc Aerosol Cans Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and certification depth, creating a tiered structure where scale advantages clash with agility in regulatory compliance. The vendor base separates into integrated slug-to-can operators, precision extrusion specialists, and regional decorators. Three archetypes dominate: multinational packaging conglomerates with backward integration into aluminum rolling, mid-cap European specialists with pharmaceutical validation capabilities, and Asia-Pacific fabricators serving cost-sensitive household product segments. Competitive moves concentrate on capacity expansion in regulated jurisdictions and strategic partnerships for recycled feedstock access.
Among Germany-based precision extrusion specialists, TUBEX GmbH exemplifies the pharmaceutical-grade specification tier, while Ball Corporation represents the scale-driven multinational archetype with integrated North American supply chains. Tecnocap S.p.A. occupies a position within the metal decorating specialization vector, differentiating shelf presence through customized lithography for cosmetics brands. These three anchors illustrate how competitive positioning fragments across certification depth, geographic coverage, and decoration technology rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Bharat Containers |
| PIONEER GROUP |
| Ball Corporation |
| TUBEX GmbH |
| Aryum Aerosol Cans Ltd |
| Tecnocap S.p.A. |
| Euro Asia Packaging (Guangdong) Co. Ltd. |
| ALUCON Public Co. Ltd. |
| Moravia Cans |
| Others |
Value Chain & Pricing Dynamics
Slug-to-can integration at German and Austrian rolling mill complexes compresses unit economics for high-volume personal care contracts while establishing price floors that smaller extruders cannot match. REACH disclosure burdens and pharmaceutical-grade certification requirements widen spreads between commodity and validated specification tiers.
Pricing Analysis
Standard-extrusion aluminum monoblocs compete on unit cost against legacy tinplate formats, while polymer-lined pharmaceutical grades and food-certified specifications command substantial premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, recycled content thresholds, and decoration complexity. Price differentiation stems from REACH-compliant coating validation timelines and cleanroom extrusion capabilities. Cost compression in economy-tier deodorant packaging intensifies as steel substitution persists, while industrial solvent applications show lowest price sensitivity due to chemical resistance requirements.
Supply Chain Analysis
Inventory buffers for precision extrusion dies face extended lead times at specialized European machine shops, constraining surge capacity for pharmaceutical validation pipelines. Supply concentrates in Germany, Austria, and China, with Rhineland-Palatinate and Guangdong Province hosting integrated slug-to-can operations. Raw material flows draw from primary aluminum smelters, high-purity slug rolling mills, and epoxy-phenolic coating resin suppliers. Single-source vulnerability runs through German-Austrian slug feedstock corridors. Distribution runs through direct converter relationships for pharmaceutical tiers and wholesale networks for personal care volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as pharmaceutical inhaler conversion and industrial solvent packaging migration accelerate specification-tier bifurcation beyond commodity personal care volumes.
For Market Incumbents: Compound defensive positioning through captive slug supply arrangements and pharmaceutical validation pipeline investments. Ball Corporation and TUBEX GmbH exemplify scale-driven and precision-specialist archetypes respectively. Threats emerge from Asia-Pacific cost competitors in household product tiers and REACH-driven coating reformulation costs. Prioritize backward integration into recycled aluminum sourcing to meet EU Green Deal circularity mandates. For New Entrants and Emerging Players: Anchor in industrial e-procurement channel development for maintenance aerosol brands bypassing traditional distribution. White-space targets include pharmaceutical-grade specification tiers in North American inhaler markets and solvent-resistant linings for precision cleaning applications. Most penetrable entry point: direct-to-contractor platforms serving facility management procurement. Go-to-market angle: validated coating chemistries with accelerated stability testing partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade extrusion specialists with FDA and EMA contact material approvals. Long-term viability favors integrated slug-to-can operators with closed-loop recycled feedstock capabilities over undifferentiated decorators. Acquisition target archetype: mid-cap European precision extruders with cleanroom certification and underutilized die capacity. Signal to watch: REACH Annex XVII fluoropolymer restriction enforcement accelerating coating chemistry replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Aluminum Sourcing | EU Green Deal thresholds reward closed-loop slug capabilities at German and Austrian rolling complexes. |
| Pharmaceutical-Grade Coating Validation Investment | FDA and Swissmedic approval pipelines enable premium positioning for inhaler and topical spray delivery. |
| Direct-to-Contractor Channel Development | Industrial maintenance aerosol brands bypass traditional distribution through integrated e-procurement platforms. |
| Precision Die Capacity Expansion | Extended refurbishment backlogs at European machine shops constrain surge capacity for high-pressure geometries. |
| REACH-Compliant Coating Reformulation | ECHA fluoropolymer restrictions force qualification of silicone-modified polyester and ceramic-impregnated alternatives. |
Study Parameters
A standing panel of aerosol packaging procurement managers, pharmaceutical formulation scientists, industrial maintenance product managers, and coating chemistry R&D directors provided ongoing calibration across primary interview rounds. Secondary validation drew from ECHA substance registration databases, EPA volatile organic compound rulemakings, EU F-Gas Regulation implementation reports, and aluminum trade association production statistics. Bottom-up volume modeling triangulated against top-down market sizing from customs records and extrusion capacity disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across material type, end-use industry, pressure rating tier, coating specification grade, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to disclosed capacity expansions and propellant reformulation timelines. Industry-specific inputs included REACH Annex XVII restriction schedules and pharmaceutical contact material approval pipelines.
Decision-makers should treat outputs as directional under assumptions of continued F-Gas Regulation phase-down enforcement and stable aluminum slug supply from integrated European rolling mills; material deviation in propellant chemistry adoption or trade policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Logistics Packaging Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Bottles Market
Packaging Containers
Airless Bottles Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Middle-East and Africa Paper Cups Market