
 Chalk Boxes Market | 2026-2036
Chalk Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Chalk Boxes Market Insights
EU REACH restrictions on heavy metals in consumer products is realigning formulation requirements across the chalk boxes supply chain. Tajima Industries Ltd leverages precision manufacturing expertise to sustain premium positioning in professional-grade layout tools. Stanley Black & Decker Inc anchors broad distribution through retail and industrial channels. Irwin Tools specializes in trade-focused product lines that dominate contractor segments in North America.
Chalk boxes are mechanical or manual devices that hold powdered chalk and dispense it through a string line to create straight, temporary markings on surfaces such as concrete, wood, or metal, typically featuring refillable reservoirs and retractable lines measured in standard lengths. The devices serve carpenters, masons, and construction crews requiring accurate layout guidance before cutting or fastening operations. Standard chalk formulations occupy the largest volume share due to universal compatibility with legacy equipment and lower per-unit pricing, while dustless chalk variants are gaining fastest adoption as OSHA silica exposure guidelines tighten across jobsites. Eco-friendly packaging represents an emerging margin pool as institutional buyers in education and commercial sectors mandate reduced plastic content in procurement specifications.
FDA oversight of color additives in consumer products, EPA regulations on particulate emissions in manufacturing, and OSHA workplace exposure limits for respirable crystalline silica collectively shape product composition, facility compliance costs, and end-user purchasing criteria in this market. The EU Green Deal's chemical sustainability targets are beginning to influence export-oriented suppliers even without direct jurisdiction. Stakeholders must monitor evolving particulate standards and packaging mandates to anticipate reformulation investments and certification requirements that will determine competitive access across key buyer segments.
Market Dynamics
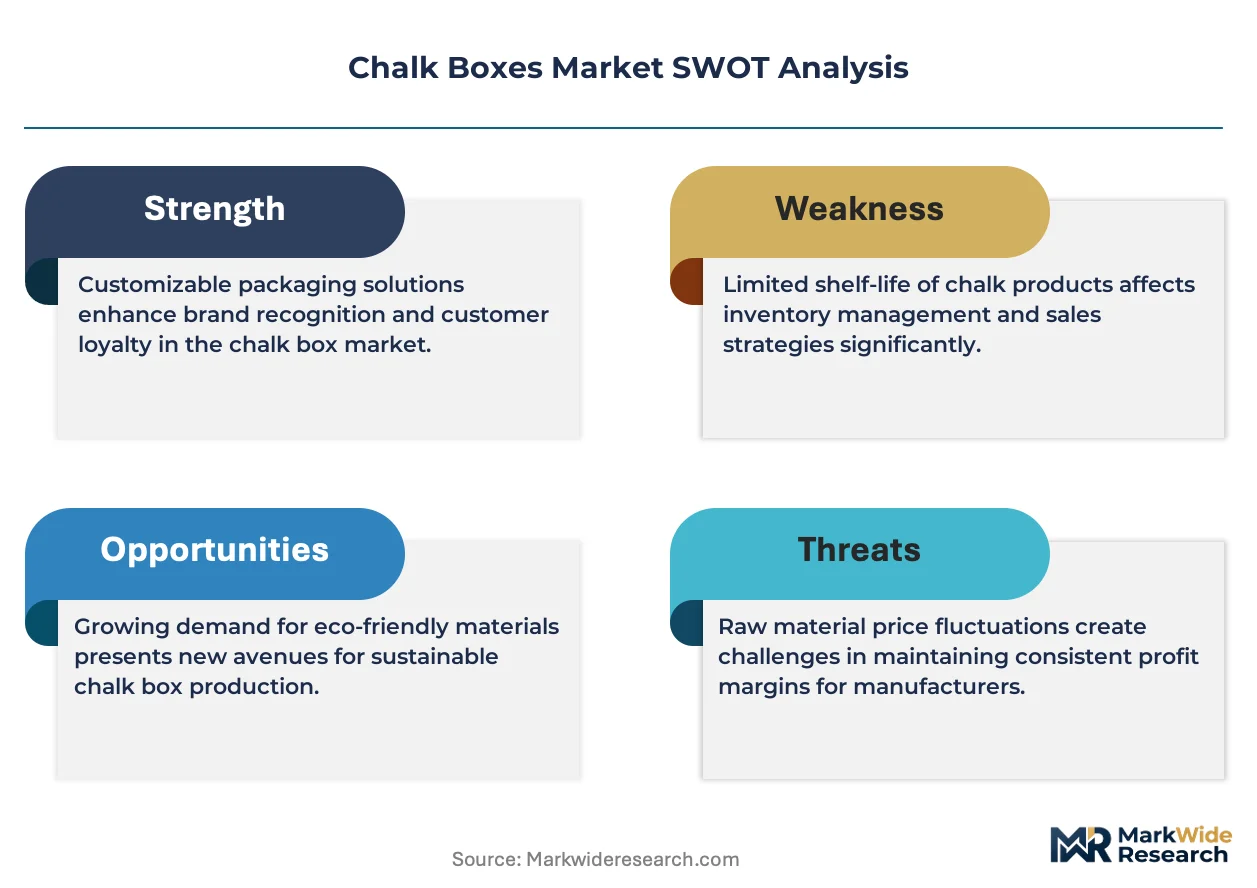
OSHA's silica exposure limits are forcing reformulation of standard chalk compositions across professional-grade product lines, compressing margins for legacy suppliers while creating entry points for dustless alternatives.
Growth Catalysts
- Infrastructure spending:Federal highway and school renovation appropriations in the United States sustain replacement cycles for layout tools among general contractors.
- REACH chemical restrictions:EU heavy metal limits are redirecting export-oriented manufacturers toward barium-free and copper-free pigment systems.
- Silica awareness:Construction trade associations in California and New York are mandating dustless chalk boxes on publicly funded projects.
Market Restraints
- Raw material concentration:Titanium dioxide and calcium carbonate supply chains concentrate in Chinese industrial clusters, exposing price volatility.
- Substitution threat:Laser layout tools and digital measuring devices are capturing precision-demanding segments in commercial construction.
- Proposition 65 friction:California's chemical labeling enforcement creates compliance costs that deter smaller manufacturers from Western US distribution.
Strategic Opportunities
- Education sector packaging mandates:K-12 procurement specifications in Texas and Florida are requiring recycled cardboard and reduced plastic content.
- Modular tool systems:Integration of chalk boxes with tape measures and levels as unified layout kits is opening premium positioning in professional channels.
- EU Green Deal alignment:Chemical sustainability targets are creating certification pathways for bio-based chalk formulations entering European markets.
Industry Challenges
- Formulation chemistry expertise:Shortage of industrial chemists familiar with particulate engineering and color-fastness testing is slowing product development cycles.
- Dual certification timelines:Simultaneous OSHA silica compliance and EU REACH registration processes extend time-to-market by 12-18 months for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chalk Boxes Market |
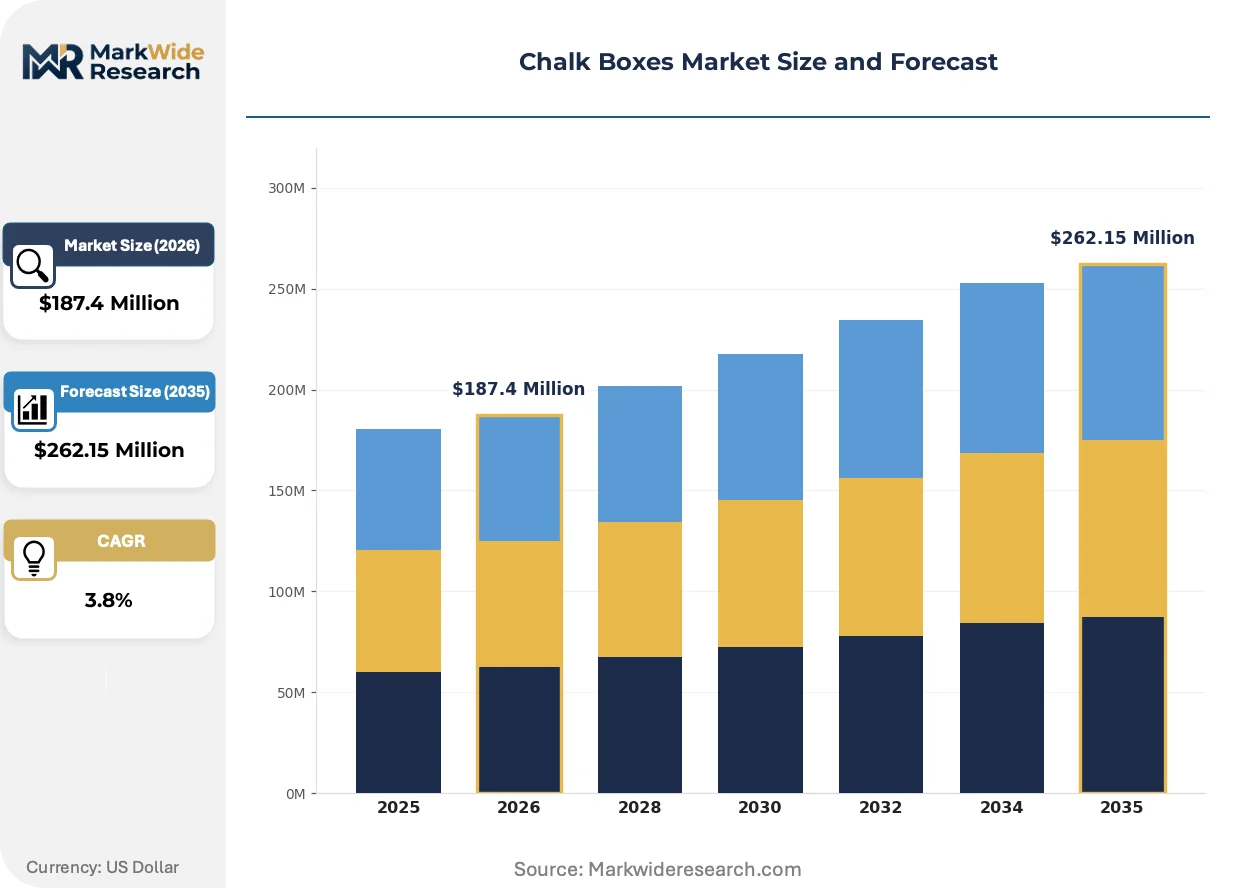
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Chalk, Colored Chalk, Chalkboard Stickers, Dustless Chalk Application: Education, Arts & Crafts, Commercial Use, Event Planning Packaging Type: Box, Bulk, Refill Packs, Eco-Friendly Packaging End User: Schools, Artists, Retailers, Event Organizers |
| Companies Covered | Apex Tool Group LLC, Stanley Black & Decker Inc, Tajima Industries Ltd, Kapro Industries Ltd, OX Group International, SNA Europe, Keson, DeWalt, Irwin Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chalk Boxes Market Trends and Innovations
Product architecture is fragmenting into specialized tiers as regulatory pressure and end-use differentiation accelerate. Manufacturers are rethinking core mechanical designs and material specifications simultaneously.
Refillable cartridge systems are modularizing the traditional chalk box architecture. Commercial contractors in the United States are adopting snap-in reservoir designs that separate the chalk chamber from the line mechanism. This modularity is compressing replacement part revenue while enabling subscription-style consumable sales.
REACH restrictions on heavy metals are redirecting pigment sourcing toward organic alternatives. German and French formulators are investing in synthetic iron oxide replacements that maintain visibility without cadmium or lead content. Professional-grade lines in Western Europe are responding fastest, with North American exporters following to maintain market access.
Institutional buyers are consolidating supplier relationships through cooperative purchasing agreements. School districts in California and Texas are bypassing traditional retail channels in favor of direct manufacturer contracts with sustainability audit requirements. This channel compression is most visible in education-sector procurement, where specification compliance now precedes price negotiation.
Chalk Boxes Market Segmentation
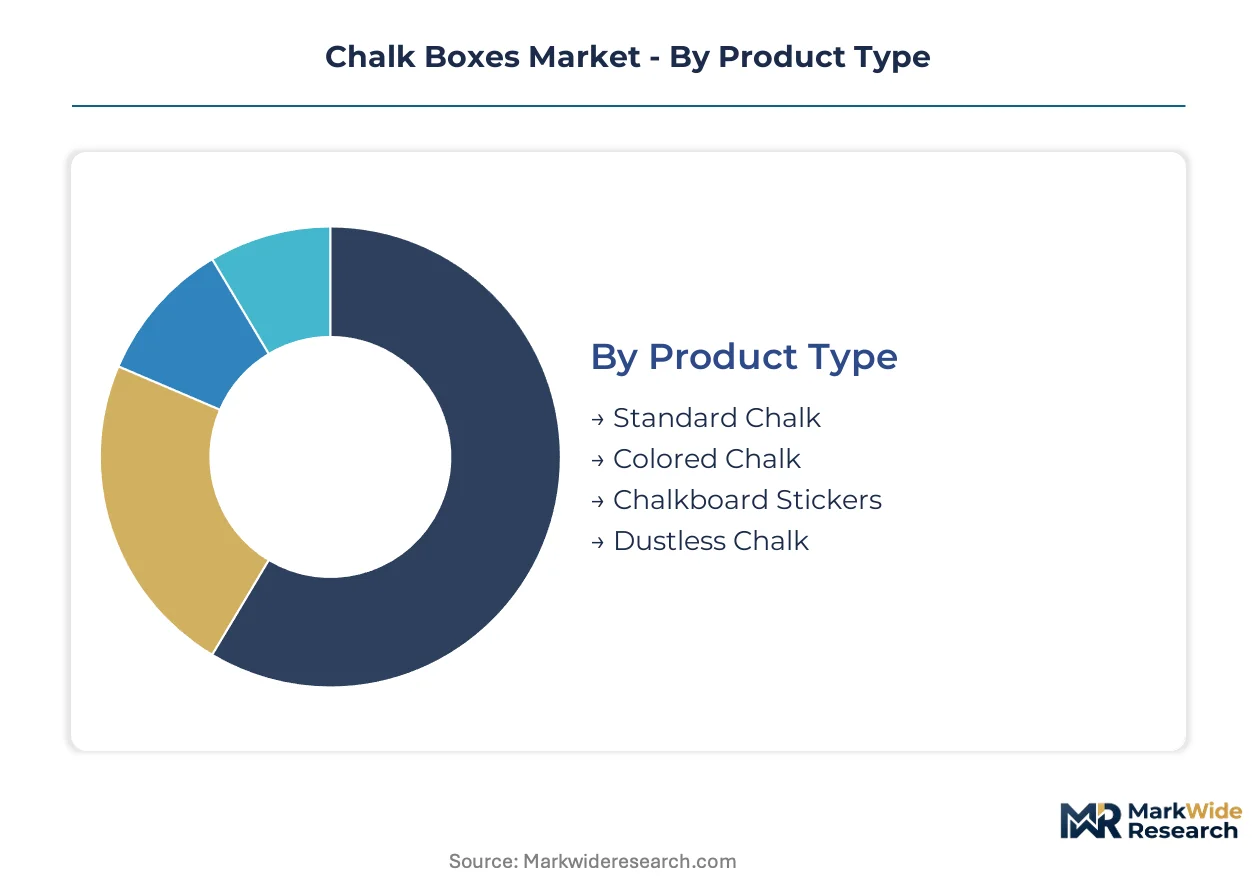
Chalk boxes fragment into distinct performance tiers as regulatory pressure and end-use specialization accelerate. Upgrade cycles vary dramatically across education, construction, and institutional procurement channels.
Product Type:
Replacement cycles diverge sharply between legacy formulations and reformulated alternatives as OSHA silica limits and EU chemical restrictions force equipment turnover.
- Standard Chalk:Calcium carbonate and gypsum-based formulations dominate contractor toolkits due to universal compatibility with existing chalk boxes. Demand concentrates among masonry crews in Texas and Florida where cost sensitivity overrides dust exposure concerns on private residential projects.
- Dustless Chalk:Engineered particulate systems bind chalk dust through polymer or oil-based carriers, reducing respirable silica below OSHA action levels. California school districts and New York public works contracts now mandate dustless systems, compressing replacement timelines for legacy equipment.
- Colored Chalk:Pigmented variants serve event planning and arts applications requiring visual differentiation on dark surfaces.
- Chalkboard Stickers:Adhesive-backed vinyl alternatives bypass traditional chalk boxes entirely in temporary signage and retail display applications.
Standard Chalk sits at the top of the volume ranking, with Dustless Chalk climbing the fastest.
Application:
Cost tier stratification separates commodity procurement from specification-driven purchasing across institutional and commercial channels.
- Education:K-12 and university procurement dominates volume through cooperative purchasing agreements. Texas and California school districts now embed sustainability audits and recycled content mandates into vendor qualification, elevating compliance costs for smaller suppliers.
- Commercial Use:Construction layout applications command premium pricing for professional-grade chalk boxes with precision line mechanisms. Infrastructure spending in the United States sustains replacement cycles among general contractors bidding federal highway and school renovation projects.
- Arts & Crafts:Hobbyist and professional artist segments prioritize color range and surface compatibility over dust suppression features.
- Event Planning:Temporary signage and decorative applications favor disposable or low-cost alternatives with minimal durability requirements.
Education captures the largest procurement volumes, while Commercial Use generates the steepest margin expansion.
Packaging Type:
Customer type dictates packaging format as institutional buyers consolidate supplier relationships and retail channels fragment.
- Refill Packs:Modular cartridge systems separate chalk reservoirs from line mechanisms, enabling subscription-style consumable sales. Commercial contractors in the United States are adopting snap-in designs that compress replacement part revenue while locking in recurring purchases.
- Eco-Friendly Packaging:Recycled cardboard and reduced-plastic specifications are becoming gatekeeping requirements in California and Texas K-12 procurement. Suppliers lacking certified sustainable packaging face automatic disqualification from cooperative purchasing agreements.
- Box:Traditional retail packaging serves hardware store and big-box distribution channels with standardized unit economics.
- Bulk:Institutional and industrial buyers procure multi-unit containers to minimize per-unit handling costs.
Refill Packs anchor professional channel revenue, with Eco-Friendly Packaging expanding most quickly in education procurement.
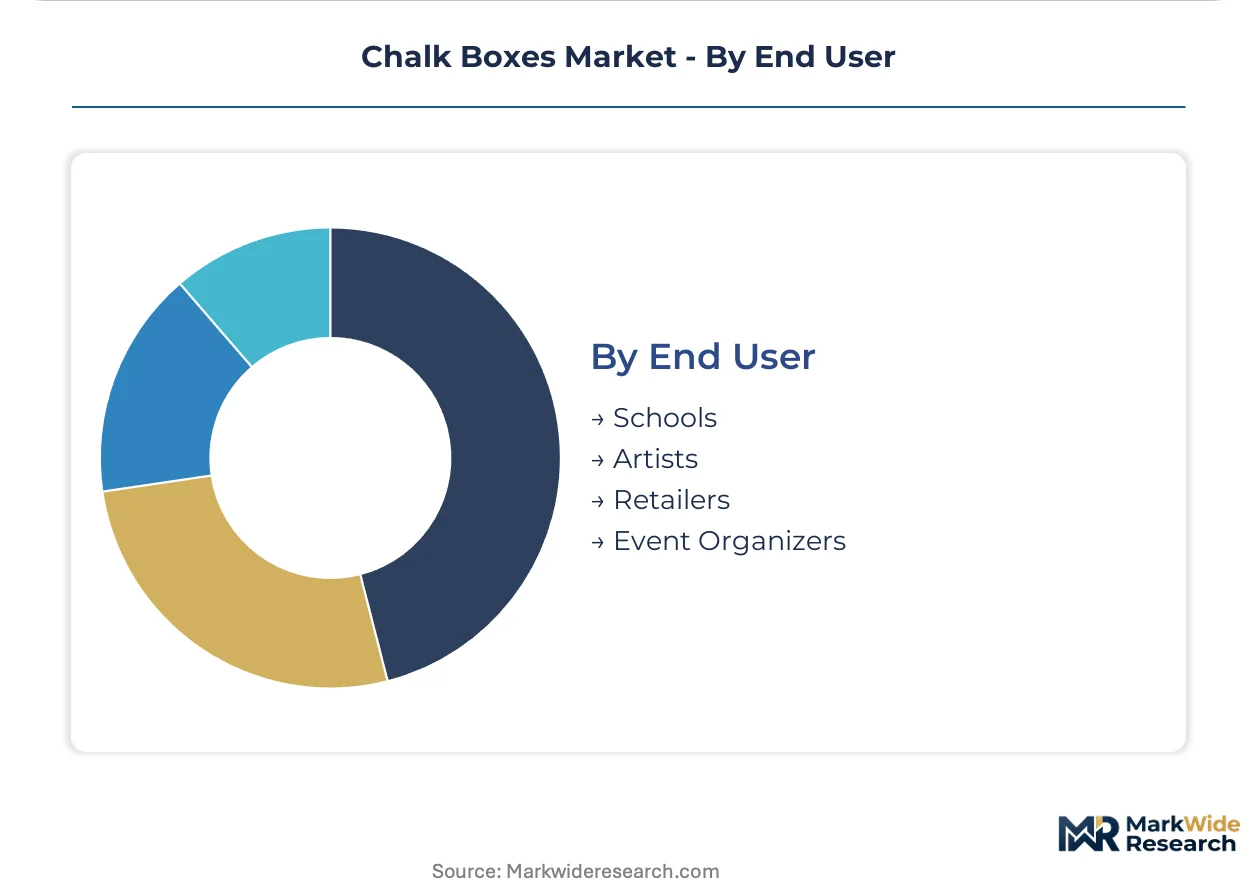
End User:
Supply concentration in pigment and calcium carbonate sourcing shapes margin pressure across divergent buyer power structures.
- Schools:Cooperative purchasing agreements in California and Texas consolidate demand through direct manufacturer contracts. Sustainability audit requirements now precede price negotiation, compressing traditional retail channel margins.
- Retailers:Hardware chains and educational supply distributors face margin compression as institutional buyers bypass traditional intermediaries.
- Artists:Individual and studio purchasers prioritize color performance and surface compatibility in lower-volume, higher-margin transactions.
- Event Organizers:Temporary application needs favor disposable economics and rapid procurement cycles over durability specifications.
Schools dominate absolute procurement volume, while Artists sustain the highest per-unit margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The chalk boxes industry traces its commercial origins to post-war American construction equipment manufacturing, with precision layout tools first scaled for mass production in the United States during the 1950s highway building era. Distribution networks later expanded across industrialized markets as standardized building practices globalized.
United States
Infrastructure appropriations and school renovation programs sustain replacement cycles among general contractors bidding federal projects. OSHA silica exposure limits are forcing reformulation of standard chalk compositions across professional-grade product lines. Manufacturing concentrates in Midwest industrial corridors serving hardware retail and direct institutional procurement channels.
Germany
REACH restrictions on heavy metals are redirecting pigment sourcing toward organic alternatives in professional-grade layout tools. ECHA registration processes for reformulated products extend certification timelines for exporters targeting EU markets. Industrial formulators in Baden-Württemberg are investing in synthetic iron oxide replacements that maintain visibility without cadmium content.
China
Titanium dioxide and calcium carbonate supply chains concentrate in eastern industrial clusters, exposing price volatility for downstream manufacturers. The country's national workplace safety regulator is tightening particulate exposure guidelines in manufacturing facilities. Production gravity centers on Shandong and Jiangsu provinces where raw material processing integrates with tool assembly operations.
Japan
Precision manufacturing expertise sustains premium positioning in professional-grade layout tools for discerning trade professionals. METI industrial standards influence product specifications across Asia-Pacific export markets. Manufacturing concentrates in the Chubu region around Nagoya where metalworking traditions support high-tolerance mechanical components.
United Kingdom
Construction trade associations are mandating dustless chalk systems on publicly funded building projects in Greater London and the Southeast. The country's chemical regulator aligns with EU REACH restrictions even post-Brexit, maintaining barrier-free pigment formulations. Procurement specifications in education and commercial sectors now embed sustainability audit requirements that precede price negotiation.
Chalk Boxes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated manufacturers control raw material conversion while specialized brands focus on distribution and specification relationships. The vendor base fragments across three tiers: multinational tool conglomerates with broad retail penetration, regional specialists serving trade-specific channels, and private-label suppliers feeding cooperative purchasing agreements. Two dominant competitive moves are reshaping positioning: modular tool system integration that bundles chalk boxes with complementary layout instruments, and direct-to-institutional contracting that bypasses traditional retail intermediaries.
Within the multinational conglomerate tier, Stanley Black & Decker Inc and Tajima Industries Ltd exemplify divergent geographic anchoring strategies. Stanley Black & Decker leverages North American retail and industrial channel density to sustain volume leadership, while Tajima Industries occupies a position calibrated to precision manufacturing reputation in professional-grade segments. Among trade-focused specialists, Irwin Tools represents the contractor-segment archetype with product lines dominating North American professional channels. Apex Tool Group LLC sits within the diversified industrial tools category, spanning multiple layout instrument categories beyond chalk boxes alone.
| Leading Market Players |
|---|
| Apex Tool Group LLC |
| Stanley Black & Decker Inc |
| Tajima Industries Ltd |
| Kapro Industries Ltd |
| OX Group International |
| SNA Europe |
| Keson |
| DeWalt |
| Irwin Tools |
| Others |
Pricing and Supply Chain Analysis
Modular cartridge system adoption across professional-grade product lines simultaneously compresses replacement part revenue and concentrates consumable purchasing power with manufacturers who control refill formulation patents. This production-method transition redraws cost economics around polymer-bound dustless compositions while tilting supply leverage toward pigment specialists with REACH-compliant organic alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates precision-manufactured Japanese components from mid-market contractor tools and disposable education-sector units. Price differentiation hinges on OSHA silica certification grade and after-sales service bundling. Cost compression in standard chalk tiers is intensifying because calcium carbonate feedstock volatility from Shandong province suppliers squeezes legacy formulators. Education procurement teams exhibit highest price sensitivity, while commercial contractors accepting dustless mandates show lowest.
Supply Chain Analysis
Direct-to-institutional channels handle consolidated school district demand, while retail distribution serves fragmented contractor and consumer segments. Raw material sourcing draws from Chinese titanium dioxide clusters, German organic pigment formulators, and Midwestern tool assembly operations. Supply chain risk centers on single-source vulnerability for polymer-bound dustless carriers patented by specialty chemical suppliers. Distribution runs through cooperative purchasing agreements, hardware retail networks, and direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where OSHA silica exposure limits and EU REACH chemical restrictions continuously force equipment turnover and reformulation investment. California Proposition 65 enforcement serves as the clearest demand catalyst, mandating labeled alternatives that accelerate replacement cycles.
For Market Incumbents: Anticipate laser layout tool substitution threats in precision commercial construction by deepening mechanical precision advantages and locking in institutional procurement relationships. Prioritize backward integration into REACH-compliant pigment sourcing to defend margin position against raw material volatility. Certification investment in dual OSHA-EU compliance creates defendable positioning as smaller competitors face 12-18 month registration timelines. For New Entrants and Emerging Players: Dustless chalk formulation expertise offers entry into California and New York public works contracts where specification mandates outpace incumbent reformulation capacity. White-space concentrates in education-sector eco-packaging compliance, where recycled cardboard specifications and sustainability audits disqualify legacy suppliers. Go-to-market through cooperative purchasing agreements bypasses retail channel barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators with REACH-registered pigment systems and established school district contracts. Long-term viability favors suppliers with dual US-EU certification capabilities and modular consumable architectures. Watch OSHA silica enforcement expansion into additional states as the inflection signal for dustless adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Sourcing | REACH-compliant organic iron oxide investments secure European market access against cadmium restrictions. |
| Modular Consumable Architecture | Snap-in cartridge designs convert one-time equipment sales into recurring refill revenue streams. |
| Dual Certification Investment | Simultaneous OSHA silica and EU REACH registration compresses competitor time-to-market by 12-18 months. |
| Direct Institutional Contracting | Bypassing retail intermediaries captures California and Texas school district cooperative purchasing volumes. |
| Eco-Packaging Repositioning | Recycled cardboard specifications satisfy K-12 procurement mandates that now precede price negotiation. |
Research Methodology
Bottom-up education and construction contractor modeling reconciled against top-down raw material supply tracking forms the analytical core of this study. Primary interviews with plant managers at calcium carbonate processing facilities, procurement leads at school district cooperatives, distribution channel partners in hardware retail, and technical R&D directors at pigment formulators informed demand segmentation. Secondary validation drew from OSHA enforcement databases, EPA particulate emissions filings, ECHA REACH registration records, and customs trade data for titanium dioxide and calcium carbonate flows.
Input-output matrices map chalk formulation chemistry to end-use equipment requirements across the projection horizon. Segmentation dimensions include product type, application channel, packaging format, and end-user archetype. CAGRs derive from equipment replacement cycle analysis tied to regulatory compliance deadlines and infrastructure appropriation schedules. Forecast inputs incorporate OSHA silica guideline adoption timelines and EU Green Deal chemical sustainability target implementation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility in Chinese industrial clusters and substitution acceleration from laser layout technologies. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Cooler Box Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
VCI Bags Market
Packaging Containers
Can Holders Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Inverted Squeeze Bottle Market