
 Global Acrylic Airless Bottle Market | 2026-2036
Global Acrylic Airless Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylic Airless Bottle Market Foresight
Capital-intensity divergence between injection-molding scale and custom decoration capability is bifurcating competitive tiers. Albéa Group leverages integrated acrylic extrusion across European facilities to sustain margin on high-volume contracts. Lumson anchors its position through specialized decoration technologies for prestige fragrance houses. AptarGroup competes via global tooling networks that reduce lead times for multinational cosmetics manufacturers.
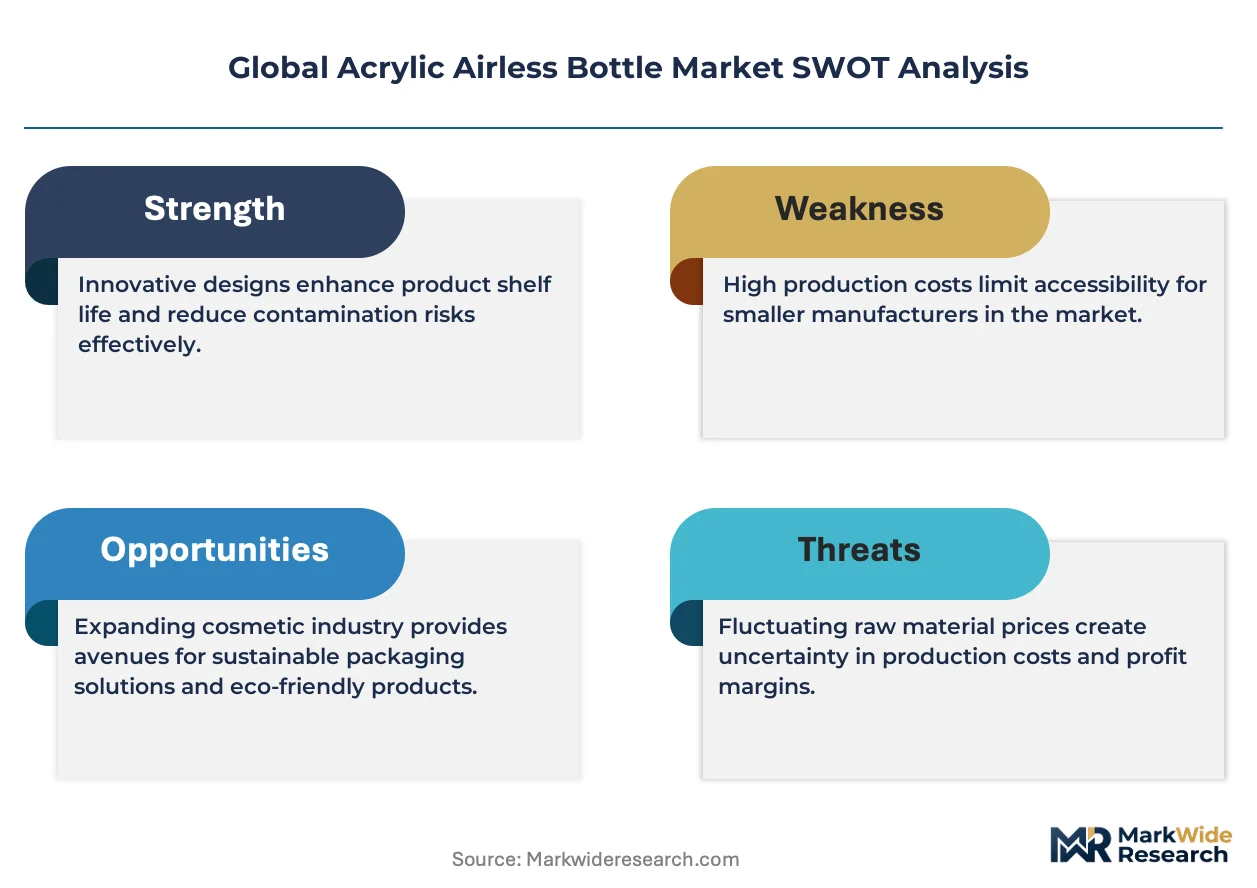
Acrylic airless bottles are rigid thermoplastic containers engineered with piston or diaphragm dispensing mechanisms that prevent air contact with contents, typically specified with wall thickness of 2–4 millimeters and barrier-grade acrylic resin to achieve 12–24 month product stability. Their primary commercial purpose is preserving oxygen-sensitive formulations in premium personal care and pharmaceutical applications. Standard airless bottles dominate unit volume across mass-market skincare lines, while custom airless bottles capture disproportionate margin pools in limited-edition luxury releases. Material composition trends show acrylic maintaining preference over PET in prestige segments due to superior optical clarity and heft, though polypropylene gains traction in pharmaceutical compliance applications.
FDA regulations on cosmetic container safety and ECHA REACH restrictions on monomer migration establish baseline material standards that shape formulation-compatibility testing across supply chains. EU MDR and ISO 15378 standards for pharmaceutical primary packaging create tiered certification requirements that filter market access for converters serving dual-use segments. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and pending EU packaging waste revisions that will recalibrate recyclability specifications for acrylic components.
Market Dynamics
Acrylic airless bottle supply chains are consolidating around dual-use pharmaceutical-cosmetic certification capabilities, with converters racing to secure ISO 15378 compliance ahead of EU MDR enforcement deadlines.
Growth Catalysts
- Preservation Technology Advancement:Piston-based airless mechanisms now achieve 24-month stability for retinol and vitamin C formulations, expanding addressable premium skincare segments.
- REACH Compliance Thresholds:ECHA monomer migration limits are accelerating material upgrades across European cosmetic packaging supply chains.
- MFDS Cosmetic Safety Directives:South Korean pharmaceutical-grade packaging standards are driving adoption of barrier-grade acrylic in K-beauty export lines.
Market Restraints
- Methyl Methacrylate Volatility:Acrylic resin feedstock prices fluctuate with crude oil derivatives, compressing converter margins on fixed-price annual contracts.
- Guangdong Province Concentration:Injection-molding capacity clusters in China's Pearl River Delta create geographic supply risk during regional logistics disruptions.
- Polypropylene Substitution:Pharmaceutical buyers increasingly specify PP for moisture-barrier applications where optical clarity is secondary.
Strategic Opportunities
- Indian Pharmaceutical Expansion:CDSCO's tightened primary packaging standards for dermocosmetics create certification-driven demand in Mumbai-Pune manufacturing corridors.
- Connected Packaging Convergence:NFC-enabled airless bottles integrating authentication and refill tracking are penetrating prestige fragrance channels.
- California EPR Framework:Extended producer responsibility legislation for rigid plastics is incentivizing mono-material acrylic designs with improved recyclability profiles.
Industry Challenges
- Tooling Lead Time Compression:Custom airless pump development cycles now demand 12-week turnaround versus historical 20-week baselines, straining in-house mold fabrication capabilities.
- Dual-Use Certification Complexity:Simultaneous ISO 15378 pharmaceutical and cosmetic GMP compliance requires redundant quality systems that extend facility qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylic Airless Bottle Market |
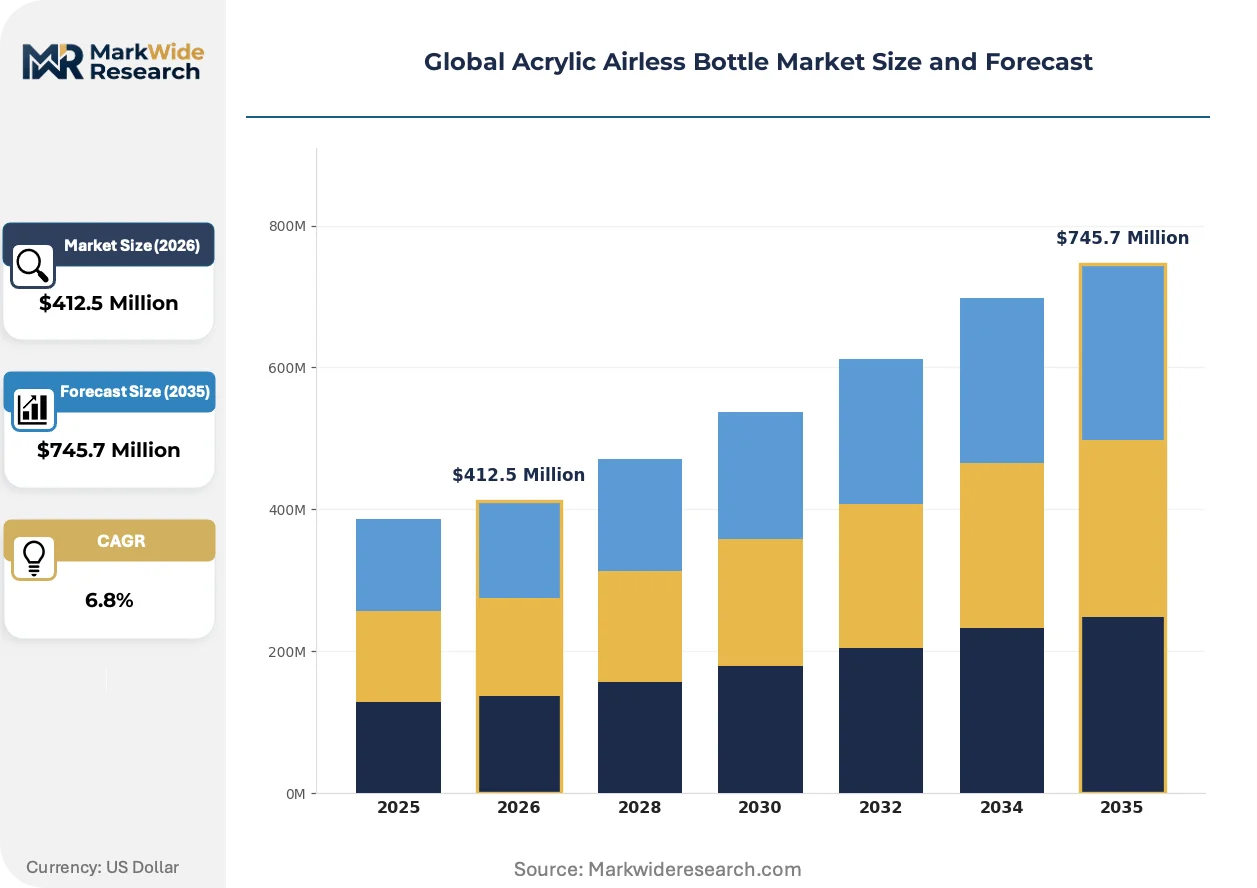
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Airless Bottles, Mini Airless Bottles, Travel Airless Bottles, Custom Airless Bottles Material Composition: Acrylic, Polyethylene Terephthalate, Aluminum, Glass, Polypropylene Application: Skincare, Haircare, Personal Hygiene, Decorative Packing, Industrial Packaging End User: Cosmetics Manufacturers, Pharmaceutical Companies, Food & Beverage Producers, Fragrance Makers |
| Companies Covered | Albéa Group, Lumson, AptarGroup, Quadpack, HCP Packaging, FusionPKG, Silgan Dispensing, Yonwoo, Raepak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylic Airless Bottle Market Shifts & Advancements
Active and intelligent packaging integration is redefining competitive differentiation in premium personal care, with material science advances enabling functional performance previously reserved for pharmaceutical applications.
Barrier-grade acrylic resin formulations is bifurcating the prestige skincare segment. High-clarity, heavy-wall constructions above 3 millimeters now dominate limited-edition luxury releases. Mass-market lines are compressing wall thickness to 2 millimeters with co-injection barrier layers. This technology is bifurcating converter capabilities between commodity injection molders and specialized decoration houses.
ECHA REACH Annex XVII restrictions on acrylate monomer migration are tightening formulation-compatibility testing protocols. Cosmetic brands must now document residual monomer levels below 0.01% for EU market access. Small-batch indie beauty labels lacking in-house analytical capabilities are outsourcing to certified testing laboratories in Germany and France.
Refillable airless systems are disrupting single-use premium packaging conventions. Prestige fragrance houses in Paris and Milan now specify modular bottle architectures with replaceable inner cartridges. South Korean skincare brands are piloting subscription-based refill programs through direct-to-consumer channels, compressing traditional retail distribution margins.
Global Acrylic Airless Bottle Market Segmentation
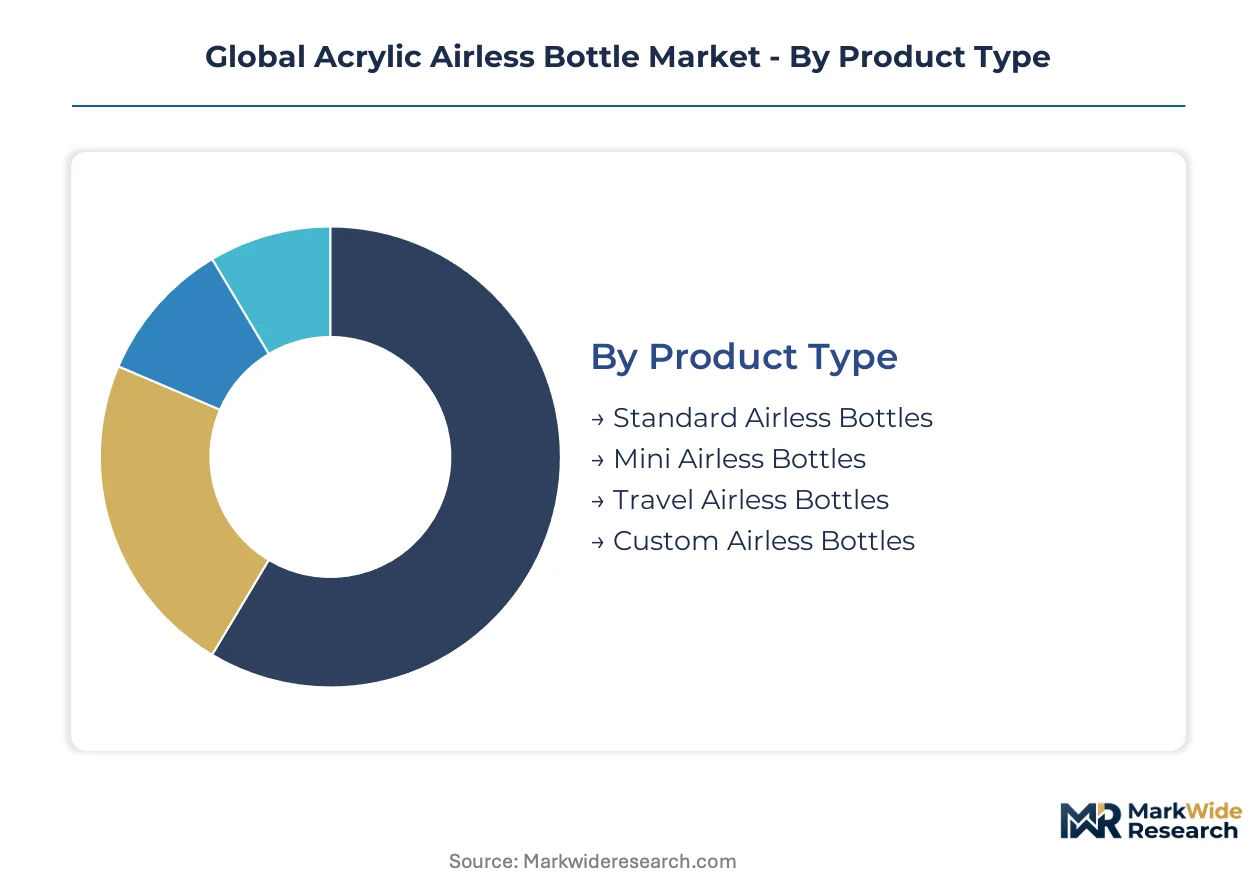
Acrylic airless bottle procurement decisions hinge on certification tier, formulation compatibility, and decoration complexity. Segmentation reveals how converter capabilities align with distinct buyer risk profiles across cosmetic and pharmaceutical end-uses.
Product Type:
Regulatory differentiation separates mass-market ISO 15378 baseline compliance from custom validation protocols for pharmaceutical primary packaging.
- Standard Airless Bottles:Fixed-dimension piston mechanisms with 2-millimeter wall thickness serve high-volume skincare lines. Demand concentrates in China's Guangdong manufacturing corridor where injection-molding scale achieves unit cost floors for multinational cosmetics brands.
- Custom Airless Bottles:Modular architectures with replaceable cartridges and specialized decoration accommodate limited-edition fragrance releases. Paris and Milan prestige houses drive specification complexity, requiring 12-week tooling cycles versus standard 20-week baselines.
- Mini Airless Bottles:Sub-30ml formats target airline retail and sampling programs with reduced monomer migration thresholds under ECHA REACH.
- Travel Airless Bottles:TSA-compliant capacities below 100ml serve duty-free channels with lightweight co-injection barrier constructions.
Established volume favors Standard Airless Bottles; emerging adoption favors Custom Airless Bottles.
Material Composition:
Cost tier stratification mirrors barrier performance requirements across oxygen-sensitive versus moisture-critical formulations.
- Acrylic:Barrier-grade resin with 3-4 millimeter heavy-wall construction delivers 24-month stability for retinol and vitamin C. South Korean K-beauty export lines specify optical clarity and heft that PET cannot replicate.
- Polypropylene:Moisture-barrier dominance in pharmaceutical applications where optical clarity is secondary. CDSCO's tightened dermocosmetic standards in India accelerate PP adoption for humidity-stable formulations.
- Polyethylene Terephthalate:Lightweight alternative for mass-market lines compressing per-unit material costs.
- Aluminum:Collapsible barrier layers in hybrid constructions for fragrance applications requiring complete oxygen exclusion.
- Glass:Premium fragrance houses in France specify for absolute chemical inertness in alcohol-based formulations.
Prestige positioning climbs fastest for Acrylic; pharmaceutical compliance shifts procurement toward Polypropylene.
Application:
Customer type concentration separates formulation stability requirements by oxygen sensitivity and regulatory exposure.
- Skincare:Retinol, vitamin C, and peptide formulations demand 12-24 month stability windows. ECHA monomer migration limits below 0.01% force material upgrades across European supply chains.
- Personal Hygiene:Lower barrier requirements permit thinner-wall constructions and faster tooling cycles.
- Haircare:Viscosity-adjusted piston mechanisms address conditioner and serum dispensing consistency.
- Decorative Packing:Limited-edition releases prioritize decoration technology over functional barrier performance.
- Industrial Packaging:Adhesive and sealant applications specify chemical resistance beyond cosmetic-grade acrylic.
Margin pools concentrate in Skincare; volume scale accumulates in Personal Hygiene.
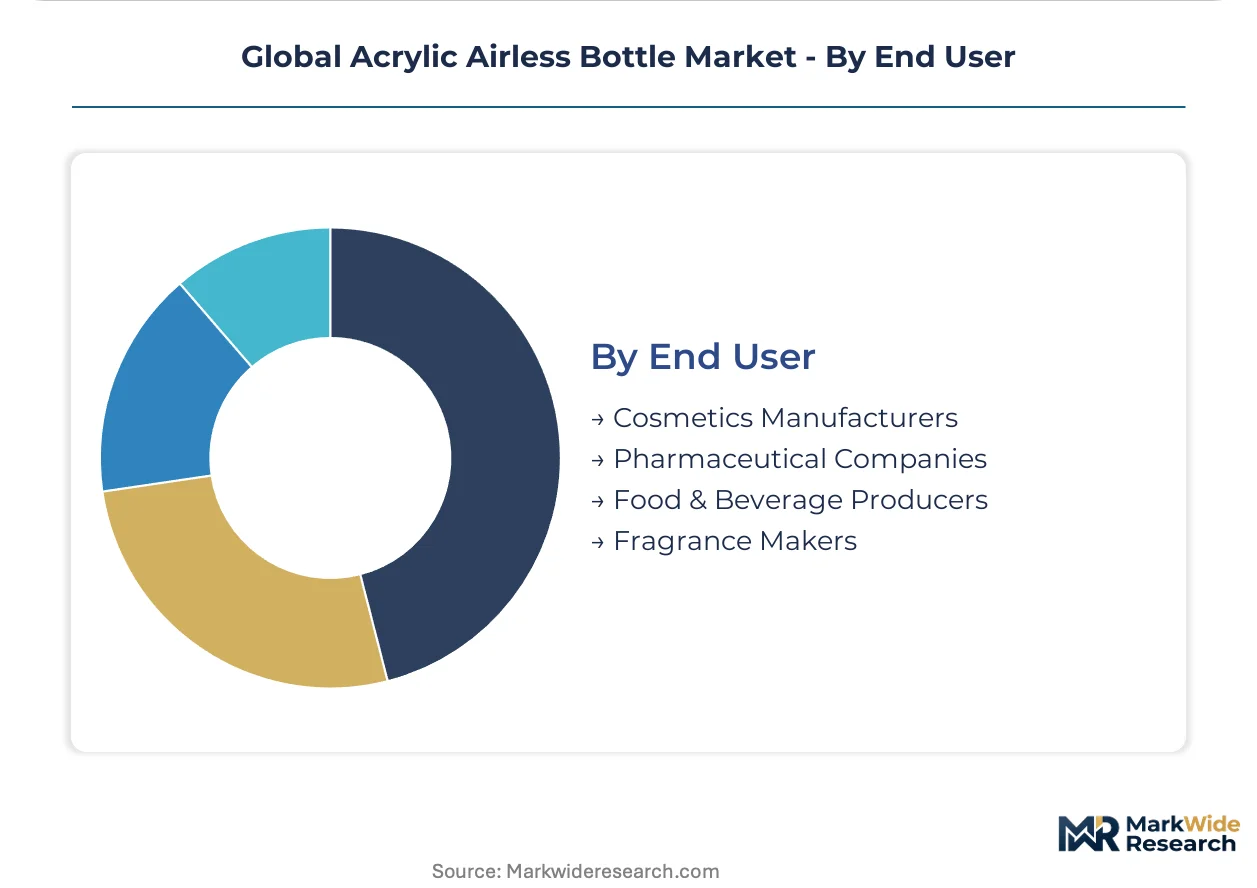
End User:
Supply concentration clusters around dual-use certification capabilities that filter market access.
- Cosmetics Manufacturers:Multinational brands leverage global tooling networks to compress lead times across regional production hubs.
- Pharmaceutical Companies:EU MDR and ISO 15378 compliance requirements extend facility qualification timelines. Simultaneous cosmetic GMP and pharmaceutical certification demands redundant quality systems.
- Fragrance Makers:Prestige houses in Milan and Paris specify modular refillable architectures with NFC-enabled authentication.
- Food & Beverage Producers:Emerging segment with FSSAI and FDA food-contact compliance requirements distinct from cosmetic standards.
Certification barriers favor established Pharmaceuticals; design innovation accelerates among Fragrance Makers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in South Korea and France where prestige skincare and fragrance houses command 40-60% packaging cost premiums, while mass-market volume aggregates in China's Guangdong corridor where unit economics compress converter margins.
China
Injection-molding capacity clusters in Guangdong's Pearl River Delta generate 70% of global acrylic airless bottle unit volume for mass-market skincare lines. SAMR's tightened cosmetic packaging safety standards are accelerating facility upgrades among Pearl River Delta converters. Dongguan and Shenzhen house the dominant tooling networks that supply multinational cosmetics brands with 12-week compressed lead times.
South Korea
Seoul Capital Area prestige skincare brands drive specification complexity for barrier-grade acrylic with 3-4 millimeter wall constructions. MFDS pharmaceutical-grade packaging directives are forcing material upgrades across K-beauty export supply chains. Incheon and Songdo free economic zones concentrate decoration specialists serving limited-edition fragrance releases for Paris and Milan houses.
Germany
ECHA REACH Annex XVII monomer migration limits below 0.01% are recalibrating formulation-compatibility testing protocols across European supply chains. CDSCO-aligned certification capabilities in Baden-Württemberg serve Indian pharmaceutical expansion into dermocosmetics. Stuttgart and Mannheim host analytical laboratories that small-batch indie beauty labels outsource to for EU market access documentation.
United States
FDA cosmetic container safety regulations establish baseline material standards that shape dual-use pharmaceutical-cosmetic converter qualification. California's extended producer responsibility framework for rigid plastics is incentivizing mono-material acrylic designs with improved recyclability profiles. Los Angeles and New Jersey manufacturing corridors concentrate refillable airless system pilots for direct-to-consumer subscription channels.
India
CDSCO's tightened primary packaging standards for dermocosmetics are creating certification-driven demand in Mumbai-Pune manufacturing corridors. BIS quality mark requirements are filtering market access for converters lacking ISO 15378 pharmaceutical compliance. Maharashtra's Thane-Belapur belt is attracting acrylic airless bottle investment from exporters targeting Middle East fragrance markets.
Global Acrylic Airless Bottle Market Competitive Landscape
Concentration sits with integrated European converters and specialized Asian decoration houses. The vendor base splits between scale-driven injection molders serving high-volume contracts and capability-focused specialists capturing limited-edition prestige releases. Three archetypes dominate: integrated acrylic extrusion operators, decoration-technology specialists, and global tooling network managers. Competitive moves center on dual-use certification acquisition and 12-week lead time compression through captive mold fabrication.
Among European-integrated converters, Albéa Group and Lumson exemplify divergent capability strategies. Albéa leverages in-house acrylic extrusion across continental facilities to defend margin on annual volume contracts. Lumson anchors prestige fragrance positioning through specialized decoration technologies that Paris and Milan houses specify for modular refillable architectures. AptarGroup represents the global tooling network archetype, with multinational cosmetics manufacturers sourcing through its distributed fabrication footprint to compress regional lead times.
| Leading Market Players |
|---|
| Albéa Group |
| Lumson |
| AptarGroup |
| Quadpack |
| HCP Packaging |
| FusionPKG |
| Silgan Dispensing |
| Yonwoo |
| Raepak |
| Others |
Supply & Pricing Matrix
Annual volume contracts with fixed-price terms lock in acrylic resin supply access for multinational cosmetics manufacturers while exposing converters to methyl methacrylate feedstock volatility. Guangdong injection molders absorb margin compression through scale economics, whereas European decoration specialists pass material cost fluctuations to prestige fragrance houses via configured-to-order pricing.
Pricing Analysis
Configured-to-order pricing for custom airless bottles commands 40-60% premiums over standard mass-market units, with differentiation driven by ISO 15378 certification tier and decoration complexity. Three-tier pricing structure across premium, standard, and economy levels stratifies converter margins, with barrier-grade acrylic resin grades separating tiers. Pricing pressure stems from polypropylene substitution in pharmaceutical applications where optical clarity is secondary. Mass-market skincare lines exhibit highest price sensitivity, while prestige K-beauty brands prioritize stability performance over per-unit cost.
Supply Chain Analysis
Inventory buffers compressed to 12-week tooling cycles strain captive mold fabrication capabilities across converter networks. Acrylic airless bottle supply concentrates in China, South Korea, and Germany, with heavy reliance on methyl methacrylate monomer, barrier-grade resin formulations, and precision pump mechanisms. Single-source vulnerability in Guangdong's Pearl River Delta creates geographic concentration risk during regional logistics disruptions. Distribution runs through direct-to-consumer subscription channels and multinational cosmetics brand procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic airless bottle demand follows cyclical recovery patterns tied to premium skincare launch calendars, with South Korean K-beauty export momentum providing near-term uplift.
For Market Incumbents: Secure dual-use ISO 15378 and cosmetic GMP certification ahead of EU MDR enforcement deadlines to defend against polypropylene substitution in pharmaceutical segments. Backward integration into captive acrylic extrusion capacity protects margin from methyl methacrylate price volatility, while 12-week lead time compression through in-house mold fabrication locks in multinational cosmetics contracts. For New Entrants and Emerging Players: Analytical testing service gaps for small-batch indie beauty labels lacking ECHA REACH documentation capabilities present white-space entry points. CDSCO-aligned certification capabilities in India's Mumbai-Pune corridor offer the most penetrable geography, with dermocosmetic packaging standards tightening faster than converter qualification timelines. Go-to-market positioning should emphasize rapid EU market access documentation for German and French outsourcing demand. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among decoration-technology specialists serving modular refillable architectures for Paris and Milan prestige houses. Five-to-ten year viability favors converters with simultaneous pharmaceutical and cosmetic certification rather than commodity injection molders exposed to Guangdong margin compression. Watch for California EPR framework implementation as inflection indicator for mono-material acrylic design adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Certification Investment | ISO 15378 compliance opens pharmaceutical-cosmetic crossover contracts ahead of EU MDR deadlines. |
| Backward Integration into Acrylic Extrusion | In-house resin production defends margin from methyl methacrylate feedstock price volatility. |
| Modular Refillable Architecture Development | Replaceable cartridge designs capture subscription revenue from South Korean direct-to-consumer channels. |
| NFC-Enabled Connected Packaging Integration | Authentication and refill tracking penetration differentiates prestige fragrance house offerings. |
| Mono-Material Design Transition | California EPR compliance improves recyclability profiles for rigid plastic packaging mandates. |
Research Methodology
Cross-validation between converter production data and multinational cosmetics procurement disclosures anchors the qualitative findings in operational reality. Primary interviews with injection-molding plant managers, prestige fragrance packaging directors, pharmaceutical regulatory affairs leads, and analytical testing laboratory heads combined with secondary validation from ECHA REACH documentation, SAMR cosmetic packaging safety filings, CDSCO dermocosmetic standards, and SEC converter 10-K disclosures. Bottom-up facility capacity modeling and top-down end-use demand triangulation reconcile volume estimates.
Sensitivity analysis across methyl methacrylate price scenarios and Guangdong logistics disruption probabilities bounds the projection range. Segmentation dimensions modeled include product type tier, material composition grade, application stability requirement, and end-user certification profile across the analysis window. CAGRs derive from facility utilization trajectories and brand launch pipeline data, with K-beauty export momentum and Indian pharmaceutical expansion serving as key demand inputs.
Forecasts assume regulatory continuity in ECHA REACH, EU MDR, and CDSCO frameworks; material policy shifts would require re-modeling. Acrylic monomer migration limit revisions, extended producer responsibility timeline accelerations, or pharmaceutical packaging standard harmonizations represent specific risk factors. Revision becomes warranted when polypropylene substitution rates in dermocosmetic applications cross threshold levels that displace barrier-grade acrylic specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Airless Bottles Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Portion Packs Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Single Serve Packaging Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Cooler Box Market