
 Correx Trays Market | 2026-2036
Correx Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Correx Trays Market Outlook
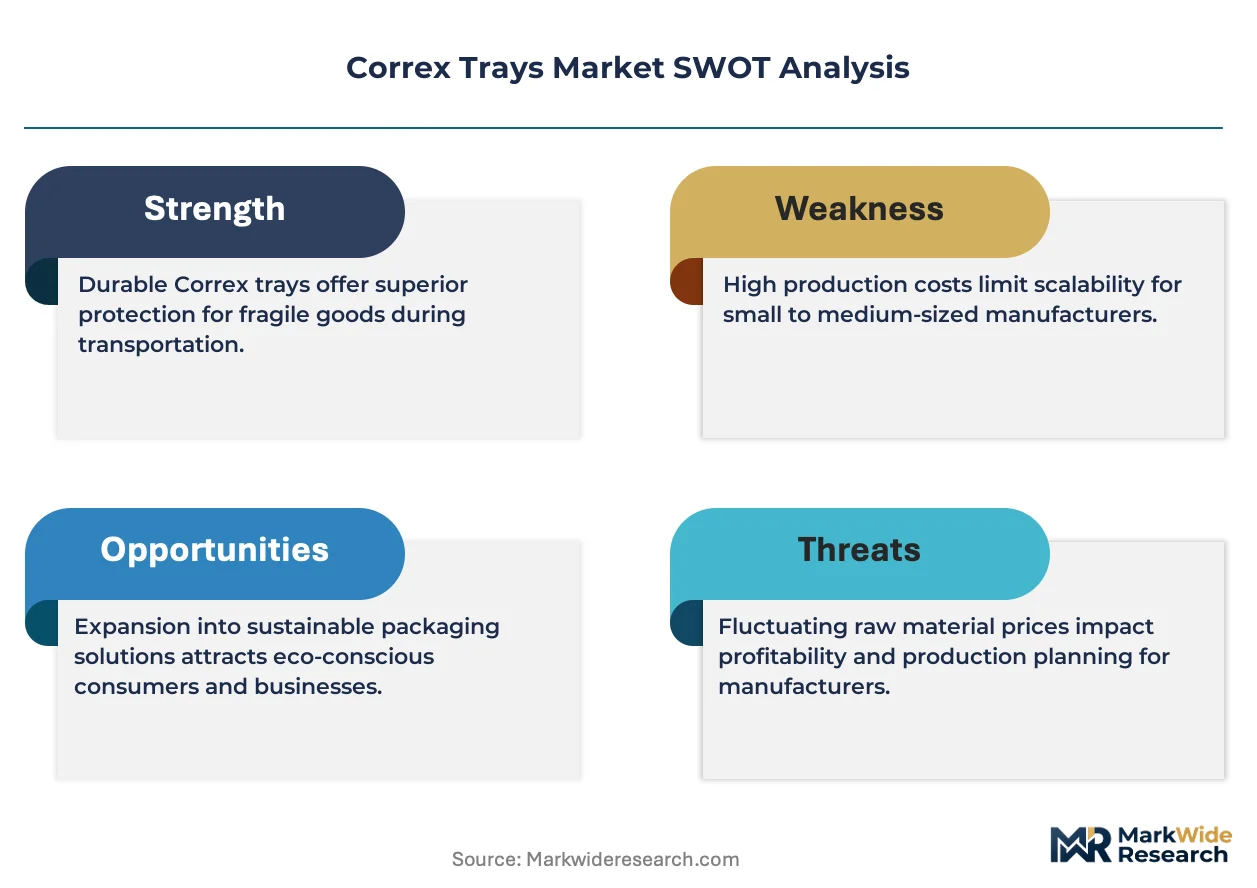
Buyer concentration across European automotive supply chains is broadening as tier-one suppliers diversify sourcing across multiple packaging vendors. DS Smith Plc leverages its continental manufacturing footprint to serve fragmented procurement desks. Sealed Air Corporation anchors North American electronics fulfillment with specialized divider tray systems. Smurfit Kappa Group competes through integrated design-to-delivery services for retail display applications.
Correx trays are fluted polypropylene sheet structures, typically manufactured through extrusion and thermoforming processes to achieve lightweight rigidity with moisture and chemical resistance. Standard tray formats serve high-volume automotive component logistics where dimensional repeatability reduces handling cost. Custom tray configurations capture margin pools in precision electronics packaging where electrostatic discharge protection and part-specific cavity design justify premium positioning. Divider trays gain traction in pharmaceutical distribution networks requiring segregated multi-SKU handling.
EU REACH compliance and FDA food-contact material standards govern resin selection and additive chemistry across export-oriented production. EPA industrial emissions guidelines shape extrusion facility siting and energy recovery investments in United States manufacturing bases. Stakeholders must monitor evolving extended producer responsibility frameworks in Germany and California that mandate minimum recycled content thresholds and end-of-life collection infrastructure.
Market Dynamics
EU packaging waste directives are forcing automotive and electronics manufacturers to abandon single-use corrugated formats in favor of reusable Correx tray systems, reshaping procurement specifications across tier-one supplier networks.
Growth Catalysts
- REACH Compliance Mandates:ECHA restrictions on hazardous additives in traditional plastics push converters toward polypropylene fluted sheet alternatives that meet chemical safety thresholds without reformulation costs.
- Automotive Component Logistics:Just-in-sequence assembly lines in Germany and the United Kingdom require dimensionally stable returnable packaging that withstands hundreds of handling cycles without degradation.
- Asia-Pacific E-Commerce Corridors:Stackable tray configurations reduce cubic meterage in cross-border fulfillment, cutting last-mile distribution costs for electronics and pharmaceutical distributors.
Market Restraints
- Polypropylene Resin Volatility:Feedstock price swings tied to naphtha and propane markets compress converter margins and destabilize long-term contract pricing with automotive OEMs.
- Chinese Extrusion Capacity Concentration:Over half of global fluted sheet production sits in Shandong and Guangdong provinces, creating geographic supply risk and quality inconsistency for export buyers.
- Competing Fiber-Molded Formats:Molded fiber trays with water-resistant coatings capture shelf-space in food-contact and light-duty electronics applications where moisture protection requirements are moderate.
Strategic Opportunities
- India Pharmaceutical Cold Chain:CDSCO temperature-compliance requirements for vaccine distribution create demand for insulated Correx hybrid trays with phase-change material integration.
- California Extended Producer Responsibility:SB 54 mandates for minimum recycled content and end-of-life collection infrastructure favor domestic converters with closed-loop recycling partnerships.
- RFID-Enabled Smart Packaging:Convergence of printed electronics with fluted polypropylene substrates enables real-time inventory tracking for high-value medical device logistics.
Industry Challenges
- Tooling Lead Times:Custom thermoform mold fabrication for precision electronics cavity trays extends new product introduction cycles beyond 16 weeks, straining customer responsiveness.
- Cross-Border Certification Complexity:Simultaneous FDA food-contact, EU REACH, and BIS compliance for export-oriented Indian manufacturers requires redundant testing protocols and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Correx Trays Market |
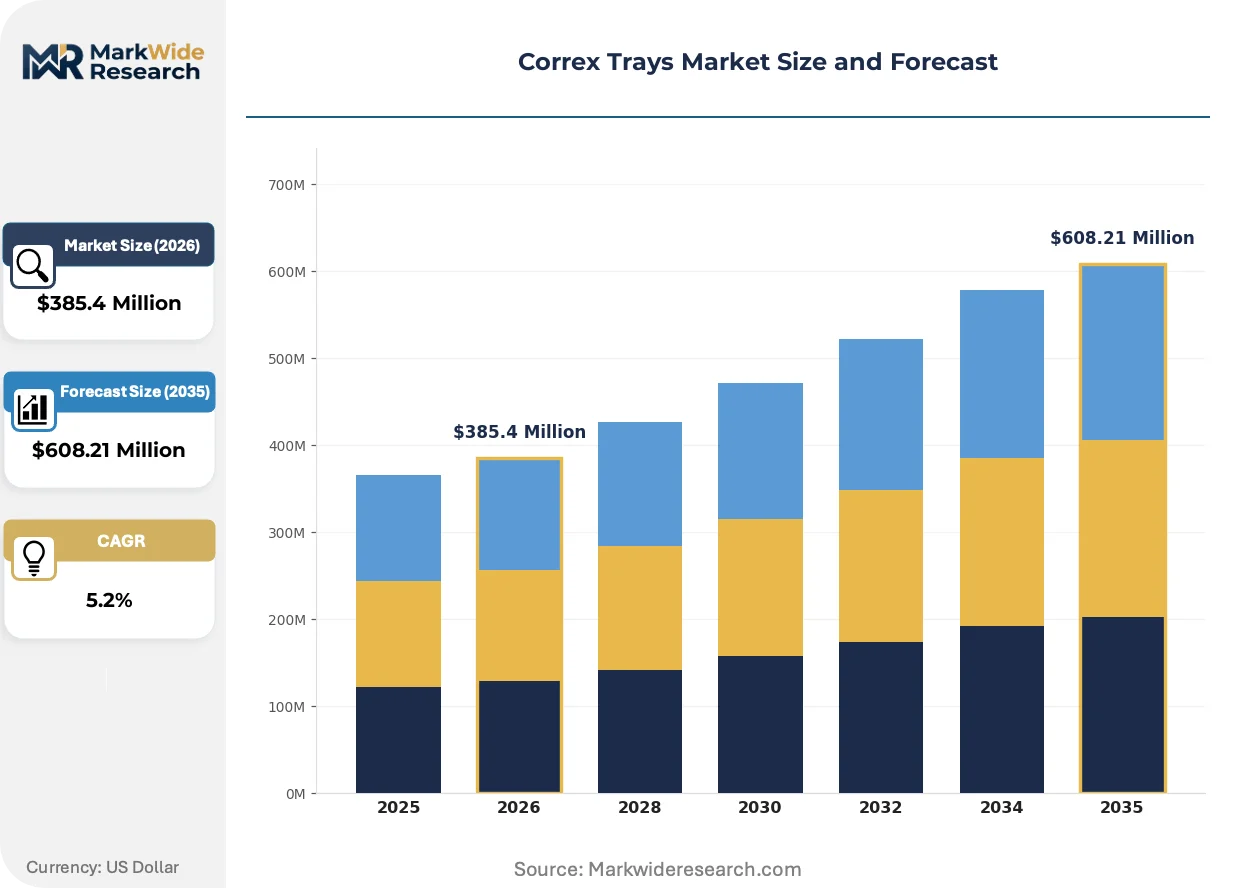
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Trays, Custom Trays, Stackable Trays, Divider Trays End User: Food Industry, Electronics, Automotive, Retail Material: Corrugated Polypropylene, Recycled Plastic, Biodegradable Material, Foam Application: Packaging, Storage, Transportation, Display |
| Companies Covered | Berry Global Inc., Sealed Air Corporation, Amcor Limited, DS Smith Plc, Huhtamaki Group, Sonoco Products Company, Smurfit Kappa Group, Inteplast Group Corporation, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Correx Trays Market Strategic Shifts
Active material science development and regulatory chemistry restrictions are compressing the viable formulation space for fluted polypropylene packaging, favoring converters with in-house polymer compounding capabilities.
Antistatic-grade Correx formulations with permanent dissipative properties are overtaking temporary topical coatings in precision electronics packaging. Semiconductor equipment manufacturers in South Korea and Taiwan specify surface resistivity below 10^9 ohms per square for wafer handling trays. This specification compression is eliminating commodity converters lacking carbon nanotube or ionic conductive additive expertise.
EU F-Gas Regulation phase-down schedules are pressuring extrusion facilities to abandon hydrofluorocarbon-based cooling systems. German and Dutch converters are retrofitting lines with ammonia-based refrigeration and heat recovery loops. Automotive suppliers sourcing from these facilities now embed carbon footprint thresholds in supplier scorecards alongside price and quality metrics.
Consolidated procurement desks at European automotive OEMs are unbundling packaging specification from logistics execution, creating direct relationships between tier-two Correx converters and central engineering teams. This disintermediation bypasses traditional distributor networks that previously captured margin and controlled technical dialogue. Volkswagen Group and BMW procurement organizations in Wolfsburg and Munich now issue material specifications directly to specialized tray manufacturers.
Correx Trays Market Segmentation
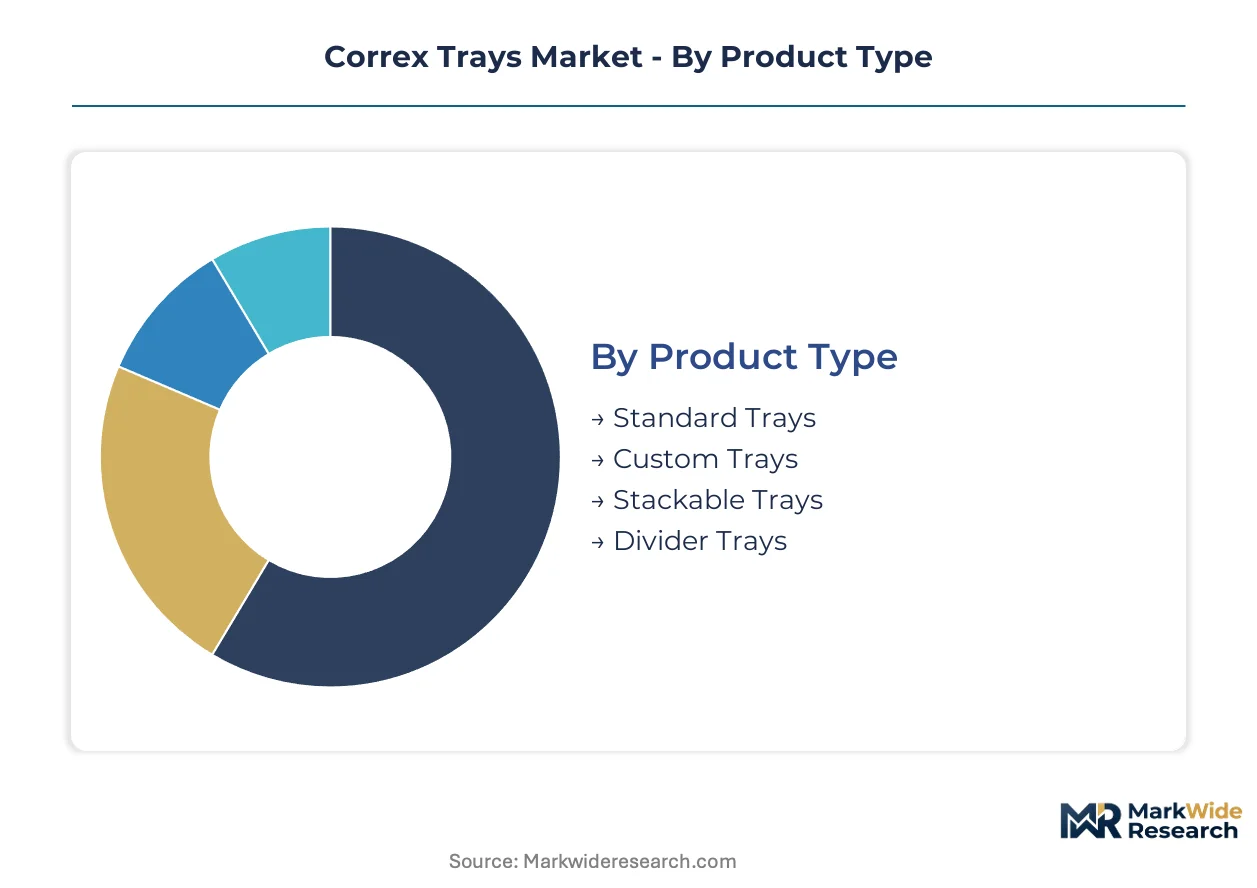
Correx tray procurement specifications diverge sharply across end-use verticals, with automotive and electronics buyers demanding returnable-loop durability while food and retail segments prioritize unit economics over cycle life. Material selection and cavity complexity separate premium custom formats from commodity standard offerings, creating distinct margin pools within converter portfolios.
Product Type:
Upgrade cycles from single-use corrugated to reusable polypropylene systems are compressing replacement timelines across European automotive supply chains, with specification changes now occurring mid-contract rather than at model-year boundaries.
- Standard Trays:Extruded fluted polypropylene sheet formed into fixed-dimension rectangular formats with uniform wall thickness and standardized corner radii. Automotive component logistics in Germany and the United Kingdom absorb volume volumes for powertrain and chassis part sequencing, where dimensional repeatability across hundreds of handling cycles reduces line-side replenishment labor.
- Custom Trays:Thermoformed cavity designs with part-specific nesting geometries, electrostatic discharge grades, and integrated labeling zones. Semiconductor equipment manufacturers in South Korea and Taiwan specify surface resistivity below 10^9 ohms per square for wafer handling applications, eliminating commodity converters lacking conductive additive expertise.
- Stackable Trays:Interlocking vertical profiles with positive-lock feet and recessed lids for cube-optimized palletization. Asia-Pacific e-commerce corridors favor these configurations for cross-border electronics fulfillment.
- Divider Trays:Segmented cavity layouts with removable or fixed partitions for multi-SKU handling. Pharmaceutical distribution networks deploy these for segregated vaccine and biologic transport under CDSCO temperature-compliance frameworks.
Standard trays sit at the top of the volume ranking, with custom trays climbing the fastest as precision electronics packaging specifications tighten.
End User:
Cost tier stratification separates capital-intensive returnable packaging investments from expendable-format procurement, with automotive and electronics buyers accepting three-year payback periods that food and retail segments reject.
- Automotive:Just-in-sequence assembly lines require dimensionally stable returnable packaging that withstands hundreds of handling cycles without degradation. Volkswagen Group and BMW procurement organizations now issue material specifications directly to specialized tray manufacturers, bypassing traditional distributor networks.
- Electronics:Precision component handling demands antistatic-grade formulations with permanent dissipative properties, overtaking temporary topical coatings. Wafer and semiconductor logistics drive the steepest specification compression in this vertical.
- Food Industry:FDA food-contact material standards govern resin selection and additive chemistry, with moderate moisture protection requirements enabling competition from fiber-molded alternatives.
- Retail:Display-oriented applications favor integrated design-to-delivery services where graphic printing and structural branding merge with protective function.
Automotive commands the largest installed base, while electronics expands most quickly as semiconductor capital investment accelerates.
Material:
Margin concentration flows toward converters with in-house polymer compounding capabilities as REACH restrictions compress viable formulation space.
- Corrugated Polypropylene:Virgin resin extrusion with controlled fluting geometry for stiffness-to-weight optimization. Dominates high-cycle automotive and precision electronics applications where lot traceability and consistent melt flow index are mandatory.
- Recycled Plastic:Post-industrial regrind and post-consumer flake incorporation, subject to California SB 54 minimum content thresholds and German extended producer responsibility mandates. Closed-loop partnerships with automotive OEMs secure supply agreements.
- Biodegradable Material:PLA and starch-blend alternatives for single-use food-contact applications with moderate durability requirements.
- Foam:Expanded polypropylene and polyethylene formats for cushioning-dominant electronics and medical device packaging.
Corrugated polypropylene holds volume leadership, with recycled plastic gaining share fastest under regulatory pressure.
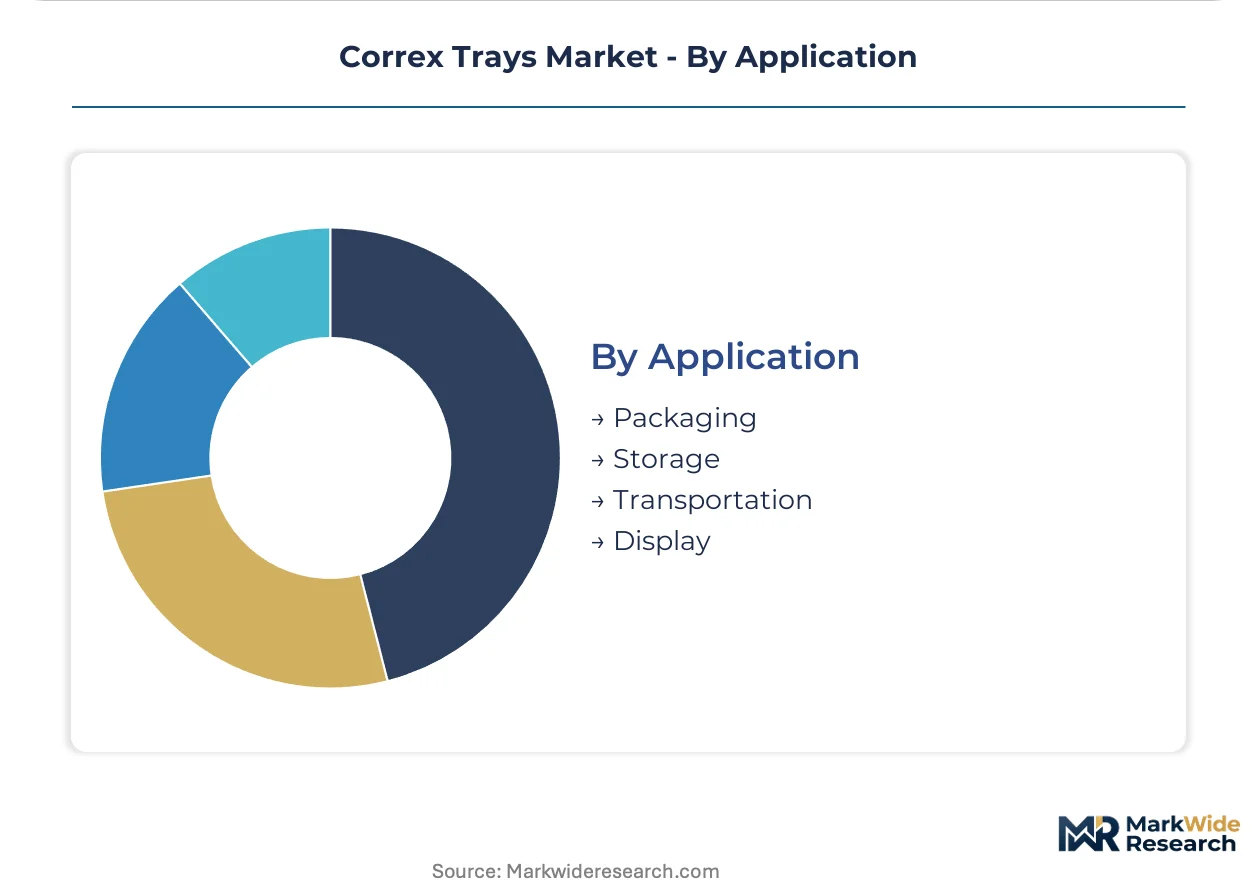
Application:
Customer type separation distinguishes logistics-executed packaging from marketing-driven display formats, with procurement desks and brand teams operating independent specification channels.
- Packaging:Protective containment for in-transit damage prevention, spanning primary product contact through tertiary palletization. Electronics and automotive verticals dominate specification complexity.
- Storage:Warehouse racking and work-in-progress inventory systems requiring stack stability and label readability over extended dwell times.
- Transportation:Cross-border and last-mile distribution optimization through cube efficiency and weight reduction. Asia-Pacific logistics corridors drive format innovation.
- Display:Point-of-sale presentation with graphic integration and structural merchandising features. Retail applications favor converters with integrated printing capabilities.
Packaging captures the deepest volume base, with display applications showing the steepest expansion trajectory as retail unbundles specification from logistics execution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China diverge sharply in Correx tray deployment patterns, with German automotive OEMs prioritizing returnable-loop durability while Chinese electronics exporters optimize for stackable cube efficiency in cross-border fulfillment.
Germany
Volkswagen Group and BMW procurement desks in Wolfsburg and Munich now issue material specifications directly to specialized tray manufacturers, bypassing traditional distributor networks. REACH restrictions on hazardous additives push converters toward polypropylene fluted sheet alternatives. The Baden-Württemberg and Bavaria industrial corridors host the densest concentration of automotive packaging engineering.
China
Over half of global fluted sheet production sits in Shandong and Guangdong provinces, creating geographic supply risk for export buyers. NMPA and GB standards govern domestic pharmaceutical distribution packaging. The Yangtze River Delta and Pearl River Delta clusters dominate electronics export logistics serving semiconductor capital equipment manufacturers.
United States
EPA industrial emissions guidelines shape extrusion facility siting and energy recovery investments across manufacturing bases. California SB 54 mandates for minimum recycled content and end-of-life collection infrastructure favor domestic converters with closed-loop recycling partnerships. The Midwest automotive belt and Southeast electronics corridors drive specification tightening.
India
CDSCO temperature-compliance requirements for vaccine distribution create demand for insulated Correx hybrid trays with phase-change material integration. BIS certification requirements add compliance layers for export-oriented manufacturers. The Maharashtra and Gujarat pharmaceutical clusters anchor cold-chain packaging innovation.
South Korea
Semiconductor equipment manufacturers specify surface resistivity below 10^9 ohms per square for wafer handling trays, eliminating commodity converters lacking conductive additive expertise. MFDS pharmaceutical regulations govern multi-SKU distribution formats. The Gyeonggi-Seoul corridor concentrates precision electronics packaging demand.
Correx Trays Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base fragments between integrated packaging conglomerates with continental manufacturing footprints and regional extrusion specialists serving single-industry verticals. Three archetypes dominate: automotive-anchored returnable packaging engineers, electronics-focused ESD-grade formulators, and retail-integrated design-to-delivery service providers. Competitive moves center on backward integration into resin compounding and strategic partnerships for closed-loop recycling infrastructure.
Among diversified packaging conglomerates, DS Smith Plc and Smurfit Kappa Group occupy positions spanning automotive logistics and retail display applications. Sealed Air Corporation exemplifies the electronics-specialist archetype with dedicated divider tray systems for North American fulfillment networks. These three companies represent distinct strategic postures: continental manufacturing scale, integrated design services, and precision electronics specialization.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Sealed Air Corporation |
| Amcor Limited |
| DS Smith Plc |
| Huhtamaki Group |
| Sonoco Products Company |
| Smurfit Kappa Group |
| Inteplast Group Corporation |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
California SB 54 mandates for minimum recycled content and end-of-life collection infrastructure gate qualified supply access for premium-tier converters, compressing margin pools for non-compliant competitors while enabling closed-loop recyclers to command sustained price premiums from automotive OEM procurement desks.
Pricing Analysis
Capacity additions in Shandong and Guangdong provinces are reshaping price floors for standard-grade extruded sheet, forcing European and North American converters toward custom thermoformed configurations. Three-tier pricing structure across premium, standard, and economy levels separates ESD-grade wafer handling trays from automotive sequencing formats and single-use retail display units. Price differentiation hinges on certification grade—EU REACH and FDA food-contact tiers command 15-25% premiums—and volume scale, with automotive OEMs locking multi-year offtake agreements. Cost compression in commodity standard trays is intensifying because Chinese extrusion overcapacity feeds spot-market volatility. Food and retail segments exhibit highest price sensitivity, rejecting payback periods beyond 18 months, while semiconductor equipment manufacturers in South Korea and Taiwan accept three-year returns for precision cavity designs.
Supply Chain Analysis
Container freight rate volatility from Asia-Pacific ports to European automotive corridors directly shapes landed cost competitiveness for stackable tray configurations. Raw material supply concentrates in China, Germany, and the United States, with polypropylene resin compounding anchored in the US Gulf Coast and German chemical complexes. Production draws from naphtha and propane feedstocks tethered to regional petrochemical infrastructure, creating geographic cost differentials. Single-source vulnerability runs through Shandong province extrusion clusters, where quality inconsistency disrupts export buyer qualification timelines. Distribution runs through tier-one automotive supplier networks in Germany, direct OEM relationships in North America, and pharmaceutical cold-chain integrators in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: converters with EU REACH-compliant compounding capabilities in Germany capture premium pricing from automotive OEMs, while non-compliant Asian exporters face margin compression from California SB 54 equivalent regulations spreading across US states.
For Market Incumbents: Anchor backward integration into resin compounding to defend margin position against polypropylene price volatility and specification compression from REACH additive restrictions. Secure closed-loop recycling partnerships with Volkswagen Group and BMW procurement organizations to lock volume commitments. Invest in ammonia-based extrusion cooling retrofits ahead of EU F-Gas Regulation phase-down deadlines to maintain supplier scorecard eligibility. For New Entrants and Emerging Players: Launch via direct OEM engineering relationships rather than distributor networks, exploiting disintermediation trends in European automotive procurement. Target India pharmaceutical cold-chain packaging as the most penetrable vertical, where CDSCO temperature-compliance requirements outpace domestic converter capability. Pursue RFID-enabled smart packaging as the primary go-to-market angle, converging printed electronics expertise with fluted substrate thermoforming. For Investors and Strategic Acquirers: Roll-up economics work for regional extrusion specialists with automotive-anchored returnable packaging expertise because tier-one supplier diversification across multiple packaging vendors fragments incumbent market share without consolidating procurement power. Five-to-ten-year viability favors converters with in-house polymer compounding and closed-loop infrastructure. Target mid-cap specialists with ESD-grade formulation capabilities in South Korea and Taiwan. Watch semiconductor capital investment cycles as the primary inflection signal for precision electronics packaging demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | REACH restrictions compress formulation space, favoring converters with captive additive expertise and lot traceability. |
| Closed-Loop Recycling Partnership | California SB 54 and German EPR mandates secure supply agreements with automotive OEMs seeking compliance pathways. |
| Ammonia-Based Cooling Retrofit | EU F-Gas Regulation phase-down pressures extrusion facilities to abandon hydrofluorocarbon systems for heat recovery loops. |
| RFID-Enabled Smart Packaging Development | Printed electronics convergence with fluted substrates enables real-time tracking for high-value medical device logistics. |
| Direct OEM Engineering Relationship | Volkswagen Group and BMW procurement desks now issue specifications directly, bypassing traditional distributor margin capture. |
Study Parameters
Bottom-up automotive and electronics end-use modeling reconciled against top-down fluted sheet production tracking forms the analytical core of this study. Primary interviews with tier-one supplier procurement managers, OEM packaging engineers, extrusion facility plant managers, and pharmaceutical cold-chain integrators combined with secondary validation from customs trade data, EU ECHA regulatory filings, SEC 10-K disclosures from packaging conglomerates, and automotive production databases. Triangulation between demand-side consumption patterns and supply-side capacity utilization ensures statistical integrity across volume and value estimates.
Input-output matrices map polypropylene resin feedstock costs through extrusion and thermoforming value-added stages to end-use price realizations across the projection horizon. Segmentation dimensions include product type, end-user vertical, material grade, and application function, with regional regulatory clusters treated as distinct market boundaries. CAGRs derive from regression analysis against automotive production forecasts, semiconductor capital expenditure cycles, and pharmaceutical cold-chain infrastructure buildouts. Forecast inputs incorporate REACH compliance cost pass-through assumptions and Chinese extrusion capacity expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polypropylene resin price volatility and EU packaging waste directive enforcement intensity. Projections reflect documented assumptions regarding automotive OEM returnable packaging adoption rates and electronics antistatic specification compression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Assembly Trays Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Food Grade Bottles Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Telescope Box Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Acrylic Boxes Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Custom Boxes Market