
 VCI Bags Market | 2026-2036
VCI Bags Market Size, Share, and Industry Trends Forecast 2026-2036
VCI Bags Market Outlook
Migration toward military-grade and aerospace-certified VCI formulations is unwinding legacy commodity pricing in the protective packaging sector. Cortec Corporation leverages its captive chemistry operations to supply customized inhibitor blends for defense contractors. Daubert Cromwell anchors North American automotive supply chains with specification-grade polyethylene and polypropylene VCI bags. Northern Technologies International Corporation specializes in bio-based corrosion inhibitor systems that differentiate its portfolio from conventional nitrite-reliant alternatives.
VCI bags are multi-layer polymer or paper-based enclosures impregnated with volatile corrosion inhibitors that sublimate to form a molecular protective film on ferrous and non-ferrous metal surfaces, typically specified by vapor-phase inhibitor concentration, film thickness measured in microns, and shelf-life duration under ASTM D1748 humidity testing conditions. The primary industrial purpose is eliminating in-process rust during storage, overseas shipment, and extended inventory holding without requiring oils, greases, or cleaning operations downstream. Polyethylene VCI bags dominate volume due to their moisture barrier properties and heat-seal compatibility, while nylon variants command premium positioning in electronics manufacturing where outgassing constraints are stringent. Flat bags remain the mature workhorse format, though zipper configurations are gaining fastest in aerospace MRO operations where repeated access to protected components is routine.
EPA oversight under the Toxic Substances Control Act constrains nitrite-based inhibitor chemistries in the United States, while REACH registration requirements in Europe mandate full substance dossiers for VCI active ingredients crossing threshold tonnages. The EU F-Gas Regulation indirectly shapes material selection by pressuring manufacturers to eliminate fluorinated barrier layers that historically enhanced vapor retention. ASTM International and ISO 9227 salt-spray testing protocols function as de facto market access gates, with OEMs refusing qualification to suppliers lacking certified performance data. Stakeholders must monitor regulatory divergence between jurisdictions on nitrite restrictions and decide whether to maintain dual formulation portfolios or accelerate conversion to amine-carboxylate and plant-derived inhibitor platforms.
Market Dynamics
REACH compliance deadlines and EPA disclosure mandates are forcing VCI bag manufacturers to abandon nitrite-reliant formulations faster than supply chains can certify alternatives, compressing qualification windows and fragmenting supplier relationships across automotive and aerospace procurement desks.
Growth Catalysts
- REACH Registration Thresholds:European chemical dossier requirements above 100-ton annual volumes are accelerating consolidation among inhibitor blenders capable of funding full substance characterization, privileging mid-cap compounders with captive analytical labs.
- Aerospace MRO Expansion:Precision component storage protocols at maintenance facilities in Germany, France, and the United States are specifying zipper-configured VCI bags for repeated access scenarios without re-bagging labor.
- Heat-Seal Automation:Polyethylene VCI bag formats compatible with robotic sealing stations are displacing manual packaging lines at just-in-time automotive supplier parks in Stuttgart and Wolfsburg.
Market Restraints
- Nitrite Input Volatility:Sodium nitrite feedstock costs fluctuate with fertilizer sector demand cycles, squeezing margin on legacy inhibitor formulations before amine-carboxylate alternatives achieve cost parity.
- Barrier Layer Supply Concentration:Multi-layer coextrusion capacity for vapor-retentive films concentrates among German and Austrian polymer processors, creating single-source vulnerability for North American VCI bag converters.
- Fluorinated Polymer Phase-Out:EU F-Gas Regulation restrictions on perfluorinated barrier layers are eliminating high-performance vapor retention options without fully qualified drop-in replacements certified to ASTM D1748.
Strategic Opportunities
- Plant-Derived Inhibitor Platforms:Bio-based corrosion inhibitor chemistry from agricultural waste streams offers regulatory tailwind under EU Green Deal bioeconomy procurement preferences and California SB 54 extended producer responsibility frameworks.
- Electronics Manufacturing Penetration:Nylon VCI bags with outgassing constraints below 100 ppm total volatile organic compounds remain underdeployed in semiconductor capital equipment supply chains serving Taiwan and South Korea fabrication facilities.
- Defense Contractor Specifications:MIL-PRF-3420H qualified VCI packaging for weapons system preservation represents a specification-grade segment with multi-year sole-source contract potential and limited qualified vendor pools.
Industry Challenges
- ASTM D1748 Certification Bottlenecks:Humidity chamber testing capacity at third-party laboratories runs six-month backlogs, delaying new formulation launches and freezing R&D pipeline conversion to revenue.
- Dual-Formulation Inventory Strain:Maintaining separate nitrite-based and nitrite-free SKUs for divergent regulatory jurisdictions doubles working capital requirements and complicates demand forecasting across automotive program lifecycles.
- Polymer Compounding Talent Scarcity:Vapor-phase inhibitor dispersion expertise in twin-screw extrusion operations concentrates among retiring cohorts at European masterbatch suppliers, constraining technology transfer to Asian contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VCI Bags Market |
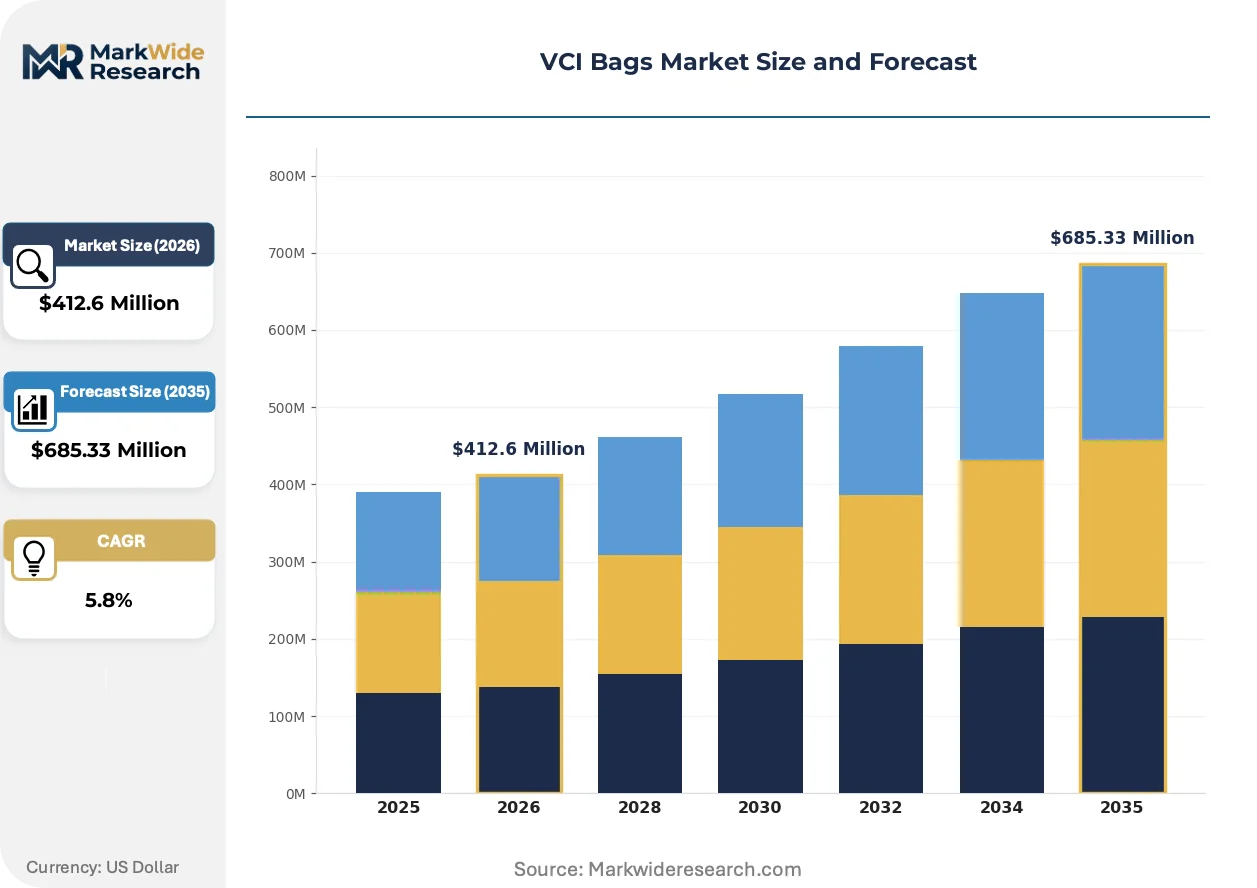
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, Paper Application: Metal Protection, Electronics, Automotive Parts, Industrial Equipment End User: Aerospace, Electronics Manufacturing, Automotive, Oil & Gas Packaging Type: Flat Bags, Gusseted Bags, Zipper Bags, Roll Bags |
| Companies Covered | Northern Technologies International Corporation, Cortec Corporation, Daubert Cromwell, Armor Protective Packaging, Intertape Polymer Group, BASF SE, Aicello Corporation, American Plastics Company, Protective Packaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VCI Bags Market Strategic Shifts
Active inhibitor chemistry is diverging along regulatory fault lines while packaging formats adapt to automation and repeated-access use cases in precision manufacturing supply chains.
Multi-layer coextrusion with vapor-phase inhibitor impregnation is fragmenting the supplier base between integrated compounders with captive film production and converters dependent on toll-coating arrangements. Aerospace MRO operations in the United States and Germany are specifying these formats for component preservation during extended storage, compressing qualification timelines and favoring suppliers with in-house ASTM D1748 testing infrastructure.
EPA enforcement discretion letters under the Toxic Substances Control Act are constraining nitrite-based inhibitor shipments into California and Northeastern states, forcing blenders to accelerate amine-carboxylate platform development. Automotive OEMs in Michigan and Ohio are responding by inserting REACH-compliant formulation requirements into supplier quality agreements eighteen months ahead of federal mandates.
Specification-driven procurement is consolidating buyer power among tier-one automotive suppliers and defense primes, displacing spot-market purchasing for commodity-grade VCI bags. Long-term inhibitor supply agreements with volume commitments and fixed-price escalators are replacing quarterly spot tenders in Germany's automotive supplier corridor, with contract duration extending from twelve to thirty-six months.
VCI Bags Market Segmentation
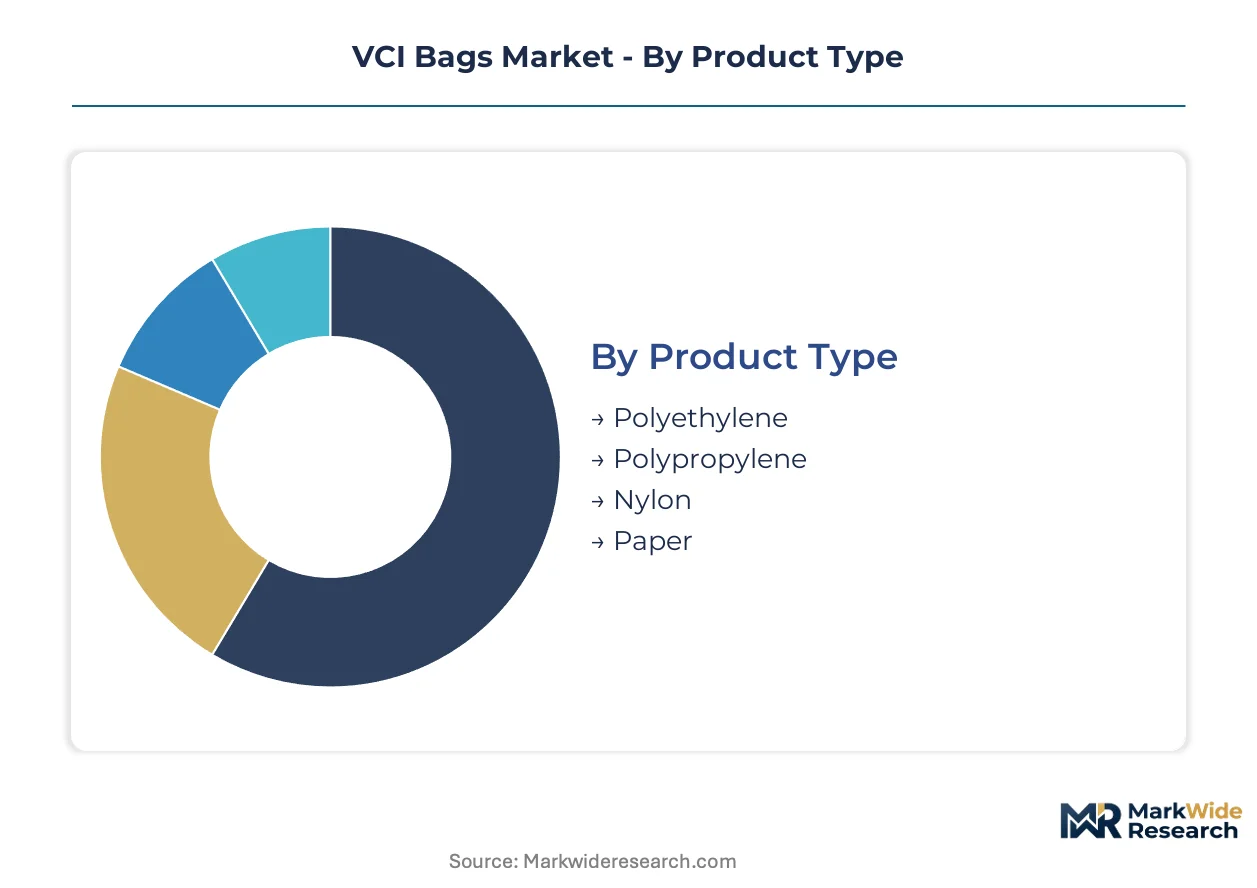
VCI bag segmentation reveals how material chemistry, barrier performance, and access frequency map to distinct procurement budgets across defense, automotive, and precision manufacturing supply chains. Each dimension carries regulatory and automation implications that reshape supplier qualification requirements.
Product Type:
Polyethylene formulations dominate domestic automotive supply chains in Germany and the United States, while export-led demand for nylon and paper variants concentrates in electronics corridors serving Taiwan and South Korea.
- Polyethylene:Multi-layer coextruded films with vapor-phase inhibitor impregnation deliver moisture barrier properties and heat-seal compatibility for robotic packaging lines. Procurement concentrates at just-in-time supplier parks in Stuttgart and Wolfsburg where Daubert Cromwell anchors specification-grade supply.
- Nylon:Low-outgassing variants with total volatile organic compound constraints below 100 ppm address semiconductor capital equipment preservation protocols. Demand clusters at fabrication facilities in Taiwan and South Korea where electronics manufacturing tolerances exclude standard polyethylene alternatives.
- Polypropylene:Higher temperature resistance suits industrial equipment storage in oil and gas field operations across Texas and Alberta.
- Paper:Bio-based substrate compatibility aligns with EU Green Deal procurement preferences in France and the Netherlands.
Polyethylene commands the established base. The steepest expansion runs through nylon as semiconductor supply chains tighten contamination protocols.
Application:
Cost tier differentiation separates specification-grade aerospace and electronics applications from commodity metal protection volumes where price-per-thousand units drives sourcing decisions.
- Metal Protection:Ferrous and non-ferrous surface preservation during overseas shipment and extended inventory holding eliminates downstream cleaning operations. Automotive stamping plants in Michigan and Ohio specify these formats for in-process rust prevention across multi-week production buffers.
- Electronics:Precision component storage with outgassing constraints and electrostatic discharge compatibility commands 3-4x pricing multiples over standard industrial grades. Taiwan Semiconductor Manufacturing Company supply chain specifications propagate these requirements through capital equipment tiers.
- Automotive Parts:Powertrain and chassis component preservation follows OEM quality agreements with REACH-compliant formulation mandates eighteen months ahead of regulatory deadlines.
- Industrial Equipment:Heavy machinery preservation in oil and gas field services tolerates higher vapor-phase inhibitor concentrations and shorter shelf-life certifications.
Metal protection captures volume leadership. Electronics applications deliver margin expansion as fabrication node advances tighten contamination thresholds.
End User:
Customer type stratification reflects procurement sophistication, with defense primes and tier-one automotive suppliers imposing multi-year inhibitor supply agreements while oil and gas operators rely on spot-market purchasing.
- Aerospace:MIL-PRF-3420H qualification requirements for weapons system preservation create limited vendor pools with sole-source contract potential. Maintenance operations in Germany, France, and the United States specify zipper-configured formats for repeated component access.
- Electronics Manufacturing:Semiconductor fabrication facilities and capital equipment OEMs propagate nylon VCI specifications through multi-tier supply chains serving Taiwan and South Korea.
- Automotive:Tier-one suppliers in Germany's automotive corridor negotiate thirty-six-month inhibitor supply agreements with volume commitments and fixed-price escalators.
- Oil & Gas:Field service operations in Texas and Alberta prioritize cost efficiency over specification-grade certification for non-critical equipment preservation.
Automotive anchors procurement volume. Aerospace delivers the steepest pricing premiums through military-grade qualification barriers.
Packaging Type:
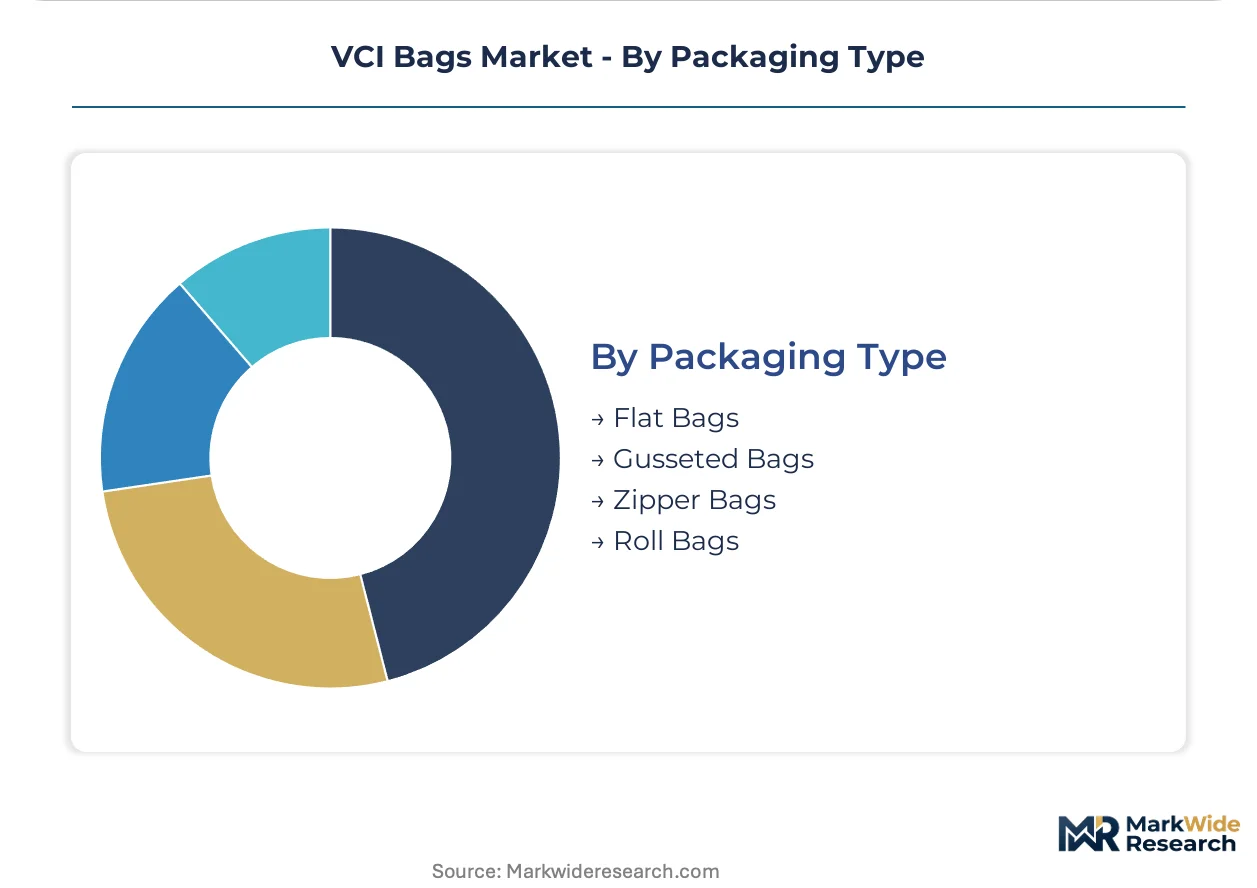
Volume concentration favors flat bag formats compatible with legacy heat-seal equipment, while automation-ready and repeated-access configurations capture fastest share gains in precision manufacturing segments.
- Flat Bags:Mature workhorse format dominates polyethylene VCI production with heat-seal compatibility for manual and semi-automated packaging lines. German automotive supplier parks maintain highest deployment density.
- Zipper Bags:Reclosable configurations eliminate re-bagging labor in aerospace MRO operations where technicians access protected components multiple times during maintenance cycles. Demand concentrates at Lufthansa Technik and Delta TechOps facilities.
- Gusseted Bags:Expanded capacity suits irregular industrial equipment geometries in oil and gas field services.
- Roll Bags:Continuous formats enable custom cut-to-length deployment at high-volume metal processing facilities.
Flat bags retain volume leadership. Zipper configurations climb fastest as aerospace MRO operations standardize repeated-access protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated film production and inhibitor compounding capabilities concentrate among German and Austrian polymer processors, creating geographic chokepoints that shape procurement patterns across automotive and aerospace supply chains.
Germany
Just-in-time automotive supplier parks in Stuttgart and Wolfsburg specify polyethylene VCI bags compatible with robotic heat-seal automation. REACH registration requirements above 100-ton annual volumes accelerate consolidation among inhibitor blenders with captive analytical labs. The automotive corridor stretching from Munich to Hamburg anchors specification-grade procurement with thirty-six-month supply agreements.
United States
EPA enforcement discretion letters under the Toxic Substances Control Act constrain nitrite-based inhibitor shipments into California and Northeastern states. Automotive OEMs in Michigan and Ohio insert REACH-compliant formulation requirements into supplier quality agreements eighteen months ahead of federal mandates. Defense contractors specify MIL-PRF-3420H qualified packaging for weapons system preservation with limited vendor pools.
China
Multi-layer coextrusion capacity expansion targets export demand for vapor-retentive films serving electronics manufacturing supply chains. The country's national chemical regulator enforces substance registration thresholds that parallel REACH frameworks for imported inhibitor active ingredients. Yangtze River Delta fabrication facilities propagate nylon VCI specifications with outgassing constraints below 100 ppm total volatile organic compounds.
South Korea
Semiconductor capital equipment OEMs drive demand for low-outgassing nylon variants serving Taiwan and domestic fabrication facilities. The national chemical safety agency maintains substance dossier requirements for vapor-phase inhibitor imports above specified tonnage thresholds. Busan-Ulsan industrial clusters concentrate electronics manufacturing procurement with contamination thresholds tightening at each fabrication node advance.
France
Aerospace MRO operations at Paris-region maintenance facilities specify zipper-configured VCI bags for repeated component access during maintenance cycles. EU F-Gas Regulation restrictions eliminate fluorinated barrier layers without fully qualified drop-in replacements certified to ASTM D1748. The Île-de-France aerospace cluster standardizes specification-grade procurement through Lufthansa Technik and Air France Industries protocols.
VCI Bags Market Competitive Environment
Concentration sits with mid-cap compounders possessing captive film production and in-house ASTM D1748 testing infrastructure. The supplier base fragments between integrated manufacturers controlling multi-layer coextrusion and toll-coating-dependent converters facing single-source vulnerability for vapor-retentive barrier layers. Three archetypes dominate: specification-grade defense contractors, automotive-tier suppliers with robotic packaging line compatibility, and bio-based chemistry specialists pursuing EU Green Deal procurement preferences. Competitive moves center on backward integration into inhibitor synthesis and strategic partnerships with polymer processors to secure coextrusion capacity.
Among North American specification-grade suppliers, Cortec Corporation, Daubert Cromwell, and Northern Technologies International Corporation occupy distinct positioning vectors. Cortec exemplifies the captive-chemistry archetype with customized inhibitor blend capabilities. Daubert Cromwell anchors automotive supply chain relationships through specification-grade polyethylene and polypropylene formats. Northern Technologies International Corporation represents the bio-based differentiation path with plant-derived corrosion inhibitor systems. These three illustrate how regulatory divergence between nitrite-restricted and nitrite-tolerant jurisdictions fragments competitive strategy across formulation portfolios.
| Leading Market Players |
|---|
| Northern Technologies International Corporation |
| Cortec Corporation |
| Daubert Cromwell |
| Armor Protective Packaging |
| Intertape Polymer Group |
| BASF SE |
| Aicello Corporation |
| American Plastics Company |
| Protective Packaging Corporation |
| Others |
Value Chain & Pricing Dynamics
Amine-carboxylate inhibitor chemistry replacing nitrite-based formulations simultaneously relocates compounding capacity toward REACH-registered European facilities and compresses margin structures for legacy blenders lacking captive synthesis infrastructure. This substitution dynamic concentrates pricing power among German and Austrian polymer processors while fragmenting procurement relationships across automotive and aerospace buyer desks.
Pricing Analysis
REACH registration thresholds dictate the pricing tier structure across the VCI bags market, separating specification-grade MIL-PRF-3420H qualified suppliers from commodity converters. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and vapor-phase inhibitor concentration, with aerospace MRO procurement showing lowest price sensitivity and oil field services highest. Cost compression in nitrite-reliant tiers is intensifying because automotive OEMs in Michigan and Ohio are inserting REACH-compliant requirements eighteen months ahead of mandates. Electronics manufacturing buyers in Taiwan and South Korea tolerate 3-4x multiples for low-outgassing nylon variants with TVOC constraints below 100 ppm.
Supply Chain Analysis
Dual-formulation inventory requirements are extending lead times for North American converters dependent on toll-coating arrangements with German and Austrian polymer processors. Geographic supply concentration centers on Germany, Austria, and China, with multi-layer coextrusion capacity for vapor-retentive films drawing from sodium nitrite, amine-carboxylate precursors, and bio-based agricultural waste streams. Single-source vulnerability runs through fluorinated barrier layer phase-outs under EU F-Gas Regulation restrictions. Distribution runs through specification-grade defense primes and tier-one automotive suppliers with thirty-six-month inhibitor supply agreements replacing quarterly spot tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VCI bags market sits at a platform-economics inflection where inhibitor formulation standardization across REACH and EPA jurisdictions is creating interoperability premiums for suppliers with dual-registered chemistry portfolios. This ecosystem shift favors integrated compounders over toll-coating-dependent converters.
For Market Incumbents: Consolidate backward integration into amine-carboxylate synthesis and captive multi-layer coextrusion capacity to defend against nitrite-free formulation margin compression. Prioritize ASTM D1748 testing infrastructure investment to compress qualification timelines for aerospace MRO procurement. Lock in thirty-six-month supply agreements with German automotive tier-one suppliers before REACH registration deadlines consolidate buyer power among mid-cap compounders with captive analytical labs. For New Entrants and Emerging Players: Bio-based corrosion inhibitor chemistry from agricultural waste streams represents the most penetrable white-space target, aligning with EU Green Deal procurement preferences and California SB 54 extended producer responsibility frameworks. Target semiconductor capital equipment supply chains in Taiwan and South Korea with low-outgassing nylon variants where contamination thresholds tighten at each fabrication node advance. Deploy direct technical sales to fabrication facility maintenance directors bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap compounders with captive film production and in-house certification infrastructure. Long-term viability over the next decade hinges on regulatory divergence between nitrite-restricted and nitrite-tolerant jurisdictions creating dual-formulation portfolio requirements. Watch for EPA enforcement discretion letters constraining nitrite shipments into California and Northeastern states as the inflection signal for accelerated amine-carboxylate platform conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Inhibitor Synthesis | Captive amine-carboxylate production insulates margin from sodium nitrite feedstock volatility at German compounders. |
| ASTM D1748 Testing Infrastructure Investment | In-house humidity chamber capacity bypasses six-month third-party laboratory backlogs freezing competitor R&D pipelines. |
| Long-term Inhibitor Supply Agreements | Thirty-six-month contracts with fixed-price escalators lock in volume commitments from Stuttgart and Wolfsburg automotive supplier parks. |
| Plant-Derived Inhibitor Platform Development | Bio-based chemistry from agricultural waste streams captures EU Green Deal procurement preferences in France and the Netherlands. |
| Strategic Partnership with Polymer Processors | Coextrusion capacity commitments with German and Austrian processors eliminate single-source vulnerability for North American converters. |
Study Parameters
Operator-level perspectives from plant managers at polymer processing facilities, procurement leads at automotive tier-one suppliers, technical R&D directors at inhibitor blenders, and maintenance directors at aerospace MRO facilities anchored the qualitative base. Primary interview findings triangulated against customs and trade data, SEC 10-K filings from packaging material suppliers, ACC and Cefic chemical industry reports, and ASTM International certification databases. Bottom-up volume estimates from individual product format deployments reconciled with top-down market sizing across material chemistry, barrier performance, and end-use application dimensions.
Sensitivity analysis tested forecast robustness across regulatory scenario variants including accelerated EPA nitrite restrictions and delayed REACH registration enforcement. Segmentation modeling captured polyethylene, nylon, polypropylene, and paper substrate variants; flat, zipper, gusseted, and roll packaging formats; and metal protection, electronics, automotive parts, and industrial equipment applications. CAGRs derived from regression analysis of historical volume trajectories adjusted for automation adoption curves in German automotive supplier parks and semiconductor fabrication node advances in Taiwan and South Korea. Price elasticity assumptions incorporated thirty-six-month contract duration shifts and dual-formulation inventory carrying cost impacts.
Forecasts assume regulatory continuity in REACH-registered European jurisdictions and EPA-enforced U.S. state-level nitrite restrictions; material policy shifts including accelerated fluorinated polymer phase-outs or harmonized global inhibitor standards would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Food Grade Bottles Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Dosage Cups Market
Packaging Containers
Bottles Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Shipping Mailers Market