
 Non-Corrugated Boxes Market | 2026-2036
Non-Corrugated Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Corrugated Boxes Market Analytics
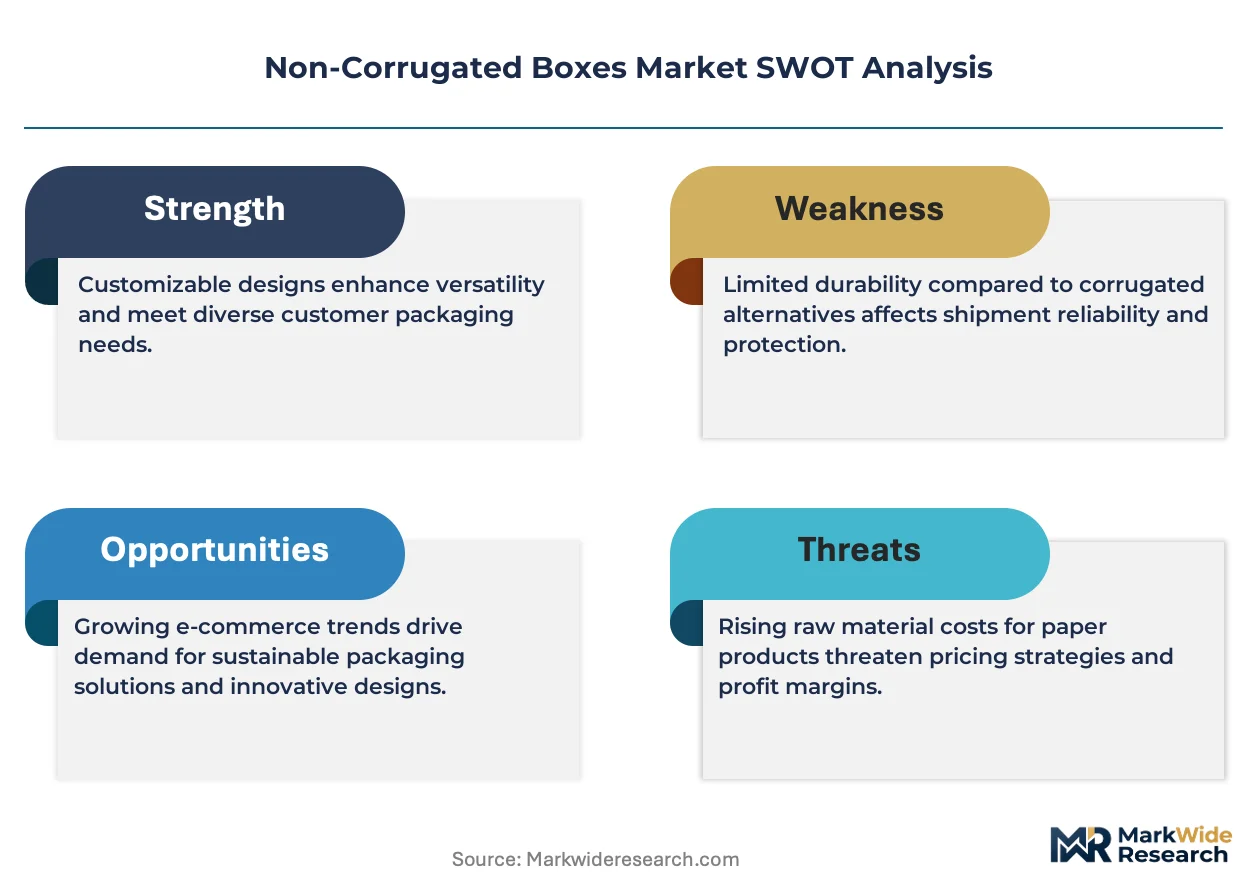
Asset-light leasing models for converting equipment is reconfiguring competitive entry barriers across the non-corrugated boxes landscape. DS Smith leverages its European recycled fiber network to sustain cost advantages in folding carton production. Mondi anchors its position through integrated kraft paper operations that feed rigid box lines. International Paper Co. competes via scale advantages in North American paperboard supply.
Non-corrugated boxes are paper-based or alternative-material containers manufactured without fluted medium, typically constructed from solid bleached sulfate board or recycled paperboard with calipers ranging from 12 to 30 points, serving primary functions in product protection, shelf presentation, and supply-chain handling. Folding boxes dominate volume flows in food and beverage applications where run lengths and graphic reproduction requirements favor efficient die-cutting and gluing operations. Rigid boxes concentrate margin pools in cosmetics and electronics segments where unboxing experience and structural permanence command price premiums. Eco-friendly materials are gaining fastest share within the material dimension as brand owners implement plastic-reduction commitments.
EPA guidelines on recycled content thresholds shape fiber sourcing decisions for U.S. producers, while EU REACH and F-Gas Regulation indirectly pressure substrate choices through chemical compliance cascades. FDA food-contact standards govern paperboard selection for folding boxes in direct food applications, creating certification moats for qualified suppliers. Stakeholders must monitor how extended producer responsibility schemes in multiple jurisdictions alter cost allocation between converters and brand owners.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to reengineer material recovery systems and recalibrate fiber sourcing strategies across European operations.
Growth Catalysts
- Electronics Premiumization:Device manufacturers in South Korea and Taiwan are specifying rigid paperboard enclosures for flagship product launches, creating specification pull for high-caliper folding carton grades.
- REACH Chemical Compliance Cascades:ECHA substance restrictions on coatings and adhesives are accelerating substitution toward bio-based barrier technologies in food-contact applications.
- German Automotive Cluster Demand:Component suppliers near Stuttgart and Wolfsburg require specialized folding box formats with integrated anti-static properties for precision parts logistics.
Market Restraints
- Recycled Fiber Cost Volatility:OCC price swings in North American spot markets compress converter margins during quarterly contract renegotiations with brand owners.
- Swedish Pulp Supply Concentration:Three integrated producers control over sixty percent of European kraftliner feedstock for rigid box substrates, creating bottleneck risk.
- Plastic Flexible Substitution Threat:Stand-up pouches with metallized films are capturing shelf-stable food volume that previously flowed to folding cartons.
Strategic Opportunities
- Indian Pharmaceutical Cold Chain:Temperature-stable rigid box formats for biologics distribution remain underpenetrated in Mumbai and Hyderabad manufacturing corridors.
- FDA Food-Contact Certification Moats:Qualified suppliers holding current good manufacturing practice approvals can capture share from uncertified competitors in direct-food segments.
- Digital Print-Diecut Convergence:Hybrid production lines integrating inkjet decoration with laser finishing are collapsing minimum order quantities for cosmetic sampling programs.
Industry Challenges
- Structural Package Engineer Talent Scarcity:Converters struggle to hire designers fluent in both CAD-based die development and paperboard stress modeling software.
- Extended Producer Responsibility Integration:Brand owners are pushing compliance cost allocation disputes onto converters without clear contractual frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Corrugated Boxes Market |
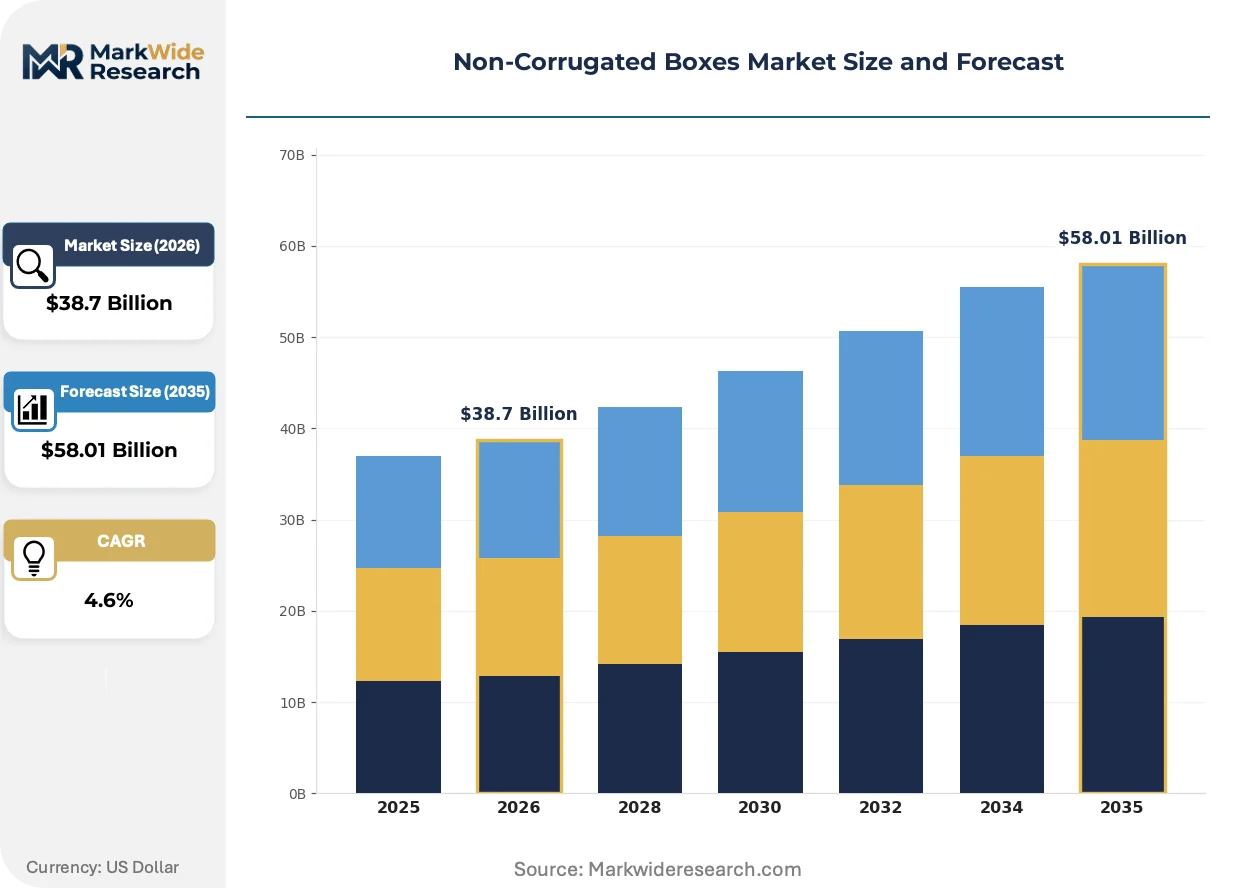
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Boxes, Folding Boxes, Sleeve Boxes, Wood Boxes Material: Paperboard, Plastic, Eco-friendly Materials, Aluminum End User: Electronics, Cosmetics, Food & Beverages, Apparel Packaging Type: Custom Packaging, Standard Packaging, Retail Packaging, Wholesale Packaging |
| Companies Covered | Stora Enso, DS Smith, International Paper Co., Sonoco, Packaging Corporation of America, Smurfit Kappa Group, Mondi, Pactiv Evergreen Inc., WestRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Corrugated Boxes Market Evolving Landscape
Material science advances and regulatory compliance architectures are compressing traditional production paradigms while opening specification opportunities in premium segments.
Barrier-coated molded fiber is hybridizing conventional rigid box construction by replacing plastic inserts with cellulose-based cushioning structures. Cosmetics houses in France and Italy are qualifying these formats for fragrance and skincare gift sets. The technology is hybridizing cost structures across primary and secondary packaging tiers, enabling converters to capture value previously lost to injection-molded suppliers.
EPA recycled content thresholds under the Resource Conservation and Recovery Act are tightening fiber sourcing requirements for U.S. folding carton producers. Domestic mills are reconfiguring pulping lines to handle higher contamination loads from post-consumer streams. Food and beverage applications face the steepest compliance ramps, with dairy and frozen meal segments accelerating certification timelines.
Brand owners are consolidating specification authority into centralized procurement functions, collapsing legacy regional buying structures. Tier-one CPG conglomerates are mandating global substrate standards across their converting portfolios. This concentration is most visible in North American and Western European operations, where sustainability scorecards now override local supplier relationships in annual vendor reviews.
Non-Corrugated Boxes Market Segmentation
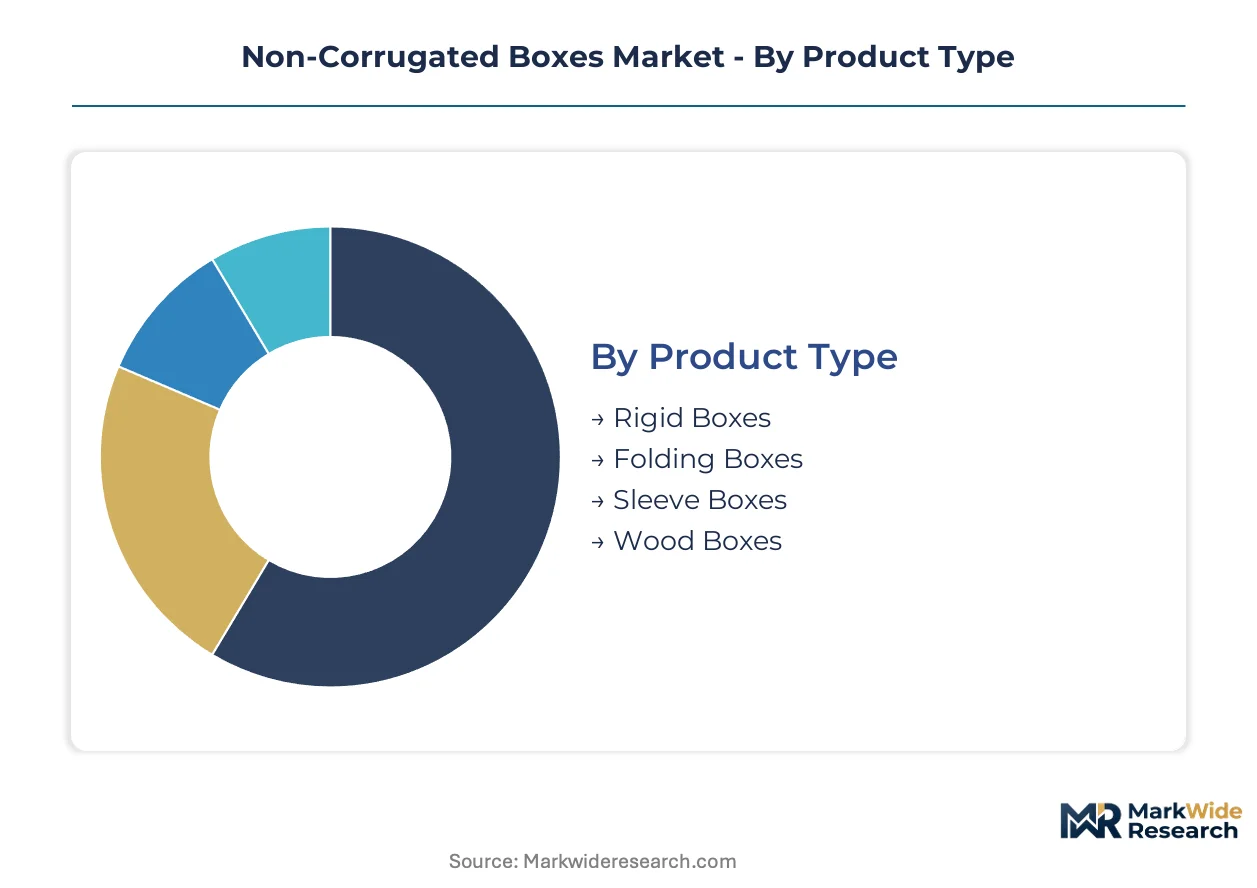
Segmentation in non-corrugated boxes reveals how substrate choice, structural format, and end-use specification create distinct margin pools and technical requirements. Converters configure equipment and fiber sourcing around these boundaries to defend position against specialized competitors.
Product Type:
Use-case spectrum spans protective logistics to premium unboxing experiences, with structural permanence and graphic reproduction quality as the primary differentiators.
- Folding Boxes:Manufactured from solid bleached sulfate or recycled paperboard with calipers of 12-24 points, these formats deploy efficient die-cutting and gluing for high-volume food and beverage runs. Demand concentrates in German automotive component corridors near Stuttgart, where anti-static folding formats protect precision electronics during transit.
- Rigid Boxes:Constructed from thick paperboard wrapped around solid chipboard or greyboard cores, these structures deliver structural permanence for cosmetics and electronics unboxing experiences. South Korean device manufacturers specify high-caliper rigid enclosures for flagship smartphone launches, creating specification pull for European converters with advanced laminating capabilities.
- Sleeve Boxes:Open-ended paperboard wraps that slide over inner trays or products, reducing material consumption while maintaining shelf presence.
- Wood Boxes:Solid timber or engineered wood constructions serving archival, luxury spirits, and high-value gift applications where natural material authenticity commands price premiums.
The dominant share belongs to Folding Boxes, while Rigid Boxes is closing the gap fastest.
Material:
Cost tier segmentation separates commodity fiber from certified sustainable substrates, with regulatory compliance thresholds acting as the primary sorting mechanism.
- Eco-friendly Materials:Barrier-coated molded fiber and agricultural residue boards are displacing plastic inserts in French and Italian cosmetics gift sets. ECHA substance restrictions on conventional coatings accelerate bio-based barrier qualification timelines for food-contact applications.
- Paperboard:Solid bleached sulfate and recycled folding boxboard constitute the volume foundation, with EPA recycled content thresholds under RCRA tightening fiber sourcing requirements for U.S. dairy and frozen meal segments.
- Plastic:PET and PP formats persist in moisture-sensitive pharmaceutical and personal care applications where fiber barriers remain technically constrained.
- Aluminum:Lightweight metal laminates serve premium fragrance and confectionery segments requiring hermetic sealing and extended shelf stability.
Paperboard retains the volume base, though Eco-friendly Materials is expanding most quickly as brand owners implement plastic-reduction commitments.
End User:
Customer type segmentation maps structural complexity requirements against regulatory exposure, with FDA food-contact and EPA fiber rules creating divergent compliance burdens.
- Electronics:Rigid and folding carton formats for smartphones, tablets, and accessories demand anti-static properties and premium graphic reproduction. Taiwanese OEMs are consolidating specification authority into centralized procurement functions with global substrate standards.
- Cosmetics:Fragrance, skincare, and color cosmetics houses in France and Italy qualify barrier-coated molded fiber formats to replace injection-molded plastic inserts in gift sets.
- Food & Beverages:Folding cartons for dairy, frozen meals, and shelf-stable goods face the steepest EPA recycled content compliance ramps, with domestic mills reconfiguring pulping lines for higher post-consumer contamination loads.
- Apparel:E-commerce fulfillment formats prioritize dimensional efficiency and return-handling durability over premium unboxing experience.
Food & Beverages commands the installed capacity base, while Electronics is gaining share fastest through premiumization specifications.
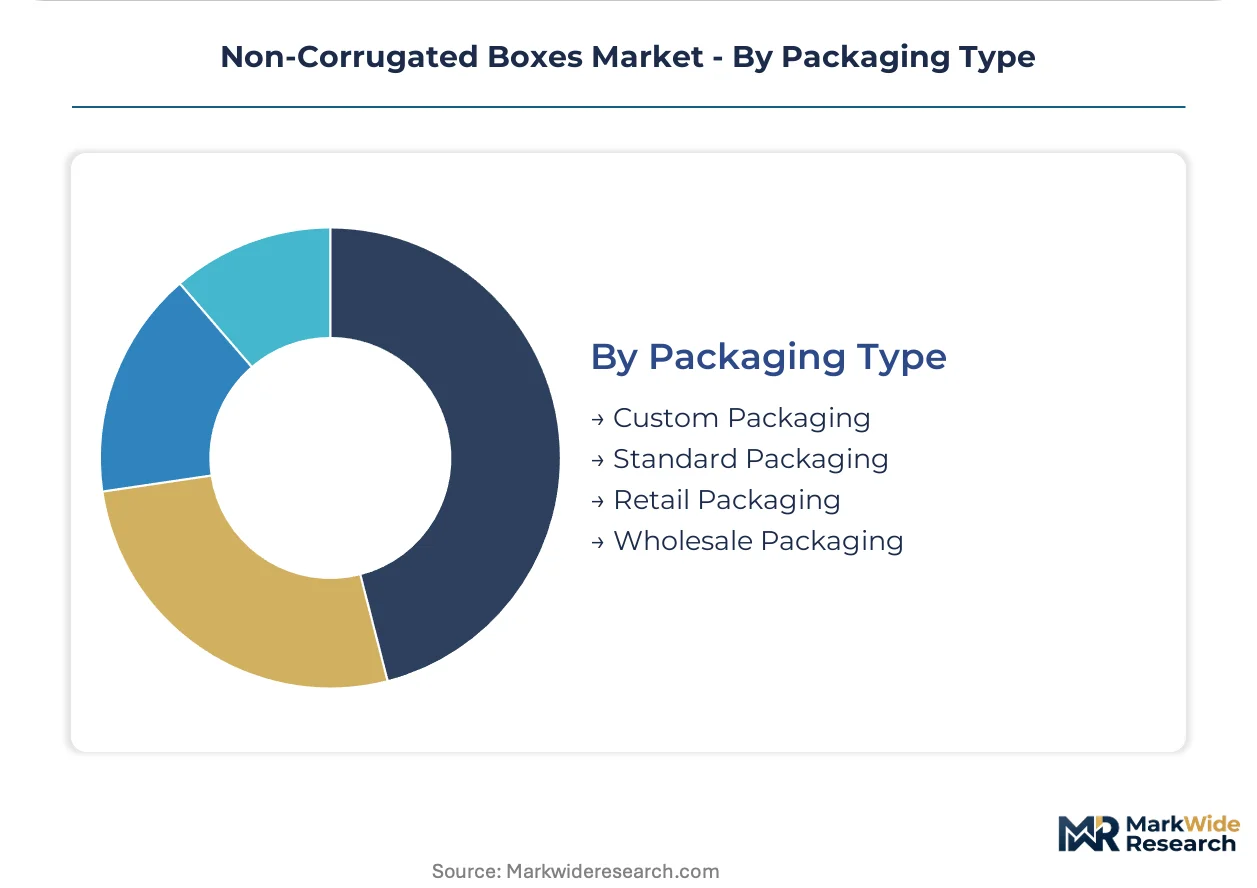
Packaging Type:
Volume-maturity segmentation separates long-run standardized formats from short-run digital production, with minimum order quantity collapse enabled by hybrid print-diecut lines.
- Custom Packaging:Short-run, brand-specific formats with unique die lines and variable data printing for cosmetic sampling programs and limited-edition product launches.
- Standard Packaging:Pre-tooled folding carton formats with rapid changeover capabilities serving high-volume CPG segments with regional graphic versioning.
- Retail Packaging:Shelf-ready designs with integrated display features and retail-compliant barcoding for direct-to-shelf merchandising.
- Wholesale Packaging:Bulk-oriented formats prioritizing cube efficiency and pallet optimization over individual unit presentation.
Standard Packaging maintains the throughput foundation, while Custom Packaging is climbing the fastest as digital print-diecut convergence collapses economic order quantities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in fiber-based packaging are reshaping regional manufacturing footprints. Countries with surplus recycled pulp capacity command pricing leverage in cross-border folding carton trade. Domestic sourcing mandates in major economies are fragmenting previously integrated supply chains.
Germany
Automotive component suppliers near Stuttgart and Wolfsburg drive specialized folding box demand with anti-static specifications for precision electronics logistics. The EU Packaging and Packaging Waste Regulation forces converters near Mannheim to reengineer material recovery systems. The Baden-Württemberg industrial corridor concentrates rigid box innovation for premium device launches.
United States
Food and beverage brand owners in Wisconsin and Pennsylvania accelerate EPA recycled content compliance for dairy and frozen meal cartons. The Resource Conservation and Recovery Act tightens fiber sourcing thresholds for domestic mills. The Midwest paperboard belt around Chicago reconfigures pulping lines for higher post-consumer contamination loads.
South Korea
Electronics OEMs in Seoul and Suwon specify rigid paperboard enclosures for flagship smartphone launches. The national chemical regulator enforces coating substance restrictions that accelerate bio-based barrier qualification. The Gyeonggi-do manufacturing cluster pulls high-caliper folding carton grades from European converters.
France
Cosmetics houses in Paris and Grasse qualify barrier-coated molded fiber formats for fragrance and skincare gift sets. ECHA substance restrictions on conventional coatings drive substitution toward cellulose-based cushioning structures. The Provence-Alpes-Côte d'Azur region anchors luxury packaging specification authority for global beauty brands.
India
Pharmaceutical manufacturers in Mumbai and Hyderabad seek temperature-stable rigid box formats for biologics cold chain distribution. The Food Safety and Standards Authority of India tightens food-contact packaging standards for export-oriented converters. The Maharashtra pharmaceutical corridor remains underpenetrated for specialized temperature-controlled formats.
Non-Corrugated Boxes Market Competitive Landscape
On the supply side, the industry is consolidating around integrated fiber-to-box operators with captive pulp supply. Tier-one converters leverage scale advantages in North American and European paperboard supply. Three strategic archetypes dominate: integrated forest products conglomerates with kraftliner feedstock control, specialized folding carton converters with FDA food-contact certification moats, and rigid box specialists with advanced laminating capabilities. Competitive moves center on backward integration into recycled fiber networks and geographic expansion through asset-light leasing models for converting equipment.
Within the integrated conglomerate tier, Stora Enso and Mondi exemplify fiber-to-box positioning through European recycled pulp and kraft paper operations. DS Smith occupies a position among converters leveraging continental fiber networks for folding carton cost advantages. These three entities represent distinct geographic anchors—Nordic, Anglo-Austrian, and British respectively—within the competitive structure.
| Leading Market Players |
|---|
| Stora Enso |
| DS Smith |
| International Paper Co. |
| Sonoco |
| Packaging Corporation of America |
| Smurfit Kappa Group |
| Mondi |
| Pactiv Evergreen Inc. |
| WestRock |
| Others |
Value Network & Pricing Analysis
Undercapacity in Swedish kraft pulp operations is tightening substrate availability for rigid box manufacturers and amplifying pricing leverage among integrated fiber suppliers. This utilization squeeze cascades through converter margins and forces brand owners into longer-term offtake commitments to secure caliper-grade paperboard.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments across quarterly renegotiation cycles. Three-tier pricing structure across premium FDA-certified, standard food-contact, and economy non-food grades separates qualified suppliers from commodity converters. Cost compression in economy folding carton tiers is intensifying because OCC spot volatility compresses margins during contract resets. Automotive component suppliers near Stuttgart show least price sensitivity due to anti-static specification requirements, while mass-market food brands exhibit highest sensitivity to substrate cost swings.
Supply Chain Analysis
DS Smith, Mondi, and Stora Enso hold dominant converting capacity across European rigid and folding box lines. Supply concentrates in Germany, Sweden, and Finland for kraftliner feedstock, with U.S. Midwest mills serving North American folding carton demand. Raw material dependencies rest on OCC recovered fiber, solid bleached sulfate pulp, and bio-based barrier coatings. Single-source vulnerability runs through Swedish pulp concentration where three integrated producers control majority kraftliner supply. Distribution runs through brand-owner centralized procurement functions that have collapsed legacy regional buying structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural package engineer talent scarcity constrains converter expansion and creates acquisition premiums for firms with CAD-die development capabilities. This capability gap justifies targeted capability-building investments across the competitive landscape.
For Market Incumbents: Entrench FDA food-contact certification moats by accelerating cGMP compliance investments ahead of EPA recycled content threshold enforcement. Capture rigid box laminating capacity in the Gyeonggi-do corridor before South Korean electronics OEMs consolidate specification authority. Prioritize backward integration into post-consumer fiber networks to offset OCC price volatility exposure.
For New Entrants and Emerging Players: Temperature-stable rigid box formats for Indian pharmaceutical cold chains represent the most penetrable entry point given underpenetrated biologics distribution infrastructure in Mumbai and Hyderabad. Digital print-diecut hybrid production lines for cosmetic sampling programs offer second white-space target with collapsed minimum order quantities. Lead with asset-light equipment leasing models to bypass capital-intensive converting infrastructure barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among FDA-certified folding carton specialists with multi-year CPG supply agreements. Long-term viability over the next decade hinges on bio-based barrier technology positioning ahead of ECHA coating restrictions. Target acquisition archetype: mid-cap converters with captive recycled fiber networks and existing pharmaceutical certification. Monitor ECHA substance restriction timelines as inflection signal for bio-based barrier adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Networks | DS Smith leverages continental OCC sourcing to sustain folding carton cost advantages against spot-market exposed competitors. |
| FDA Food-Contact Certification Investment | cGMP approval creates contractual moats in dairy and frozen meal segments where EPA thresholds tighten fastest. |
| Digital Print-Diecut Hybrid Line Deployment | Laser finishing integration collapses economic order quantities for French and Italian cosmetics sampling programs. |
| Bio-Based Barrier Technology Qualification | ECHA coating restrictions accelerate substitution timelines for food-contact applications in European operations. |
| Asset-Light Equipment Leasing Expansion | Converting capacity deployment without capital intensity enables rapid geographic entry into Indian pharmaceutical corridors. |
Research Methodology
A standing panel of folding carton plant managers, brand-owner packaging procurement directors, rigid box structural engineers, and FDA regulatory compliance specialists provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from EPA RCRA filings, ECHA substance restriction databases, EU Packaging and Packaging Waste Regulation impact assessments, and SEC 10-K disclosures from integrated paperboard producers. Bottom-up volume modeling across substrate grades and end-use segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing around regulatory enforcement timelines and fiber cost volatility bounds framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, material substrate, end-use industry, packaging format tier, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy inflection points and technology substitution curves. Industry-specific forecast inputs incorporated ECHA coating restriction phase-in schedules and EPA recycled content compliance ramps.
Practitioners should monitor ECHA substance restriction enforcement, EPA threshold compliance deadlines, and Swedish pulp capacity utilization for early signals of forecast revision. Forecasts reflect assumptions about regulatory implementation pace and fiber network reconfiguration timelines. Quarterly review of OCC spot price volatility, FDA certification backlog durations, and bio-based barrier qualification rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Telescope Box Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Insulated Icebox Market
Packaging Containers
Bottles Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Snap Single Dose Dispensers Market
Packaging Containers
Pillow Pack Packaging Market