
 Wide Mouth Bottles Market | 2026-2036
Wide Mouth Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Wide Mouth Bottles Market Analytics
Outdoor enthusiasts and fitness consumers is reorganizing demand patterns across the wide mouth bottles landscape. Hydro Flask leverages premium insulation technology to command higher price tiers in the outdoor recreation channel. Berry Global sustains manufacturing scale across multiple polymer platforms for private-label and branded programs. Nalgene anchors the scientific and educational segments with polycarbonate durability standards.
Wide mouth bottles feature expanded aperture diameters, typically 53mm to 63mm, enabling direct filling with ice cubes, powders, and thick liquids while accommodating brush cleaning. Stainless steel variants with double-wall vacuum construction dominate premium outdoor applications, while polyethylene terephthalate and high-density polyethylene grades lead mass-market beverage and food storage segments. Glass wide mouth containers retain strength in medical and laboratory use where chemical inertness outweighs fragility concerns. Closure innovation concentrates in screw cap and flip top mechanisms, with pump dispenser formats gaining traction in personal care crossover applications.
The US FDA governs food-contact material compliance for polymer-based wide mouth bottles, while the EU Green Deal and REACH framework restrict certain plasticizers and mandate recyclability disclosures. The EPA and state-level extended producer responsibility programs in California and Oregon are reshaping post-consumer collection infrastructure requirements. Stakeholders must monitor evolving material bans and recyclability mandates to align product development with compliance trajectories.
Market Dynamics
Material substitution pressures and circular economy mandates are compressing traditional polymer supply chains while elevating stainless steel and aluminum alternatives across outdoor and institutional channels.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases accelerates demand for vacuum-insulated stainless steel bottles as reusable alternatives to disposable packaging in European food service.
- Sports hydration infrastructure:Marathon and trail running event organizers mandate refill stations, creating captive demand for wide-mouth formats that accommodate rapid ice loading and electrolyte mixing.
- Double-wall vacuum construction:Thermal retention technology now achieves 24-hour cold performance at mid-tier price points, expanding addressable market beyond premium outdoor segments.
Market Restraints
- Stainless steel coil concentration:Cold-rolled 304-grade supply clusters in Chinese and Indonesian mills, exposing bottle fabricators to tariff volatility and alloy price swings.
- REACH plasticizer restrictions:ECHA scrutiny of phthalate and bisphenol alternatives limits flexible lid compound formulations, extending R&D timelines for European-market products.
- Glass fragility in logistics:Breakage rates during e-commerce fulfillment constrain direct-to-consumer glass bottle economics, favoring polymer and metal alternatives.
Strategic Opportunities
- California SB 54 implementation:Extended producer responsibility mandates for single-use packaging create institutional procurement incentives for reusable wide-mouth containers in municipal and university settings.
- Medical specimen crossover:Laboratory-grade polycarbonate durability standards translate to consumer wellness applications, opening pharmaceutical-adjacent distribution through clinical supply channels.
- Flip-top pump convergence:Personal care dispenser mechanisms adapted for thick nutritional supplements enable hybrid positioning between beverage and cosmeceutical retail placements.
Industry Challenges
- Multi-material separation:Stainless steel bodies bonded to polypropylene lids complicate end-of-life sorting, requiring design-for-recycling expertise that exceeds current supplier capabilities.
- Insulation certification timelines:Third-party thermal performance verification for vacuum-sealed vessels extends 14-18 weeks, delaying seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wide Mouth Bottles Market |
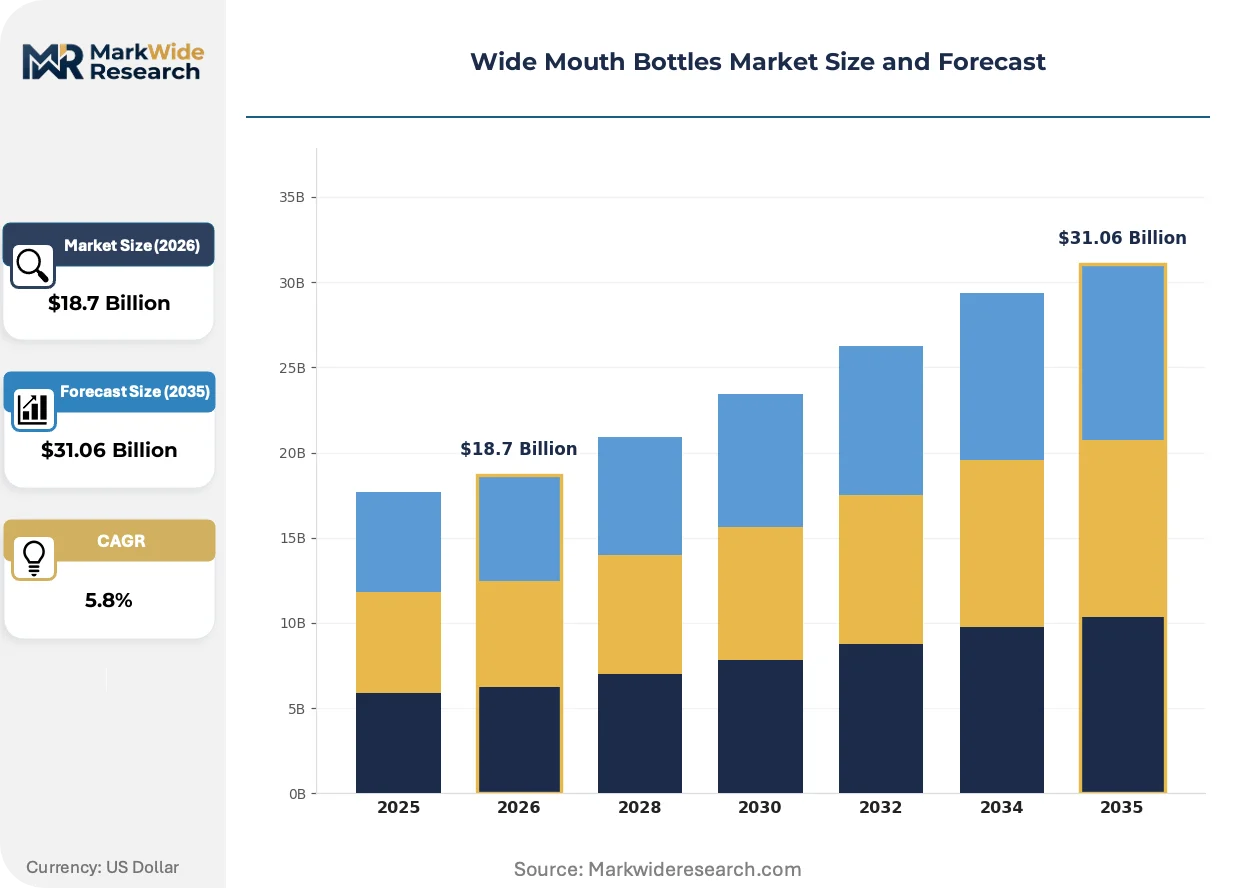
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Stainless Steel, Aluminum Application: Food Storage, Beverages, Outdoor Activities, Medical Use Size: 500ml, 1L, 2L, 3L Closure Type: Screw Cap, Flip Top, Pump Dispenser, Spout |
| Companies Covered | Thermos LLC, Hydro Flask, Contigo, Nalgene, Klean Kanteen, Amcor, Berry Global, CamelBak, Tupperware Brands Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wide Mouth Bottles Market Evolving Landscape
Active thermal management and modular closure systems are displacing static vessel design, while regulatory disclosure requirements reshape material selection protocols across manufacturing footprints.
Vacuum insulation technology is miniaturizing. Double-wall construction now achieves sub-12mm wall thickness in 32-ounce capacities, matching thermal performance of bulkier predecessors. Ultralight backpacking and fastpacking segments adopt these slim-profile vessels for weight-critical applications. The format compression is enabling premium feature sets at standard-tier price positioning.
REACH framework amendments expand substance-of-very-high-concern candidate list scrutiny to polymer stabilizers and colorants used in food-contact bottles. Manufacturers face reformulation cycles for existing SKUs or market withdrawal decisions. German and French retailers enforce upstream compliance documentation, shifting supplier qualification burden to smaller private-label producers.
Direct-to-consumer subscription models for replacement parts—gaskets, caps, straws—extend product lifecycles and capture recurring revenue. Outdoor specialty retailers resist this disintermediation by bundling cleaning kits and accessories at point of sale. The channel tension is most acute in North American markets where Amazon-driven purchase patterns dominate repeat buying behavior.
Wide Mouth Bottles Market Segmentation
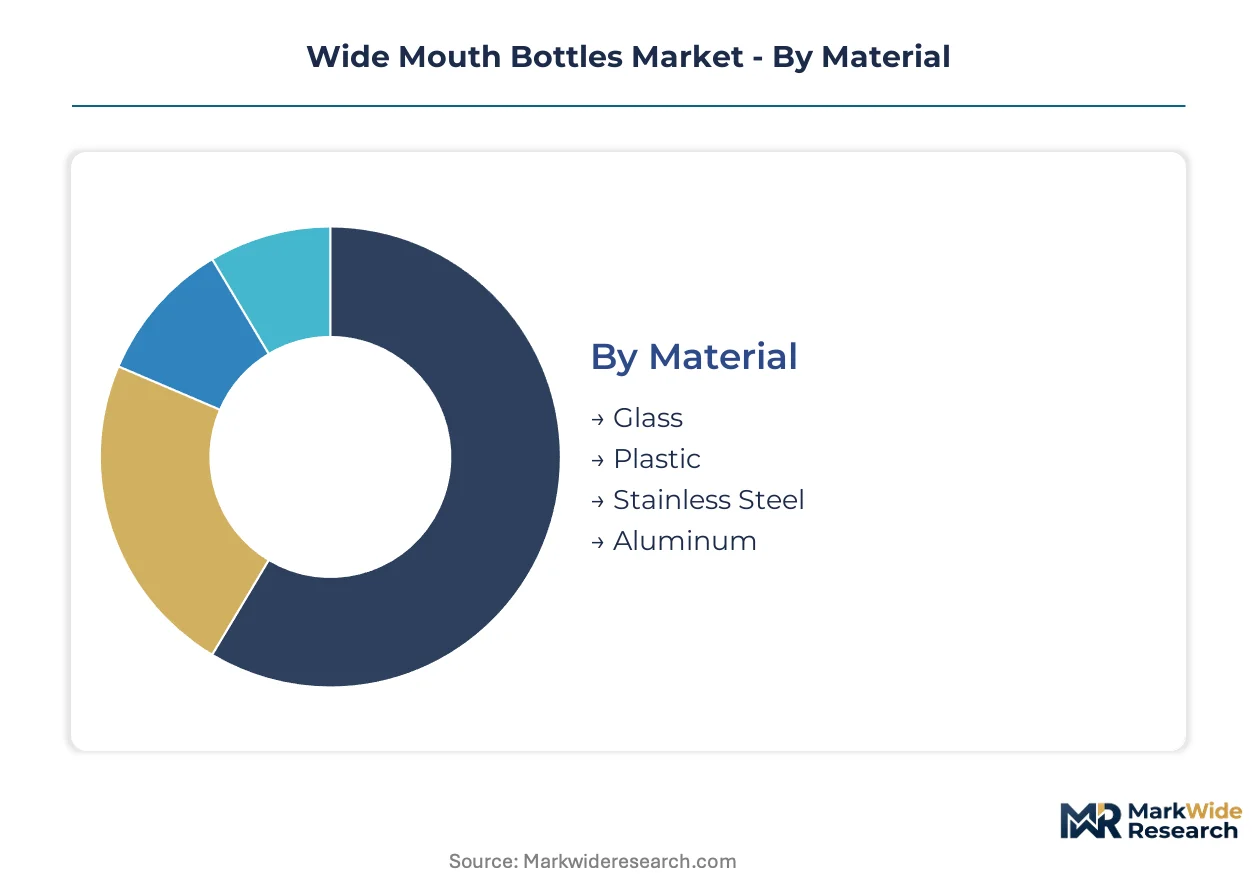
Wide mouth bottles serve divergent functional requirements across thermal performance, chemical resistance, and portability mandates. Material selection and aperture geometry determine channel placement and pricing architecture. Understanding segment boundaries clarifies where technical specifications translate into procurement premiums versus commodity substitution.
Material:
Domestic production clusters serve regional beverage and institutional markets, while export-oriented fabricators concentrate on premium stainless steel for North American and European outdoor channels.
- Stainless Steel:Double-wall vacuum construction achieves thermal retention across 12-24 hour windows. Demand concentrates in Germany, the United States, and Japan where marathon infrastructure and backcountry recreation drive replacement cycles for disposable alternatives.
- Plastic:Polyethylene terephthalate and high-density polyethylene grades dominate mass-market beverage and food storage with sub-dollar unit economics. Export volumes from Chinese and Vietnamese converters supply private-label programs across European retail.
- Glass:Borosilicate and soda-lime compositions serve medical specimen and laboratory applications where chemical inertness outweighs logistics fragility.
- Aluminum:Single-wall construction targets cycling and ultralight segments where weight minimization overrides thermal performance requirements.
Stainless steel commands the established base in premium outdoor channels. The steepest expansion runs through aluminum as cycling event sponsorships and bike-share integrations multiply touchpoints.
Application:
Cost tier stratification separates institutional procurement with multi-year replacement cycles from impulse retail purchases driven by seasonal outdoor participation.
- Outdoor Activities:Hydration systems for trail running, climbing, and paddle sports require rapid ice loading and electrolyte mixing compatibility. German retailers and US specialty chains enforce thermal performance certification as a listing prerequisite.
- Beverages:Reusable alternatives to single-use packaging dominate municipal procurement in California and Oregon under extended producer responsibility mandates.
- Food Storage:Wide aperture formats accommodate bulk dry goods and meal prep workflows in urban household segments.
- Medical Use:Polycarbonate durability standards from laboratory specimen containers translate to consumer wellness applications through clinical supply distribution.
Outdoor activities command the established base with the highest per-unit pricing. The steepest expansion runs through medical use as pharmaceutical-adjacent channels open wellness crossover opportunities.
Size:
Volume segmentation tracks hydration science evolution and portability constraints across activity intensity levels.
- 1L:The utility standard for daily commuting and gym workflows balances capacity against bag compatibility. Demand concentrates in urban professional segments across US metropolitan markets.
- 500ml:Pocket-format vessels serve cycling and running segments where carrying system integration determines adoption.
- 2L:Base camp and group hydration formats target car camping and expedition contexts with stationary or vehicle-borne transport.
- 3L:Expedition-grade capacities for multi-day backcountry travel where resupply intervals exceed 24 hours.
1L formats command the established base across daily-use contexts. The steepest expansion runs through 500ml as running event participation and bike infrastructure investment accelerate in European and East Asian cities.
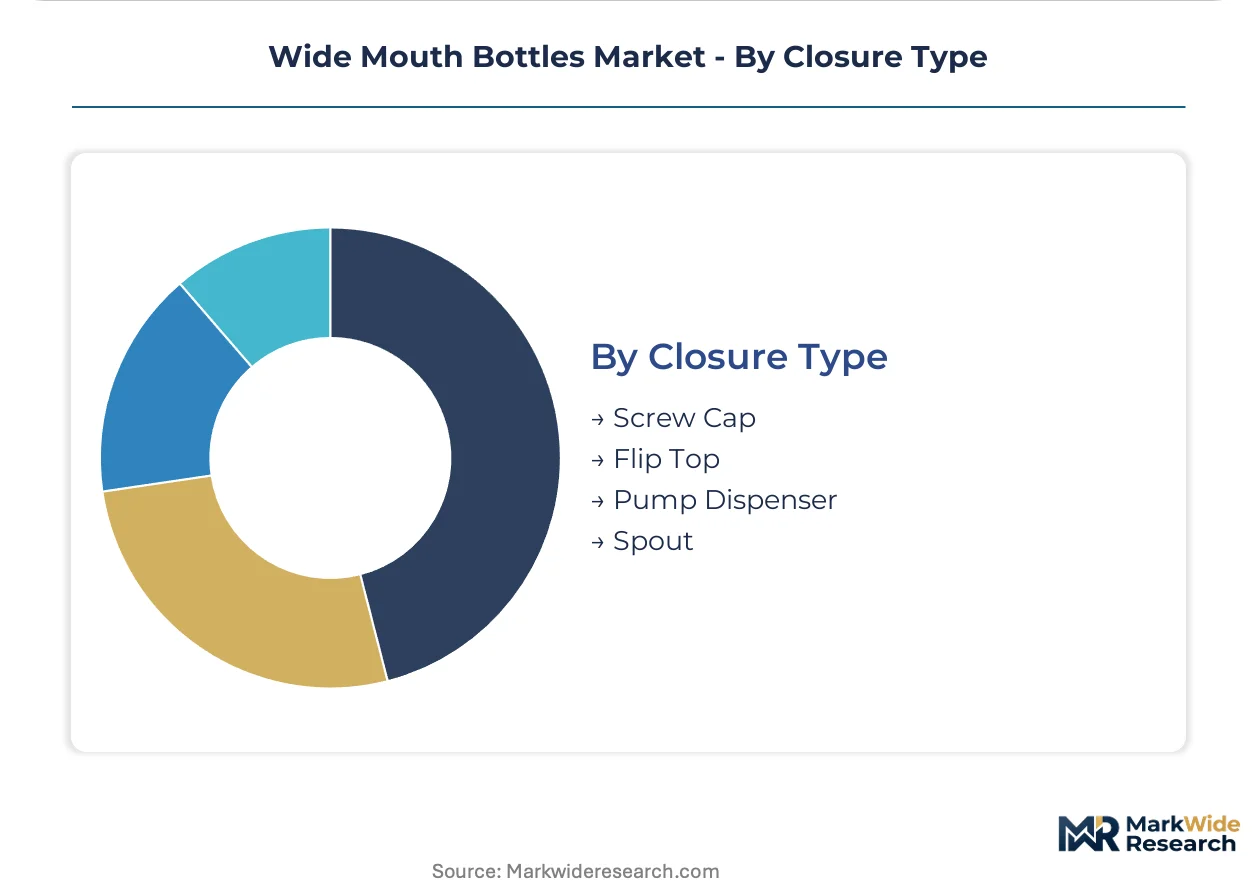
Closure Type:
Margin structure varies sharply between commodity screw mechanisms and patented pump or flip-top systems with replacement part revenue streams.
- Screw Cap:Threaded polypropylene or thermoplastic elastomer seals dominate food storage and basic hydration with universal interchangeability and sub-fifty-cent manufacturing cost.
- Flip Top:Hinged mechanisms enable single-handed operation during activity. German and US outdoor brands enforce drop-test durability standards that extend supplier qualification timelines.
- Pump Dispenser:Personal care mechanisms adapted for thick nutritional supplements enable hybrid positioning between beverage and cosmeceutical retail placements.
- Spout:Integrated drinking ports target youth and educational segments with spill reduction features.
Screw cap commands the established base with lowest unit cost and broadest compatibility. The steepest expansion runs through pump dispenser as supplement brands seek shelf differentiation in pharmacy and wellness channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for stainless steel coil imports serving vacuum-insulated bottle fabricators across Northern Germany. Rail corridors from Rotterdam and Antwerp feed polymer resin to Dutch and Belgian converters supplying private-label programs. These infrastructure assets position the Rhine-Ruhr and Randstad clusters as continental logistics hubs for reusable container trade.
United States
Marathon and trail running event infrastructure drives demand for rapid-fill hydration formats across California, Oregon, and Colorado. EPA and state-level extended producer responsibility programs in California and Oregon reshape municipal procurement toward reusable alternatives. Pacific Northwest manufacturing clusters near Portland and Seattle specialize in premium outdoor channel production.
Germany
Berlin and Hamburg municipal procurement mandates accelerate institutional adoption of wide-mouth reusable containers under EU Green Deal implementation. The EU F-Gas Regulation phases down fluorinated greenhouse gases, elevating vacuum-insulated stainless steel as food-service alternatives. Bavarian and North Rhine-Westphalia fabricators concentrate on thermal performance certification for outdoor specialty retail.
China
Cold-rolled 304-grade stainless steel coil production clusters in Jiangsu and Zhejiang provinces supply global bottle fabricators. GB standards and MIIT directives govern food-contact material compliance for polymer-based containers. Yangtze River Delta manufacturing zones export polyethylene terephthalate and high-density polyethylene grades to European and North American private-label programs.
Japan
METI efficiency standards and JIS certification requirements elevate thermal performance verification as a market entry barrier. Tokyo and Osaka metropolitan areas drive 1L format demand for daily commuting and urban professional hydration workflows. Kansai region fabricators specialize in ultralight aluminum construction for cycling and fastpacking segments.
Australia
TGA-aligned material safety standards and state-level single-use plastic restrictions in New South Wales and Victoria expand reusable container procurement. Sydney and Melbourne outdoor retail channels enforce drop-test durability standards for flip-top mechanisms. Victorian manufacturing clusters serve domestic demand while exporting to Southeast Asian wellness markets.
Wide Mouth Bottles Market Competitive Landscape
Concentration sits with diversified material specialists and premium outdoor brands. The vendor base spans multinational polymer converters, stainless steel fabricators, and heritage scientific equipment manufacturers. Three archetypes dominate: integrated polymer processors with private-label scale, premium thermal technology specialists, and laboratory-grade durability anchors. Competitive moves center on material compliance certification acceleration and direct-to-consumer subscription infrastructure for replacement parts.
Among North American heritage brands, Hydro Flask and Nalgene exemplify divergent positioning archetypes. Hydro Flask occupies the premium thermal technology tier with vacuum-insulated stainless steel construction. Nalgene anchors scientific and educational segment credibility through polycarbonate durability standards. Berry Global represents the integrated polymer processing archetype with manufacturing scale across multiple material platforms.
| Leading Market Players |
|---|
| Thermos LLC |
| Hydro Flask |
| Contigo |
| Nalgene |
| Klean Kanteen |
| Amcor |
| Berry Global |
| CamelBak |
| Tupperware Brands Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Jiangsu and Zhejiang cold-rolled stainless steel mills shapes both supply concentration and price floors across vacuum-insulated bottle fabrication. Scale economies in 304-grade coil production compress input costs for tier-one fabricators while elevating barriers for mid-tier competitors dependent on spot-market sourcing.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement contracts from direct-to-consumer retail pricing across the wide mouth bottles landscape. Premium-mid-economy pricing differentiation tracks thermal certification grade and replacement-part bundling intensity. Cost compression in polymer-based mass-market tiers is intensifying because REACH plasticizer restrictions extend R&D timelines and reformulation expenses. Municipal procurement buyers exhibit highest price sensitivity, while outdoor specialty retailers prioritize thermal performance verification over unit cost.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Ningbo port congestion elevate landed costs for European and North American fabricators sourcing 304-grade stainless steel coil. Raw material supply draws from Chinese and Indonesian mills for cold-rolled coil, Jiangsu province for polymer resin, and Belgian converters for specialty closure compounds. Single-source vulnerability clusters in Yangtze River Delta steel production expose bottle fabricators to tariff volatility and alloy price swings. Distribution runs through Hamburg and Rotterdam port clusters for European channels, with Pacific Northwest rail corridors serving North American outdoor specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EU F-Gas Regulation and REACH framework compliance create certification barriers that entrench qualified incumbents against unqualified challengers.
For Market Incumbents: Shield market position by accelerating thermal performance certification pipelines to compress 14-18 week verification timelines. Deepen backward integration into cold-rolled coil supply through captive offtake agreements with Jiangsu mills, insulating fabrication margins from spot-market volatility. Aluminum substitution threats from cycling event sponsorships demand proactive insulation technology investment to defend premium positioning.
For New Entrants and Emerging Players: Aftermarket replacement-part subscription gaps expose incumbent disintermediation vulnerabilities that new entrants can exploit through direct-to-consumer infrastructure. Medical specimen crossover applications present the most penetrable white space, leveraging laboratory-grade polycarbonate durability standards for wellness channel entry. Pursue clinical supply distribution partnerships as the primary go-to-market angle, bypassing saturated outdoor retail gatekeepers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fabricators with certified vacuum-insulation capabilities and established EU regulatory compliance documentation. Long-term viability hinges on circular economy adaptation capacity across multi-material separation and design-for-recycling expertise. Watch California SB 54 implementation velocity as the signal indicating institutional procurement inflection toward reusable container mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Performance Certification Acceleration | Compresses 14-18 week verification timelines to align with seasonal product launch windows. |
| Backward Integration into Coil Supply | Captive offtake agreements with Jiangsu mills reduce exposure to 304-grade price volatility. |
| Replacement-Part Subscription Infrastructure | Direct-to-consumer gasket and cap revenue extends product lifecycles beyond initial vessel purchase. |
| Medical Specimen Crossover Development | Laboratory-grade polycarbonate standards enable pharmaceutical-adjacent wellness channel entry. |
| Design-for-Recycling Capability Investment | Multi-material separation expertise addresses EU Green Deal end-of-life compliance requirements. |
Research Methodology
Operator-level perspectives from bottle fabrication plant managers, outdoor specialty retail category buyers, polymer procurement leads at converters, and thermal certification laboratory directors anchored the qualitative base. Primary interview data combined with secondary validation from FDA food-contact material filings, ECHA REACH substance registrations, EPA extended producer responsibility program documentation, and customs trade records for stainless steel coil and polymer resin shipments. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Sensitivity analysis tested forecast robustness across alternative regulatory implementation timelines and raw material price scenarios. Segmentation dimensions modeled include material platform, application channel, closure mechanism, and geographic regulatory cluster. CAGRs derived from trend extrapolation calibrated against historical replacement cycle data and event-driven demand inflections. Vacuum insulation technology diffusion curves and REACH plasticizer restriction compliance costs served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU F-Gas Regulation phasedown schedules and California SB 54 implementation timelines; material policy shifts would require re-modeling. Commodity price volatility in 304-grade stainless steel and polymer resin feedstocks represents primary revision risk. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Telescope Box Market
Packaging Containers
Single Serve Packaging Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Snap Single Dose Dispensers Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Correx Trays Market
Packaging Containers
Non-Corrugated Boxes Market
Packaging Containers
Bottles Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
North America Food Cans Market