
 Latin America Aerosol Cans Market | 2026-2036
Latin America Aerosol Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Aerosol Cans Market Foresight
REACH-aligned chemical safety protocols across Latin American trade blocs is hardening sustainability requirements for aerosol can producers. Can-Pack SA leverages integrated aluminum smelting and can-making operations across Poland and Brazil to sustain cost leadership in regional supply. Crown Holdings Inc. anchors its Latin American position through beverage-can scale economies that extend into aerosol manufacturing lines. Ball Corporation differentiates via lightweighting technology and recycled-content aluminum specifications that compete on environmental credentials.
Latin America aerosol cans are sealed, pressurized metal or composite containers designed to dispense products as fine sprays, foams, or mists through a valve-and-actuator system, typically constructed from aluminum or tinplate steel with internal coatings resistant to propellant-product interaction. Aluminum dominates product type segmentation due to corrosion resistance, printability, and infinite recyclability that supports circular economy mandates across the region. Personal care applications lead volume demand through deodorant and hair spray consumption, while industrial applications represent the fastest-expanding segment driven by Brazil's automotive refinishing and Mexico's electronics cleaning sectors. Household applications occupy mature growth territory with stable replacement demand tied to insecticide and air freshener purchasing patterns.
Brazil's ANVISA pharmaceutical and cosmetic regulator enforces propellant safety standards that shape personal care aerosol formulation and can interior coating requirements, while Mexico's PROFEPA environmental enforcement aligns with Montreal Protocol phasedown schedules for hydrofluorocarbon propellants. Argentina's IRAM standards body and Chile's SEC certification framework add compliance layers for cross-border trade within Mercosur and Pacific Alliance structures. Stakeholders must monitor evolving extended producer responsibility legislation across the region's largest economies to determine recycling infrastructure investment timing and circular design commitments.
Market Dynamics
Mexico's PROFEPA enforcement of Montreal Protocol phasedown schedules is forcing hydrofluorocarbon reformulation across personal care and industrial aerosol lines, while Brazil's São Paulo corridor concentrates aluminum can supply amid raw material cost volatility.
Growth Catalysts
- REACH-aligned chemical safety protocols:Trade bloc harmonization across Mercosur and Pacific Alliance members is hardening sustainability requirements that favor aluminum recyclability credentials in cross-border commerce.
- Automotive refinishing sector expansion:Brazil's vehicle aftermarket is pulling industrial aerosol volumes for paint touch-up and coating applications through authorized dealer networks.
- Electronics cleaning demand:Mexico's Monterrey manufacturing cluster is consuming precision aerosol solvents for semiconductor and component assembly operations.
Market Restraints
- Aluminum ingot price volatility:Raw material cost swings compress converter margins and complicate long-term contract pricing with brand owners.
- Tinplate supply concentration:Regional steel can production depends on limited domestic rolling capacity, exposing buyers to import dependency and currency risk.
- Propellant transition timelines:ANVISA safety standards and PROFEPA environmental rules create overlapping compliance windows that extend product reformulation cycles.
Strategic Opportunities
- Chile and Colombia market development:Pacific Alliance trade facilitation is lowering tariff barriers for aerosol exporters targeting underpenetrated Andean consumer bases.
- Recycled-content aluminum specifications:Circular economy mandates across Brazilian states are creating premium positioning for cans with verified post-consumer content.
- E-commerce direct-to-consumer channels:Personal care brands are bypassing traditional retail distribution through platform logistics that accommodate hazmat shipping protocols.
Industry Challenges
- Interior coating chemistry expertise:Formulation compatibility between propellant-product mixtures and can linings requires specialized polymer science talent that remains scarce in regional labor markets.
- Extended producer responsibility infrastructure:Recycling system investments must precede regulatory deadlines in Brazil and Mexico, forcing capital allocation ahead of proven return models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Aerosol Cans Market |
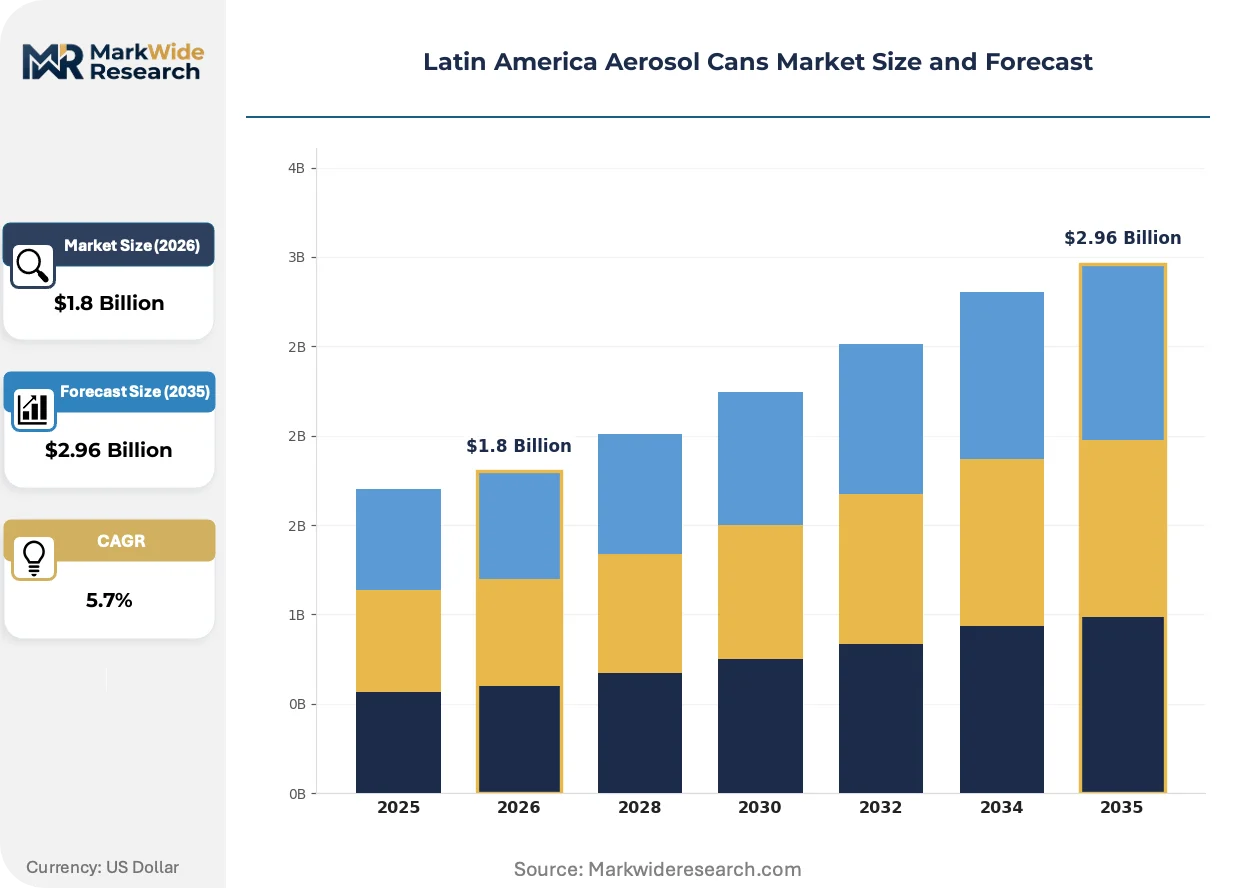
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Composite, Plastic Application: Personal Care, Household, Automotive, Industrial End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Can-Pack SA, Mauser Packaging Solutions, Crown Holdings Inc., Tecnocap Group, Silgan Holdings Inc., Ball Corporation, Ardagh Group, LINDAL Group, CCL Industries Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Aerosol Cans Market Shifts & Advancements
Active reformulation of propellant systems and lightweighting of aluminum substrates are compressing material intensity per unit while regulatory deadlines accelerate capital deployment into coating and filling equipment.
Bag-on-valve (BOV) barrier technology is separating propellant from product through a laminated film pouch that collapses during dispensing. Personal care and pharmaceutical manufacturers in Brazil are adopting BOV for sensitive formulations at accelerating rates. This architecture is decentralizing formulation possibilities by enabling water-based and oil-based products that would corrode conventional unlined cans.
ANVISA pharmaceutical and cosmetic regulations are tightening documentation requirements for can interior coatings that contact skin-applied products. Manufacturers must now submit migration testing data that extends product development timelines by several quarters. Personal care aerosol lines face the steepest compliance burden, with some Brazilian converters adding dedicated pharmaceutical-grade filling suites to capture premium positioning.
Brand owners are consolidating supplier relationships toward single-source aluminum can partnerships that bundle design, coating, and logistics services. Traditional spot-market purchasing of commodity cans is contracting among mid-sized personal care companies. This concentration is most visible in Mexico, where multinational FMCG headquarters are mandating regional supply base rationalization to simplify audit and compliance workflows.
Latin America Aerosol Cans Market Segmentation
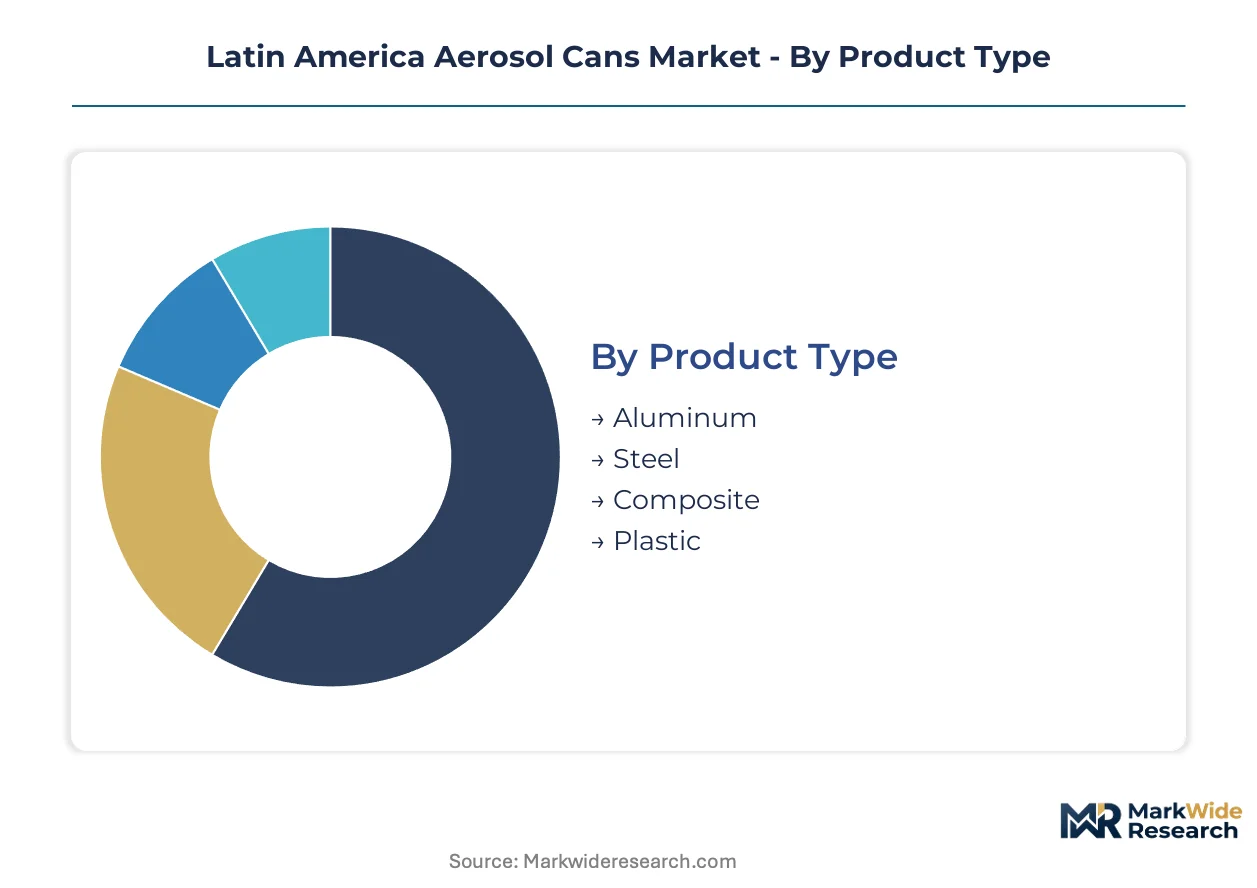
Latin America aerosol can segmentation reflects divergent compliance burdens across material substrates and end-use applications. ANVISA pharmaceutical-grade requirements and PROFEPA environmental mandates create tiered certification thresholds that reshape procurement patterns for converters and brand owners.
Product Type:
Certification requirements vary sharply by substrate, with aluminum facing recycled-content verification under Brazilian state circular economy laws while steel must satisfy IRAM metallurgical standards for cross-border Mercosur trade.
- Aluminum:Corrosion-resistant, infinitely recyclable substrate dominates premium personal care and pharmaceutical lines. São Paulo industrial corridor converters favor aluminum for ANVISA-compliant deodorant and hair spray packaging where interior coating migration testing is mandatory. Raw material cost volatility remains the primary margin pressure.
- Steel:Tinplate construction serves cost-sensitive household applications with established supply chains from limited regional rolling capacity. Argentina's IRAM standards and Chile's SEC certification add compliance layers for insecticide and air freshener cans distributed across Pacific Alliance markets. Import dependency creates currency exposure for buyers.
- Composite:Multi-layer barrier structures address specialized industrial solvents requiring chemical resistance beyond monobloc capabilities.
- Plastic:PET and nylon variants penetrate water-based product niches where metal corrosion risks exclude conventional cans.
Leading the category by volume: Aluminum. Growing fastest: Composite.
Application:
End-use applications stratify by margin structure, with personal care commanding premium pricing for ANVISA-compliant coating specifications while industrial volumes scale through Brazil's automotive aftermarket.
- Personal Care:Deodorant, hair spray, and shaving foam consumption concentrates in Brazil's urban centers. ANVISA pharmaceutical and cosmetic regulations mandate dedicated pharmaceutical-grade filling suites for skin-contact products, extending development timelines. Brand owners are consolidating toward single-source aluminum partnerships to simplify audit workflows.
- Industrial:Automotive refinishing, electronics cleaning, and precision solvents represent the steepest expansion trajectory. Brazil's vehicle aftermarket pulls paint touch-up volumes through authorized dealer networks while Mexico's Monterrey cluster consumes aerosol solvents for semiconductor assembly. PROFEPA hydrofluorocarbon phasedown is forcing active propellant reformulation.
- Household:Insecticide and air freshener replacement demand occupies mature growth territory with stable purchasing patterns.
- Automotive:Dedicated aftermarket coatings and lubricants segment with specialized corrosion-resistant interior specifications.
Dominating volume: Personal Care. Climbing the fastest: Industrial.
End User:
Customer type determines order scale and specification complexity, with manufacturers demanding integrated design-coating-logistics bundles while retailers prioritize shelf-ready packaging formats.
- Manufacturers:FMCG brand owners and contract fillers specify can-coating-propulsion integrated systems. Multinational headquarters in Mexico are mandating regional supply base rationalization to reduce audit burden. Procurement is shifting toward long-term single-source partnerships away from spot-market purchasing.
- Retailers:Supermarket and drugstore chains specify private-label aerosol programs with standardized pallet configurations.
- Distributors:Wholesale intermediaries aggregate fragmented regional demand for mid-sized personal care companies.
- Consumers:Direct e-commerce channels are emerging for subscription personal care models with hazmat-compliant last-mile logistics.
Primary volume driver: Manufacturers. Fastest-growing access path: Consumers via e-commerce.
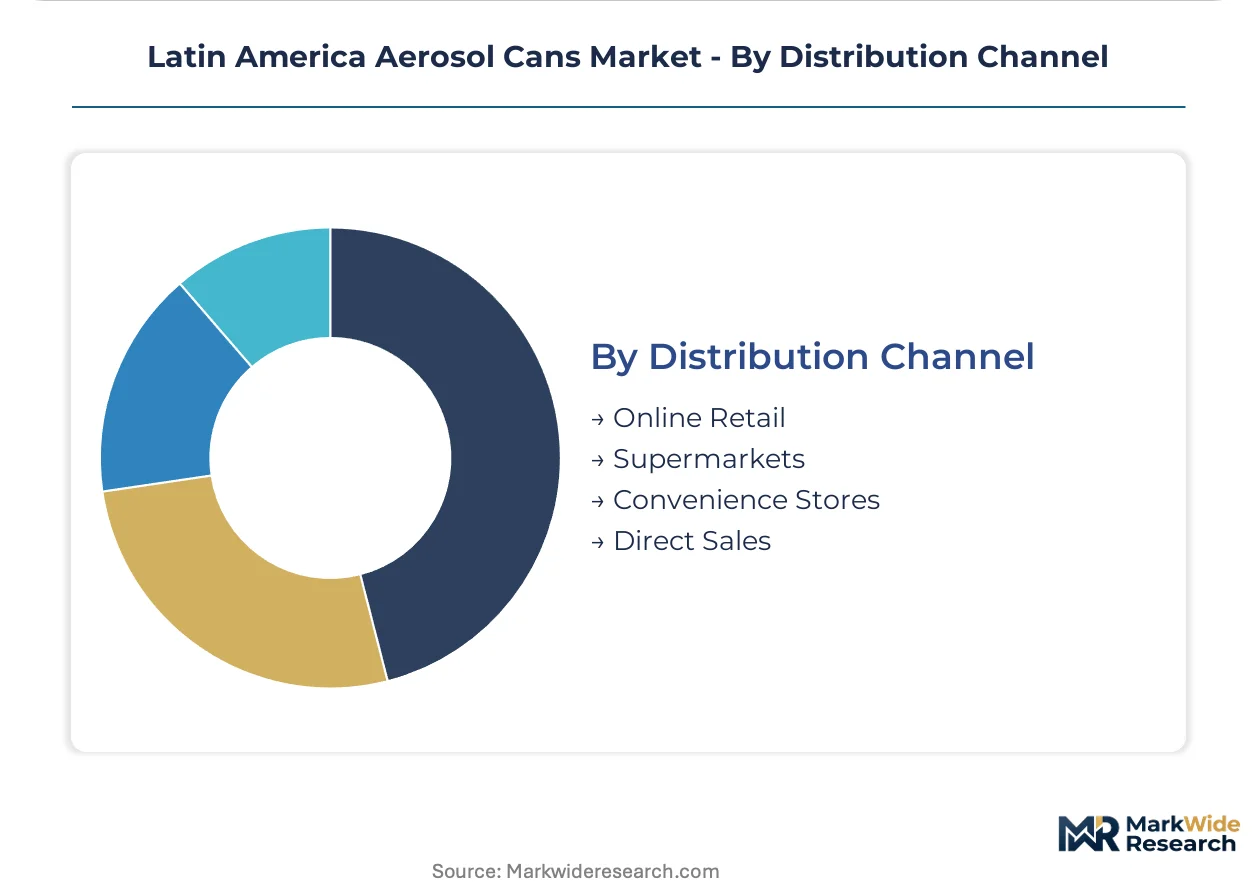
Distribution Channel:
Channel selection balances reach against regulatory complexity, with hazmat shipping protocols favoring established retail networks over direct-to-consumer expansion.
- Supermarkets:Hypermarket and supermarket chains anchor personal care volume through promotional display programs and loyalty card data.
- Online Retail:Platform logistics accommodating pressurized container shipping are enabling brand bypass of traditional distribution. Chile and Colombia Pacific Alliance trade facilitation is lowering tariff barriers for cross-border e-commerce aerosol sales.
- Convenience Stores:Urban proximity retail captures impulse replacement purchases for deodorant and travel-size formats.
- Direct Sales:Industrial and automotive channels run through authorized dealer networks with technical specification support.
Highest volume channel: Supermarkets. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Brazil and Mexico while consumption spreads across Pacific Alliance trade corridors. Argentina and Chile import finished cans to compensate for limited domestic rolling capacity. Colombia's Andean consumer base remains underpenetrated relative to per-capita aerosol usage in Southern Cone markets.
Brazil
São Paulo's industrial corridor hosts integrated aluminum smelting and can-making operations serving ANVISA-regulated personal care lines. The national pharmaceutical and cosmetic regulator enforces migration testing for interior coatings contacting skin-applied products. São Paulo state circular economy laws mandate recycled-content verification, pushing converters toward verified post-consumer aluminum specifications.
Mexico
Monterrey's manufacturing cluster consumes precision aerosol solvents for semiconductor and electronics assembly operations. PROFEPA environmental enforcement aligns with Montreal Protocol phasedown schedules for hydrofluorocarbon propellants. Mexico City metro area anchors beverage-can scale economies that extend into aerosol manufacturing through shared aluminum supply chains.
Argentina
IRAM standards body certification adds compliance layers for cross-border Mercosur trade in household insecticide and air freshener cans. Buenos Aires province concentrates import-dependent tinplate conversion for cost-sensitive applications. Currency volatility exposes buyers to rolling capacity shortages from limited domestic steel production.
Chile
Santiago's consumer market pulls premium personal care aerosols through Pacific Alliance trade facilitation lowering tariff barriers. SEC certification framework governs electrical and electronic product safety adjacent to industrial aerosol applications. Northern mining regions generate specialized demand for corrosion-resistant industrial coatings in equipment maintenance.
Colombia
Bogotá and Medellín urban centers present underpenetrated demand for deodorant and hair spray formats relative to Brazilian per-capita consumption. E-commerce platform logistics accommodating hazmat shipping protocols enable direct-to-consumer personal care subscription models. Andean geography fragments distribution networks, favoring regional converter partnerships over centralized supply.
Latin America Aerosol Cans Market Competitive Landscape
The competitive structure tilts toward integrated aluminum specialists with captive smelting or beverage-can scale advantages. Tiered positioning separates premium pharmaceutical-grade converters from commodity household can suppliers. Three archetypes dominate: backward-integrated aluminum producers, diversified packaging conglomerates with cross-divisional scale, and specialized aerosol component system suppliers. Capacity expansion and supply base rationalization constitute the dominant competitive moves as brand owners consolidate toward single-source partnerships.
Among integrated metal packaging specialists, Can-Pack SA, Crown Holdings Inc., and Ball Corporation exemplify contrasting scale strategies. Can-Pack SA anchors cost leadership through captive aluminum production bridging European and Latin American operations. Crown Holdings Inc. occupies a position leveraging beverage-can infrastructure for aerosol line extensions. Ball Corporation represents environmental credential competition via lightweighting technology and recycled-content specifications.
| Leading Market Players |
|---|
| Can-Pack SA |
| Mauser Packaging Solutions |
| Crown Holdings Inc. |
| Tecnocap Group |
| Silgan Holdings Inc. |
| Ball Corporation |
| Ardagh Group |
| LINDAL Group |
| CCL Industries Inc. |
| Others |
Supply & Pricing Matrix
London Metal Exchange aluminum ingot pricing cascades through Latin American aerosol can supply chains into three distinct procurement tiers. São Paulo converters with captive smelting access capture margin insulation against spot volatility, while import-dependent Argentine tinplate buyers absorb currency-driven cost compression.
Pricing Analysis
ANVISA pharmaceutical-grade certification anchors value-based pricing for skin-contact aerosol lines. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-compliant aluminum cans from IRAM-certified steel household formats and unlined commodity imports. Cost compression in standard-tier steel cans is intensifying because Brazilian currency depreciation inflates import-rolling exposure. Mid-sized personal care brands exhibit highest price sensitivity, while multinational FMCG headquarters prioritize audit simplification over unit cost.
Supply Chain Analysis
Direct-to-converter channels handle multinational FMCG demand through single-source aluminum partnerships bundling design, coating, and logistics. Supply concentrates in Brazil, Mexico, and Poland through Can-Pack SA's integrated smelting-canning operations. Raw material flows draw from bauxite-alumina smelting, tinplate rolling imports, and propellant chemical feedstocks. Single-source vulnerability pervades regional steel rolling capacity, forcing Argentine and Chilean buyers into dollar-denominated import contracts. Distribution runs through São Paulo and Monterrey manufacturing clusters into Pacific Alliance trade corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where converters with captive aluminum smelting or beverage-can scale economies capture sustainable margin positions against spot-market dependent competitors.
For Market Incumbents: Cement supply security through backward integration into bauxite-alumina supply or long-term tolling agreements with São Paulo smelters. Add dedicated pharmaceutical-grade filling suites ahead of ANVISA documentation deadline acceleration. Capacity addition in Colombia addresses Pacific Alliance trade facilitation opportunities before tariff barriers fully erode. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Andean personal care aerosols offers white-space entry below multinational FMCG procurement minimums. Target Bogotá and Medellín urban centers with deodorant formats adapted to lower per-capita consumption patterns. E-commerce direct-to-consumer channels with hazmat-compliant last-mile logistics provide viable go-to-market architecture outside traditional retail gatekeeping. For Investors and Strategic Acquirers: The window for entry favors mid-cap converters with verified post-consumer aluminum specifications and existing ANVISA compliance infrastructure. Long-term viability hinges on circular economy mandate timing across Brazilian states. Watch for extended producer responsibility legislation implementation as inflection indicator for recycling infrastructure investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Smelting Integration | Insulates Can-Pack SA margin from LME volatility through upstream bauxite-alumina control. |
| Pharmaceutical-Grade Filling Suite Addition | Captures ANVISA-compliant premium positioning as migration testing requirements tighten. |
| Recycled-Content Verification Investment | Meets São Paulo state circular economy mandates for post-consumer aluminum specifications. |
| Pacific Alliance Distribution Expansion | Leverages Chile-Colombia trade facilitation to access underpenetrated Andean consumer bases. |
| Bag-on-Valve Technology Adoption | Enables water-based formulation compatibility beyond conventional unlined can corrosion limits. |
Research Methodology
Multi-period observation of LME aluminum pricing, ANVISA regulatory filing timelines, and PROFEPA enforcement actions anchored the trend analysis, supplemented by interviews with aerosol converter plant managers, FMCG brand procurement leads, pharmaceutical-grade coating suppliers, and Pacific Alliance trade logistics specialists. Secondary validation drew from SEC 10-K filings of listed packaging conglomerates, Brazilian customs export records, IRAM standards documentation, and Montreal Protocol phasedown schedules. Bottom-up volume triangulation across end-use applications converged with top-down aluminum consumption estimates from regional smelter associations.
Input-output matrices modeled demand drivers across product type, application, end user, and distribution channel dimensions over the projection horizon. Segmentation outputs incorporated propellant reformulation cycles, coating chemistry migration testing timelines, and e-commerce hazmat logistics penetration as industry-specific forecast inputs. CAGRs were derived from weighted regression of historical volume trends against regulatory deadline acceleration and trade bloc harmonization schedules.
Inputs from ANVISA regulatory databases and LME price archives were available through the study window; gaps in real-time converter inventory data introduce uncertainty bands around quarterly volume estimates. Forecasts reflect documented assumptions regarding Montreal Protocol compliance timelines and Pacific Alliance tariff phaseout schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Wrist Watch Packaging Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Correx Trays Market
Packaging Containers
Insulated Icebox Market
Packaging Containers
Cluster Packaging Market