
 Gable Boxes Market | 2026-2036
Gable Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Gable Boxes Market Foresight
The divergence between premium and commodity tiers is hardening in the gable boxes market as food brands demand custom-printed, barrier-coated formats while cost-driven industrial buyers prioritize unbleached kraft at volume. Crown Holdings leverages its metal packaging heritage to extend coating technologies into paper-based gable structures. Smurfit Kappa Group anchors European supply through integrated containerboard and converting operations. Graphic Packaging International differentiates via beverage-specific gable top innovations with extended shelf-life performance.
Gable boxes are paper-based cartons with peaked, folded tops that lock without adhesive, typically constructed from 18-24 point solid bleached sulfate or recycled kraft linerboard with optional polyethylene or aqueous barrier coatings, designed for gravity-fed dispensing and stackable retail display. Kraft paper and corrugated fiberboard segments dominate food packaging applications where grease resistance and crush strength determine specification compliance. Pharmaceutical packaging represents a faster-growing niche as unit-dose compliance packs adopt gable geometries for child-resistant closure integration.
FDA food contact substance regulations govern barrier coating approvals in the United States, while EU REACH and the Packaging and Packaging Waste Regulation enforce recyclability thresholds and extended producer responsibility fees across member states. The EU Green Deal's 2030 packaging reuse targets are forcing converters to validate fiber recovery rates for laminated gable structures. Stakeholders must monitor how diverging transatlantic sustainability timelines reshape material specification standards and capital allocation priorities.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to re-engineer laminated gable structures for fiber recovery compliance, reshaping capital allocation and material specifications across the value chain.
Growth Catalysts
- Takeout format standardization:Food service operators in Germany are mandating recyclable gable boxes for bakery and ready-meal delivery, creating procurement pull at volume.
- REACH recyclability thresholds:EU member states now enforce extended producer responsibility fees that reward mono-material gable designs over multi-layer alternatives.
- Barrier coating innovation:Aqueous and bio-based coatings are achieving grease resistance parity with polyethylene, unlocking fiber-to-fiber recycling loops.
Market Restraints
- Containerboard supply concentration:Integrated European mills control kraft linerboard pricing, exposing converters to input cost volatility during energy price spikes.
- Lamination complexity:Polyethylene-coated gable structures face technical limitations in standard pulp recovery streams, complicating compliance with EU Green Deal targets.
- Flexible pouch substitution:Stand-up pouches with spouts are capturing liquid food applications where gable tops once dominated shelf-stable segments.
Strategic Opportunities
- Pharmaceutical compliance packs:Unit-dose gable geometries with child-resistant closures are penetrating prescription packaging where blister packs face sustainability scrutiny.
- Reuse target alignment:The EU Green Deal's 2030 packaging reuse mandates create regulatory tailwinds for durable gable formats in institutional food service.
- Digital printing convergence:Hybrid inkjet and flexo systems are enabling short-run customization for craft food brands without plate changeover costs.
Industry Challenges
- Coating chemist scarcity:Formulation expertise for food-contact barrier layers is concentrating at specialized compounders, lengthening R&D cycles for mid-tier converters.
- Validation timeline compression:FDA food contact substance notifications and EFSA safety assessments now run in parallel, demanding dual-track regulatory affairs capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gable Boxes Market |
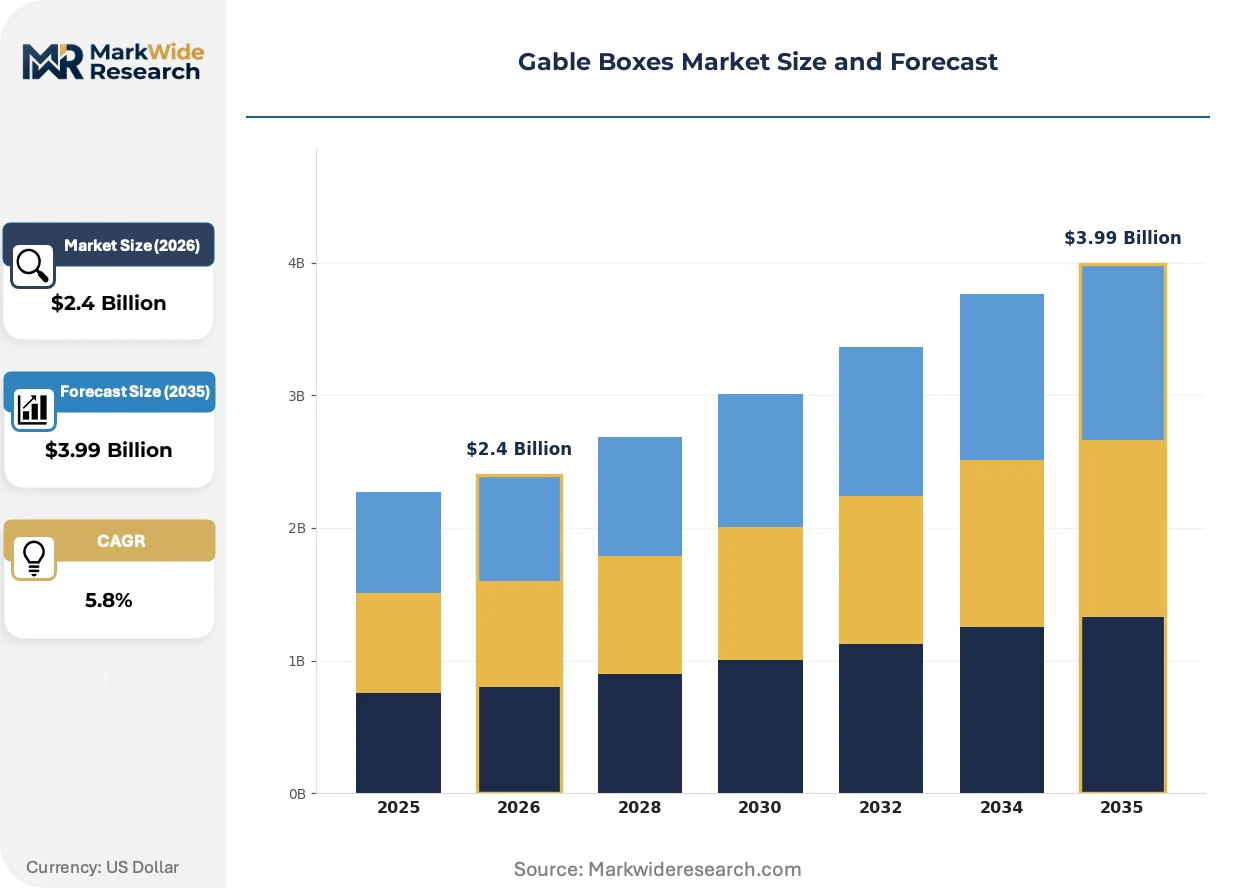
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kraft Paper, Cardboard, Corrugated Fiberboard, Plastic, Biodegradable Paper, Laminated Paper Application: Food Packaging, Beverage Containers, Gift Packaging, Cosmetic Packaging, Pharmaceutical Packaging, Industrial Packing Packaging Size: Small, Medium, Large, Extra Large, Custom Size Sales Channel: Online Retailers, Supermarkets, Specialty Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Crown Holdings, Smurfit Kappa Group, Packaging Corporation of America, DS Smith, Graphic Packaging International, WestRock, Green Bay Packaging, Sonoco, International Paper Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gable Boxes Market Shifts & Advancements
Material science advances and regulatory stringency are converging to redefine performance benchmarks for paper-based packaging, with sustainability credentials now determining specification wins.
Water-based barrier coatings are rewriting competitive access in food service packaging. Quick-service chains and meal-kit providers are adopting these formulations at pilot scale ahead of mandated plastic reduction targets. The technology is rewriting margin structures by eliminating separate lamination steps while satisfying emerging fiber recovery standards.
The EU Green Deal's packaging reuse targets are tightening material circulation requirements. Industrial consequence includes mandatory design-for-recycling protocols that disqualify legacy polyethylene-lined gable boxes from public procurement. Bakery chains across Germany, France, and Italy are responding by qualifying mono-material alternatives ahead of 2030 enforcement windows.
Direct sourcing from converters is compressing traditional distribution layers. Regional food brands are bypassing merchant distributors to secure custom-printed gable formats with shorter lead times. This pattern is most visible in Nordic markets where sustainability certifications drive specification decisions and brand owners demand supply chain transparency documentation.
Gable Boxes Market Segmentation
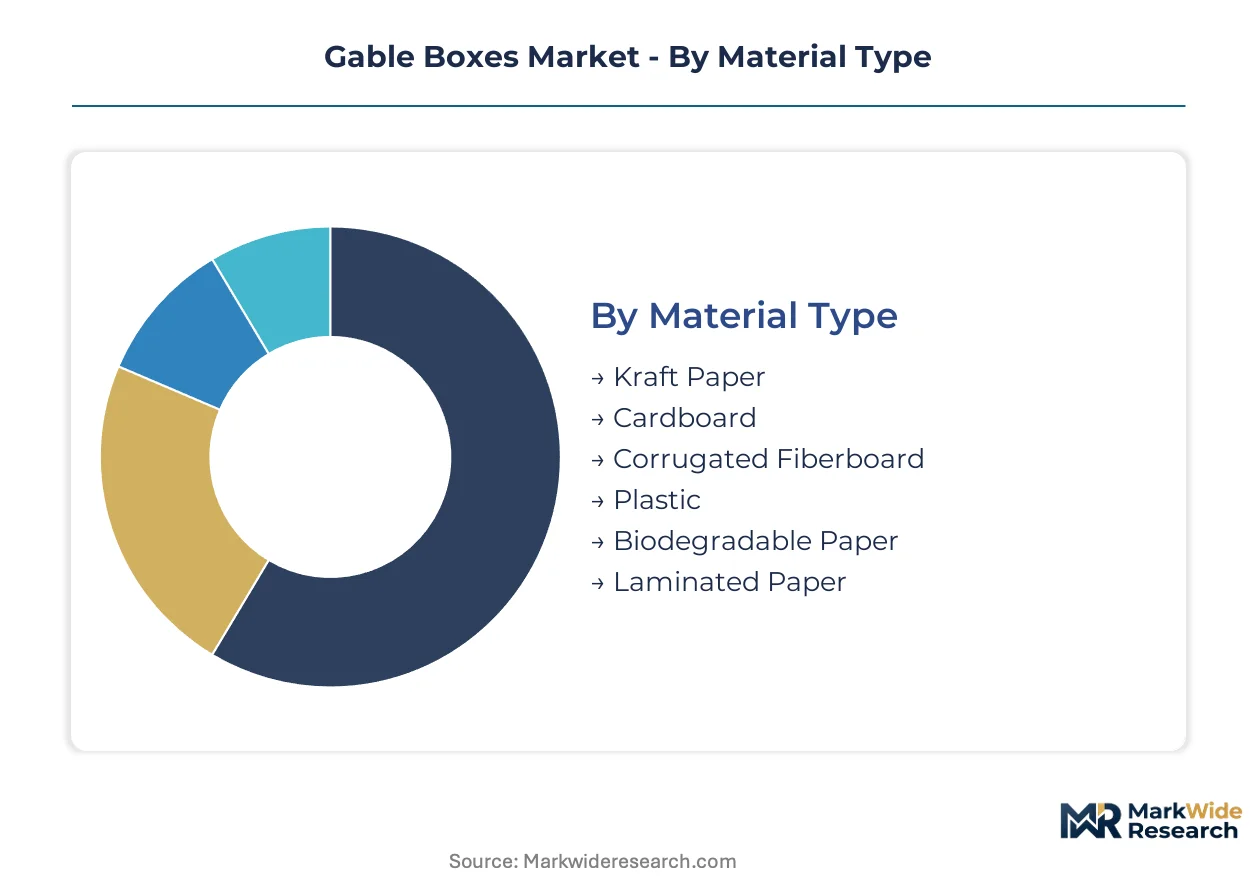
Material specifications and end-use performance requirements drive divergent procurement patterns across the gable boxes market. Buyers prioritize barrier properties, fiber recovery compliance, and printability depending on whether the application serves food service, pharmaceutical, or industrial segments.
Material Type:
Cost tier and sustainability credentials determine specification selection, with unbleached grades commanding volume and coated alternatives capturing premium positioning.
- Kraft Paper:Unbleached virgin or recycled fiber construction delivers grease resistance and structural rigidity for bakery and ready-meal applications. German bakery chains standardize on this grade for EU Packaging and Packaging Waste Regulation compliance, prioritizing mono-material recyclability over laminated alternatives.
- Corrugated Fiberboard:Fluted medium sandwiched between linerboards provides crush strength for heavier industrial contents and multi-unit retail packs. Demand concentrates in German ready-meal distribution where palletization and cold-chain stacking requirements favor double-wall constructions.
- Cardboard:Solid bleached sulfate boards offer superior printability for gift and cosmetic applications requiring high-definition graphics.
- Plastic:Polypropylene and PET variants persist in liquid containment where moisture vapor transmission rates must approach zero.
- Biodegradable Paper:Cellulose-based substrates with bio-coatings serve composting infrastructure markets in France and Italy.
- Laminated Paper:Polyethylene-extruded or aqueous-coated structures balance barrier performance with emerging fiber recovery capabilities.
Volume sits with Kraft Paper; growth tilts toward Biodegradable Paper.
Application:
Regulatory exposure and shelf-life requirements fragment demand across end-use segments with diverging compliance burdens.
- Food Packaging:Grease-resistant coatings and FDA food contact substance approvals govern specification for quick-service takeout and meal-kit delivery. EU REACH thresholds for recyclability are forcing German operators to qualify aqueous-coated mono-material formats ahead of extended producer responsibility fee adjustments.
- Pharmaceutical Packaging:Unit-dose compliance packs with child-resistant closure integration are expanding fastest as blister packs face sustainability scrutiny. EMA and national regulators are tightening documentation requirements for fiber-based primary packaging.
- Beverage Containers:Gable top cartons with extended shelf-life barriers compete against stand-up pouches in ambient liquid segments.
- Gift Packaging:Premium print finishes and foil stamping drive specification for seasonal retail and corporate gifting.
- Cosmetic Packaging:Luxury unboxing experiences favor rigid board constructions with magnetic or friction-fit closures.
- Industrial Packing:Bulk component containment prioritizes stack strength and moisture protection over aesthetic considerations.
Food Packaging anchors procurement tonnage; Pharmaceutical Packaging climbs the fastest.
Packaging Size:
Automation compatibility and last-mile logistics efficiency determine size selection across fulfillment channels.
- Small:Single-serve portions for confectionery and pharmaceutical unit doses.
- Medium:Standard ready-meal and bakery formats dominating German food service procurement.
- Large:Family-size meal kits and institutional catering packs.
- Extra Large:Bulk ingredient containment for food manufacturing and industrial supply.
- Custom Size:Brand-differentiated dimensions for subscription boxes and limited-edition retail.
Medium formats carry volume concentration; Custom Size specifications are expanding most quickly.
Sales Channel:
Supply chain transparency requirements and lead-time compression are restructuring traditional distribution layers.
- Direct Sales:Regional food brands bypass merchant distributors to secure custom-printed formats with sustainability certification documentation. Nordic markets exhibit the strongest direct procurement patterns where supply chain transparency is mandatory for brand positioning.
- Online Retailers:E-commerce fulfillment demands are driving short-run digital print compatibility and variable dimension flexibility.
- Supermarkets:Private-label standardization favors high-volume, low-variation specifications.
- Specialty Stores:Premium and artisanal brands source through converters with hybrid inkjet capabilities.
- Wholesale Distributors:Traditional stock-and-serve models face margin compression from direct sourcing trends.
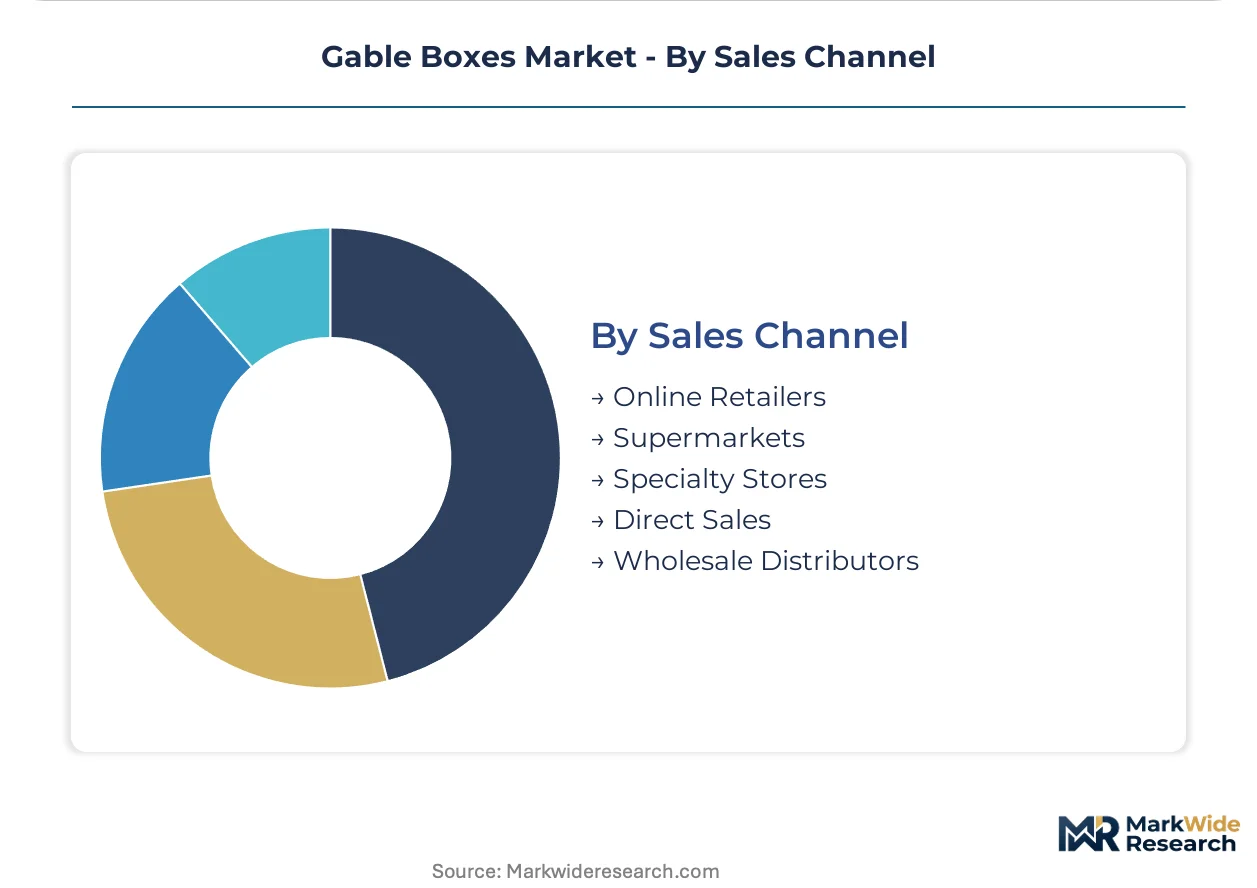
Direct Sales commands margin concentration; Online Retailers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor concentrates European gable box procurement, with Düsseldorf-based converters supplying standardized formats to bakery chains and ready-meal distributors across Germany and neighboring markets.
Germany
Bakery chains and ready-meal producers drive standardized gable box procurement at volume. The EU Packaging and Packaging Waste Regulation enforces material recovery targets that favor mono-material fiberboard designs. North Rhine-Westphalia hosts integrated containerboard mills supplying kraft linerboard to regional converters.
United States
Quick-service chains and meal-kit providers pilot aqueous-coated gable formats for takeout standardization. FDA food contact substance regulations govern barrier coating approvals, creating compliance timelines distinct from European counterparts. Wisconsin and Georgia paperboard corridors supply unbleached kraft grades to food service distributors.
France
Composting infrastructure markets in Île-de-France and Provence-Alpes-Côte d'Azur favor biodegradable paper substrates with bio-based coatings. ANSM pharmaceutical packaging standards intersect with national sustainability procurement rules for hospital food service. Lyon-based converters supply unit-dose compliance packs to regional pharmacy chains.
China
E-commerce fulfillment demands drive short-run digital print compatibility for subscription box formats. GB standards and SAMR regulations govern food contact paper safety, while dual carbon goals pressure converters toward fiber recovery validation. Yangtze River Delta packaging clusters export laminated gable structures to Southeast Asian markets.
India
Quick-service restaurant expansion in Maharashtra and Karnataka creates procurement pull for grease-resistant gable formats. FSSAI food safety standards and emerging extended producer responsibility frameworks reshape material specifications. Mumbai-based converters integrate aqueous coating lines to serve domestic bakery chains and export-ready spice packagers.
Gable Boxes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier coating sophistication and fiber recovery certification tiers. The vendor base spans integrated paperboard producers, specialized converters, and hybrid packaging conglomerates with metal-to-paper technology transfer capabilities. Three archetypes dominate: integrated mills with captive fiber supply, coating technology specialists, and beverage-focused format innovators. Consolidation pressures and capacity rationalization in European linerboard drive backward integration imperatives, while aqueous coating R&D partnerships reshape technical collaboration patterns.
Among integrated European producers, Smurfit Kappa Group and DS Smith exemplify the mill-to-converter archetype with containerboard integration. Graphic Packaging International occupies a position on the beverage-specific innovation vector, extending barrier performance into ambient liquid segments. Crown Holdings represents the cross-material technology transfer pattern, applying metal packaging coating heritage to paper-based structures.
| Leading Market Players |
|---|
| Crown Holdings |
| Smurfit Kappa Group |
| Packaging Corporation of America |
| DS Smith |
| Graphic Packaging International |
| WestRock |
| Green Bay Packaging |
| Sonoco |
| International Paper Co. |
| Others |
Supply & Pricing Matrix
Kraft linerboard pricing volatility originating from integrated European mills cascades through converter margins into end-user procurement tiers, with energy price spikes compressing mid-tier converter profitability while premium aqueous-coated formats sustain markup resilience.
Pricing Analysis
Barrier performance against grease and moisture transmission anchors value-based pricing tiers across the gable boxes market. Three-tier pricing structure across premium, standard, and economy levels separates aqueous-coated mono-material formats from polyethylene-laminated alternatives and unbleached kraft commodity grades. Cost compression in standard tiers is intensifying because German bakery chains are consolidating volume procurement around EU Packaging and Packaging Waste Regulation-compliant specifications. Quick-service operators exhibit the highest price sensitivity, while pharmaceutical packers prioritizing child-resistant closure integration demonstrate the lowest.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia, Wisconsin, and the Yangtze River Delta anchor hub-and-spoke fulfillment patterns for gable box converters. Supply concentration in Germany, the United States, and China draws from virgin kraft pulp, recycled fiber streams, and aqueous barrier coating chemistries. Single-source vulnerability concentrates in specialized compounders possessing food-contact formulation expertise. Distribution runs through direct converter relationships in Nordic markets and traditional wholesale layers in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerboard mill capacity constraints in energy-intensive European production corridors are propping pricing power for integrated producers with captive fiber supply.
For Market Incumbents: Lock in backward integration into aqueous coating R&D partnerships before formulation expertise concentrates further at specialized compounders. Secure volume offtake agreements with German bakery chains ahead of extended producer responsibility fee adjustments. Crown Holdings and Smurfit Kappa Group demonstrate the defensive value of cross-material technology transfer and captive linerboard supply respectively. For New Entrants and Emerging Players: Capture pharmaceutical unit-dose compliance pack segments where blister pack substitution creates specification windows for fiber-based child-resistant formats. Target Nordic direct-sourcing corridors where sustainability certification documentation commands procurement preference. Lead with digital print compatibility to serve craft food brands requiring short-run customization without plate costs. For Investors and Strategic Acquirers: EU Green Deal enforcement timeline acceleration is the leading indicator that mono-material gable format validation capabilities will command acquisition premiums. Over the medium-term horizon, coating technology specialists with FDA and EFSA dual-track regulatory affairs infrastructure represent the most defensible acquisition archetype. Monitor aqueous barrier performance parity announcements as the signal of impending specification tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Coating R&D Partnership | Unlocks fiber-to-fiber recycling compliance ahead of EU Green Deal mandates. |
| Backward Integration into Kraft Linerboard | Insulates converter margins from energy price volatility at integrated European mills. |
| Pharmaceutical Compliance Pack Qualification | Captures unit-dose substitution demand as blister packs face sustainability scrutiny. |
| Direct Sales Channel Development | Bypasses wholesale margin compression in Nordic transparency-driven procurement markets. |
| Digital Print Capability Investment | Enables short-run craft brand customization without traditional plate changeover costs. |
Research Methodology
Independent corroboration across converter operations managers, food service procurement directors, and pharmaceutical packaging engineers underwrites the qualitative findings in this study. Primary fieldwork with aqueous coating formulators and regulatory affairs specialists at EU and US notified bodies combined with secondary validation from FDA food contact substance notifications, EFSA safety assessments, EU Packaging and Packaging Waste Regulation implementation documents, and containerboard trade association production data. Bottom-up volume triangulation against top-down spending pattern analysis anchored segmentation outputs.
Historical reference periods spanning pre-regulatory and enforcement-phase intervals anchored the forecast window construction. The analytical framework modeled material type, application end-use, packaging size tier, and sales channel dynamics throughout the forecast period. CAGRs derived from segment-level demand elasticity coefficients and substitution rate assumptions for aqueous versus polyethylene barrier formats. Industry-specific inputs included EU extended producer responsibility fee schedules and FDA notification timeline compression effects.
The model holds under sustained regulatory enforcement timelines and stable energy input costs; deviation in coating chemistry breakthrough velocity or pulp price volatility spikes would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Single Serve Packaging Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Bottles Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Food Grade Bottles Market