
 Clamshell Packaging Market | 2026-2036
Clamshell Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Clamshell Packaging Market Analysis
The EU Green Deal is restructuring demand trajectories across European clamshell supply chains, compelling converters to certify recycled content thresholds. Amcor Limited leverages its integrated rPET sourcing network to secure preferred supplier status with pan-European retailers. Placon Corporation anchors North American foodservice clamshell supply through proprietary EcoStar recycled material streams. Sonoco Products Company competes via diversified molded fiber and hybrid plastic portfolios across pharmaceutical and electronics channels.
Clamshell packaging denotes a hinged, thermoformed container comprising two matched halves joined at a continuous fold, typically produced through vacuum forming, pressure forming, or twin-sheet thermoforming of PET, PVC, or polypropylene substrates between 0.010 and 0.060 inches thick, engineered to deliver tamper-evident product visibility and mechanical protection for retail and industrial distribution. PET clamshells dominate food and beverage end-use applications due to clarity, barrier performance, and established recycling infrastructure, while polypropylene segments gain traction in microwave-ready and higher-temperature food packaging where thermal resistance creates margin premiums. Electronics end-use demand concentrates in rectangular and custom-shaped configurations with snap or sealed closures, driven by anti-theft display requirements and the need for damage-resistant transit of consumer devices.
The EPA regulates volatile organic compound emissions from thermoforming operations under Clean Air Act Title V permitting, while FDA 21 CFR standards govern direct food contact material migration limits and substantiation requirements. REACH and RoHS frameworks in Europe restrict phthalate plasticizers and heavy metal additives in PVC clamshells bound for electronics and toy applications, redirecting formulation strategies toward compliant stabilizer packages. Stakeholders must monitor evolving extended producer responsibility schemes and state-level recycled content mandates to calibrate capital allocation between virgin and post-consumer feedstock infrastructure.
Market Dynamics
EU Green Deal compliance deadlines are compressing converter capital allocation timelines, forcing simultaneous retooling of thermoforming lines and feedstock certification systems across multiple substrate categories.
Growth Catalysts
- Electronics anti-theft mandates:Retailers in Germany and France now require tamper-evident display packaging for consumer devices above threshold values, pulling vacuum-formed PET clamshells into standard merchandising protocols.
- REACH Article 33 disclosure requirements:Substance-of-very-high-concern tracking is redirecting electronics and toy packaging away from legacy PVC formulations toward compliant PET and polypropylene alternatives.
- Guangdong manufacturing density:Export-oriented consumer goods clusters in Shenzhen and Dongguan generate concentrated demand for retail-ready protective packaging with integrated hang-hole and snap-closure features.
Market Restraints
- rPET feedstock competition:Beverage bottle reclaimers capture post-consumer PET bales at premiums that thermoformers struggle to match, constraining recycled content attainment for clamshell converters.
- Guangdong-Zhejiang supply concentration:Over half of global thermoforming capacity for export-grade clamshells sits within 200 kilometers of Pearl River Delta ports, creating vulnerability to regional energy rationing or logistics disruptions.
- Twin-sheet forming technical ceiling:Wall thickness uniformity below 0.015 inches remains difficult to achieve in pressure-formed polypropylene, limiting penetration into precision electronics housings.
Strategic Opportunities
- Indian pharmaceutical cold chain:Temperature-stable clamshell configurations for vaccine vial transport remain underdeveloped, with CDSCO stability testing protocols creating first-mover certification advantages.
- Bio-based PLA hybrid structures:Laminated PLA-PET twin-sheet combinations are absorbing pilot orders from French and Dutch retailers seeking compostable display packaging pathways.
- Direct-to-retailer e-commerce channels:Bypassing traditional distribution layers, converters in Michigan and Ohio are capturing specification authority with big-box electronics buyers through digital sampling platforms.
Industry Challenges
- Thermoforming technician scarcity:Vacuum forming and pressure forming machine operation requires 18-24 month apprenticeship cycles that regional technical colleges have not scaled to match replacement demand.
- FDA 21 CFR migration study timelines:New direct-food-contact clamshell designs face 12-18 month substantiation periods that compress product launch windows against private-label retailer deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clamshell Packaging Market |
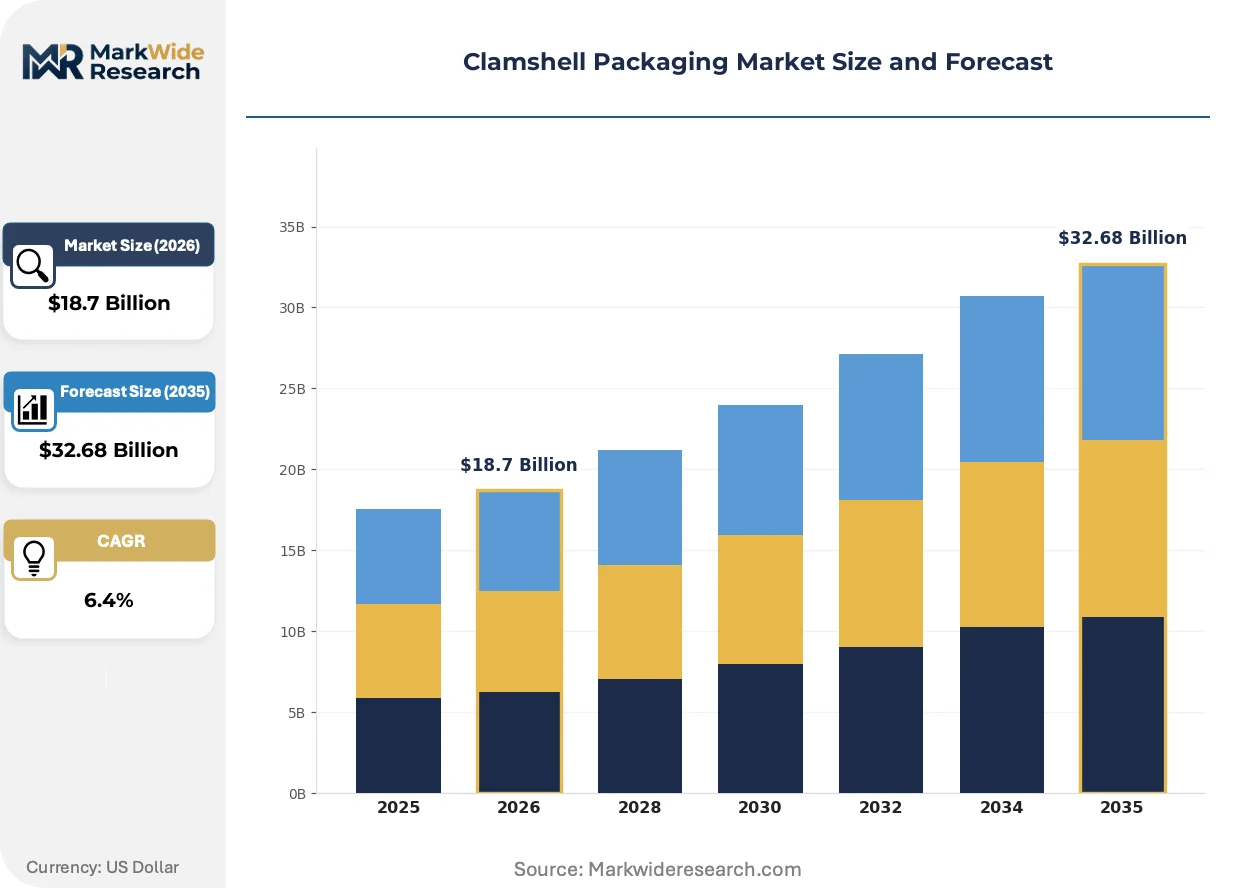
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Polypropylene, PVC, PET End User: Food & Beverage, Electronics, Toys, Pharmaceuticals Shape: Square, Rectangular, Oval, Custom Closure Type: Snap Closure, Hinged Closure, Sealed, Clipped |
| Companies Covered | Sealed Air Corporation, Placon Corporation, Amcor Limited, Dart Container Corporation, D&W Fine Pack, Sonoco Products Company, Pactiv LLC, Plastic Ingenuity, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clamshell Packaging Market Emerging Trajectories
Material substitution pressures and forming process digitization are restructuring competitive capability requirements, separating converters with integrated rPET sourcing from those dependent on spot resin markets.
Digital cavity pressure monitoring systems are absorbing capital investment priority across mid-scale thermoforming operations. Electronics contract manufacturers in Bavaria and Baden-Württemberg are specifying real-time thickness verification for anti-static clamshell shipments. This sensor integration is absorbing quality assurance labor costs while compressing reject rates in high-value device packaging.
EU Green Deal packaging waste directives are mandating 30% post-consumer recycled content thresholds by 2030. Thermoformers serving pan-European retailers must now certify mass-balance chain of custody or secure dedicated rPET flake supply. Food-contact clamshell segments face the steepest compliance ramps, with EFSA novel food contact material opinions adding 8-14 months to formulation validation.
Consolidated retail buying is compressing supplier rosters for standard clamshell formats. Mass merchandisers in Texas and California are reducing approved vendor lists from 12-15 converters to 3-4 strategic partners with multi-site molding capacity. This concentration is visible most acutely in blister and clamshell categories for over-the-counter pharmaceuticals, where specification uniformity across distribution centers outweighs unit price minimization.
Clamshell Packaging Market Segmentation
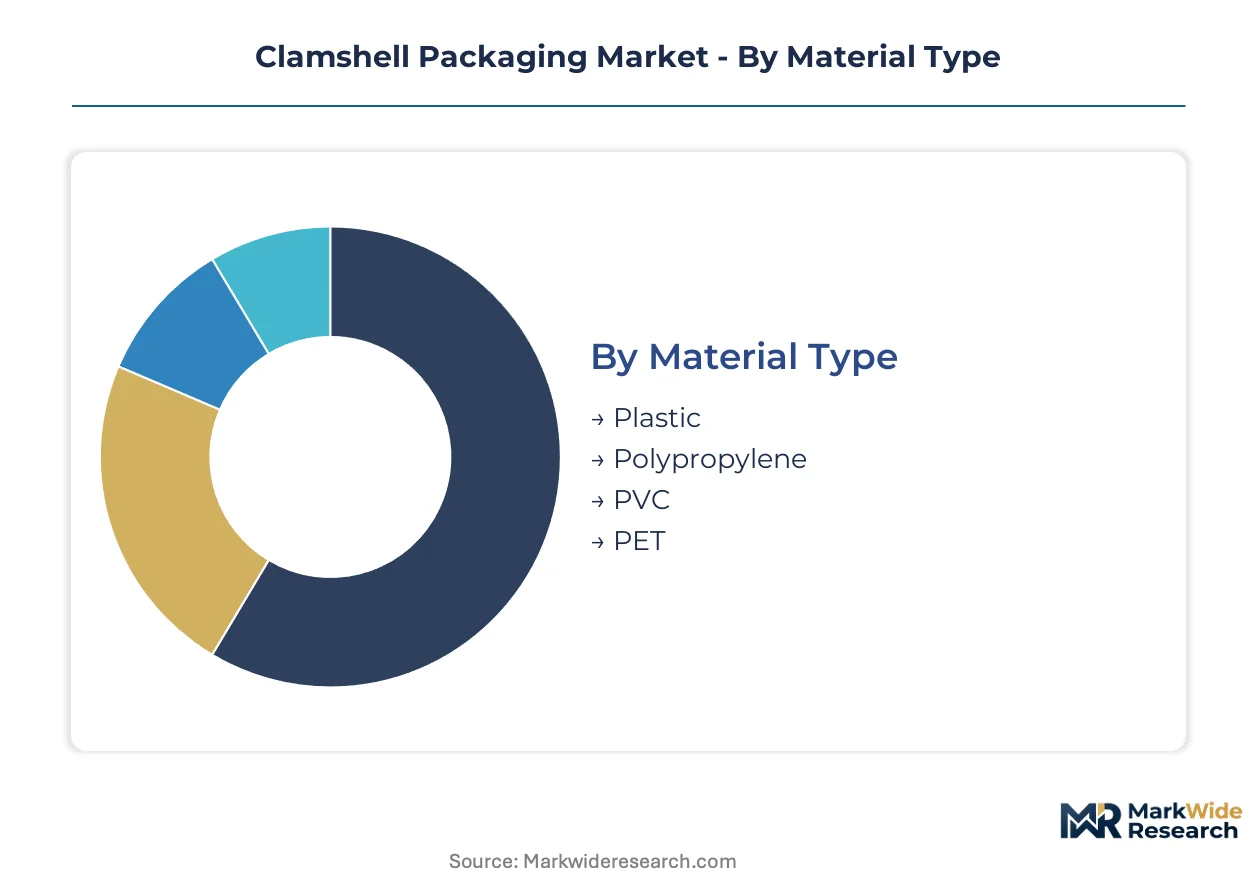
Thermoforming substrate selection and closure configuration determine regulatory pathway complexity and capital equipment requirements across clamshell production. End-use certification standards fragment addressable markets, with food-contact and pharmaceutical segments demanding substantiation timelines that electronics and toy applications avoid.
Material Type:
FDA 21 CFR migration limits apply to PET and polypropylene clamshells in direct food contact, while REACH Article 33 SVHC disclosure requirements govern PVC formulations in electronics and toy channels. EFSA novel food contact opinions add validation periods for recycled-content PET that virgin material escapes.
- Plastic:Umbrella category encompassing thermoformed sheets from 0.010 to 0.060 inches thick, vacuum-formed or pressure-formed into hinged configurations. Demand concentrates in Guangdong export manufacturing clusters where Shenzhen electronics contract manufacturers specify anti-static formulations for device protection.
- PET:Amorphous polyester delivering optical clarity and established mechanical recycling streams. Food and beverage end-use dominates volume, with rPET feedstock competition from beverage bottle reclaimers constraining recycled content attainment for thermoformers.
- Polypropylene:Semi-crystalline olefin with thermal resistance enabling microwave-ready food packaging. Higher-temperature applications command margin premiums, though twin-sheet forming below 0.015-inch wall thickness remains technically challenging.
- PVC:Legacy substrate facing REACH and RoHS restrictions on phthalate plasticizers and heavy metal stabilizers. Electronics and toy packaging demand is redirecting toward compliant PET and polypropylene alternatives.
Leading the category by volume: PET. Expanding most quickly: Polypropylene in higher-temperature food applications.
End User:
Application-specific performance requirements segment clamshell demand across divergent certification burdens and margin structures. Customer procurement authority concentrates differently by channel, with mass merchandisers reducing approved vendor lists in pharmaceutical and electronics categories.
- Food & Beverage:FDA 21 CFR substantiation and EFSA migration studies govern direct-contact clamshell designs. Fresh produce and ready-meal segments drive vacuum-formed PET volume, with EU Green Deal recycled content mandates compressing formulation validation timelines.
- Electronics:Anti-theft display mandates in Germany and France require tamper-evident configurations for consumer devices above threshold values. Bavarian contract manufacturers specify real-time thickness verification for anti-static clamshell shipments.
- Toys:REACH SVHC tracking redirects packaging away from legacy PVC toward compliant alternatives. Safety-critical applications demand hinge durability testing under EN 71 standards.
- Pharmaceuticals:CDSCO stability testing protocols in India create first-mover certification advantages for temperature-stable vaccine vial transport configurations. Mass merchandisers in Texas and California concentrate supplier rosters to 3-4 strategic partners with multi-site capacity.
Dominant by procurement concentration: Food & Beverage. Steepest certification ramp: Pharmaceuticals.
Shape:
Geometric configuration determines thermoforming process selection and tooling amortization economics. Custom cavity design absorbs capital investment priority as electronics manufacturers specify device-specific protection.
- Square:Standardized format minimizing tooling cost and maximizing sheet utilization. Retail-ready display applications in mass merchandise channels favor this geometry for shelf efficiency.
- Rectangular:Dominant electronics configuration accommodating circuit boards, accessories, and consumer devices. Dongguan manufacturing clusters generate concentrated demand with integrated hang-hole features.
- Oval:Premium cosmetic and personal care applications where differentiation drives specification. Higher tooling complexity limits adoption outside brand-conscious segments.
- Custom:Device-specific protection for high-value electronics requiring precise cavity matching. Digital sampling platforms enable Michigan and Ohio converters to capture specification authority directly with big-box buyers.
Highest volume: Rectangular. Fastest specification growth: Custom shapes in electronics.
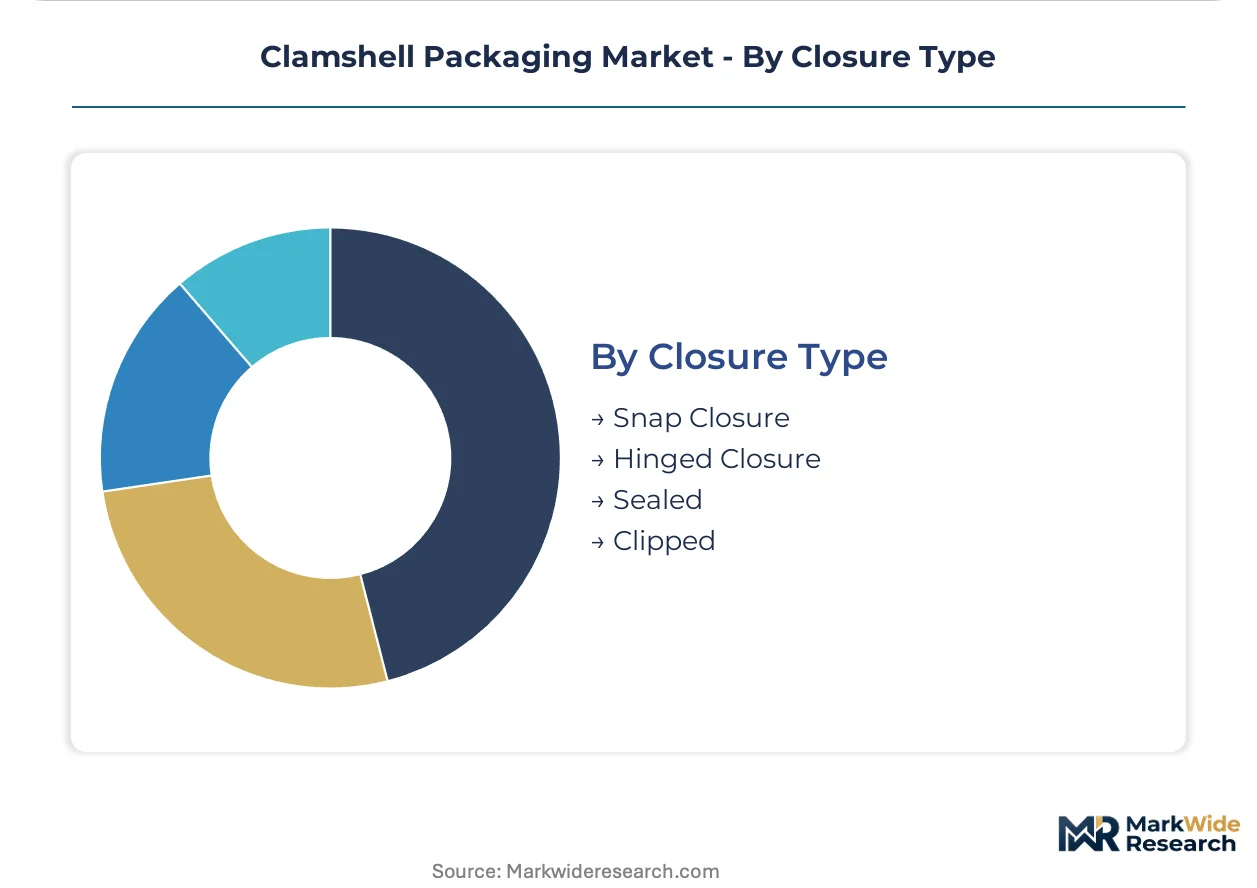
Closure Type:
Opening mechanism selection balances tamper evidence, resealability, and line-speed compatibility. Regulatory mandates in European retail channels are elevating snap and sealed configurations over clipped alternatives.
- Snap Closure:Integral hinge with interlocking features enabling repeated opening. Electronics anti-theft mandates in France and Germany specify this configuration for display-floor protection.
- Hinged Closure:Continuous fold joining matched halves, the defining characteristic of clamshell architecture. Standard across food and industrial applications where resealability is secondary.
- Sealed:Permanent fusion of perimeter edges delivering maximum tamper evidence. Pharmaceutical cold chain and high-value electronics specify ultrasonic or RF sealing for integrity assurance.
- Clipped:Removable fasteners enabling non-destructive opening. Declining share in regulated channels as tamper-evident requirements tighten.
Most widely specified: Hinged Closure. Gaining regulatory preference: Sealed configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan and Shenzhen anchor global clamshell manufacturing density, with Pearl River Delta export clusters generating concentrated demand for retail-ready protective packaging. Guangdong province thermoforming capacity supplies electronics contract manufacturers requiring anti-static formulations and integrated hang-hole features. Zhejiang province complements this ecosystem with specialized converters serving consumer goods exporters.
China
Export-oriented manufacturing in Shenzhen and Dongguan drives vacuum-formed PET volume for electronics protection. The country's dual carbon goals pressure converters toward energy-efficient thermoforming lines. Guangdong province hosts over half of global export-grade capacity within 200 kilometers of Pearl River Delta ports.
Germany
Bavarian electronics contract manufacturers specify real-time thickness verification for anti-static clamshell shipments. The EU Green Deal mandates 30% post-consumer recycled content thresholds by 2030, compressing converter certification timelines. Baden-Württemberg automotive suppliers are piloting custom cavity designs for device-specific protection.
United States
Michigan and Ohio converters capture specification authority with big-box electronics buyers through digital sampling platforms. EPA Clean Air Act Title V permitting governs volatile organic compound emissions from thermoforming operations. Texas and California mass merchandisers concentrate pharmaceutical clamshell supplier rosters to 3-4 strategic partners.
India
Temperature-stable clamshell configurations for vaccine vial transport remain underdeveloped, creating first-mover opportunities. CDSCO stability testing protocols establish certification barriers for cold chain packaging entrants. Maharashtra pharmaceutical clusters generate concentrated demand for tamper-evident sealed configurations.
France
Anti-theft display mandates for consumer devices above threshold values pull vacuum-formed PET into standard merchandising protocols. REACH Article 33 substance-of-very-high-concern tracking redirects electronics packaging from legacy PVC toward compliant alternatives. Île-de-France retail headquarters coordinate pan-European supplier qualification programs.
Clamshell Packaging Market Vendor Landscape
Premium-margin players sit above commodity-margin players across recycled content certification and multi-site molding capacity. The vendor base stratifies into integrated resin sourcers, regional thermoforming specialists, and diversified packaging conglomerates. Three archetypes dominate: rPET-integrated converters with mass-balance chain of custody, precision electronics-focused fabricators with digital quality systems, and foodservice-anchored players with proprietary recycled material streams. Competitive moves concentrate on backward integration into flake supply and geographic consolidation to serve pan-European retailer mandates.
Among diversified packaging conglomerates, Amcor Limited and Sonoco Products Company occupy positions spanning multiple substrate categories and end-use channels. Sealed Air Corporation exemplifies the scale-driven archetype with thermoforming operations integrated into broader protective packaging portfolios. Placon Corporation anchors the North American foodservice segment through proprietary recycled material streams, representing the specialist model of captive feedstock control.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Placon Corporation |
| Amcor Limited |
| Dart Container Corporation |
| D&W Fine Pack |
| Sonoco Products Company |
| Pactiv LLC |
| Plastic Ingenuity |
| Berry Global Inc. |
| Others |
Supply Flow & Price Mechanics
Captive rPET flake sourcing anchors both supply security and margin protection for converters serving EU Green Deal mandates. Backward integration into post-consumer bottle reclaiming separates premium-positioned thermoformers from spot-market resin buyers facing feedstock competition from beverage reclaimers.
Pricing Analysis
Throughput-linked pricing models dominate contract structures between converters and pan-European retailers, with certified mass-balance chain of custody commanding tiered premiums. Price differentiation separates rPET-integrated suppliers from virgin-material competitors and spot-market dependent players. Cost compression in standard-grade PET clamshells intensifies as Guangdong export manufacturers absorb thin-margin volume. Mass merchandisers exhibit highest price sensitivity in pharmaceutical categories where specification uniformity outweighs unit cost, while electronics contract manufacturers prioritize thickness verification and anti-static performance over base price.
Supply Chain Analysis
Freight cost absorption from Pearl River Delta ports to European distribution centers constrains margin structures for China-anchored export supply. Thermoforming capacity concentrates in China, Germany, and the United States, with raw material dependencies spanning virgin PET resin, post-consumer flake, and polypropylene homopolymer. Single-source vulnerability runs through Guangdong-Zhejiang manufacturing clusters where regional energy rationing disrupts export-grade output. Distribution runs through direct-to-retailer digital sampling platforms and traditional distributor networks serving mass merchandise channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's 30% post-consumer recycled content threshold erects a certification moat that favors incumbent converters with validated mass-balance systems and penalizes entrants lacking established rPET supply relationships.
For Market Incumbents: To counter feedstock competition from beverage bottle reclaimers, deepen backward integration into post-consumer flake collection and washing infrastructure. Secure dedicated supply agreements with pan-European retailers before certification deadlines compress vendor qualification windows. For New Entrants and Emerging Players: Capture underdeveloped temperature-stable configurations for Indian pharmaceutical cold chain applications where CDSCO stability testing protocols create first-mover certification advantages. Pursue direct-to-retailer digital sampling platforms to bypass entrenched distributor relationships in North American electronics channels. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified packaging conglomerates seeking rPET-integrated capacity and pan-European retailer relationships. Five-to-ten year viability favors converters with captive flake supply and multi-site thermoforming footprints. Monitor EU member state implementation timelines for recycled content mandates as inflection signals for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Supply | Captive post-consumer feedstock secures preferred supplier status with EU retailers facing Green Deal mandates. |
| Digital Sampling Platform Deployment | Michigan and Ohio converters capture specification authority directly with big-box electronics buyers, bypassing traditional distribution. |
| Multi-Site Thermoforming Capacity Expansion | Geographic consolidation satisfies mass merchandiser requirements for specification uniformity across Texas and California distribution centers. |
| CDSCO Stability Testing Certification | First-mover validation for temperature-stable vaccine vial transport creates defensive positioning in Indian pharmaceutical cold chain. |
| Real-Time Thickness Verification System Installation | Bavarian electronics contract manufacturers specify sensor-integrated quality assurance for anti-static clamshell shipments. |
Methodological Framework
Independent corroboration across thermoforming plant managers, procurement leads at downstream OEMs, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC filings of publicly traded packaging conglomerates, and EU regulatory implementation notices. Bottom-up capacity assessments across Guangdong and Zhejiang manufacturing clusters triangulate with top-down demand estimates from electronics contract manufacturers and mass merchandiser procurement data.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. The analytical framework models segmentation dimensions including material substrate, end-use application, closure configuration, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation adjusted for EU Green Deal compliance ramps and rPET feedstock availability constraints. Industry-specific forecast inputs incorporate thermoforming line utilization rates and FDA 21 CFR substantiation timelines for direct-food-contact designs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU member state enforcement intensity and post-consumer PET bale competition dynamics. Forecasts reflect assumptions about regulatory implementation pace and feedstock market development that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Insulated Icebox Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Snap Single Dose Dispensers Market
Packaging Containers
Can Holders Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Correx Trays Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Candle Box Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Insulated Food Containers Market