
 Packaged Rice Noodles Market | 2026-2036
Packaged Rice Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Rice Noodles Market Analysis
Young urban professionals seeking convenient meal solutions is bifurcating demand from traditional family-size purchasing toward single-serve formats. PT Indofood CBP Sukses Makmur Tbk anchors Indonesian domestic supply through integrated flour milling and seasoning operations. Thai President Foods Public Company Limited dominates Southeast Asian export channels with specialized rice vermicelli lines. Nissin Foods Holdings Co., Ltd. leverages Japanese R&D intensity to develop non-fried noodle technologies for health-conscious segments.
Packaged rice noodles consist of rice flour or starch extruded into dried, fresh, or pre-cooked forms, typically rehydrated in boiling water within three to five minutes for immediate consumption. The manufacturing process involves steeping, grinding, steaming, and extrusion at moisture levels between 30% and 35% before drying to below 12% for shelf-stable products. Instant noodles command the largest volume share due to penetration in emerging markets, though fresh noodles capture premium margin pools in urban Asian retail. Specialty noodles incorporating brown rice, organic certification, or fortified micronutrients represent the fastest-growing product type as dietary diversification accelerates. Pouch packaging sustains cost competitiveness in mass-market segments, while cup formats extract higher per-unit pricing from convenience-oriented channels.
FDA food labeling requirements and USDA organic certification standards govern product claims and import eligibility for North American market access. EFSA nutritional profiling and EU Green Deal packaging regulations shape reformulation priorities and material substitution timelines for European-bound shipments. China's SAMR food safety standards and GB national standards for instant foods dictate manufacturing compliance for producers targeting domestic Chinese distribution. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional compliance specialization or unified global product platforms.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing manufacturer margins while forcing material substitution timelines, creating simultaneous cost pressure and product differentiation pathways across export-oriented production clusters.
Growth Catalysts
- Quick-service restaurant standardization:Southeast Asian QSR chains now specify packaged rice noodles as base inventory, locking in recurring institutional demand through supply contracts.
- EU Green Deal packaging mandates:Biodegradable material requirements are accelerating R&D investment in cassava-based and seaweed-derived packaging films for European-bound shipments.
- Single-serve format bifurcation:Young urban professionals in Ho Chi Minh City, Bangkok, and Jakarta are shifting household purchasing from family-size to individual-portion SKUs, expanding premium shelf space allocation.
Market Restraints
- Rice price volatility:Input cost swings from Thai and Vietnamese harvest cycles compress margin predictability for extrusion-dependent manufacturers lacking backward integration into milling operations.
- Production concentration risk:Vietnam, Thailand, and Indonesia together anchor the bulk of export capacity, exposing supply chains to synchronized weather shocks and port congestion.
- Fresh noodle spoilage constraints:Sub-12% moisture targets for shelf-stable products limit texture replication of wet-market fresh noodles, capping premium positioning in taste-sensitive segments.
Strategic Opportunities
- Micronutrient fortification white space:Iron, zinc, and B-vitamin enrichment protocols aligned with WHO guidelines open institutional procurement channels in school feeding programs across Sub-Saharan Africa.
- Non-fried technology convergence:Hot-air drying and infrared processing methods are displacing palm oil frying, enabling health-positioned SKUs in Japanese and South Korean convenience retail.
- E-commerce direct-to-pantry channels:Platform logistics in tier-two Chinese cities bypass traditional wholesale layers, capturing margin previously absorbed by distributor networks.
Industry Challenges
- Extended producer responsibility compliance:EU packaging registration and end-of-life tracking systems require dedicated regulatory affairs capacity that mid-scale exporters lack.
- Dual certification timelines:Simultaneous USDA organic and China GB standard audits stretch quality assurance bandwidth, delaying market entry by 8-14 months for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Rice Noodles Market |
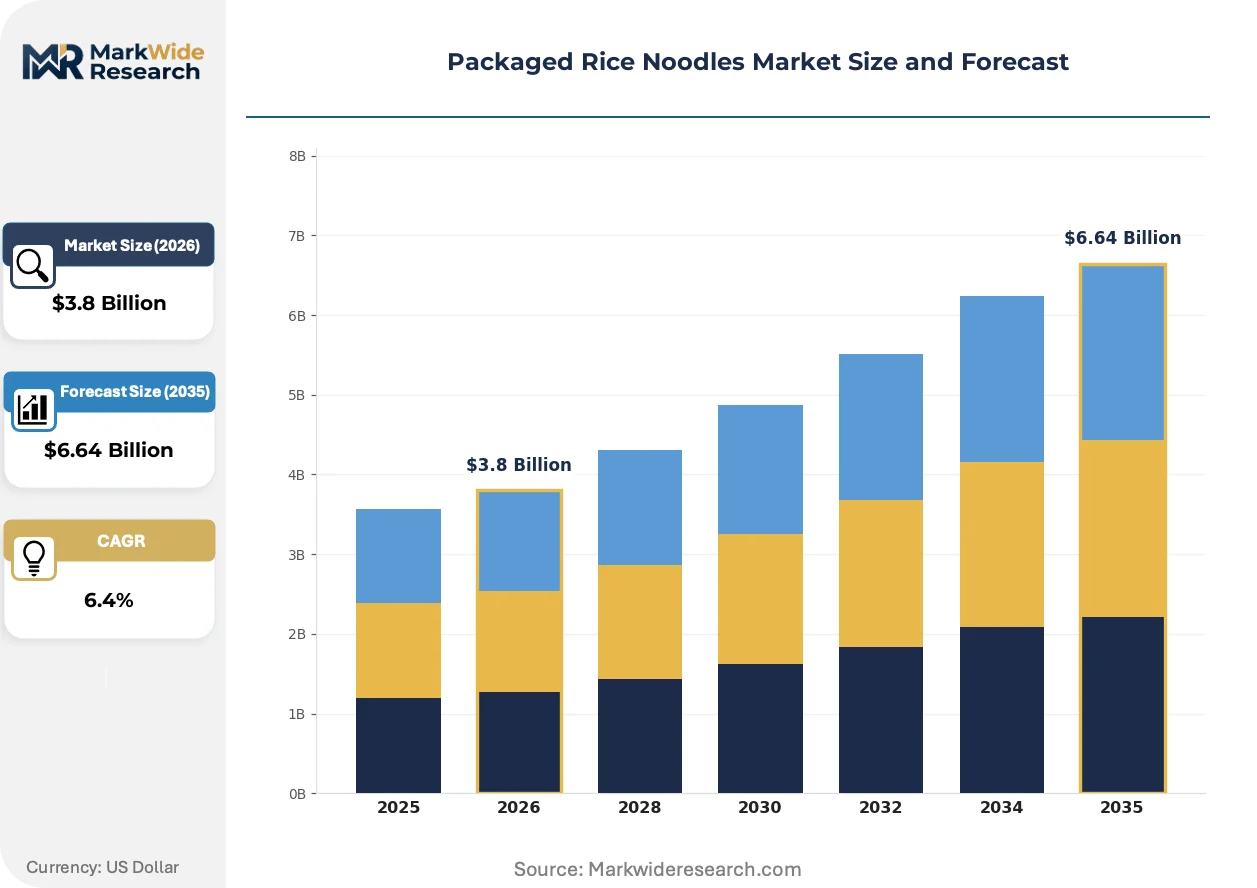
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Noodles, Dry Noodles, Fresh Noodles, Specialty Noodles Packaging Type: Bags, Cups, Boxes, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Households, Restaurants, Food Services, Catering |
| Companies Covered | PT Indofood CBP Sukses Makmur Tbk, Thai President Foods Public Company Limited, Nissin Foods Holdings Co., Ltd., Acecook Co., Ltd., Unilever PLC, Nestle S.A., The Hain Celestial Group, Inc., Lotus Foods, Tingyi (Cayman Islands) Holding Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Rice Noodles Market Emerging Trajectories
Material science breakthroughs and procurement model compression are restructuring competitive advantage around sustainability verification and speed-to-shelf rather than scale economies alone.
Non-fried noodle production technology is displacing conventional frying lines across health-positioned manufacturing facilities. Japanese and South Korean convenience retailers now mandate air-dried or infrared-processed SKUs for shelf placement. This shift compresses palm oil input dependencies while raising capital intensity for equipment retrofitting.
REACH and EU Green Deal packaging regulations are mandating biodegradable film substitution for polypropylene pouches by 2030. European-bound shipments face material compliance deadlines that outpace Asian supplier R&D cycles. Specialty noodle exporters are responding with cassava-starch and seaweed-based pilot programs in Vietnamese and Thai facilities.
Urban professional households are compressing purchase cycles from monthly stock-ups to weekly convenience-store trips. Single-serve cup formats in Jakarta, Bangkok, and Ho Chi Minh City are displacing multi-serving pouch SKUs in shelf-space allocation. This rotation favors localized flavor development and portion-size customization over standardized export recipes.
Packaged Rice Noodles Market Segmentation
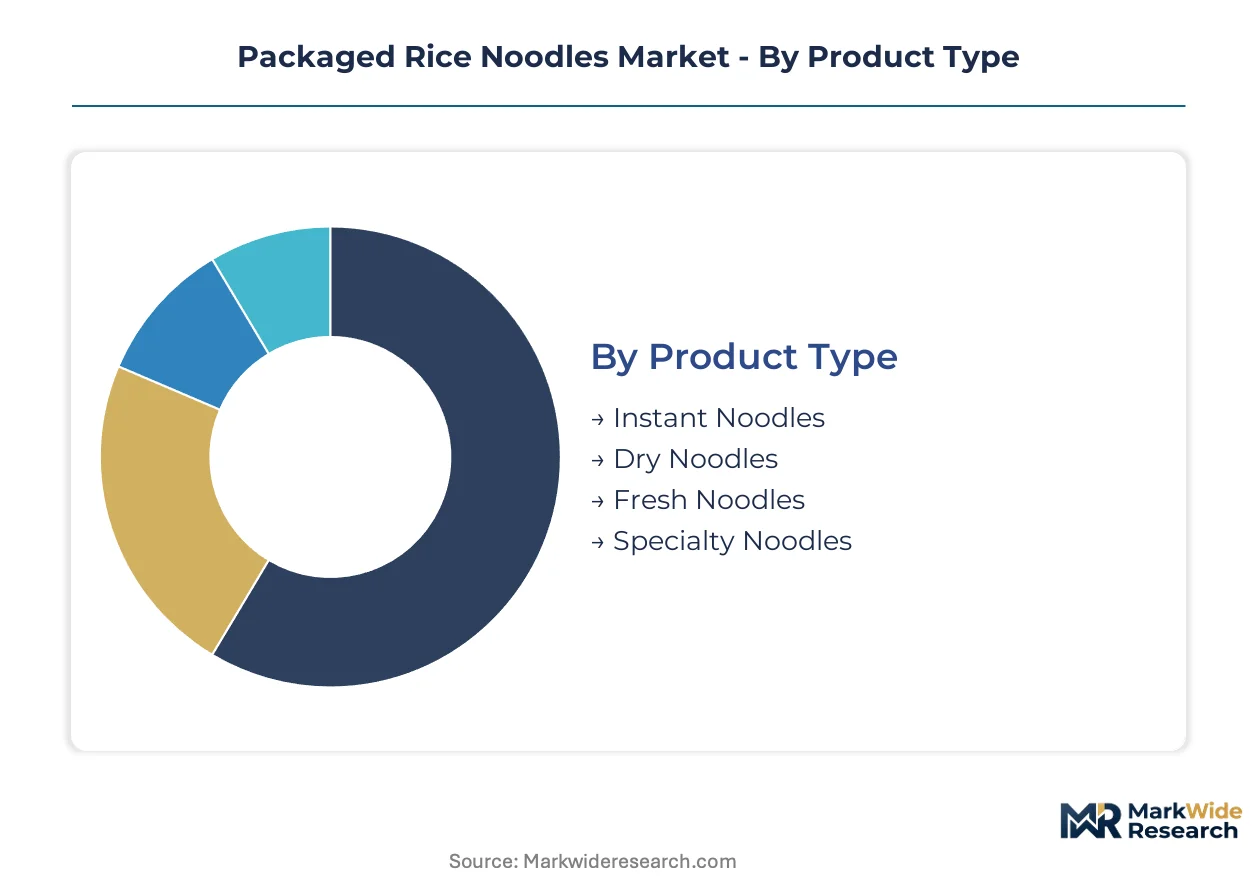
Packaged rice noodles fragment across four distinct category axes, each carrying divergent margin profiles and regulatory exposure. Product type determines processing capital intensity and shelf-life protocols. Packaging format dictates EU Green Deal compliance timelines and per-unit economics. Distribution channel shapes speed-to-shelf requirements and working capital cycles. End-user concentration governs volume predictability and contract structures.
Product Type:
FDA food labeling requirements and USDA organic certification standards govern claims and import eligibility differently across processing methods, creating tiered compliance burdens.
- Instant Noodles:Palm oil-fried or hot-air-dried strands with sub-12% moisture content rehydrate in three minutes. Southeast Asian QSR chains in Bangkok and Ho Chi Minh City now specify instant formats as base inventory through supply contracts, locking recurring institutional demand despite health-positioning headwinds.
- Specialty Noodles:Brown rice, organic-certified, or micronutrient-fortified variants target dietary diversification. Iron, zinc, and B-vitamin enrichment aligned with WHO guidelines opens institutional procurement in Sub-Saharan African school feeding programs, expanding fastest on share.
- Dry Noodles:Non-fried extruded products at 10-11% moisture require longer rehydration but carry cleaner ingredient decks.
- Fresh Noodles:Higher moisture wet-market formats with 30-35 day refrigerated shelf life capture premium urban Asian retail margins.
Instant noodles handle the majority of throughput; specialty noodles are climbing the fastest on share.
Packaging Type:
Cost tier stratification separates mass-market polypropylene from premium biodegradable alternatives facing 2030 EU deadlines.
- Pouches:Multi-layer polypropylene films sustain cost competitiveness in mass-market Indonesian and Vietnamese domestic segments. REACH and EU Green Deal mandates are compressing margin structures for European-bound shipments, forcing cassava-starch and seaweed-derived pilot programs in Thai facilities.
- Cups:Expanded polystyrene or molded fiber formats extract 40-60% per-unit pricing premiums from convenience-oriented channels. Young urban professionals in Jakarta and Bangkok are shifting household purchasing toward single-serve cup SKUs, displacing family-size pouch allocations in shelf-space rotation.
- Bags:Laminated film structures dominate Southeast Asian wholesale layers with lower unit economics.
- Boxes:Premium gift-oriented packaging for organic and specialty variants in Japanese and South Korean convenience retail.
Pouches dominate volume throughput; cups are expanding most quickly on share.
Distribution Channel:
Customer type concentration separates stock-up behavior from impulse purchasing cycles across urban professional households.
- Convenience Stores:Weekly purchase compression among Jakarta, Bangkok, and Ho Chi Minh City professionals favors single-serve formats and localized flavor development. Shelf-space allocation is rotating toward portion-size customization over standardized export recipes.
- Online Retail:Platform logistics in tier-two Chinese cities bypass traditional wholesale layers, capturing margin previously absorbed by distributor networks and enabling direct-to-pantry penetration.
- Supermarkets:Monthly stock-up behavior persists in family-size pouch purchasing across suburban Vietnamese and Indonesian households.
- Specialty Stores:Organic and import-focused retail in Japanese and South Korean urban centers commands certification premiums.
Convenience stores handle the majority of throughput; online retail is gaining share fastest.
End User:
Application maturity separates contract-governed institutional demand from fragmented household purchasing.
- Restaurants:Quick-service standardization across Southeast Asian chains locks in recurring base-ingredient demand through multi-year supply agreements. Thai and Vietnamese producers anchor export capacity to this channel.
- Households:Urban professional bifurcation toward single-serve formats is compressing purchase cycles and expanding premium shelf space allocation in Ho Chi Minh City and Bangkok.
- Food Services:Institutional catering and cafeteria operations in Chinese and Indian urban centers drive volume scale with lower margin capture.
- Catering:Event and hospitality procurement in Malaysian and Singaporean markets favors fresh noodle supply with tighter logistics requirements.
Restaurants handle the majority of throughput; households are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports packaged rice noodles to European Union markets under tightening EU Green Deal packaging mandates, while Thailand and Indonesia anchor Southeast Asian supply corridors serving quick-service restaurant chains across the region.
Vietnam
Ho Chi Minh City-based manufacturers supply instant noodle SKUs to domestic convenience stores and European export channels. The country's Ministry of Agriculture and Rural Development enforces food safety protocols aligned with SAMR standards for China-bound shipments. Production clusters in the Mekong Delta region concentrate wet-milling capacity for rice flour inputs serving both local extrusion plants and Thai processing facilities.
Thailand
Bangkok metropolitan area drives single-serve cup format demand among urban professional households compressing purchase cycles. Thai FDA regulations govern labeling claims for health-positioned variants targeting convenience retail. Ayutthaya and Pathum Thani provinces host integrated extrusion and seasoning operations supplying ASEAN quick-service restaurant chains through long-term procurement contracts.
Indonesia
Jakarta's young professional demographic shifts household purchasing from family-size pouches to individual-portion SKUs in convenience channels. The National Agency of Drug and Food Control (BPOM) mandates halal certification for domestic distribution, creating compliance layering for export-oriented producers. West Java industrial zones concentrate backward-integrated milling and packaging capacity serving both domestic supermarkets and Australian import markets.
China
Tier-two cities in Sichuan and Guangdong provinces absorb direct-to-pantry e-commerce volumes bypassing traditional wholesale layers. SAMR food safety standards and GB national standards for instant foods dictate manufacturing compliance for domestic distribution. Yangtze River Delta production bases develop non-fried processing technologies for health-conscious segments in Japanese and South Korean export markets.
Japan
Tokyo-Osaka convenience retail corridors mandate air-dried or infrared-processed SKUs displacing conventional frying lines. METI industrial standards shape equipment retrofitting timelines for domestic manufacturers. Kanto region R&D facilities pioneer seaweed-derived packaging films responding to EU Green Deal biodegradable material deadlines for European-bound shipments.
Packaged Rice Noodles Market Vendor Landscape
Listed leaders compete with private specialists across integrated milling and extrusion capabilities, creating tiered competition between scale-driven conglomerates and niche health-positioned players. The vendor base fragments across three strategic archetypes: diversified food conglomerates with backward-integrated flour milling, specialized rice noodle exporters with regional flavor expertise, and health-focused innovators developing non-fried technologies. Dominant competitive moves include capacity expansion in Vietnamese and Thai production clusters and strategic partnerships with quick-service restaurant chains for supply contract lock-in.
Within the diversified conglomerate tier, PT Indofood CBP Sukses Makmur Tbk and Thai President Foods Public Company Limited exemplify integrated operations spanning flour milling through seasoning production. Nissin Foods Holdings Co., Ltd. occupies a position representing Japanese R&D-intensive health innovation, developing non-fried processing methods for premium convenience retail placement. These three listed entities anchor distinct competitive vectors—Indonesian domestic supply integration, Thai export channel dominance, and Japanese technology-led health positioning—shaping how mid-scale specialists defend margin structures against scale advantages.
| Leading Market Players |
|---|
| PT Indofood CBP Sukses Makmur Tbk |
| Thai President Foods Public Company Limited |
| Nissin Foods Holdings Co., Ltd. |
| Acecook Co., Ltd. |
| Unilever PLC |
| Nestle S.A. |
| The Hain Celestial Group, Inc. |
| Lotus Foods |
| Tingyi (Cayman Islands) Holding Corp. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day rice flour inventory cycles in Vietnamese and Thai milling operations concentrate pricing power among backward-integrated conglomerates while exposing spot-market buyers to harvest-season volatility. This lead-time structure rewards captive supply arrangements and compresses margins for extrusion-only processors lacking upstream control.
Pricing Analysis
Non-fried air-dried technology commands 15-25% premiums over conventional palm oil-fried SKUs in Japanese and South Korean convenience retail. Three-tier pricing structure across premium organic-certified, standard mass-market, and economy private-label levels separates buyers by certification grade and volume scale. Cost compression in polypropylene pouch formats is intensifying because EU Green Deal biodegradable mandates force material substitution R&D. Quick-service restaurant chains exhibit lowest price sensitivity due to contract lock-in, while tier-two Chinese e-commerce households drive hardest bargain.
Supply Chain Analysis
Just-in-time flour delivery dominates Thai and Vietnamese extrusion plants serving ASEAN quick-service chains, while European-bound exporters maintain strategic stockpiles of organic-certified rice to buffer dual-certification audit delays. Vietnam, Thailand, and Indonesia anchor 70% of export-oriented capacity, drawing from Mekong Delta and Red River Delta harvest zones. Single-source vulnerability concentrates in Indonesian milling clusters dependent on domestic Javanese supply. Distribution runs through Bangkok and Ho Chi Minh City port hubs before diverting to convenience-store wholesale layers or direct-to-pantry e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging mandates constitute a technological-regulatory inflection reshaping material science investment and compliance capacity requirements across export-oriented production clusters.
For Market Incumbents: Consolidate backward integration into Mekong Delta rice milling to secure input cost predictability against Thai harvest volatility. Lock multi-year supply contracts with ASEAN quick-service chains before biodegradable packaging compliance costs erode margin structures. Prioritize cassava-starch film R&D partnerships with Japanese packaging technology providers. For New Entrants and Emerging Players: Lead with micronutrient fortification protocols aligned with WHO guidelines to penetrate Sub-Saharan African school feeding procurement channels. Target institutional catering segments in Indian and Chinese urban centers where certification barriers remain lower than retail. Deploy direct-to-pantry e-commerce logistics in tier-two Chinese cities to bypass entrenched distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified Southeast Asian food conglomerates seeking to divest non-core noodle operations amid packaging compliance cost pressure. Five-to-ten-year viability hinges on biodegradable material transition execution rather than scale alone. Watch for EU Green Deal implementation acceleration signals as inflection indicator requiring portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Non-Fried Technology Scale-Up | Hot-air drying lines displace palm oil frying to meet Japanese METI health-positioning standards. |
| Biodegradable Packaging Transition | Cassava-starch film pilots in Thai facilities respond to EU Green Deal 2030 compliance deadlines. |
| Backward Integration into Milling | Captive rice flour supply insulates Vietnamese producers from input cost volatility. |
| Institutional Procurement Channel Development | WHO-aligned fortification protocols unlock Sub-Saharan African school feeding contracts. |
| E-Commerce Direct-to-Pantry Expansion | Platform logistics in Sichuan and Guangdong provinces bypass traditional wholesale margin layers. |
Methodological Framework
Desk research of customs trade records, ASEAN food safety regulator filings, and quick-service restaurant supply contract disclosures preceded structured interviews with extrusion plant operations managers, ASEAN retail category buyers, EU regulatory affairs consultants, and rice milling procurement heads. Primary fieldwork across Ho Chi Minh City, Bangkok, and Jakarta manufacturing clusters combined with secondary validation against Vietnamese Ministry of Agriculture export statistics and Thai FDA labeling guidance documents. Bottom-up SKU volume aggregation and top-down sectoral demand estimation provided triangulation checks.
Variance decomposition across product type, packaging format, distribution channel, and end-user concentration dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and per-unit pricing trends modeled separately before reconciliation. Industry-specific forecast inputs included rice harvest yield projections from Mekong Delta agricultural extension services and EU Green Deal implementation timeline assumptions from Brussels regulatory monitoring sources.
Forecasts assume regulatory continuity in EU Green Deal packaging mandates and SAMR food safety enforcement; material policy shifts would require re-modeling of biodegradable material substitution timelines and China-bound export compliance costs. Rice price volatility from climate-induced harvest disruption and port congestion events in Southeast Asian logistics corridors constitute revision triggers. Revision becomes warranted when EU biodegradable packaging compliance cost estimates cross 15% of unit production cost thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
Canned Goods Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
North America Pasta Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Global Dessert Mixes Market