
 Bread Flour Market | 2026-2036
Bread Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Flour Market Analysis
Artisan bakery chains are restructuring flour procurement toward higher-protein and specialty-grade bread flour. King Arthur Baking Company leverages its premium brand positioning to command shelf space in specialty retail channels. Ardent Mills sustains geographic dominance through its extensive North American milling network and direct bakery relationships. Nisshin Flour Milling anchors Asian supply security with integrated grain origination and ocean freight logistics.
Bread flour is a hard wheat flour with protein content typically ranging from 12% to 14%, milled from hard red spring or hard red winter wheat varieties and formulated to develop strong gluten networks for yeast-leavened bread production. Its primary commercial purpose is to provide structural integrity and volume in industrial, artisan, and home baking applications. The organic and whole wheat type segments are attracting margin pools as clean-label commitments from bakeries reshape ingredient specifications. Higher protein and specialty grades occupy the fastest-growing tier, driven by sourdough and long-fermentation trends that demand superior gluten performance.
The FDA sets standards of identity for flour enrichment and labeling in the United States, while the USDA oversees grain grading and quality inspection protocols that directly affect miller procurement decisions. In Europe, EFSA and national regulators enforce maximum residue limits for pesticides in wheat and mycotoxin thresholds that constrain import sourcing and domestic milling operations. Stakeholders must monitor how climate-driven wheat quality variability and evolving clean-label regulations reshape formulation requirements and supplier qualification criteria.
Market Dynamics
Artisan bakery chains are restructuring flour procurement toward higher-protein and specialty-grade bread flour, while the EU Green Deal and F-Gas Regulation press millers to reduce energy intensity in milling operations. This dual pressure on input specifications and process efficiency is reshaping supplier qualification criteria and capital allocation across the value chain.
Growth Catalysts
- Clean-label mandates:Bakeries are reformulating recipes to eliminate artificial additives, driving specification changes toward organic and whole wheat flour types that command premium positioning.
- Sourdough fermentation revival:Long-fermentation bread trends demand superior gluten performance, concentrating procurement of 13-14% protein hard wheat varieties from specific North American and Black Sea growing regions.
- EU Green Deal compliance:The F-Gas Regulation is forcing millers to retrofit pneumatic conveying and tempering systems with lower-global-warming-potential refrigerants and heat recovery technology.
Market Restraints
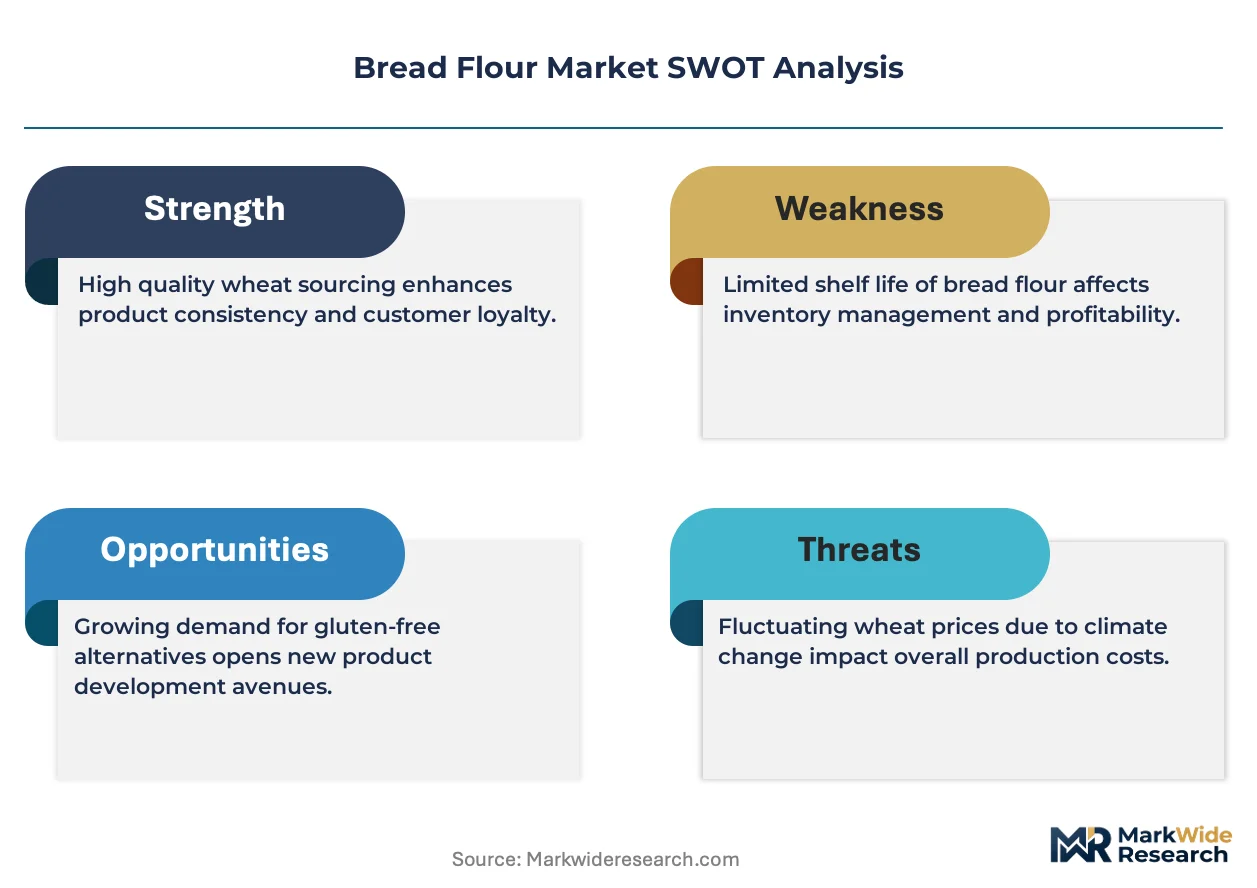
- Hard wheat supply concentration:Premium high-protein bread flour depends on hard red spring wheat from the US Northern Plains and Canadian Prairies, creating origination risk during drought cycles.
- Energy cost volatility:Roller milling and pneumatic conveying are electricity-intensive; European millers face structurally higher power costs than competitors in grain-exporting nations.
- Protein content variability:Climate-driven wheat quality fluctuations force millers to blend more aggressively, compressing margins on fixed-price bakery contracts.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Vietnam and Indonesia exhibit rising Western-style bread consumption with limited domestic high-protein wheat milling capacity, creating import substitution potential.
- Carbon labeling differentiation:The EU Green Deal's emerging carbon border adjustments will reward millers with verified low-carbon milling processes and regenerative agriculture sourcing.
- Direct-to-bakery digital platforms:Specialty flour producers are bypassing traditional distributor networks to capture margin and capture formulation data from artisan bakery chains.
Industry Challenges
- Milling engineering talent scarcity:Modern roller mill automation and optical sorting technology require technicians with cross-disciplinary skills in mechanical engineering and data analytics that traditional training pipelines do not produce.
- Certification timeline compression:Organic and regenerative agriculture certifications require multi-year field transitions, creating supply gaps during demand surges that cannot be filled by conventional suppliers.
- Legacy equipment integration:Retrofitting century-old mill buildings with energy-efficient pneumatic systems and dust containment infrastructure requires custom engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Flour Market |
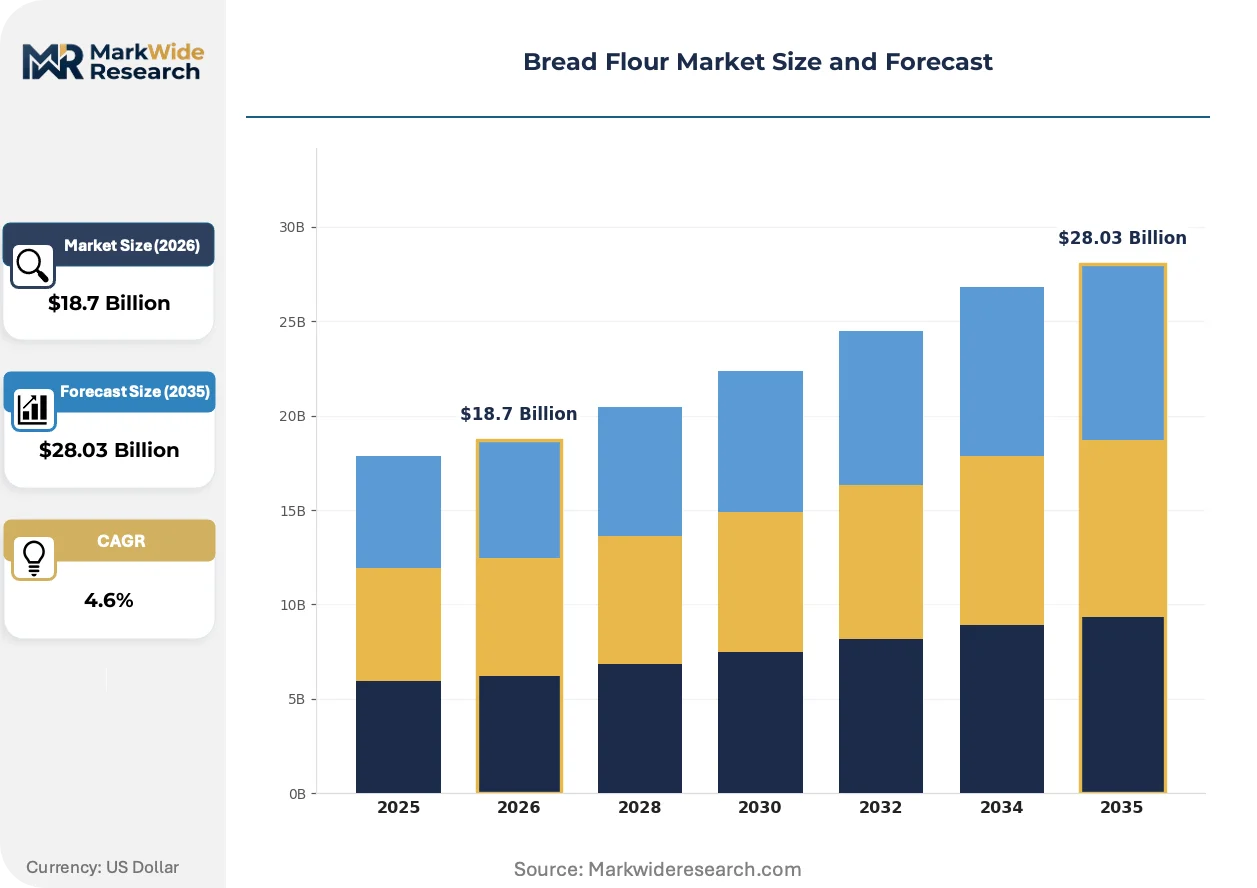
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Whole Wheat, All-Purpose, Bread, Organic Packaging Type: Bags, Boxes, Bulk, Sachets End Use: Bakeries, Home Baking, Industrial, Food Service Grade: Higher Protein, Unbleached, Bleached, Specialty |
| Companies Covered | Nisshin Flour Milling, Interflour Group, Archer Daniels Midland Company, Bob's Red Mill Natural Foods, Acarsan Holding, Ardent Mills, Allied Pinnacle, King Arthur Baking Company, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Flour Market Emerging Trajectories
Flour milling is absorbing digital process control and optical sorting technologies that were developed for other commodity processing industries. These innovations are compressing quality variability and enabling lot-level traceability that artisan bakeries now specify in procurement contracts.
Near-infrared spectroscopy paired with machine learning algorithms is absorbing quality control functions that previously required laboratory analysis. North American and European millers are deploying inline protein and moisture sensors to adjust blending ratios in real time. This technology is absorbing the cost of quality assurance labor while enabling consistent gluten performance across variable wheat harvests.
The EU F-Gas Regulation is accelerating refrigerant transitions in pneumatic flour conveying and tempering systems. Millers in Germany, France, and Italy are retrofitting facilities with ammonia-based or transcritical CO2 systems to avoid phasedown penalties. This regulatory pressure is absorbing capital that might otherwise expand capacity, concentrating investment among larger integrated millers with balance sheet flexibility.
Artisan bakery chains are consolidating supplier relationships around fewer flour partners who can deliver consistent protein specifications and regenerative agriculture documentation. This buyer concentration is displacing fragmented procurement through regional distributors. Germany's craft bakery culture exhibits this pattern most visibly, with chains like Zeit für Brot and Joseph Brot specifying single-origin wheat and transparent supply chain mapping.
Bread Flour Market Segmentation
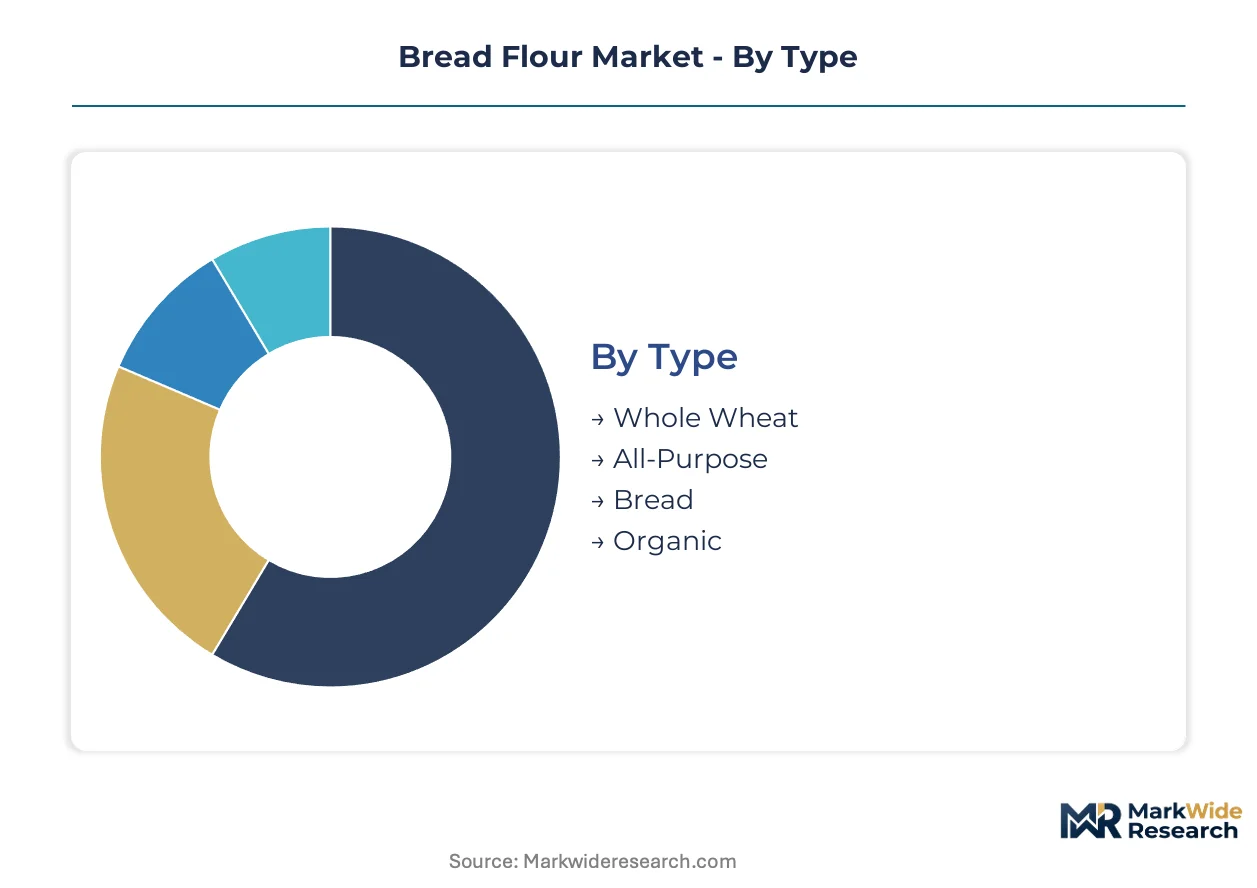
Bread flour segmentation reveals how protein specifications, packaging formats, and end-use applications concentrate margin pools across distinct supply configurations. Millers configure production lines and procurement networks differently for each segment tier, creating divergent competitive positions.
Type:
Supply concentration in hard wheat origination zones determines which flour types command premium positioning and operational priority at major millers.
- Whole Wheat:Milled from entire wheat kernels including bran and germ, delivering higher fiber content and denser crumb structure. German craft bakeries like Zeit für Brot specify whole wheat for clean-label product lines, though bran interference with gluten development limits volume in industrial applications.
- All-Purpose:Versatile blend of hard and soft wheats with moderate protein content around 10-12%, serving as the default flour for small-scale bakeries and home bakers lacking specialized inventory. US Northern Plains hard red winter wheat supplies the hard wheat component for North American all-purpose production.
- Bread:Hard wheat flour with 12-14% protein content formulated specifically for yeast-leavened applications requiring strong gluten networks. Artisan bakery chains concentrate procurement here for sourdough and long-fermentation breads.
- Organic:Certified organic wheat flour produced without synthetic pesticides or fertilizers, commanding price premiums from clean-label committed bakeries. Multi-year field transitions create supply gaps during demand surges.
Bread flour absorbs the bulk of installed capacity; organic is expanding most quickly.
Packaging Type:
Cost tier differentiation separates packaging formats, with bulk delivery minimizing unit costs for high-volume users while smaller formats capture convenience premiums.
- Bags:Standard 5-pound and 50-pound paper or poly-woven bags dominate retail and small commercial channels. King Arthur Baking Company leverages premium bag design and branding to command shelf space in specialty retail.
- Boxes:Corrugated containers protecting flour during distribution to food service and institutional buyers. European millers increasingly specify recyclable box materials to satisfy EU Green Deal packaging requirements.
- Bulk:Tanker truck or railcar delivery to large industrial bakeries and milling facilities, eliminating packaging costs entirely. Ardent Mills sustains geographic dominance through bulk distribution infrastructure across its North American network.
- Sachets:Single-serve packets for food service portion control and home baking convenience, carrying highest per-unit packaging costs but enabling trial and travel use cases.
Bulk delivery absorbs the bulk of volume throughput; sachets are climbing the fastest on convenience positioning.
End Use:
Customer type concentration shapes formulation specifications, with artisan chains demanding traceable single-origin wheat while industrial buyers prioritize consistency and cost.
- Bakeries:Artisan and craft bakeries driving specification toward higher-protein and specialty grades with regenerative agriculture documentation. Germany's craft bakery culture sustains premium flour consumption through chains specifying transparent supply chain mapping.
- Home Baking:Retail-packaged flour for consumer use, with pandemic-era baking surges permanently expanding the home baker segment. All-purpose and bread flour types dominate this channel.
- Industrial:Large-scale commercial bread production requiring consistent protein specifications and long-term contract pricing. Industrial buyers blend aggressively to manage wheat quality variability.
- Food Service:Restaurants, hotels, and institutional kitchens using flour for in-house bread programs or prepared items. This segment concentrates in urban clusters with strong food service density.
Industrial end use absorbs the bulk of volume; artisan bakeries are gaining share fastest on premium positioning.
Grade:
Margin concentration aligns with protein tier and processing intensity, with higher grades capturing value from gluten performance and clean-label positioning.
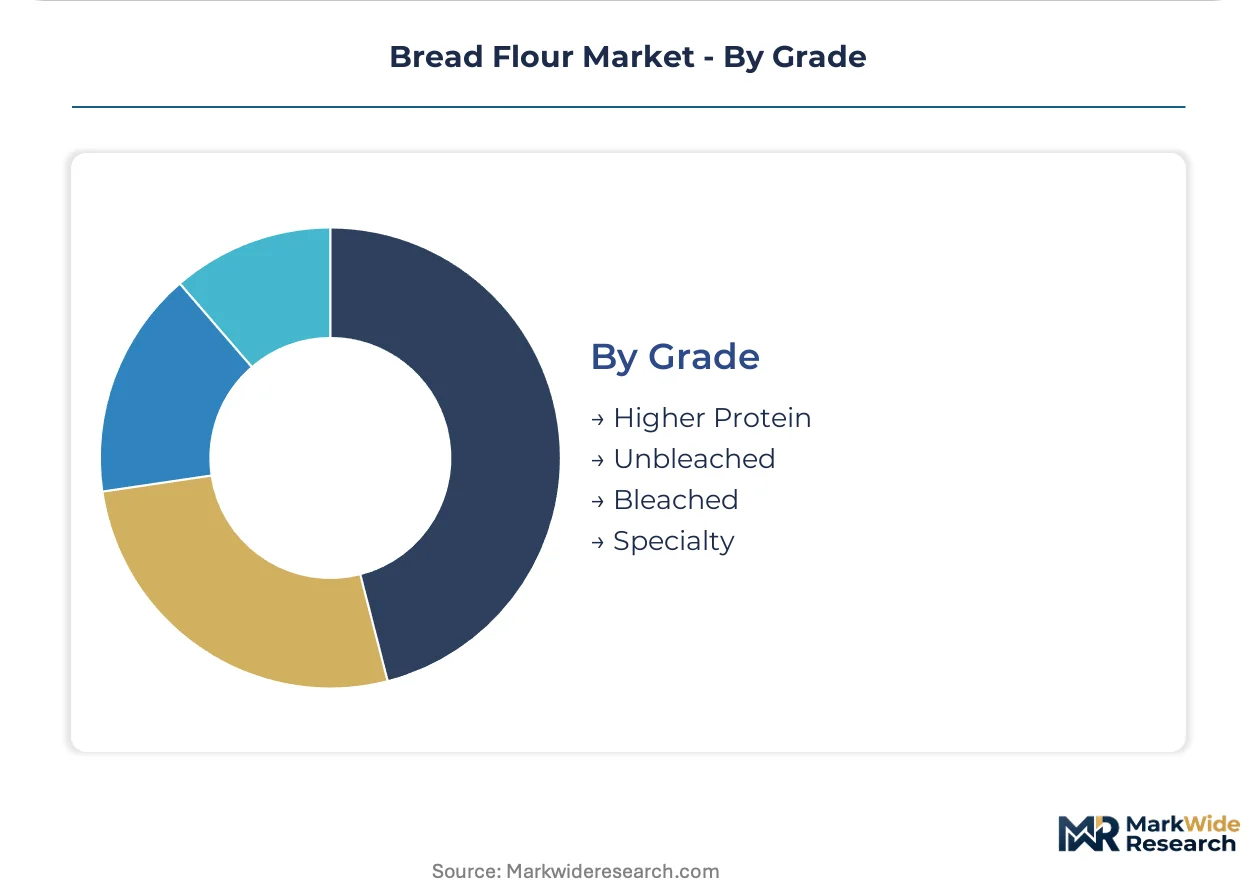
- Higher Protein:Flour exceeding 13.5% protein content from hard red spring wheat, delivering superior gluten strength for sourdough and long-fermentation applications. Sourdough revival trends concentrate demand in this tier.
- Unbleached:Naturally aged flour without chemical whitening agents, satisfying clean-label requirements from bakeries eliminating artificial additives. EFSA and national regulators enforce maximum residue limits that reinforce unbleached positioning.
- Bleached:Chemically treated flour with whiter appearance and softer texture, still dominant in industrial applications prioritizing consistency and cost over clean-label positioning.
- Specialty:Heritage wheat varieties, single-origin, or regenerative agriculture certified flours commanding highest premiums. Certification timelines create supply constraints during demand surges.
Bleached flour absorbs the bulk of industrial capacity; specialty grades are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hard red spring wheat production concentrates in the US Northern Plains and Canadian Prairies, while consumption gravity pulls toward craft bakery clusters in Germany, artisan revival markets in France, and industrial baking corridors in Japan. This geographic split between grain origination and premium flour demand shapes cross-border trade flows and supplier qualification networks.
United States
North Dakota and Montana hard red spring wheat supplies premium protein grades for sourdough revival trends. The FDA enforces flour enrichment standards that constrain formulation flexibility for clean-label bakeries. Minneapolis-St. Paul anchors North American milling infrastructure with integrated grain terminals and rail distribution networks serving industrial bakeries.
Germany
Zeit für Brot and Joseph Brot chains specify single-origin wheat with transparent supply chain mapping for craft product lines. The EU Green Deal and F-Gas Regulation force millers to retrofit pneumatic conveying systems with lower-global-warming-potential refrigerants. Bavaria's craft bakery culture sustains premium flour consumption through regenerative agriculture certification requirements.
France
Artisan boulangeries drive procurement toward heritage wheat varieties and stone-milled specialty grades. EFSA enforces maximum residue limits for pesticides in wheat that constrain import sourcing from non-EU origins. The Paris Basin concentrates milling capacity serving both industrial baguette production and premium artisan channels.
Japan
Western-style bread consumption expands in Tokyo and Osaka metro areas with limited domestic high-protein wheat milling capacity. METI oversees grain import quotas that protect domestic farmers while permitting strategic wheat purchases from Australia and North America. Kanto region industrial bakeries blend aggressively to compensate for variable imported wheat protein content.
Canada
Prairie hard red spring wheat exports anchor global premium bread flour protein specifications. The Canadian Grain Commission enforces grading protocols that directly affect miller procurement decisions across North American and Asian markets. Manitoba and Saskatchewan grain elevators concentrate origination infrastructure with direct rail links to Vancouver and Thunder Bay export terminals.
Bread Flour Market Vendor Landscape
Top-tier vendors anchor integrated milling networks with direct bakery relationships, while regional specialists occupy heritage wheat and organic certification niches. The market exhibits tiered concentration around scale-driven millers, specialty-grade artisans, and grain-trading conglomerates with captive flour divisions. Strategic archetypes include protein-specification leaders, regenerative agriculture certifiers, and geographic-dominance players with bulk distribution infrastructure. Competitive moves concentrate on M&A to secure origination assets and capacity expansion in underpenetrated Southeast Asian markets.
Within the premium specialty tier, King Arthur Baking Company occupies a position exemplifying brand-driven shelf space capture in specialty retail channels. Ardent Mills anchors scale-driven competitive positioning through extensive North American milling infrastructure and direct industrial bakery relationships. Nisshin Flour Milling represents integrated supply security archetypes with captive grain origination and ocean freight logistics serving Asian markets. These three entities illustrate how protein specification control, geographic coverage density, and supply chain integration separate competitive tiers in bread flour procurement.
| Leading Market Players |
|---|
| Nisshin Flour Milling |
| Interflour Group |
| Archer Daniels Midland Company |
| Bob's Red Mill Natural Foods |
| Acarsan Holding |
| Ardent Mills |
| Allied Pinnacle |
| King Arthur Baking Company |
| General Mills |
| Others |
Supply Flow & Price Mechanics
Artisan bakery chains specifying single-origin wheat with regenerative agriculture documentation are forcing millers to reconfigure procurement networks around traceable hard red spring wheat from the US Northern Plains and Canadian Prairies, compressing margins on fixed-price contracts while enabling protein-premium capture for verified supply chains.
Pricing Analysis
Short lead-time premiums dominate pricing for artisan bakery chains requiring lot-level traceability and rapid formulation adjustments. Three-tier pricing structure across specialty, premium, and commodity levels separates regenerative-certified heritage varieties from standard organic and conventional grades. Pricing pressure stems from energy cost volatility in European milling operations where the EU F-Gas Regulation mandates capital-intensive retrofits. Industrial bakeries exhibit highest price sensitivity due to volume scale and blending flexibility, while craft chains absorb premiums for transparent supply chain documentation.
Supply Chain Analysis
Regional distribution centers in Minneapolis-St. Paul, Rotterdam, and Vancouver anchor hub-and-spoke patterns serving industrial bakeries and artisan chains respectively. Hard red spring wheat concentrates in North Dakota, Montana, and the Canadian Prairies, with secondary origination from the Black Sea region during drought cycles in North America. Milling operations draw from tempering systems, roller mills, and pneumatic conveying infrastructure with refrigerant-dependent cooling stages. Single-source vulnerability runs through concentrated hard wheat origination zones where climate-driven quality fluctuations force aggressive blending. Distribution runs through bulk rail and tanker truck for industrial buyers, with bagged specialty formats for retail and artisan channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated millers with balance sheet flexibility to absorb EU Green Deal compliance costs, forcing regional specialists and undifferentiated commodity producers toward exit or acquisition.
For Market Incumbents: Deploy optical sorting and inline protein sensing technology to compress quality variability and defend formulation partnerships with artisan chains against emerging precision-milling entrants. Backward integration into grain origination assets in the Northern Plains secures protein specification control during drought cycles. Capacity consolidation in Southeast Asian import markets captures Western-style bread consumption growth where domestic milling capacity remains limited. For New Entrants and Emerging Players: Launch via direct-to-bakery digital platforms bypassing traditional distributor networks to capture margin and formulation data from mid-sized artisan chains in Germany and France. Vietnam and Indonesia present the most penetrable geographies with rising bread consumption and constrained domestic high-protein wheat milling infrastructure. Heritage wheat variety certification offers differentiation entry point against established commodity millers. For Investors and Strategic Acquirers: The window for entry favors integrated millers with regenerative agriculture sourcing capabilities and EU Green Deal retrofit completion. Long-term viability rests on supply chain transparency infrastructure and direct bakery relationships rather than commodity scale. Watch for carbon border adjustment implementation signals as inflection indicator rewarding verified low-carbon milling processes.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | Clean-label commitments from German craft bakeries like Zeit für Brot reshape supplier qualification criteria and enable protein-premium capture. |
| F-Gas Regulatory Compliance Retrofit | EU Green Deal mandates force capital allocation toward ammonia-based refrigerant systems rather than capacity expansion. |
| Direct-to-Bakery Digital Platform Launch | Specialty flour producers bypass distributor networks to capture margin and real-time formulation data from artisan chains. |
| Southeast Asian Import Market Expansion | Vietnam and Indonesia exhibit rising Western-style bread consumption with limited domestic high-protein wheat milling capacity. |
| Heritage Wheat Variety Sourcing | Artisan boulangeries in France drive procurement toward stone-milled specialty grades with transparent supply chain mapping. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this bread flour market analysis, supplemented by primary interviews with milling operations directors, artisan bakery procurement leads, grain elevator managers, and food service distribution channel partners. FDA enrichment standards, USDA grading protocols, EFSA residue limit enforcement, and EU F-Gas Regulation implementation timelines provided regulatory boundary conditions. Bottom-up volume modeling across protein tiers, packaging formats, and end-use segments triangulated against top-down trade flow analysis.
Segmentation granularity extended to protein content bands, organic certification status, regenerative agriculture documentation, and geographic origination clusters across the projection horizon. CAGRs were derived from trend extrapolation of artisan bakery chain procurement patterns, EU regulatory compliance cost absorption rates, and Southeast Asian import demand trajectories. Wheat quality variability indices and energy cost differentials between European and North American milling operations informed margin compression assumptions.
Climate-driven hard wheat supply disruptions, F-Gas Regulation enforcement intensity variations, and carbon border adjustment implementation timing are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Cooking Oil Market
Ingredients
Low Calorie Oil Market
Ingredients
Cocoa Maker Market
Ingredients
Cocoa Solids Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market
Ingredients
Cold Pressed Oil Market
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Homecare Ingredients Market
Ingredients
Salt Content Reduction Ingredients Market