
 Food and Beverage Sterilizing Agent Market | 2026-2036
Food and Beverage Sterilizing Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverage Sterilizing Agent Market Analysis
The capital-intensity divergence between integrated peracetic acid producers and commodity bleach blenders is redrawing competitive boundaries in food and beverage sterilization. Solvay leverages its integrated hydrogen peroxide-to-peracetic acid chain to sustain margin capture across European dairy processing. Ecolab Inc. anchors North American beverage manufacturing through service-contract bundling that extends beyond chemical supply into dosing equipment and monitoring systems. Mitsubishi Gas Chemical Company dominates Asian hydrogen peroxide supply, positioning its ultra-pure grades for aseptic packaging lines in Japan and South Korea.
Food and beverage sterilizing agents are antimicrobial chemical formulations, typically oxidizing compounds such as peracetic acid, hydrogen peroxide, sodium hypochlorite, or ozone, applied at concentrations between 50 ppm and 2,000 ppm depending on target organism and surface type, designed to eliminate pathogenic and spoilage microorganisms from processing equipment, packaging materials, and liquid streams in commercial food production. Peracetic acid leads product type value contribution due to its broad-spectrum efficacy and minimal residue profile, while ozone grows fastest in bottled water and cold-pressed juice applications where chlorine-free labeling commands retail premium. Equipment sanitization captures the largest application margin pool because processors prioritize continuous clean-in-place systems over intermittent surface spraying, locking in multi-year chemical supply agreements.
FDA food contact notification requirements and EPA antimicrobial pesticide registration govern product approval timelines and label claims in the United States, while REACH and EU Food Contact Materials Regulation constrain active substance migration limits across European markets. The EU Green Deal accelerates substitution away from chlorinated compounds in dairy and beverage plants, redirecting procurement toward peracetic acid and ozone systems that align with farm-to-fork sustainability commitments. Stakeholders must monitor evolving biocidal product authorization timelines under BPR and state-level disinfectant listing requirements, as regulatory lag between jurisdiction approvals increasingly determines which suppliers can bid on multinational processing contracts.
Market Dynamics
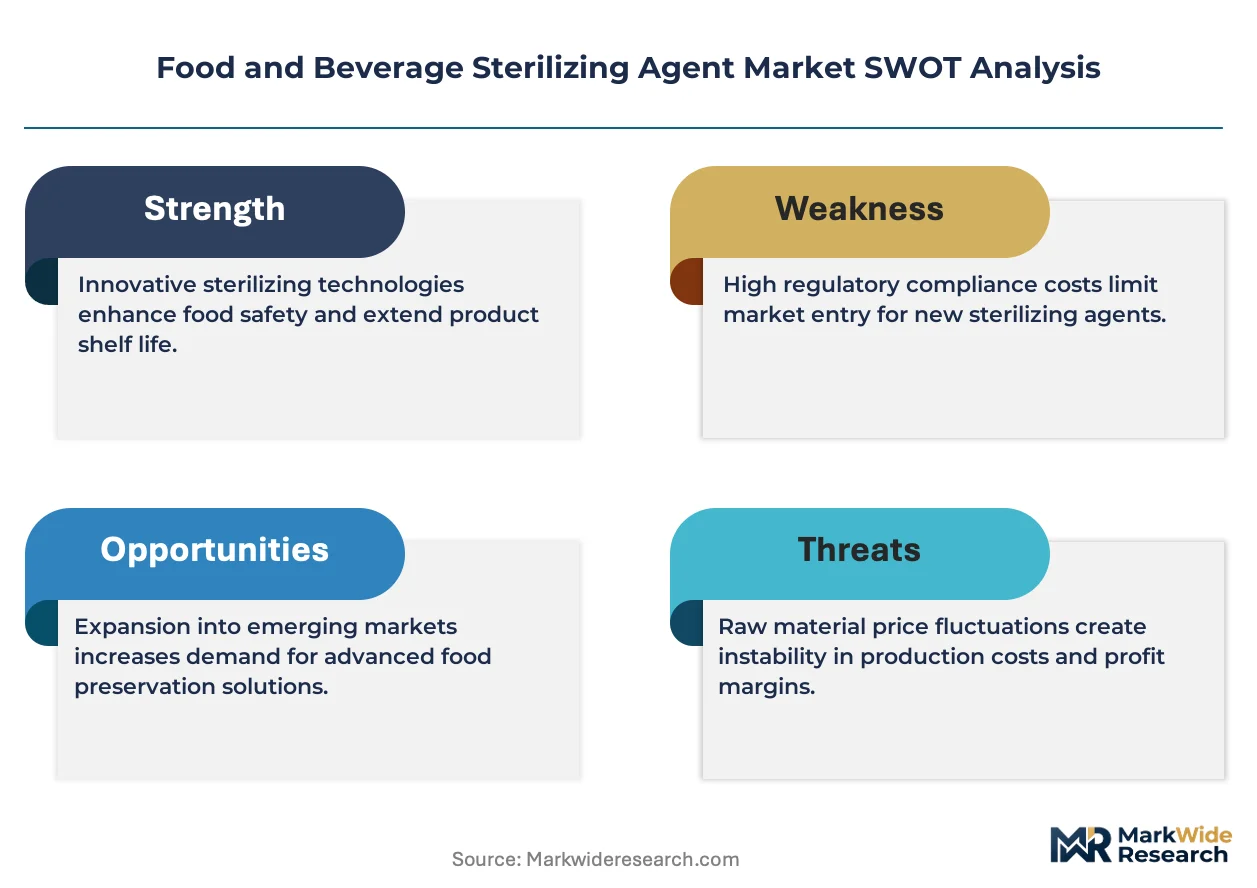
The EU F-Gas Regulation and Green Deal are forcing dairy processors to abandon chlorinated sanitizers, triggering wholesale reformulation toward peracetic acid and ozone systems that carry higher input costs but satisfy farm-to-fork sustainability audits.
Growth Catalysts
- Cold-chain dairy exports:German and Dutch cooperatives are expanding aseptic filling capacity to serve Middle Eastern and Asian markets, locking in multi-year sterilizing agent supply contracts for extended shelf-life milk and yogurt products.
- REACH-compliant reformulation mandates:The European Chemicals Agency is tightening biocidal product authorization timelines, accelerating substitution away from legacy chlorine donors toward peracetic acid blends with faster degradation profiles.
- Clean-in-place automation:Beverage bottlers in Bavaria and North Rhine-Westphalia are retrofitting continuous dosing systems that reduce chemical waste while maintaining microbial control thresholds.
Market Restraints
- Hydrogen peroxide feedstock volatility:Integrated peracetic acid producers face margin compression when energy costs spike, as captive hydrogen peroxide synthesis is electricity-intensive and tied to regional natural gas pricing.
- Asian supply concentration:Ultra-pure hydrogen peroxide for aseptic packaging remains dependent on Japanese and South Korean merchant suppliers, creating vulnerability for European dairy exporters seeking BRC-certified inputs.
- Ozone generator capex barriers:Small-to-mid-size juice processors cannot absorb the upfront capital for on-site ozone generation, limiting penetration in the fastest-growing chlorine-free labeling segment.
Strategic Opportunities
- Polish and Romanian dairy modernization:EU cohesion funds are financing cold-chain infrastructure in Eastern European member states, opening procurement channels for sterilizing agent vendors with REACH pre-registration.
- Electrochemical ozone generation:Convergence of membrane electrolysis and IoT dosing control is enabling distributed ozone production that bypasses hazardous chemical transport for rural bottling facilities.
- Extended producer responsibility frameworks:The EU Packaging and Packaging Waste Regulation is incentivizing sterilizing agent suppliers to bundle chemical supply with spent solution recovery services.
Industry Challenges
- BPR dossier compilation expertise:Biocidal Product Regulation authorization requires toxicological and environmental fate data that mid-size formulators struggle to generate without contract research organization partnerships.
- Legacy CIP system retrofit compatibility:Decades-old stainless steel piping in established dairy plants cannot tolerate the oxidative stress of concentrated peracetic acid without material degradation or gasket failure.
- Multi-jurisdiction label harmonization:Divergent EPA antimicrobial pesticide registration and EU BPR active substance approval timelines force suppliers to maintain parallel regulatory teams for transatlantic accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverage Sterilizing Agent Market |
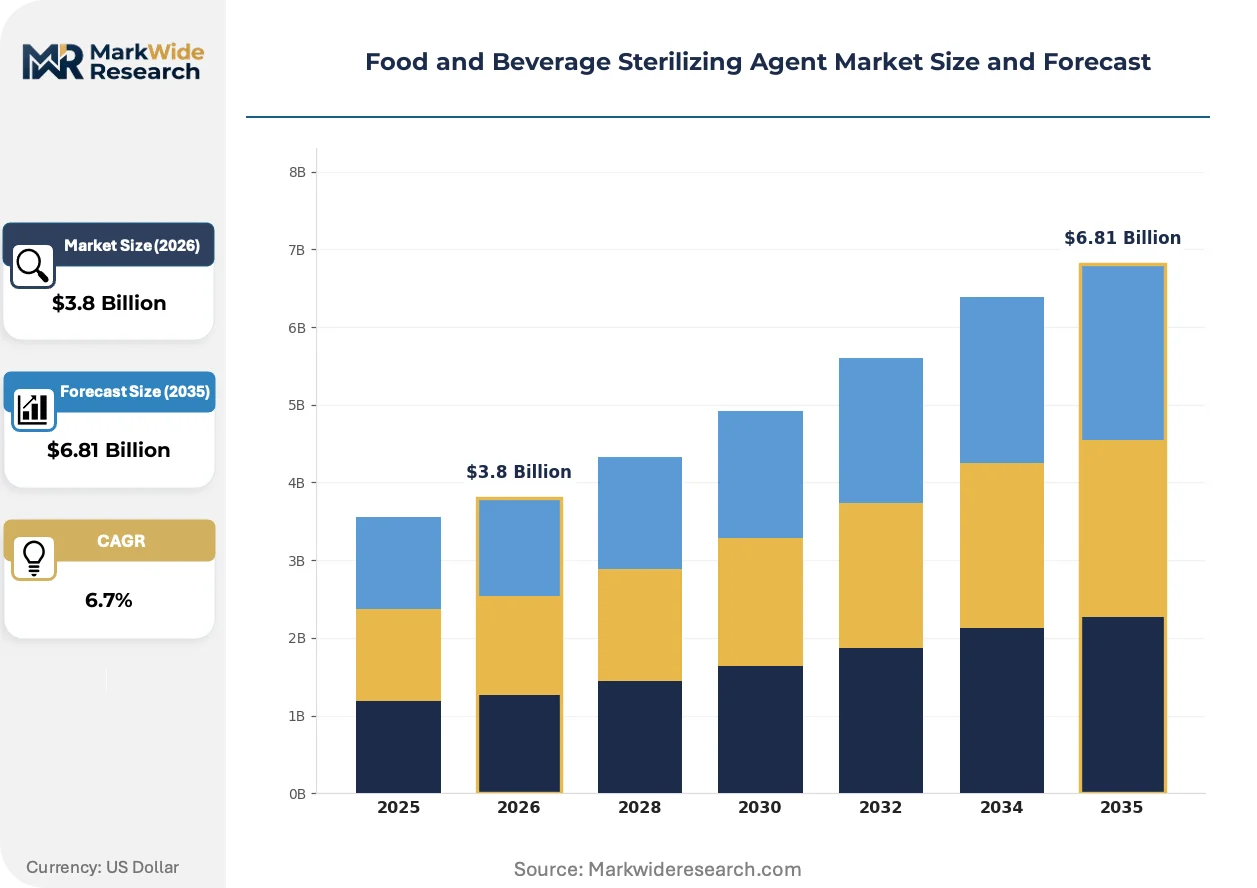
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Hypochlorite, Peracetic Acid, Hydrogen Peroxide, Ozone Application: Liquid Sterilization, Surface Disinfection, Equipment Sanitization, Packaging Treatment Delivery Mode: Aerosol, Liquid Concentrate, Powder, Ready-to-Use End User: Food Processing, Beverage Manufacturing, Dairy Industry, Restaurants |
| Companies Covered | Solvay, Steris, Peroxy Chem, Evonik Industries, Mitsubishi Gas Chemical Company, Arkema, OCI Company Ltd., Hansol Chemical, Ecolab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverage Sterilizing Agent Market Emerging Trajectories
Reformulation chemistry and dosing automation are converging to displace manual sanitization protocols, while regulatory pressure on chlorine discharge accelerates capital deployment into alternative oxidation systems.
Electrochemical ozone generation is fragmenting the bottled water sterilization landscape. On-site ozone production eliminates hazardous chemical transport and storage liabilities for regional bottlers. Craft beverage producers in Scandinavia are adopting compact electrolytic cells that integrate with existing reverse osmosis lines. This distributed production model is compressing the addressable market for bulk-delivered sodium hypochlorite in sub-50,000 liter-per-day facilities.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon propellants is indirectly tightening chlorine gas availability for hypochlorite synthesis. German dairy processors face reformulation deadlines that align with cooperative sustainability reporting cycles under the Corporate Sustainability Reporting Directive. Large Bavarian cooperatives are pre-qualifying peracetic acid suppliers based on cradle-to-gate carbon footprint data ahead of formal procurement tenders.
Buyer consolidation among European dairy cooperatives is compressing supplier switching cycles and unbundling after-sales technical service from chemical supply agreements. Procurement teams at Dutch and Irish dairy giants now separate dosing equipment maintenance from sterilizing agent procurement, forcing chemical vendors to compete on unit economics alone. This disaggregation is most visible in Germany, where multi-site cooperative networks centralize chemical buying through shared service centers.
Food and Beverage Sterilizing Agent Market Segmentation
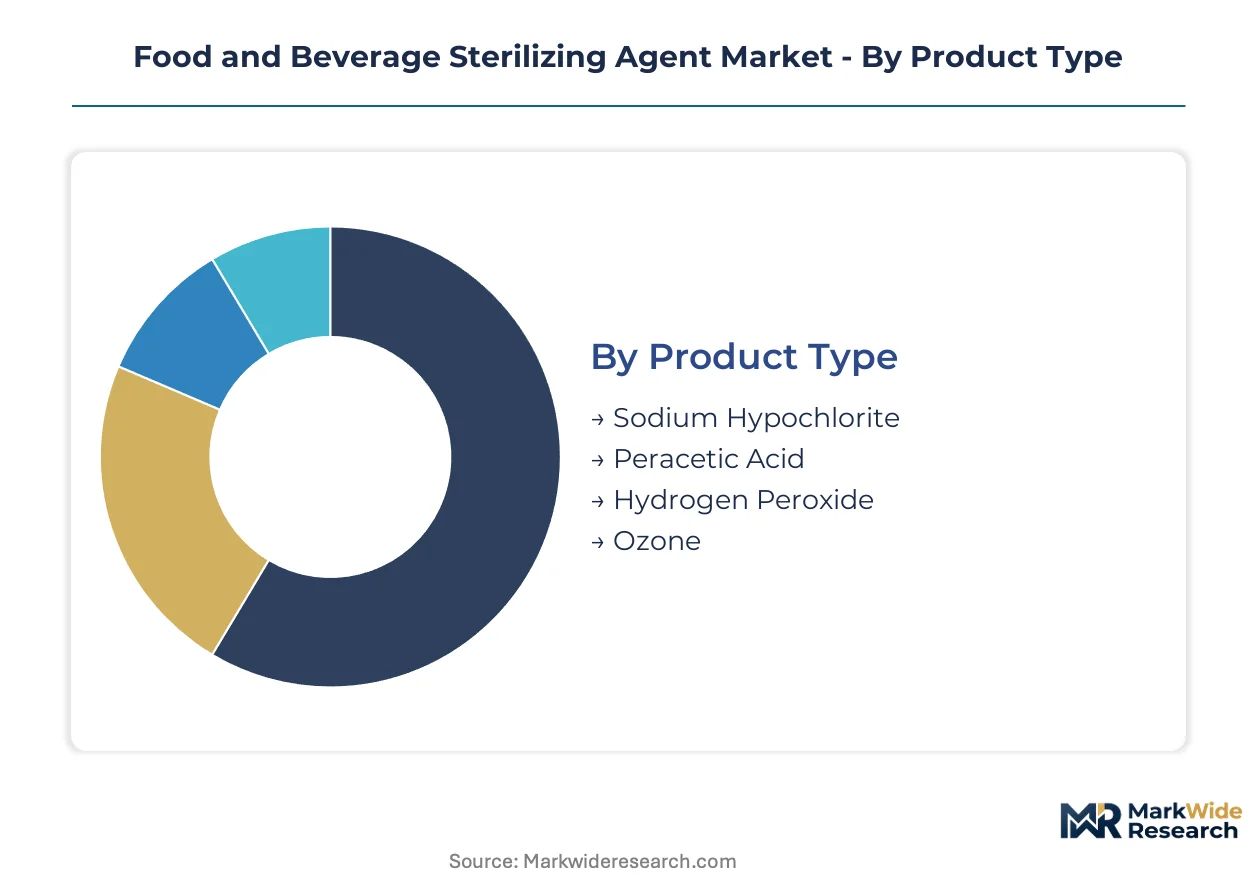
Sterilizing agent procurement patterns diverge sharply across product chemistries and application contexts. Dairy processors prioritize residue profiles and degradation kinetics, while beverage bottlers weigh dosing automation compatibility against unit economics.
Product Type:
Margin pools concentrate in peracetic acid and hydrogen peroxide, where integrated producers capture value through captive oxidation chemistry rather than blending operations.
- Peracetic Acid:Formulated through equilibrium reaction of acetic acid and hydrogen peroxide with sulfuric acid catalyst, yielding a equilibrium mixture typically containing 5-15% peracetic acid. German dairy cooperatives in Bavaria are locking in multi-year supply contracts as EU F-Gas Regulation deadlines force abandonment of chlorinated alternatives. The minimal residue profile satisfies farm-to-fork sustainability audits for cold-chain dairy exports to Middle Eastern markets.
- Hydrogen Peroxide:Supplied in technical grades from 35% to 70% concentration, with ultra-pure specifications for aseptic packaging lines requiring sub-ppm metallic impurity thresholds. Japanese and South Korean merchant suppliers dominate ultra-pure production, creating supply vulnerability for European dairy exporters seeking BRC-certified inputs. Energy-intensive anthraquinone process synthesis ties margins to regional natural gas pricing.
- Sodium Hypochlorite:Alkaline chlorine solution typically delivered at 12-15% available chlorine for bulk sanitation operations.
- Ozone:Triatomic oxygen generated on-site through corona discharge or electrolytic methods, eliminating hazardous transport liabilities.
Peracetic acid holds installed capacity. Ozone is rotating up the share rankings.
Application:
Equipment sanitization commands premium pricing through multi-year clean-in-place system contracts, while surface disinfection competes on spot procurement economics.
- Equipment Sanitization:Continuous clean-in-place systems circulate sterilizing solutions through stainless steel piping at 60-80°C, requiring chemical compatibility with elastomer gaskets and seal materials. Bavarian and North Rhine-Westphalia beverage bottlers are retrofitting automated dosing systems that reduce chemical waste while maintaining microbial control thresholds. The capital intensity of CIP infrastructure locks processors into multi-year chemical supply agreements.
- Liquid Sterilization:Direct injection of sterilizing agents into product streams or process water, demanding precise concentration control to prevent organoleptic impact. Cold-pressed juice processors in Scandinavia are adopting electrochemical ozone generation to bypass chlorine-free labeling requirements, though small-to-mid-size facilities face capex barriers for on-site generation equipment.
- Surface Disinfection:Intermittent spraying or foaming applications for floors, walls, and non-product contact surfaces.
- Packaging Treatment:Sterilization of bottles, caps, and aseptic carton materials prior to filling operations.
Equipment sanitization dominates contract value. Liquid sterilization is climbing the fastest.
Delivery Mode:
Volume concentrates in liquid concentrate formats compatible with automated dosing infrastructure, while ready-to-use formulations serve fragmented restaurant and small-processor segments.
- Liquid Concentrate:Dilution ratios from 1:10 to 1:1000 enable bulk delivery and on-site blending, minimizing transport costs and storage footprint.
- Ready-to-Use:Pre-diluted formulations eliminate operator error in concentration management but carry higher per-unit costs.
- Powder:Solid precursors such as sodium dichloroisocyanurate tablets for remote facilities lacking liquid handling infrastructure.
- Aerosol:Pressurized spray cans for targeted surface treatment in manual sanitization protocols.
Liquid concentrate anchors procurement volume. Ready-to-use is gaining share in foodservice channels.
End User:
Procurement sophistication stratifies between multinational dairy cooperatives with centralized chemical buying and fragmented restaurant operators purchasing through distribution intermediaries.
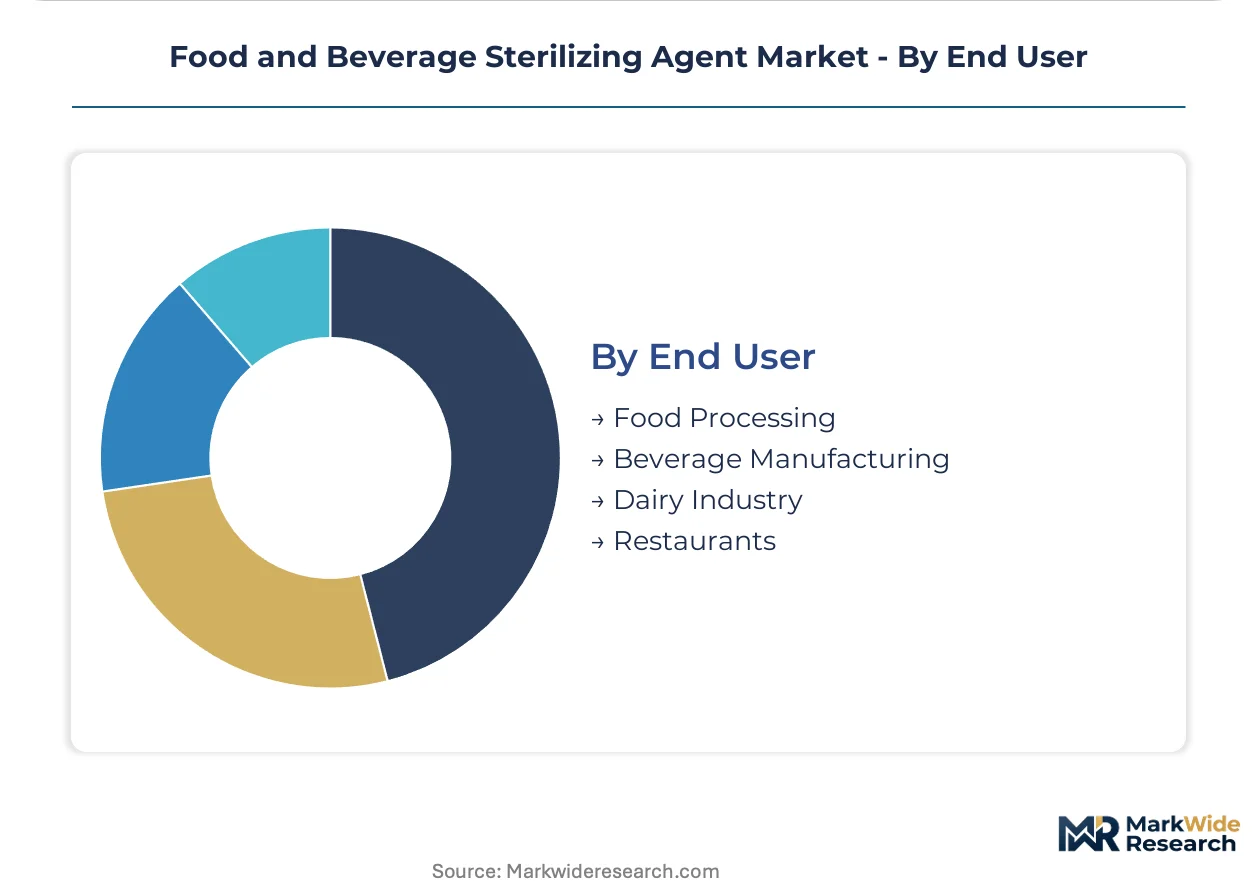
- Dairy Industry:Extended shelf-life milk and yogurt production drives aseptic filling capacity expansion, with German and Dutch cooperatives pre-qualifying suppliers on cradle-to-gate carbon footprint data ahead of formal tenders under Corporate Sustainability Reporting Directive obligations.
- Beverage Manufacturing:Bottled water and carbonated soft drink producers balance chlorine-free labeling premiums against ozone generator capital requirements.
- Food Processing:Meat, poultry, and prepared food facilities with diverse sanitation protocols across raw and cooked product zones.
- Restaurants:Commercial kitchens with intermittent, low-volume procurement through foodservice distributors.
Dairy industry holds contract concentration. Beverage manufacturing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dairy processors favor peracetic acid systems for cold-chain export compliance, while Japanese bottlers prioritize ultra-pure hydrogen peroxide for aseptic packaging lines. This consumption-mix differential reflects divergent regulatory pressures and end-use sophistication across major markets.
United States
Beverage manufacturers in California and the Pacific Northwest drive ozone adoption for chlorine-free labeling. FDA food contact notification requirements and EPA antimicrobial pesticide registration govern approval timelines. Wisconsin dairy cooperatives retrofit clean-in-place systems to meet extended shelf-life export specifications.
Germany
Bavarian and North Rhine-Westphalia bottlers anchor peracetic acid demand as EU F-Gas Regulation deadlines force chlorinated sanitizer phase-out. The EU Green Deal and REACH biocidal product authorization accelerate reformulation toward degradation-friendly alternatives. Large dairy cooperatives centralize procurement through shared service centers in Munich and Cologne clusters.
Japan
Aseptic packaging lines for ready-to-drink beverages consume ultra-pure hydrogen peroxide grades with sub-ppm metallic impurity thresholds. METI industrial standards and pharmaceutical-grade chemical specifications constrain supplier qualification. Kanto region bottlers around Tokyo and Yokohama maintain multi-year supply agreements with domestic merchant producers.
Netherlands
Dutch dairy giants expand aseptic filling capacity for Middle Eastern and Asian cold-chain exports. ECHA biocidal product authorization timelines under BPR redirect procurement toward pre-registered peracetic acid blends. Rotterdam port logistics clusters enable bulk chemical import and distribution across Benelux processing networks.
South Korea
Bottled water and functional beverage producers adopt electrochemical ozone generation for premium chlorine-free positioning. MFDS food additive regulations and national hydrogen peroxide purity standards shape supplier selection. Busan-Ulsan manufacturing corridors host automated dosing system retrofits for continuous sanitization protocols.
Food and Beverage Sterilizing Agent Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with margin capture diverging sharply between captive oxidation chemistry and commodity blending operations. The upper tier commands pricing power through hydrogen peroxide-to-peracetic acid integration, while mid-size formulators compete on service bundling and regional regulatory expertise. Three archetypes dominate: integrated peroxide producers, service-contract bundlers, and ultra-pure specialty suppliers. Competitive moves concentrate on REACH pre-registration positioning and multi-year clean-in-place system lock-ins.
Within the integrated chemistry tier, Solvay and Evonik Industries exemplify producers with captive oxidation capabilities spanning hydrogen peroxide through peracetic acid equilibrium synthesis. Ecolab Inc. anchors the service-contract archetype, bundling chemical supply with dosing equipment and monitoring infrastructure. Mitsubishi Gas Chemical Company occupies a position in ultra-pure hydrogen peroxide for aseptic packaging lines, representing the specialty-grade concentration that Japanese and South Korean bottlers specify for BRC-certified exports.
| Leading Market Players |
|---|
| Solvay |
| Steris |
| Peroxy Chem |
| Evonik Industries |
| Mitsubishi Gas Chemical Company |
| Arkema |
| OCI Company Ltd. |
| Hansol Chemical |
| Ecolab Inc. |
| Others |
Supply Flow & Price Mechanics
Captive hydrogen peroxide synthesis at Solvay and Evonik facilities creates scale economies that compress peracetic acid unit costs below blenders sourcing merchant feedstock, concentrating margin capture among integrated producers while forcing commodity blenders toward price floors set by energy-intensive anthraquinone process economics. This supply-side consolidation feeds directly into procurement leverage for German dairy cooperatives bundling multi-year clean-in-place contracts.
Pricing Analysis
After-sales technical service revenue—spanning dosing equipment calibration, sensor maintenance, and regulatory compliance auditing—drives lifetime value beyond chemical unit sales. Three-tier pricing structure across premium REACH-certified grades, standard technical blends, and economy bulk hypochlorite segments stratifies the market. Cost compression in standard peracetic acid blends is intensifying because Dutch and Irish dairy giants now unbundle equipment maintenance from chemical procurement, forcing pure-play suppliers to compete on unit economics alone. Small-to-mid-size juice processors exhibit highest price sensitivity due to ozone generator capex barriers, while multinational cooperatives prioritize certification premiums over per-liter costs.
Supply Chain Analysis
Inventory lead times for ultra-pure hydrogen peroxide extend 8-12 weeks from Japanese and South Korean merchant suppliers to European dairy exporters, creating working capital intensity for BRC-certified input sourcing. Supply concentrates in Germany for peracetic acid equilibrium synthesis, Belgium for hydrogen peroxide anthraquinone production, and Japan for ultra-pure aseptic packaging grades. Raw material dependencies span acetic acid, sulfuric acid catalyst, and electricity-intensive hydrogen peroxide feedstock. Single-source vulnerability runs through Asian ultra-pure supply for European cold-chain exporters. Distribution runs through Rotterdam port logistics clusters enabling bulk chemical import and Benelux processing network distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against electrochemical ozone generation systems that bypass hazardous chemical transport entirely, threatening peracetic acid and hypochlorite volume in sub-50,000 liter-per-day beverage facilities.
For Market Incumbents: Fortify multi-year clean-in-place contract lock-ins by bundling IoT-enabled dosing automation with chemical supply, raising switching costs for Bavarian and North Rhine-Westphalia bottlers. Deepen backward integration into captive hydrogen peroxide synthesis to absorb feedstock volatility from regional natural gas pricing. Prioritize REACH pre-registration positioning ahead of Biocidal Product Regulation authorization deadlines to exclude mid-size formulators lacking contract research organization partnerships. For New Entrants and Emerging Players: EU BPR fast-track certification for peracetic acid blends with accelerated degradation profiles opens procurement channels in Polish and Romanian dairy modernization projects financed by cohesion funds. Target electrochemical ozone generation equipment leasing models for Scandinavian craft beverage producers seeking chlorine-free labeling without upfront capital absorption. Penetrate through service-contract unbundling—offering pure chemical supply at aggressive unit economics to Dutch cooperative shared service centers that have already separated dosing equipment maintenance. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated peroxide-to-peracetic acid producers with captive oxidation chemistry and multi-year CIP system agreements. Over the projection horizon, viability hinges on regulatory pre-positioning rather than capacity scale alone. Prioritize acquisition targets with established BPR dossier compilation expertise and pre-registered active substance portfolios. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator—accelerated chlorinated sanitizer phase-out timelines would compress valuation multiples for legacy hypochlorite blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Peroxide | Captive anthraquinone synthesis insulates margins from European natural gas volatility at Solvay and Evonik facilities. |
| REACH Pre-Registration Positioning | Early biocidal product dossier submission excludes mid-size formulators from German dairy cooperative tenders under BPR timelines. |
| Electrochemical Ozone Generation Deployment | On-site membrane electrolysis bypasses hazardous transport liabilities for rural Scandinavian bottling facilities. |
| Clean-in-Place System Retrofit Partnerships | Automated dosing integration locks Bavarian beverage processors into multi-year chemical supply agreements. |
| Extended Producer Responsibility Bundling | Spent solution recovery services align with EU Packaging and Packaging Waste Regulation incentives for sterilizing agent vendors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade data, Cefic industry reports, and ECHA biocidal product authorization databases. Interviews with plant managers at integrated peroxide facilities, procurement leads at Dutch dairy cooperatives, distribution channel partners in Benelux chemical logistics, and technical R&D directors at dosing equipment manufacturers provided operational validation. Bottom-up triangulation across product chemistry grades and application segments was cross-checked against top-down trade flow analysis.
Segmentation dimensions modeled span product type chemistry, application context, delivery mode format, and end-user procurement sophistication across the projection horizon. CAGRs were derived from installed capacity expansion trajectories, regulatory substitution timelines, and cold-chain infrastructure investment patterns. Forecast inputs incorporated EU F-Gas Regulation phase-out schedules, cohesion fund disbursement tracking for Eastern European dairy modernization, and electrochemical ozone generation technology cost curves.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable natural gas feedstock pricing; material deviation in regulatory intensity or energy cost volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Nutraceutical Excipients Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Semi-Finished Pastry Ingredients Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market