
 Global Lactase Market | 2026-2036
Global Lactase Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lactase Market Foresight
Dairy application demand is shifting toward lactose-free and reduced-lactose product lines across industrial food manufacturing. Novozymes A/S leverages its fermentation technology leadership to supply high-purity neutral lactase at scale. DSM-Firmenich anchors its position through integrated enzyme-nutrition platforms serving European and North American dairy processors. Kerry Group plc competes by extending its application-specific technical service capabilities to mid-sized dairy brands.
Lactase denotes the beta-galactosidase enzyme that hydrolyzes lactose into glucose and galactose, typically operating optimally between pH 6.0-7.0 for neutral variants and pH 3.0-5.0 for acid-stable forms used in fermented dairy. Industrial production relies on submerged fermentation of Aspergillus oryzae, Kluyveromyces lactis, or recombinant microbial strains, yielding liquid or powdered concentrates standardized to activity units per gram. Neutral lactase dominates volume throughput in milk processing, while acid lactase captures faster growth in yogurt and cheese applications where pH tolerance eliminates pre-treatment steps. Recombinant lactase variants command premium positioning as pharmaceutical-grade specifications tighten, particularly for nutraceutical encapsulation.
FDA enzyme regulation and the EU's REACH framework govern production residue limits and food-contact safety, directly influencing supplier qualification timelines for new lactase sources. Japan's Ministry of Health, Labour and Welfare maintains distinct enzyme additive positive lists that constrain market entry for novel recombinant strains. China's National Health Commission has accelerated novel food enzyme approvals, creating parallel compliance pathways. Stakeholders must monitor divergence between regional enzyme classification systems to avoid formulation lock-in that limits geographic expansion.
Market Dynamics
The EU Green Deal's sustainable production mandates are compressing fermentation process timelines and forcing enzyme suppliers to requalify manufacturing lines under stricter carbon-accounting protocols before 2027.
Growth Catalysts
- Clean-label dairy portfolios:German precision dairy processors are expanding lactose-free product lines to capture premium shelf positioning as consumer intolerance awareness rises.
- REACH framework compliance:EU residue limit harmonization is accelerating supplier qualification for novel recombinant lactase strains across member-state food-contact applications.
- Acid-stable enzyme adoption:Yogurt and cheese manufacturers are eliminating pre-treatment steps by switching to pH-tolerant lactase variants that operate directly in fermented matrices.
Market Restraints
- Fermentation feedstock volatility:Corn syrup and yeast extract input costs fluctuate with agricultural commodity cycles, compressing margin buffers for bulk lactase concentrate suppliers.
- Supplier concentration risk:Neutral lactase volume throughput depends heavily on Danish and Dutch fermentation infrastructure, creating geographic single-point vulnerability.
- Japan's positive-list friction:MHLW enzyme additive restrictions block rapid market entry for recombinant Kluyveromyces-derived strains, delaying product registration by 18-24 months.
Strategic Opportunities
- China's accelerated approval pathway:NHC novel food enzyme fast-track mechanisms create first-mover advantage for suppliers with recombinant strain documentation.
- Nutraceutical encapsulation:Pharmaceutical-grade lactase specifications for dietary supplement applications command 3-4x pricing multiples over food-grade concentrates.
- Fermentation-membrane hybrid technology:Integrated bioprocessing with in-situ product recovery is reducing downstream purification capex by 30-40% for new market entrants.
Industry Challenges
- Strain documentation backlog:FDA Generally Recognized as Safe (GRAS) self-affirmation timelines for recombinant Aspergillus platforms extend 14-18 months due to toxicology data requirements.
- Legacy dairy equipment retrofit costs:Continuous lactase dosing systems require stainless steel piping upgrades and automated pH monitoring that strain mid-sized processor capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lactase Market |
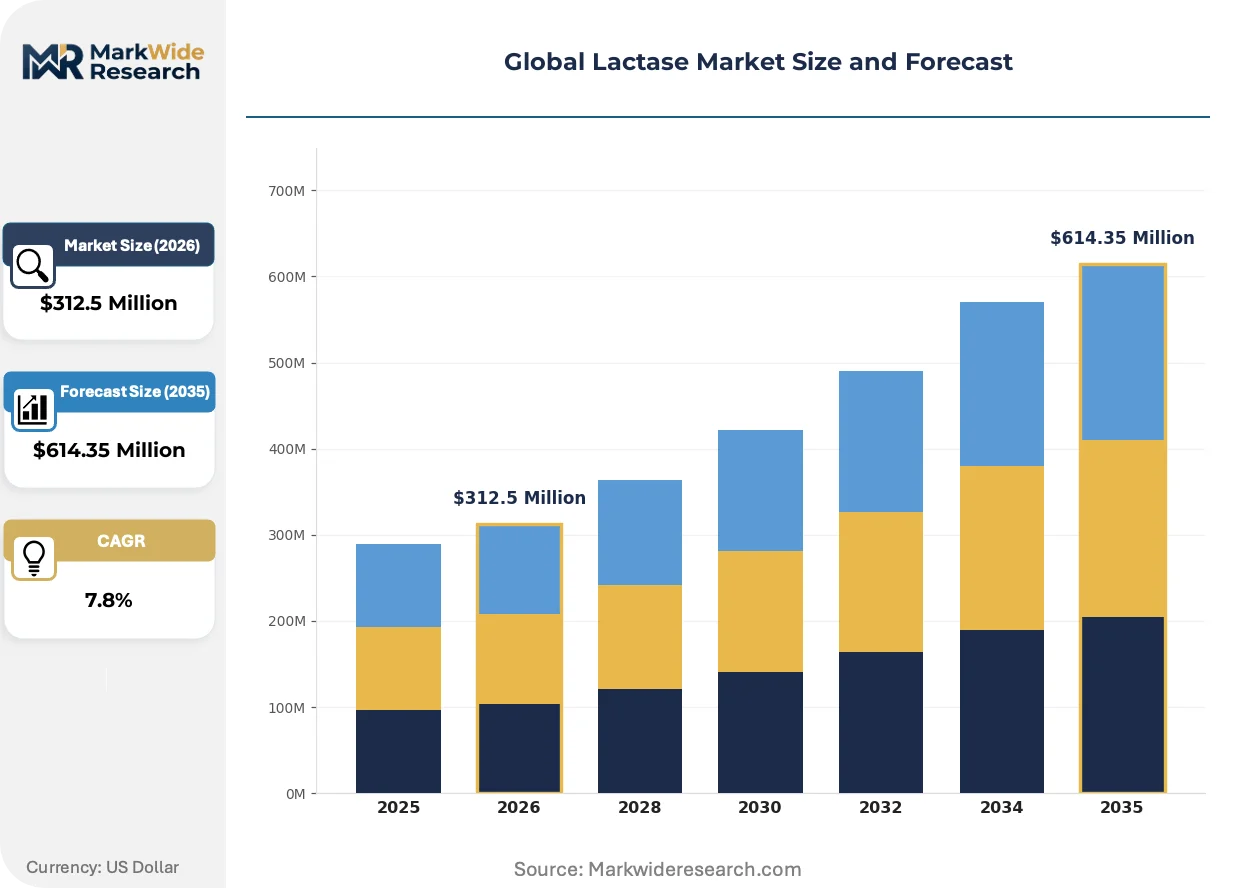
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neutral Lactase, Acid Lactase, Alkaline Lactase, Recombinant Lactase Application: Dairy Products, Pharmaceuticals, Animal Feed, Baking Industry, Beverages End User: Food Manufacturers, Nutraceutical Companies, Animal Nutrition Firms, Pharmaceutical Manufacturers Form: Liquid, Powder, Granules, Capsules |
| Companies Covered | Novozymes A/S, DSM-Firmenich, International Flavors and Fragrances Inc., Chr. Hansen Holdings A/S, Advanced Enzyme Technologies, Amano Enzyme Inc., Kerry Group plc, Novonesis, Enzyme Development Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lactase Market Shifts & Advancements
Enzyme manufacturing is pivoting toward closed-system bioreactor designs that reduce water intensity and enable real-time carbon footprint tracking for Scope 3 reporting.
Recombinant lactase expression in Aspergillus oryzae is consolidating competitive advantage for suppliers serving pharmaceutical-grade specifications. Nutraceutical contract manufacturers in Switzerland and Germany are qualifying these high-purity variants for infant formula and medical nutrition applications. The technology is consolidating supplier tiers by compressing price premiums for second-generation neutral lactase into single-digit spreads.
REACH framework amendments on enzyme production residue limits are tightening food-contact safety thresholds for fermentation-derived proteins. Industrial lactase suppliers must revalidate downstream purification protocols to meet ECHA's updated characterization requirements. European dairy processors are demanding batch-level certificates of analysis to document compliance, shifting procurement qualification toward documentation-heavy supplier relationships.
Buyer concentration among multinational dairy cooperatives is compressing switching cycles for enzyme supply contracts. FrieslandCampina and Arla Foods are consolidating vendor panels to three qualified suppliers per enzyme category, replacing fragmented regional sourcing. This pattern is most visible in the Netherlands and Denmark, where cooperative-owned processing infrastructure dominates fluid milk volume.
Global Lactase Market Segmentation
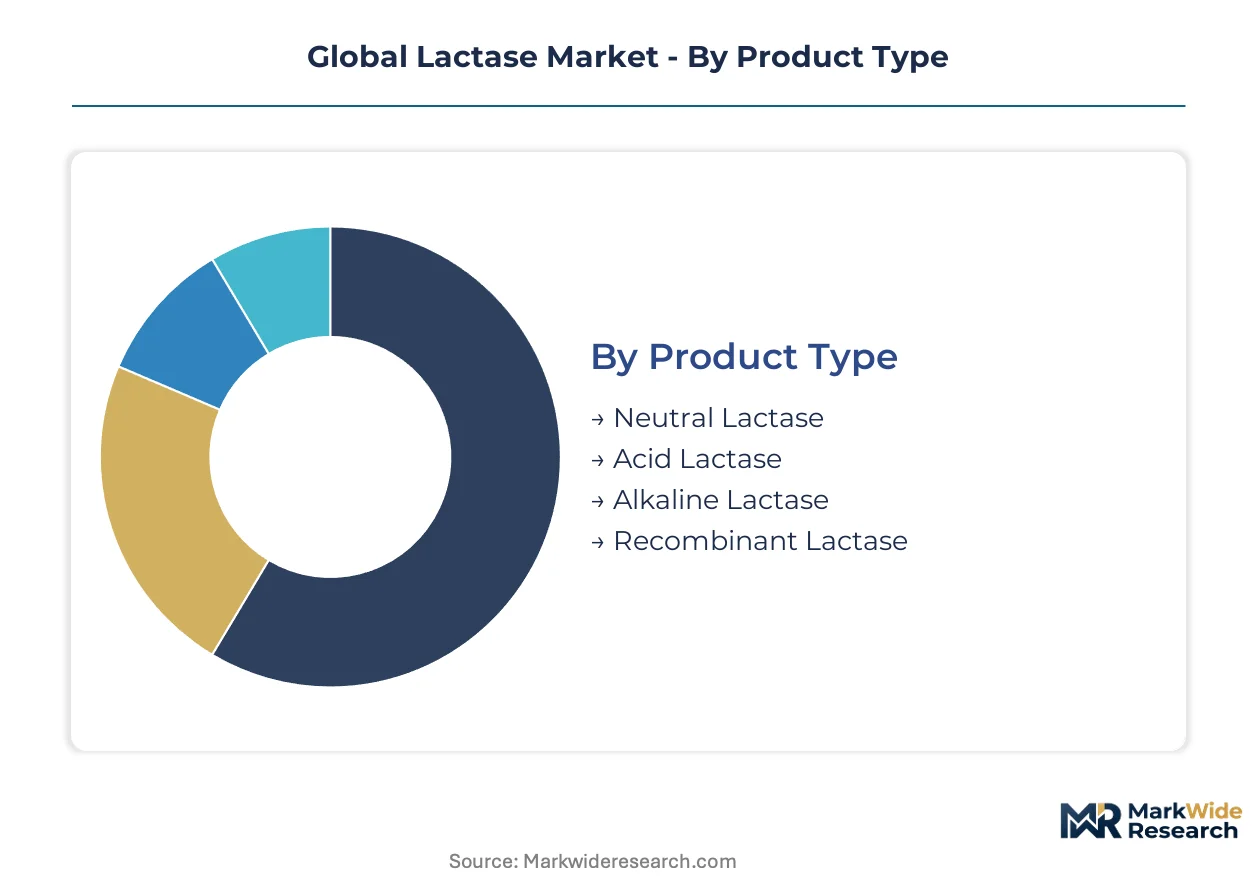
Lactase segmentation reveals distinct performance requirements across pH environments, formulation formats, and end-use specifications. Manufacturers configure supply chains differently for bulk dairy processing versus pharmaceutical-grade encapsulation, creating divergent margin structures within the same enzyme class.
Product Type:
Standalone lactase formulations dominate commodity dairy processing, while embedded enzyme systems integrate into specialized fermentation platforms for precision nutrition applications.
- Neutral Lactase:Operates optimally at pH 6.0-7.0 through submerged fermentation of Kluyveromyces lactis or Aspergillus oryzae. Fluid milk processors in Germany and the United States standardize on this variant for pre-treatment hydrolysis, though pH adjustment steps add process complexity. Neutral lactase leads volumes today; recombinant lactase is gaining share fastest.
- Acid Lactase:Functions at pH 3.0-5.0 without pre-treatment, eliminating neutralization steps in yogurt and cheese matrices. French and Italian fermented dairy specialists are converting production lines to capture efficiency gains from direct-inoculation protocols.
- Alkaline Lactase:High-pH variants serve niche pharmaceutical extraction processes and specialized whey protein modification. Limited commercial deployment constrains supplier qualification investments.
- Recombinant Lactase:Genetically optimized strains deliver pharmaceutical-grade purity for infant formula and medical nutrition. Swiss and German nutraceutical contract manufacturers command 3-4x pricing multiples over food-grade concentrates.
Acid-stable variants are compressing neutral lactase's historical dominance in fermented dairy applications.
Application:
Cost-tier segmentation separates commodity volume drivers from premium specification markets with divergent documentation and certification requirements.
- Dairy Products:Lactose-free fluid milk, cheese, and yogurt represent the volume anchor, with German precision dairy processors expanding clean-label portfolios. EU Green Deal carbon-accounting protocols are forcing fermentation suppliers to requalify manufacturing lines.
- Pharmaceuticals:Medical nutrition and infant formula applications impose pharmaceutical-grade purity standards with batch-level certificates of analysis. Swissmedic and FDA oversight extends qualification timelines.
- Animal Feed:Calf milk replacers and precision livestock diets utilize lower-purity concentrates with reduced documentation overhead.
- Baking Industry:Enzyme-supplemented dough conditioners improve fermentation tolerance and browning characteristics in artisan and industrial bakeries.
- Beverages:Lactose-free dairy drinks and functional beverage formulations require cold-stable enzyme variants with extended shelf-life compatibility.
Dairy applications consume the majority of tonnage; pharmaceutical specifications deliver the steepest expansion trajectory.
End User:
Customer-type segmentation distinguishes between integrated multinationals with captive technical service demands and mid-sized processors purchasing application-specific support.
- Food Manufacturers:Multinational dairy cooperatives in the Netherlands and Denmark consolidate vendor panels to three qualified suppliers per enzyme category, replacing fragmented regional sourcing.
- Nutraceutical Companies:Dietary supplement and medical nutrition formulators demand pharmaceutical-grade documentation with toxicology data packages for novel recombinant strains.
- Animal Nutrition Firms:Feed compounders prioritize cost-optimized concentrates with standardized activity units over purity certification.
- Pharmaceutical Manufacturers:Infant formula and clinical nutrition producers impose the tightest residue limits, driving supplier consolidation toward recombinant Aspergillus platforms with GRAS self-affirmation.
Food manufacturers anchor procurement volumes; nutraceutical buyers are expanding their specification influence fastest.
Form:
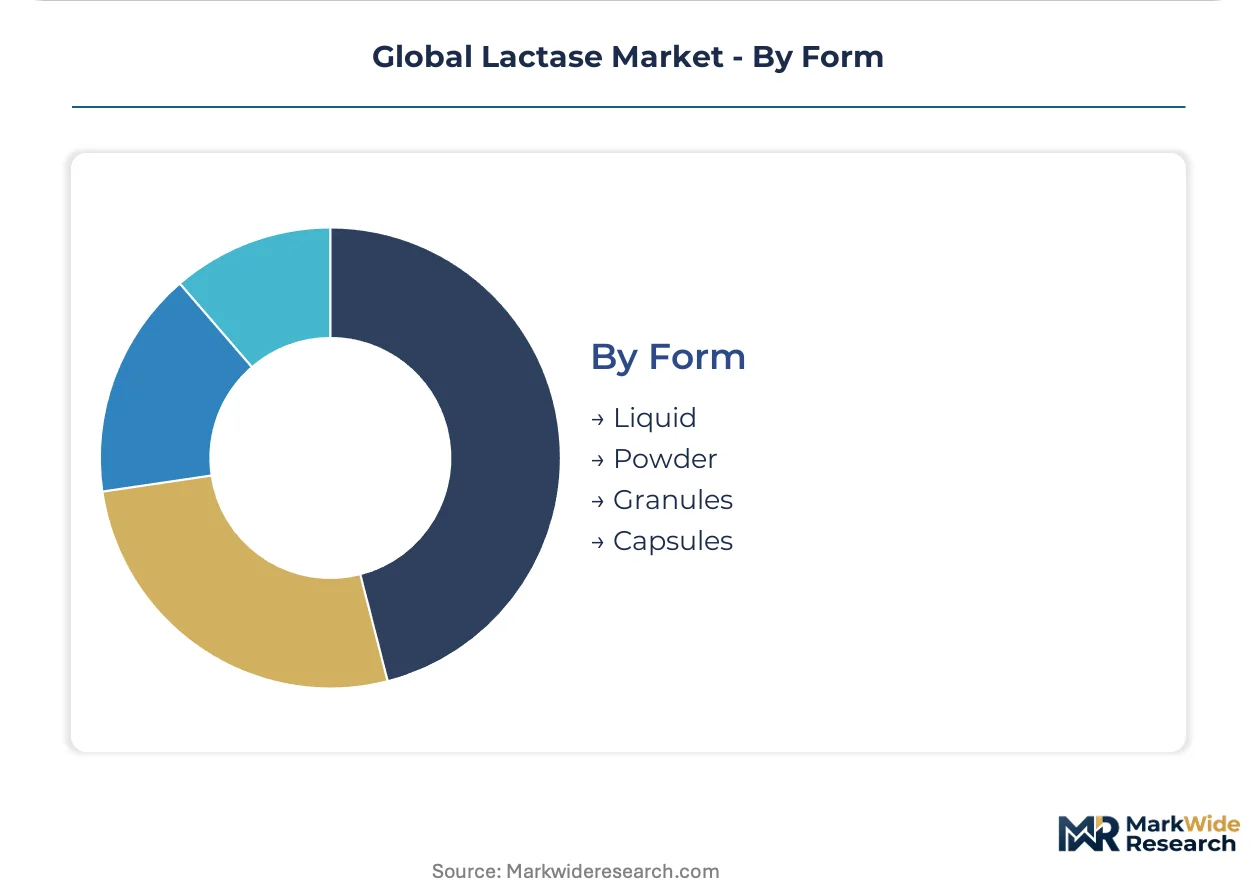
Supply concentration in liquid formats reflects fermentation infrastructure location, while powder and granule alternatives serve geographic markets with limited cold-chain reliability.
- Liquid:Concentrated fermentation broths with standardized activity units serve high-volume dairy processors with continuous dosing systems. Danish and Dutch fermentation infrastructure dominates supply.
- Powder:Spray-dried concentrates enable extended shelf stability for export markets and mid-sized processors without refrigerated storage capacity.
- Granules:Agglomerated formats reduce dust exposure and improve flow characteristics for automated dosing equipment in industrial bakeries.
- Capsules:Pre-measured unit doses serve dietary supplement manufacturers and pharmaceutical encapsulation lines with exact potency requirements.
Liquid concentrates dominate industrial throughput; capsule formats are climbing fastest in nutraceutical contract manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting lactase production toward jurisdictions with streamlined enzyme approval pathways. Suppliers are relocating fermentation capacity to exploit gaps between the EU's REACH residue limits and China's accelerated NHC fast-track mechanisms.
Germany
Precision dairy processors in Bavaria and North Rhine-Westphalia are expanding clean-label lactose-free portfolios to capture premium retail positioning. The EU Green Deal's carbon-accounting mandates are forcing fermentation suppliers to requalify manufacturing lines before 2027. The Munich-Stuttgart corridor hosts the densest concentration of pharmaceutical-grade lactase contract manufacturers serving infant formula specifications.
United States
Fluid milk processors in Wisconsin and California are standardizing on neutral lactase pre-treatment hydrolysis for lactose-free product lines. FDA GRAS self-affirmation timelines for recombinant Aspergillus platforms extend 14-18 months due to toxicology data requirements. The Midwest dairy belt dominates volume throughput, though coastal nutraceutical encapsulators in New Jersey and California command premium pricing tiers.
China
Domestic dairy brands in Inner Mongolia and Heilongjiang are integrating lactase-treated milk powders for lactose-intolerant consumer segments. The National Health Commission's novel food enzyme fast-track mechanisms create first-mover advantage for suppliers with recombinant strain documentation. Yangtze River Delta fermentation infrastructure is expanding to serve both domestic dairy processors and export pharmaceutical markets.
Japan
Fermented dairy specialists in Hokkaido and the Tokyo-Osaka corridor are converting production lines to acid-stable lactase variants. The Ministry of Health, Labour and Welfare maintains distinct enzyme additive positive lists that constrain market entry for recombinant Kluyveromyces-derived strains, delaying registration by 18-24 months. Regional dairy cooperatives are lobbying for regulatory harmonization with Codex standards.
Switzerland
Nutraceutical contract manufacturers in Basel and Zurich are qualifying recombinant lactase variants for medical nutrition and infant formula applications. Swissmedic oversight extends qualification timelines but validates 3-4x pricing multiples over food-grade concentrates. The country's precision fermentation cluster leverages pharmaceutical-grade GMP infrastructure to serve EU and Middle Eastern export markets.
Global Lactase Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers seek to secure fermentation capacity and geographic regulatory coverage. The vendor base consolidates around three tiers: multinational enzyme houses with integrated nutrition platforms, mid-sized fermentation specialists with regional regulatory expertise, and emerging Chinese suppliers leveraging NHC fast-track approvals. Danish and Dutch infrastructure anchors neutral lactase volume, while Swiss and German specialists capture pharmaceutical-grade premiums. Competitive moves center on M&A to acquire recombinant strain portfolios and capacity expansion in low-carbon-accounting jurisdictions.
Within the multinational enzyme house tier, Novozymes A/S and DSM-Firmenich occupy positions defined by fermentation technology leadership and integrated enzyme-nutrition platforms respectively. Kerry Group plc exemplifies the application-specific technical service archetype, extending support capabilities to mid-sized dairy brands. These three entities represent distinct competitive vectors: scale-driven fermentation, platform integration, and service-led mid-market penetration.
| Leading Market Players |
|---|
| Novozymes A/S |
| DSM-Firmenich |
| International Flavors and Fragrances Inc. |
| Chr. Hansen Holdings A/S |
| Advanced Enzyme Technologies |
| Amano Enzyme Inc. |
| Kerry Group plc |
| Novonesis |
| Enzyme Development Corporation |
| Others |
Supply & Pricing Matrix
Corn syrup futures and yeast extract spot markets transmit volatility directly into lactase concentrate cost structures, compressing margin buffers for bulk suppliers while amplifying spreads between food-grade and pharmaceutical-grade tiers. Buyers in Germany and Switzerland absorb these input swings differently, with precision dairy processors locking in contract terms and nutraceutical encapsulators accepting spot premiums for recombinant strain documentation.
Pricing Analysis
Direct-to-OEM discounts dominate volume procurement for multinational dairy cooperatives, while distributor markups persist for mid-sized processors lacking technical service integration. Three-tier pricing structure across premium, standard, and economy levels separates recombinant pharmaceutical-grade lactase from neutral dairy concentrates and feed-grade alternatives. Price differentiation hinges on certification grade—FDA GRAS self-affirmation or Swissmedic validation—and volume scale with annual offtake commitments. Cost compression in standard-tier neutral lactase is intensifying because fermentation feedstock volatility erodes supplier margins. Animal nutrition firms exhibit highest price sensitivity; infant formula manufacturers show least.
Supply Chain Analysis
China's NHC novel food enzyme fast-track mechanisms are reshaping sourcing patterns, incentivizing recombinant strain documentation investments for domestic-content qualification. Fermentation capacity concentrates in Denmark, the Netherlands, and Germany, with Yangtze River Delta infrastructure expanding fastest. Raw material dependencies draw from agricultural commodity markets—corn syrup, yeast extract, and pharmaceutical-grade filtration membranes. Single-source vulnerability runs through Danish and Dutch neutral lactase volume, where cooperative-owned processing infrastructure dominates fluid milk throughput. Distribution runs through integrated enzyme-nutrition platforms serving European and North American dairy processors, supplemented by regional fermentation specialists with local regulatory expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global lactase market functions as a regulatory compounder, with EU Green Deal carbon-accounting mandates forcing supplier requalification timelines and compressing competitive windows before manufacturing line deadlines.
For Market Incumbents: Acquire recombinant Aspergillus strain portfolios to defend pharmaceutical-grade positioning against emerging Chinese suppliers leveraging NHC fast-track approvals. Consolidate fermentation capacity in low-carbon-accounting jurisdictions to preempt EU Green Deal compliance costs. Backward integration into corn syrup and yeast extract sourcing mitigates feedstock volatility exposure. For New Entrants and Emerging Players: The premium-to-economy price gap in acid-stable lactase variants offers entry traction, as French and Italian fermented dairy specialists convert production lines to eliminate pre-treatment steps. Target Japan's acid-lactase conversion wave, where MHLW positive-list friction delays recombinant strain registration and creates incumbent vulnerability. Lead with technical service capabilities for mid-sized dairy brands underserved by multinational enzyme houses. For Investors and Strategic Acquirers: Asymmetric upside sits with Swiss and German nutraceutical contract manufacturers commanding pharmaceutical-grade lactase premiums for infant formula encapsulation. Five-to-ten-year viability favors recombinant strain platforms with GRAS self-affirmation documentation and integrated GMP fermentation infrastructure. Watch for FDA toxicology data requirement backlogs as inflection signal—accelerated GRAS timelines would compress competitive moats for documented suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Strain Acquisition | Captures pharmaceutical-grade pricing multiples from Swiss and German nutraceutical contract manufacturers. |
| Fermentation-Membrane Hybrid Technology | Reduces downstream purification capex for new entrants competing with established Danish and Dutch infrastructure. |
| EU Green Deal Compliance Investment | Requalifies manufacturing lines under stricter carbon-accounting protocols before cooperative procurement consolidation. |
| China NHC Fast-Track Documentation | Accelerates novel recombinant lactase approvals for domestic dairy brands in Inner Mongolia and Heilongjiang. |
| Acid-Stable Product Line Conversion | Eliminates pH adjustment steps for French and Italian yogurt and cheese manufacturers seeking process efficiency. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and Switzerland, with primary inputs from each market cluster combined with secondary validation. The research team conducted interviews with fermentation technology directors at enzyme houses, regulatory affairs leads navigating FDA GRAS and ECHA REACH frameworks, procurement managers at multinational dairy cooperatives, and technical service heads supporting mid-sized dairy brands. Secondary sources include FDA GRAS notification databases, ECHA substance characterization requirements, NHC novel food enzyme approval registers, and SEC filings from listed enzyme suppliers. Bottom-up volume modeling triangulates against top-down market sizing across pH variant, application, and end-user segments.
Rate-of-change decomposition separates volume growth drivers from value expansion across the projection horizon. The analytical framework models neutral, acid, and recombinant lactase variants; dairy, pharmaceutical, and nutraceutical applications; and food manufacturer, nutraceutical company, and pharmaceutical manufacturer end-user categories. CAGRs derive from segmented growth rate aggregation with cross-validation against industry stakeholder consensus. Forecast inputs incorporate fermentation capacity expansion announcements, regulatory approval timeline trajectories, and cooperative procurement consolidation patterns.
Caveats apply where FDA toxicology data backlogs, EU Green Deal requalification delays, or Japan MHLW positive-list harmonization failures could materially shift the outlook. Forecasts reflect assumptions about recombinant strain documentation completion rates and carbon-accounting protocol adoption timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Europe Leavening Agents Market