
 Japan Food Preservatives Market | 2026-2036
Japan Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Food Preservatives Market Foresight
Japanese beverage companies is bifurcating the preservative demand landscape away from legacy food manufacturers seeking cost-optimized synthetic solutions. Ajinomoto leverages its amino acid fermentation expertise to dominate natural preservative supply for premium beverage clients. Corbion anchors the sorbates segment through backward integration into bio-based raw material production. Kerry Group competes by extending its clean-label preservative portfolio tailored to Japan's shrinking household size and single-serve packaging trends.
Food preservatives encompass chemical and biological substances added to food and beverage matrices to inhibit microbial spoilage, enzymatic degradation, and oxidative rancidity, typically dosed at 0.01% to 0.3% by weight depending on water activity and pH targets. Their primary commercial purpose centers on extending shelf stability while meeting Japan's stringent Standards for Foods and Food Additives under the Food Sanitation Act. Sorbates leads among product types due to its broad pH efficacy and GRAS alignment with export-oriented Japanese processors. Natural source preservatives represent the fastest-expanding category as METI's sustainability guidelines and consumer preference shifts pressure synthetic alternatives. Phosphates maintains mature, stable demand within processed meat and seafood applications where water retention and color fixation remain non-negotiable.
METI enforces additive labeling transparency through the Consumer Affairs Agency's Food Labeling Act amendments, compelling reformulation toward shorter ingredient declarations. PMDA and the Ministry of Health, Labour and Welfare coordinate on novel natural preservative safety assessments, creating multi-year approval bottlenecks that favor incumbent suppliers with established dossiers. JIS standards for food-grade chemical purity further segment supplier qualification tiers, restricting market access for uncertified imports. Stakeholders must monitor emerging fermentation-derived biopreservatives and their regulatory classification trajectory to anticipate which production investments will secure preferential channel positioning.
Market Dynamics
METI's Food Recycling Law revisions are forcing Japanese food manufacturers to abandon legacy synthetic preservatives in favor of fermentation-derived alternatives, compressing formulation cycles from years to months.
Growth Catalysts
- Clean-label beverage mandates:Premium drink processors now require preservative systems with fewer than five declared ingredients, pulling natural extract demand upward.
- Kanto manufacturing density:Tokyo's food production corridor enables just-in-time preservative delivery, reducing inventory carrying costs for processors.
- PMDA novel food additive pathways:Accelerated safety review timelines for plant-derived antimicrobials shorten commercialization cycles.
Market Restraints
- Sorbitol feedstock volatility:Bio-based sorbate production faces input cost swings from corn and tapioca starch markets.
- Chinese citric acid dominance:Over 70% of global supply concentrates in Shandong province, exposing Japanese buyers to single-source risk.
- pH efficacy ceilings:Natural organic acids lose antimicrobial activity above pH 5.5, restricting application in neutral formulations.
Strategic Opportunities
- Kansai underpenetration:Osaka-Kobe food processors lag Tokyo in clean-label adoption, creating a 24-month catch-up window.
- Single-serve packaging surge:Portion-controlled products need milder preservation due to faster consumption cycles.
- METI green procurement incentives:Tax advantages for bio-based additive purchases improve natural preservative unit economics.
Industry Challenges
- Fermentation scale-up expertise:Japanese chemical engineers with industrial bioprocess experience command premium compensation.
- JIS certification timelines:Food-grade purity testing for novel natural preservatives extends 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Food Preservatives Market |
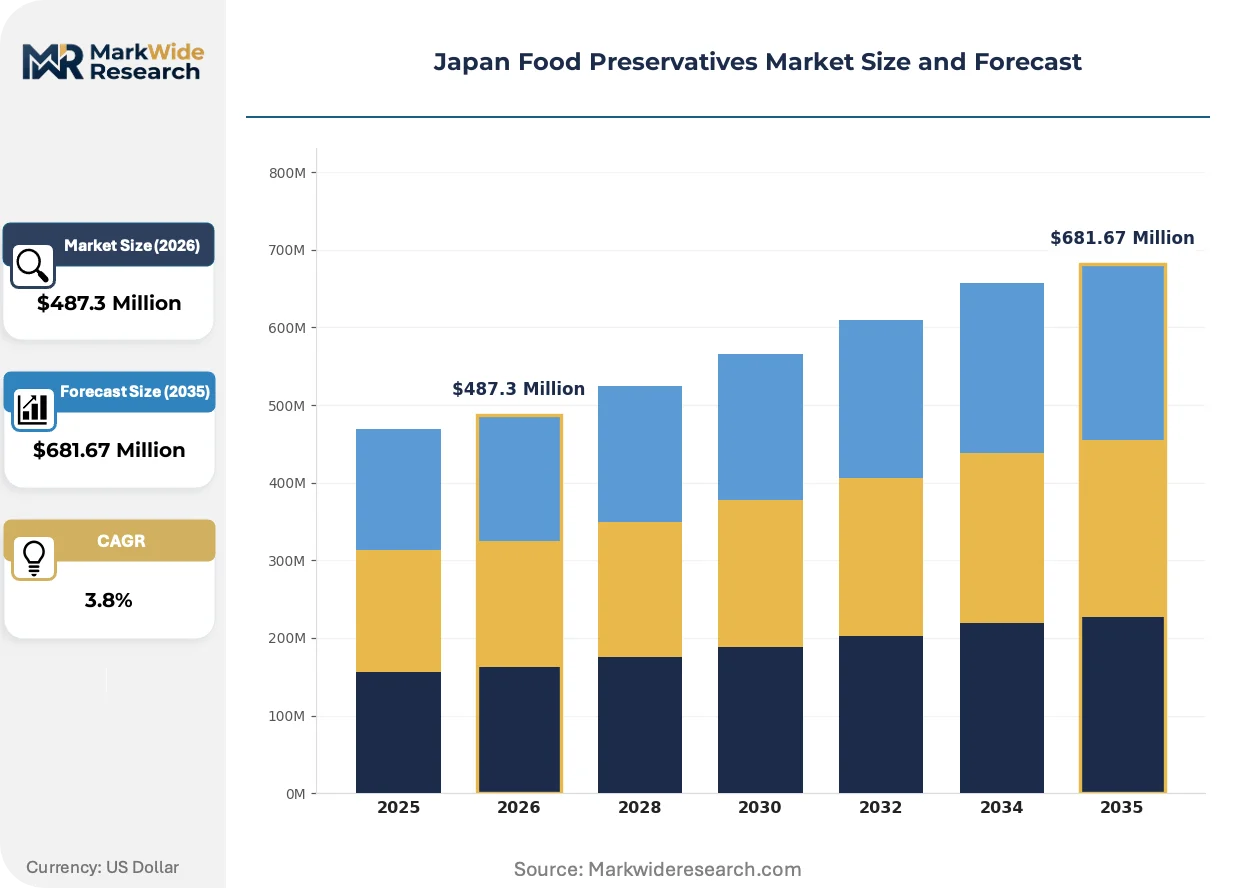
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Benzoates, Nitrites, Phosphates End User: Food Manufacturers, Beverage Companies, Retail Chains, Restaurants Formulation: Liquid, Powder, Granular, Tablet Source: Natural, Synthetic, Organic, Preservative Blends |
| Companies Covered | Corbion, DuPont de Nemours, Kerry Group, Chr. Hansen Holding, Ajinomoto, Cargill, Archer Daniels Midland Company, Nissin Foods Holdings, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Food Preservatives Market Shifts & Advancements
Japanese preservative markets are bifurcating between synthetic efficiency and natural provenance, with technology investments clustering around precision fermentation and extraction methods that reduce dosage rates.
Encapsulation technology is miniaturizing preservative delivery systems. Liposome and nano-emulsion formats protect active compounds from thermal degradation during retort processing. Beverage manufacturers in Saitama and Chiba prefectures are piloting these formats for tea and functional drinks. The structural consequence is compression of effective dosage thresholds by 30-40% compared to conventional liquid additions.
METI's 2023 Food Labeling Act amendments mandate full additive disclosure on front-of-pack labels. Processors must now reformulate to shorter ingredient lists or risk retail delisting. Premium sauce and dressing manufacturers face the steepest compliance costs, accelerating partnerships with fermentation-derived antimicrobial suppliers.
Buyer concentration among Japan's top five beverage conglomerates is consolidating procurement decisions. Mid-tier preservative suppliers now negotiate directly with central technical teams rather than regional plants. This shift is most visible in the Kanto corridor, where Ajinomoto and domestic trading houses have established dedicated clean-label procurement desks.
Japan Food Preservatives Market Segmentation
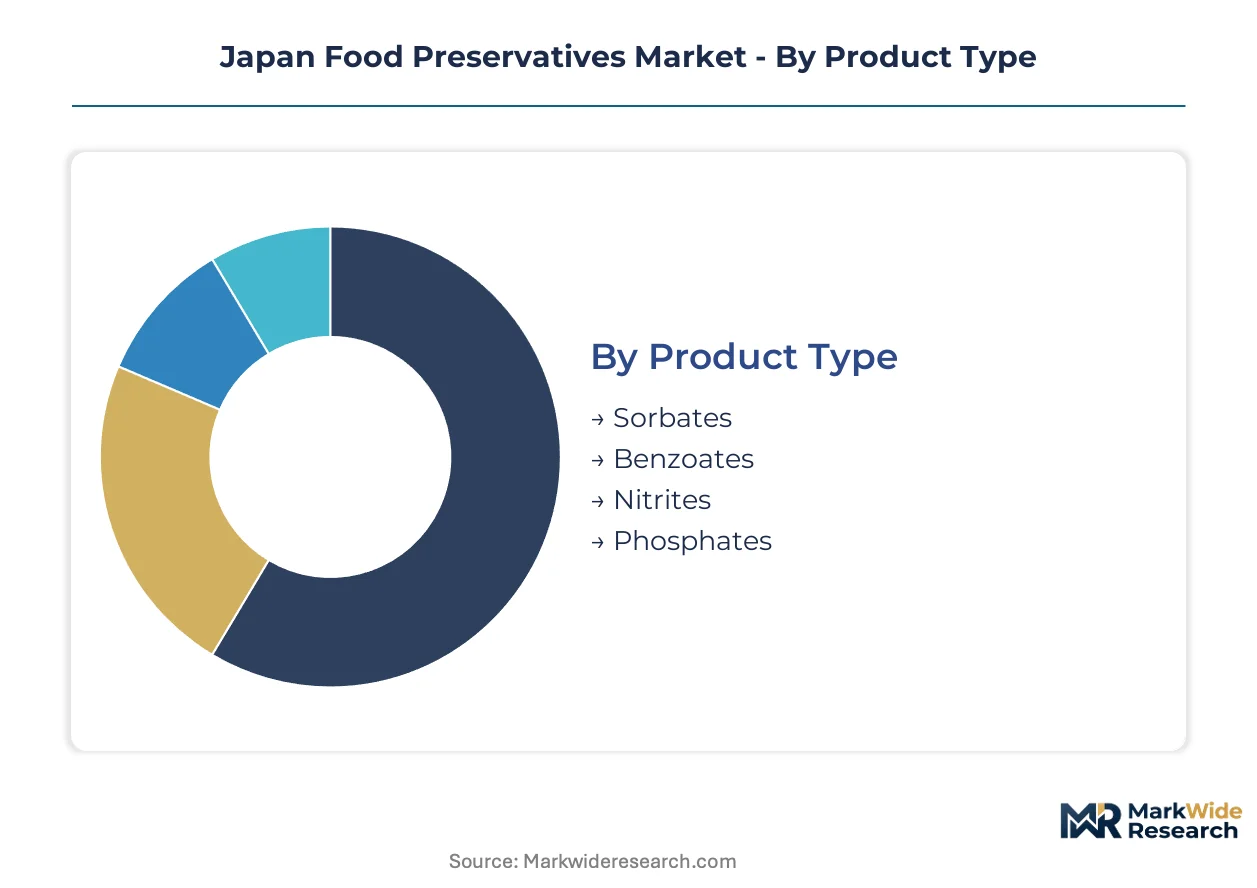
Japan's food preservative segmentation reflects METI's bifurcated regulatory pressure on synthetic disclosure versus natural fermentation pathways. Formulation choices now pivot on clean-label compliance costs rather than pure antimicrobial efficacy.
Product Type:
METI's Food Labeling Act amendments impose stricter declaration thresholds for synthetic antimicrobials, reshaping procurement priorities across Japanese processors.
- Sorbates:Potassium sorbate delivers broad-spectrum mold and yeast inhibition across pH 2.5-6.5, making it indispensable for acidic beverages and sauces. Kanto-region beverage manufacturers prioritize sorbates for export-compliant GRAS status. Corbion's bio-based production in Japan secures supply chain proximity for premium clients.
- Phosphates:Sodium and potassium phosphates stabilize water retention and color in processed seafood and meat matrices. Osaka-Kobe processors depend on phosphates for surimi and cured pork applications where texture standards are non-negotiable. METI has not classified phosphates under clean-label pressure, preserving stable demand.
- Benzoates:Sodium benzoate remains cost-effective for high-acid condiments and pickles, though front-of-pack disclosure requirements are eroding its use in premium positioning.
- Nitrites:Sodium nitrite and nitrate salts dominate cured meat color fixation and botulism prevention, constrained by strict PMDA residue limits in ham and sausage production.
Sorbates handles the majority of throughput; Natural-source alternatives are gaining share fastest among reformulating beverage clients.
End User:
Customer procurement power concentrates where volume scale meets technical specification complexity.
- Beverage Companies:Premium drink manufacturers in Saitama and Chiba prefectures now mandate preservative systems with under five declared ingredients. Single-serve packaging trends favor milder preservation due to accelerated consumption cycles. Ajinomoto's amino acid-derived solutions dominate this segment's supplier base.
- Food Manufacturers:Processed sauce and dressing producers face steepest METI compliance costs, driving partnerships with fermentation-derived antimicrobial suppliers. Tokyo's dense manufacturing cluster enables just-in-time preservative delivery.
- Retail Chains:Private-label processors balance shelf-life extension against clean-label claims, often accepting shorter stability windows for simpler ingredient decks.
- Restaurants:Foodservice distributors prioritize cost-optimized synthetic blends where front-of-pack visibility is irrelevant to B2B procurement.
Food Manufacturers absorb the largest procurement volume; Beverage Companies are expanding most quickly on specification sophistication.
Formulation:
Physical format selection hinges on processing equipment compatibility and thermal stability requirements during retort sterilization.
- Liquid:Aqueous solutions integrate directly into beverage mixing tanks and brine injection systems, dominating high-volume continuous processing. Nano-emulsion and liposome encapsulation formats in Saitama pilot plants protect actives from thermal degradation.
- Powder:Spray-dried preservatives offer extended shelf stability and precise dosing for dry seasoning blends and flour-based applications.
- Granular:Free-flowing granules reduce dust exposure in meat processing facilities and improve dispersion in dry rub formulations.
- Tablet:Compressed formats serve niche artisanal producers with batch-scale equipment lacking liquid metering infrastructure.
Liquid handles the majority of throughput; Powder is climbing the fastest on encapsulation technology adoption.
Source:
Raw material provenance now determines tax advantage eligibility under METI green procurement incentives.
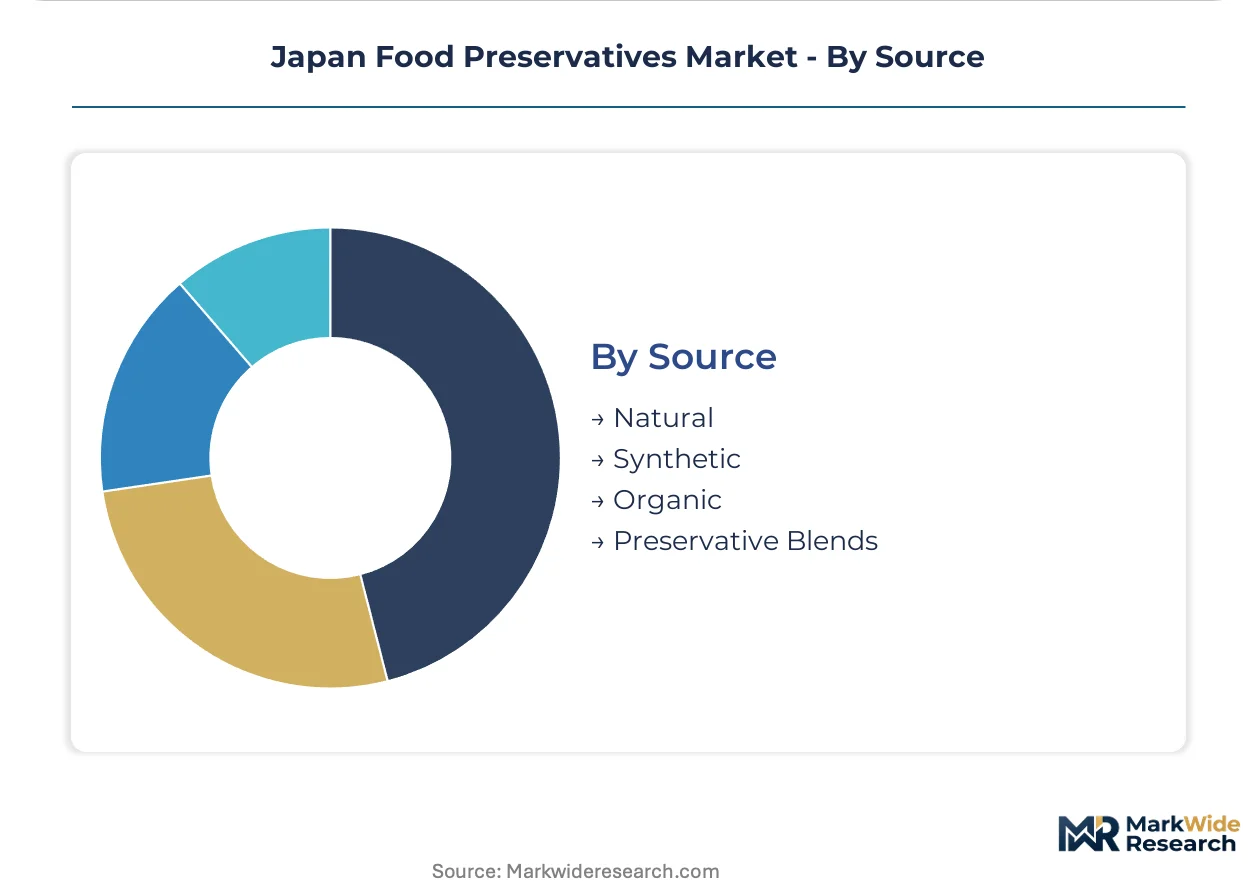
- Natural:Fermentation-derived antimicrobials from amino acid and organic acid pathways qualify for METI bio-based purchase incentives. PMDA's novel food additive review timelines create multi-year approval bottlenecks favoring established dossiers.
- Synthetic:Petrochemical-derived benzoates and sorbates retain cost advantage in mass-market applications where label transparency carries minimal consumer penalty.
- Organic:Certified organic preservatives command premium positioning in export-oriented and domestic specialty channels, constrained by JIS purity certification timelines of 18-24 months.
- Preservative Blends:Synergistic combinations of natural and synthetic actives optimize efficacy-cost ratios for reformulating mid-tier processors.
Synthetic handles the majority of throughput; Natural is expanding most quickly on METI sustainability guideline alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Tokyo anchors Japan's food preservative distribution network, handling bulk chemical imports and fermentation-derived inputs for Kanto-region processors. Containerized preservative shipments from Rotterdam and Shanghai terminate here before rail dispersal to Saitama and Chiba manufacturing clusters. This maritime infrastructure underwrites Japan's position as Asia's most sophisticated food additive market.
Kanto/Tokyo
Tokyo's dense food manufacturing corridor drives bulk procurement of natural and synthetic preservative blends. METI's Food Labeling Act amendments compel reformulation toward shorter ingredient declarations in this region. Saitama and Chiba prefectures pilot liposome encapsulation formats for beverage applications, compressing effective dosage thresholds.
Kansai/Osaka
Osaka-Kobe food processors lag Tokyo in clean-label adoption, creating a 24-month catch-up window for fermentation-derived antimicrobial suppliers. The Consumer Affairs Agency enforces identical disclosure rules here, but compliance costs bite harder on mid-tier sauce manufacturers. The Hanshin Industrial Zone maintains stable phosphate demand for surimi and cured pork applications.
Chubu/Nagoya
Nagoya's processed meat sector sustains mature nitrite demand for color fixation and botulism prevention in ham and sausage production. PMDA residue limits constrain formulation flexibility here more than in beverage-heavy regions. Toyota's logistics networks enable just-in-time preservative delivery to Aichi prefecture processors.
Kyushu
Fukuoka's food export hub faces stricter GRAS alignment requirements for US-bound shipments, favoring sorbate procurement over benzoates. Regional processors balance cost-optimized synthetic blends against clean-label premiums demanded by Tokyo-based trading houses. The Kanmon Strait ports facilitate raw material imports for bio-based preservative production.
Hokkaido
Dairy and seafood processors in Hokkaido prioritize phosphates for water retention in frozen surimi and cured fish matrices. JIS standards for food-grade chemical purity restrict supplier access for uncertified imports through Tomakomai and Hakodate ports. Cold chain infrastructure extends preservative efficacy windows for remote distribution.
Japan Food Preservatives Market Competitive Landscape
Concentration sits with diversified fermentation specialists and global ingredient conglomerates that have secured PMDA dossier approvals. The supplier base tiers into three archetypes: amino acid fermentation leaders with backward integration into raw material production, bio-based chemical producers leveraging European biotechnology licensing, and trading houses consolidating procurement for mid-tier Japanese processors. Dominant competitive moves include strategic partnerships with Kanto beverage conglomerates and capacity expansion into encapsulation technology formats.
Among fermentation-derived specialists, Ajinomoto and Corbion occupy positions exemplifying the natural preservative supply archetype, while Kerry Group represents the clean-label portfolio diversification strategy. Ajinomoto leverages amino acid fermentation expertise for premium beverage clients. Corbion anchors sorbates supply through bio-based raw material production. Kerry Group competes by extending clean-label preservative portfolios tailored to Japan's shrinking household size.
| Leading Market Players |
|---|
| Corbion |
| DuPont de Nemours |
| Kerry Group |
| Chr. Hansen Holding |
| Ajinomoto |
| Cargill |
| Archer Daniels Midland Company |
| Nissin Foods Holdings |
| BASF SE |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Kanto beverage conglomerates and fermentation-derived preservative suppliers lock in multi-year supply access while anchoring price visibility against sorbitol feedstock volatility. These arrangements concentrate procurement power among Japan's top five drink manufacturers, compressing margin flexibility for mid-tier suppliers competing on spot market terms.
Pricing Analysis
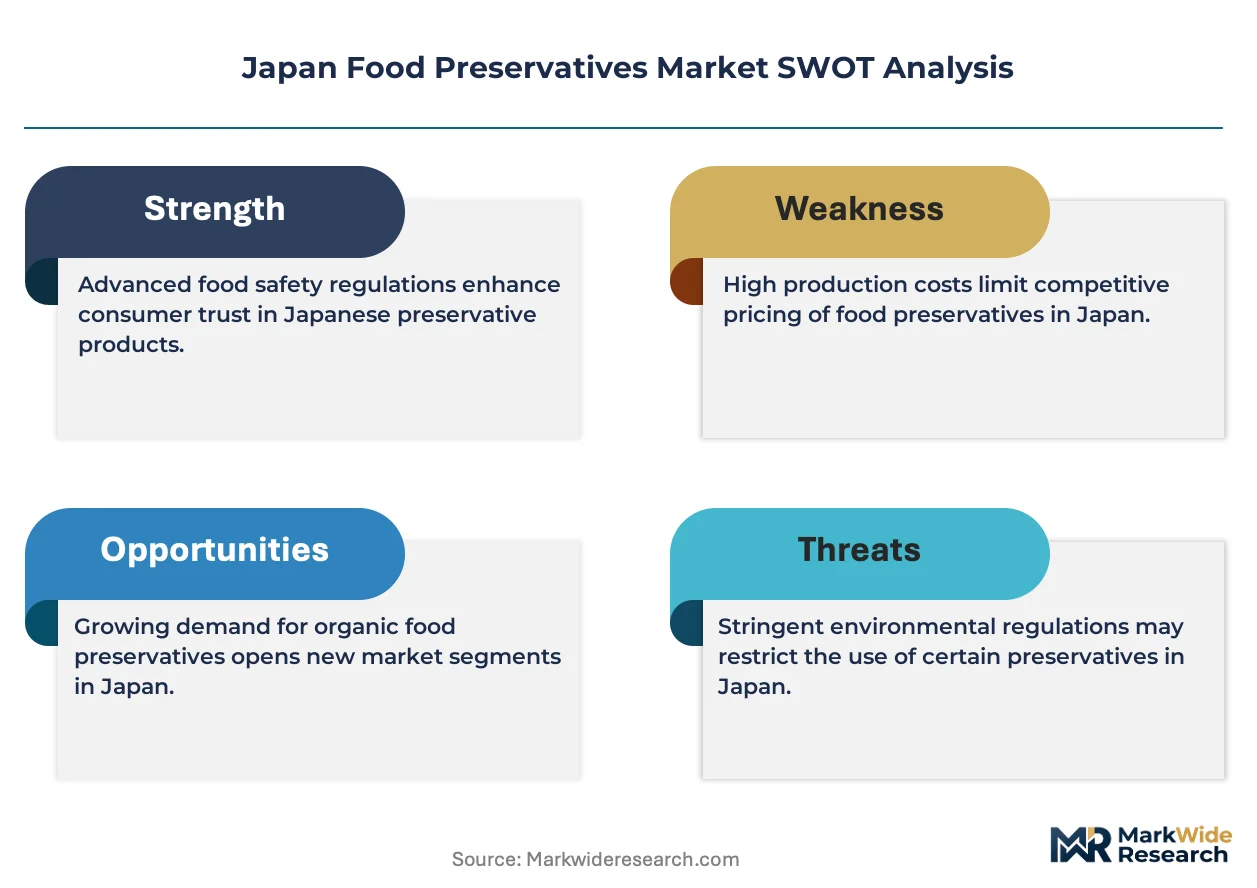
Volume-discount tiering separates premium natural preservatives certified under JIS standards from standard synthetic grades and economy bulk blends. Price differentiation hinges on METI green procurement tax eligibility and PMDA dossier completeness, with certification-grade products commanding substantial premiums. Cost compression in the economy tier is intensifying because Chinese citric acid dominance exposes Japanese buyers to single-source risk. Retail chains exhibit the highest price sensitivity, while premium beverage companies prioritize clean-label compliance over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites bulk chemical shipments from Rotterdam and Shanghai to the Port of Tokyo, creating a logistics chokepoint for European fermentation-derived inputs. Supply concentration rests on China for citric acid, the Netherlands for bio-based sorbate precursors, and domestic Japanese amino acid fermentation capacity. Raw material dependencies include corn and tapioca starch for bio-sorbates, phosphoric acid for phosphate production, and fermentation substrates for natural antimicrobials. Single-source vulnerability in Chinese citric acid exposes formulations to disruption. Distribution runs through dedicated procurement desks at Kanto trading houses serving Saitama and Chiba manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as METI's Food Labeling Act amendments splinter demand between clean-label reformulators and cost-optimized legacy processors, creating distinct niche supply positions.
For Market Incumbents: Shield market position by accelerating backward integration into fermentation substrate production to offset sorbitol feedstock volatility, while securing PMDA dossier extensions for novel natural preservatives before approval bottlenecks tighten. Priority lever: encapsulation technology capacity in Chiba prefecture to capture single-serve packaging demand. For New Entrants and Emerging Players: Anchor in Kansai's underpenetrated Osaka-Kobe corridor, where sauce manufacturers lag Tokyo in clean-label adoption by 24 months. Target mid-tier processors seeking reformulation partnerships for METI compliance without premium pricing. Go-to-market angle: fermentation-derived antimicrobial blends with expedited JIS certification support. For Investors and Strategic Acquirers: Fermentation specialists with established PMDA dossiers and captive amino acid production represent the highest-conviction acquisition archetype for the 5-10 year horizon. Signal to watch: PMDA novel food additive review timeline compression indicating regulatory pathway maturation for plant-derived antimicrobials.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Substrates | Captive corn and tapioca starch supply insulates Corbion and Ajinomoto from commodity volatility. |
| Encapsulation Technology Scale-Up | Liposome format deployment in Saitama pilot plants reduces thermal degradation losses for beverage clients. |
| JIS Certification Fast-Track Programs | Expedited 18-month purity testing timelines unlock mid-tier processor procurement decisions. |
| Kansai Regional Partnership Expansion | Osaka-Kobe sauce manufacturer relationships capture 24-month clean-label adoption window. |
| PMDA Dossier Extension Investment | Novel natural preservative approvals secure multi-year competitive moats against unqualified imports. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI regulatory filings, PMDA safety assessment databases, and JIS standards documentation. Primary interviews engaged formulation chemists at Kanto beverage manufacturers, procurement leads at Osaka-Kobe sauce processors, and technical directors at fermentation-derived preservative suppliers. Secondary sources included Food Sanitation Act amendment records, Consumer Affairs Agency labeling guidance, and customs trade data on citric acid and sorbate imports. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, and source segments.
Segmentation dimensions modeled encompass product type, end user industry, physical formulation, and raw material provenance across the projection horizon. CAGRs derived from volume-weighted average growth trajectories calibrated to METI policy implementation timelines and PMDA review cycle assumptions. Forecast inputs incorporated Kanto manufacturing density metrics, Kansai adoption lag coefficients, and encapsulation technology penetration curves.
Material uncertainties — PMDA novel additive approval delays, sorbitol feedstock price shocks, and METI enforcement intensity variations — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway maturation and clean-label demand elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Brazil Food Emulsifiers Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Monoglyceride Market