
 Phosphated Distarch Phosphate Market | 2026-2036
Phosphated Distarch Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphated Distarch Phosphate Market Analytics
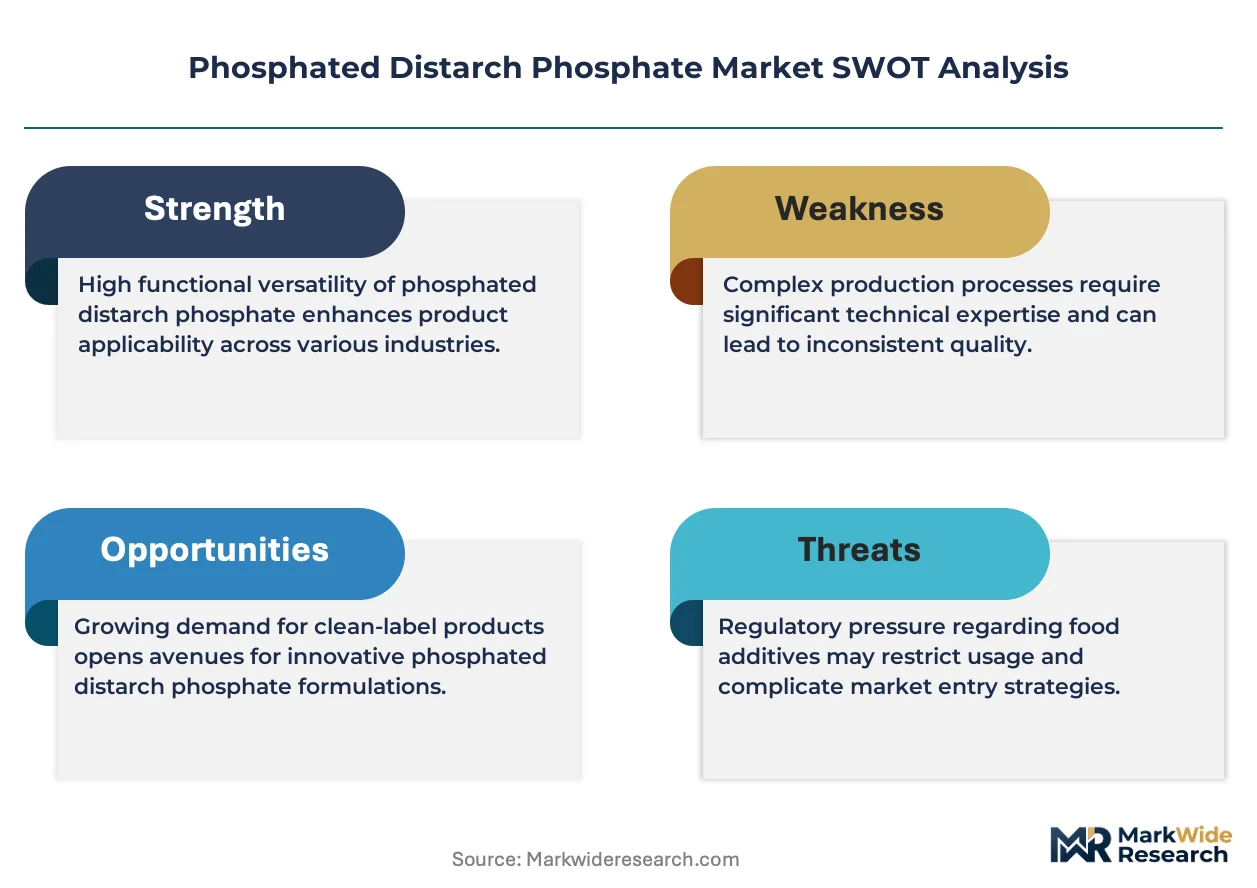
Consolidation among multinational food manufacturers is restructuring procurement patterns for phosphated distarch phosphate, as large buyers centralize ingredient sourcing across fewer approved supplier lists. Roquette Frères leverages its European potato starch vertical to sustain supply security for frozen food clients. Ingredion Incorporated anchors North American demand through its specialty ingredient portfolio, while Cargill Incorporated competes on global grain sourcing scale.
Phosphated distarch phosphate is a chemically modified starch produced by cross-linking starch with sodium trimetaphosphate or phosphorus oxychloride, yielding resistance to high temperature, acid, and shear stress during industrial processing. Food grade formulations dominate volume demand as bakery and dairy processors require stable viscosity under retort conditions. Industrial grade applications in adhesives and textiles represent a smaller but growing segment where phosphate cross-linking imparts film-forming durability. Pharmaceutical grade supply occupies higher margin tiers as excipient purity standards tighten across regulated markets.
FDA food additive regulations and EFSA re-evaluations of phosphate exposure limits are reshaping formulation disclosure requirements and maximum usage levels in processed foods. China's SAMR implements GB standards for modified starch labeling that affect import compliance for foreign suppliers. Stakeholders must monitor evolving phosphate intake assessments from WHO and national health agencies to anticipate reformulation mandates ahead of regulatory publication cycles.
Market Dynamics
Cross-border regulatory divergence on phosphate additive safety thresholds is fragmenting formulation standards and forcing manufacturers to maintain parallel product portfolios for different compliance jurisdictions.
Growth Catalysts
- Clean-label reformulation mandates:EFSA's tightened phosphate exposure assessments are compelling European food processors to source modified starches with enhanced stability at lower usage rates.
- Retort processing expansion:Asia-Pacific dairy and ready-meal manufacturers are adopting phosphated distarch phosphate to maintain viscosity under extreme heat and acid conditions.
- India:The country's snack manufacturing corridor is scaling production of extruded and fried products requiring shear-resistant starch systems.
Market Restraints
- Phosphate raw material volatility:Sodium trimetaphosphate and phosphorus oxychloride prices fluctuate with fertilizer industry demand cycles and energy input costs.
- Supplier concentration risk:European potato starch supply channels face seasonal crop variability and competing bioethanol offtake.
- Natural starch substitution:Unmodified tapioca and rice starches with label-friendly positioning capture share in premium clean-label segments.
Strategic Opportunities
- Pharmaceutical excipient tier:Tightening purity standards in regulated markets create margin expansion for USP-grade phosphated distarch phosphate production.
- China's GB standard alignment:Foreign suppliers achieving SAMR compliance certification gain preferential access to processed food import channels.
- Textile sizing convergence:Phosphate cross-linking durability properties are penetrating technical textile finishing applications beyond traditional food uses.
Industry Challenges
- Regulatory intelligence staffing:Manufacturers require dedicated personnel to track simultaneous EFSA, FDA, and SAMR evaluation timelines and draft guidance documents.
- Dual certification capex:Separate production lines for food-grade and pharmaceutical-grade output demand redundant processing equipment and quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphated Distarch Phosphate Market |
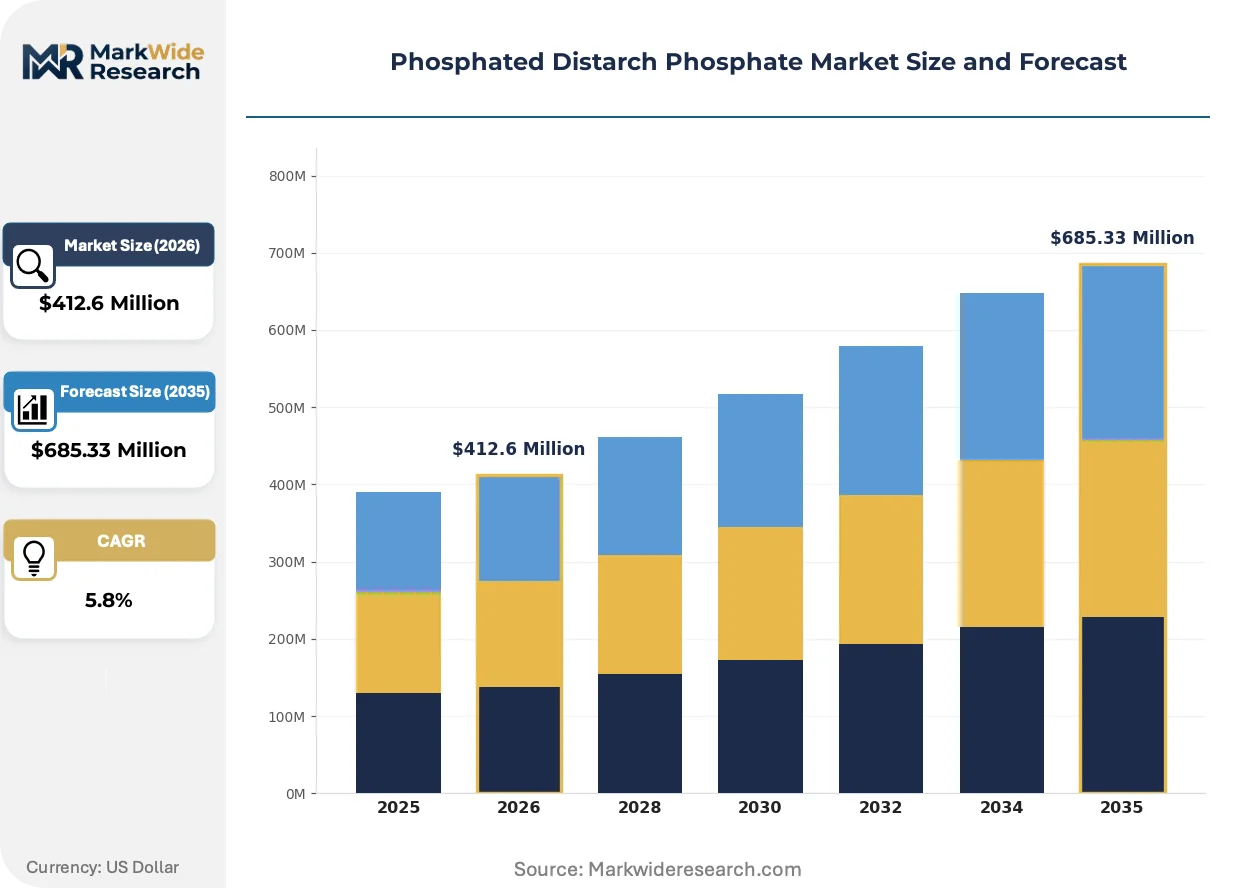
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Food Processing, Personal Care, Pharmaceutical, Agriculture End User: Food Manufacturers, Cosmetic Companies, Healthcare Providers, Agricultural Firms Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Roquette Frères, Avebe U.A, Ingredion Incorporated, Agrana Beteiligungs-AG, China Essence Group Ltd., Tate & Lyle PLC, Archer-Daniels-Midland Co., Emsland Group, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphated Distarch Phosphate Market Evolving Landscape
Process intensification and digital quality control systems are compressing development cycles for modified starch variants while regulatory transparency tools reshape how buyers verify supplier compliance credentials.
Enzyme-assisted phosphorylation is modularizing traditional chemical cross-linking protocols. Bakery and dairy processors in Germany and Japan are piloting these systems to reduce phosphate residual levels while maintaining functional performance. The technology is modularizing equipment footprints and enabling smaller-batch production economics previously unavailable to mid-scale manufacturers.
EFSA's ongoing re-evaluation of phosphate additives under the food improvement agent program is tightening maximum permitted levels across processed meat and dairy categories. European manufacturers are reformulating with reduced phosphate loads and enhanced disclosure labeling. Frozen food and ready-meal segments are most affected, with suppliers accelerating stability testing for alternative modified starch systems.
Direct supplier engagement models are displacing traditional ingredient distributor networks. Large North American and European food manufacturers are building approved supplier lists with audit rights and traceability requirements. This pattern is most visible in China's processed food corridor, where multinational buyers consolidate procurement through centralized quality agreements rather than spot-market purchasing.
Phosphated Distarch Phosphate Market Segmentation
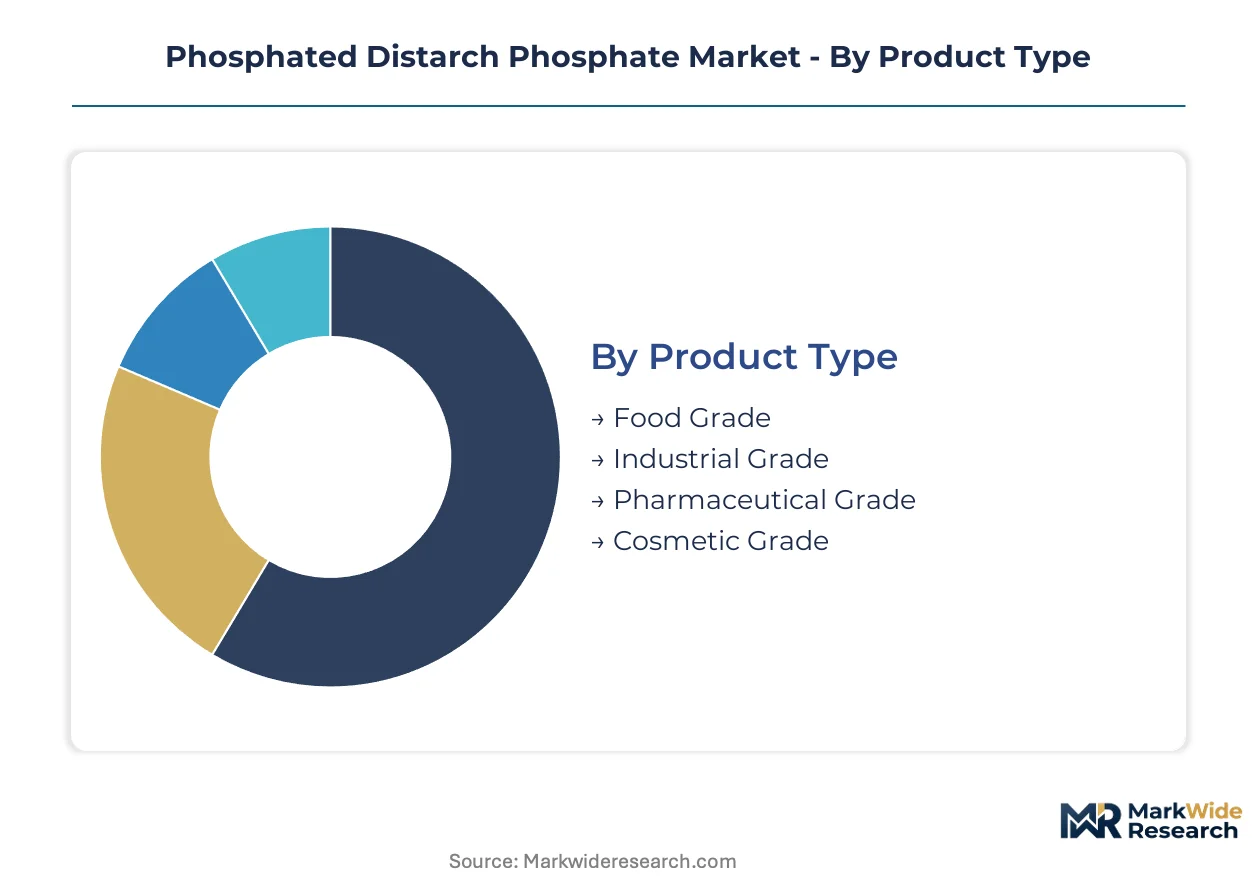
Segmentation in phosphated distarch phosphate reveals how functional requirements diverge across purity tiers and end-use specifications. Each grade commands distinct processing protocols, pricing bands, and regulatory compliance burdens that reshape supplier economics.
Product Type:
Standalone formulations dominate high-volume food and industrial applications, while embedded pharmaceutical and cosmetic grades integrate into complex multi-ingredient systems where excipient compatibility governs selection.
- Food Grade:Chemically modified starch cross-linked with sodium trimetaphosphate or phosphorus oxychloride to withstand retort temperatures, acid conditions, and high-shear processing. Bakery and dairy manufacturers in Germany and Japan source this grade for viscosity stability under extreme heat, though EFSA's tightened phosphate exposure limits are forcing reformulation at reduced usage rates.
- Industrial Grade:Lower-purity phosphorylated starch employed in adhesives, textiles, and paper sizing where film-forming durability outweighs food-safety certification costs. Technical textile finishers in China's manufacturing belt are adopting phosphate cross-linking for shear-resistant coating applications beyond traditional food channels.
- Pharmaceutical Grade:USP-compliant excipient material meeting tightening purity mandates across regulated markets.
- Cosmetic Grade:Refined specification for personal care emulsions and film-forming applications.
Food Grade leads volumes today; Pharmaceutical Grade is gaining share fastest.
Application:
Cost-tier stratification separates commodity-scale food processing from premium-margin pharmaceutical and personal care segments.
- Food Processing:Modified starches stabilize viscosity in retorted dairy, frozen ready-meals, and extruded snacks. Asia-Pacific processors in China's corridor and India's snack belt scale procurement as clean-label mandates intensify.
- Personal Care:Film-forming and emulsion-stabilizing functions in skincare and haircare formulations.
- Pharmaceutical:Tablet binders and controlled-release matrices where excipient purity standards are tightening across FDA and EMA jurisdictions.
- Agriculture:Seed coating and controlled-release fertilizer applications.
Food Processing anchors current demand; Pharmaceutical applications show the steepest expansion trajectory.
End User:
Customer-type concentration concentrates procurement power among multinational food manufacturers centralizing approved supplier lists.
- Food Manufacturers:Large-scale bakery, dairy, and ready-meal producers consolidating ingredient sourcing through centralized quality agreements rather than distributor networks.
- Cosmetic Companies:Formulators seeking label-friendly stabilizers for premium skincare lines.
- Healthcare Providers:Pharmaceutical manufacturers and contract development organizations.
- Agricultural Firms:Seed treatment and crop protection specialists.
Food Manufacturers dominate procurement volumes; Healthcare Providers are expanding specifications most aggressively.
Distribution Channel:
Supply concentration favors direct relationships for high-volume accounts, fragmenting only at smaller scale.
- Direct Sales:Multinational food and pharmaceutical manufacturers negotiate centralized procurement contracts with audit rights and traceability requirements, displacing traditional distributor networks in China's processed food corridor.
- Distributors:Regional intermediaries serving mid-scale manufacturers lacking volume for direct supplier engagement.
- Online Retail:E-commerce platforms for small-batch and specialty grade procurement.
- Specialty Stores:Niche channels for cosmetic and artisanal food ingredient buyers.
Direct Sales commands the largest transaction value; Online Retail is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's processed food corridor absorbs larger phosphate-modified starch volumes than Germany's frozen food belt, yet both face tightening additive disclosure mandates from their respective regulators.
China
Retort-ready meal manufacturers in the Yangtze River Delta scale procurement of cross-linked starches as clean-label reformulation accelerates. SAMR's GB standards for modified starch labeling now require batch-level phosphate content disclosure for import clearance. Shanghai and Suzhou-based dairy processors test reduced-phosphate formulations ahead of anticipated maximum level revisions.
Germany
Bakery and frozen food manufacturers source phosphate-cross-linked starches for viscosity stability under extreme heat and acid conditions. EFSA's ongoing re-evaluation of phosphate additives under the food improvement agent program tightens maximum permitted levels across processed meat and dairy categories. The Rhine-Ruhr industrial corridor hosts stability testing facilities accelerating alternative modified starch validation.
United States
Large-scale food manufacturers centralize ingredient sourcing through approved supplier lists with audit rights and traceability requirements. FDA food additive regulations reshape formulation disclosure requirements and maximum usage levels in processed foods. Midwest dairy processors and Southeast snack manufacturers negotiate multi-year supply agreements displacing traditional distributor networks.
India
Extruded and fried snack producers in Maharashtra and Gujarat scale shear-resistant starch procurement as production capacity expands. FSSAI notification requirements for modified starch labeling affect import compliance timelines for foreign suppliers. The Mumbai-Pune manufacturing belt concentrates new ready-to-eat production lines requiring retort-stable thickeners.
Japan
Enzyme-assisted phosphorylation pilot programs in Kansai region dairy and bakery facilities reduce phosphate residual levels while maintaining functional performance. METI guidance on food additive transparency pressures manufacturers toward enhanced disclosure labeling. Osaka-based processors test smaller-batch production economics previously unavailable to mid-scale manufacturers.
Phosphated Distarch Phosphate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across supply security and formulation customization vectors. The market structure consolidates around three to five multinational ingredient suppliers controlling majority volume, with regional specialists capturing niche certification tiers. Strategic archetypes include European potato starch verticals, North American grain-based diversified portfolios, and Asian tapioca-centric regional players. Competitive moves concentrate on backward integration into raw starch supply and pharmaceutical-grade certification capacity expansion.
Among European potato starch specialists, Roquette Frères and Avebe U.A occupy positions exemplifying supply security strategies for frozen food clients. Ingredion Incorporated anchors North American demand through specialty ingredient portfolio breadth. Cargill Incorporated sits within the grain-sourcing scale tier competing on global agricultural commodity integration.
| Leading Market Players |
|---|
| Roquette Frères |
| Avebe U.A |
| Ingredion Incorporated |
| Agrana Beteiligungs-AG |
| China Essence Group Ltd. |
| Tate & Lyle PLC |
| Archer-Daniels-Midland Co. |
| Emsland Group |
| Cargill Incorporated |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between pharmaceutical USP standards and industrial commodity tiers compresses margin structures at the bottom while expanding premium capture at the top, with supply chain configurations tracking this bifurcation through dedicated production lines and segregated logistics networks.
Pricing Analysis
Capacity additions in China's modified starch corridor are reshaping price floors for standard food-grade material, while European potato starch verticals defend premium positioning through supply security guarantees. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects purity certification costs and batch-level traceability investments. Price differentiation centers on EFSA compliance documentation and SAMR import clearance protocols, with European buyers least sensitive due to reformulation urgency and Asian commodity processors most responsive to spot-market swings. Cost compression in standard food-grade material intensifies as Chinese manufacturers scale enzymatic phosphorylation capacity.
Supply Chain Analysis
Pharmaceutical-grade qualification gating through USP and EP certification creates supply exclusivity that industrial-grade channels bypass entirely. Raw material flows concentrate in the Netherlands, Germany, and China for potato and tapioca starch feedstocks, with sodium trimetaphosphate and phosphorus oxychloride sourcing anchored in Chinese and German chemical manufacturing clusters. Supply chain risk centers on European potato crop variability and competing bioethanol offtake that diverts starch supply. Distribution runs through direct procurement contracts for multinational food and pharmaceutical manufacturers, with regional distributors serving mid-scale accounts lacking volume for centralized quality agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade certification tiers and enzyme-assisted production technologies that reduce phosphate residuals while commanding premium positioning.
For Market Incumbents: Deploy backward integration into captive potato and tapioca starch supply to insulate against European crop volatility and bioethanol competition. Secure dual FDA-EFSA certification capacity ahead of anticipated maximum level revisions, while consolidating distributor relationships into direct procurement contracts with audit rights to defend against Asian price competition. For New Entrants and Emerging Players: Begin with pharmaceutical excipient white space in regulated markets where USP-grade supply concentration creates entry vulnerability. Target India's expanding snack manufacturing belt with shear-resistant starch systems tailored to extruded product specifications, leveraging FSSAI notification timelines to establish import compliance credentials before multinational incumbents localize production. For Investors and Strategic Acquirers: Consolidation pressure builds where pharmaceutical-grade certification capex requirements exceed standalone returns for mid-scale European potato starch processors. Long-term viability favors acquisition targets with existing USP-grade capacity and SAMR compliance infrastructure, with the signal to watch being EFSA's final phosphate exposure limit determinations that would trigger accelerated reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Supply | Captive potato and tapioca sourcing insulates Roquette and Avebe against European crop variability and bioethanol competition. |
| Pharmaceutical-Grade Certification Expansion | USP and EP compliance capacity captures margin expansion as FDA and EMA tighten excipient purity mandates across regulated markets. |
| Enzyme-Assisted Phosphorylation Scale-Up | Modular production economics enable mid-scale manufacturers to reduce phosphate residuals while maintaining functional performance. |
| SAMR GB Standard Alignment | Foreign suppliers achieving China import clearance certification gain preferential access to Yangtze River Delta processed food channels. |
| Direct Supplier Engagement Models | Centralized procurement contracts with audit rights displace distributor networks in China's processed food corridor and India's snack belt. |
Research Methodology
Bottom-up food processing and pharmaceutical excipient modeling reconciled against top-down modified starch production tracking forms the analytical core. Primary interviews with plant managers at European potato starch facilities, procurement leads at Asia-Pacific dairy processors, regulatory affairs directors navigating EFSA and SAMR compliance, and technical R&D heads developing enzyme-assisted phosphorylation systems combined with secondary validation from customs trade data, GB standard filings, EFSA food improvement agent program documentation, and SEC 10-K disclosures from diversified ingredient suppliers.
Historical trendline analysis across food-grade, industrial-grade, and pharmaceutical-grade shipment patterns established baseline growth trajectories, with segmentation modeling across purity tier, end-use application, and regional regulatory cluster. CAGRs were derived from demand elasticity coefficients tied to clean-label reformulation mandates and retort processing expansion, incorporating phosphate raw material cost cycles and certification timeline delays as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unanticipated EFSA prohibition of phosphate additives, catastrophic European potato crop failure, and breakthrough natural starch substitutes achieving equivalent shear resistance. Forecasts reflect assumptions about regulatory evaluation timelines and import clearance processing speeds. Deviation in EFSA's final maximum permitted level determinations or SAMR's accelerated GB standard revision schedule would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
South Africa Anti Caking Agents Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Carob Bean Gum Market
Food Additives and Ingredients
Calcium Butyrate Market