
 Vietnam Food Additives Market | 2026-2036
Vietnam Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Food Additives Market Insights
China's additive manufacturing expansion is reshaping ingredient supply dynamics across Southeast Asia. Cargill Vietnam leverages its integrated starch and sweetener infrastructure to dominate local sourcing networks for bakery and beverage clients. Kerry Group sustains formulation partnerships with Vietnamese meat processors seeking clean-label alternatives. Ajinomoto Vietnam anchors the umami segment through its localized MSG and nucleotide production.
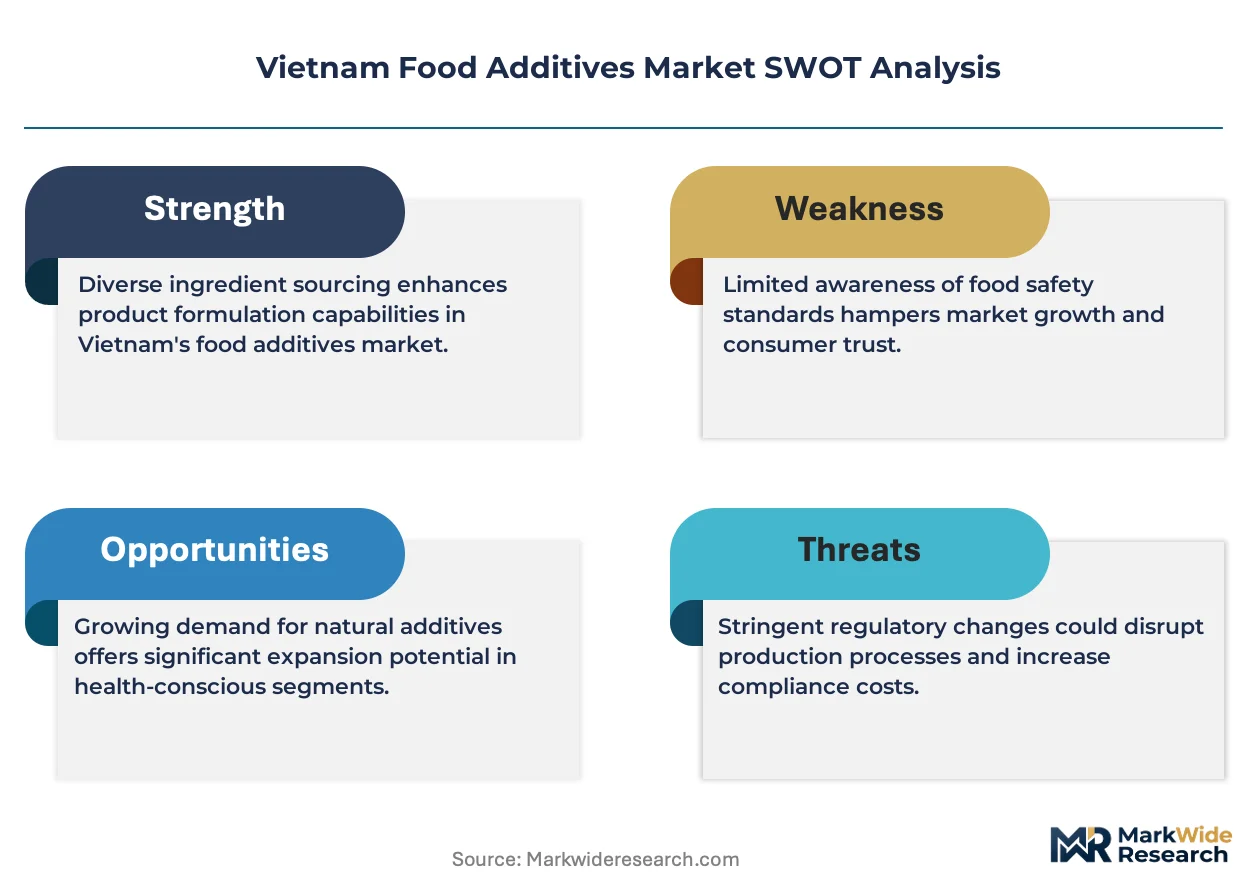
Food additives encompass chemical or natural substances incorporated into food products at concentrations typically below one percent by weight to preserve quality, enhance sensory attributes, or improve processing efficiency. These compounds serve industrial purposes including shelf-life extension, flavor modulation, color stabilization, and texture control in packaged and prepared foods. Preservatives command the largest share among product types due to Vietnam's tropical climate and limited cold-chain coverage, while flavor enhancers register the fastest structural growth as instant noodle and seasoning manufacturers scale output. Within applications, meat processing absorbs the highest additive volume per ton of finished product, whereas beverages offer superior margin pools for specialty emulsifiers and colorants.
Vietnam's Ministry of Health and the Vietnam Food Administration enforce additive standards aligned with Codex Alimentarius and ASEAN harmonization protocols, with BIS-equivalent local testing requirements for imported ingredients. The country's national food safety regulator mandates positive-list compliance and maximum usage limits that directly determine which suppliers qualify for domestic manufacturing contracts. Stakeholders must monitor pending revisions to labeling rules and the pace of mutual recognition agreements with EU and Japanese standards bodies, as these will reshape import substitution opportunities and local certification costs.
Market Dynamics
Urbanization and dietary westernization are compressing the gap between raw commodity consumption and processed food penetration across Vietnamese households. The Ministry of Health's Circular 27/2012/TT-BYT continues tightening purity benchmarks, forcing domestic suppliers to rebuild formulation pipelines around cleaner-label portfolios.
Growth Catalysts
- Convenience food proliferation:Instant noodle and ready-to-eat meal manufacturers in Ho Chi Minh City are scaling production lines, pulling demand for flavor enhancers and texture modifiers into double-digit expansion territory.
- Circular 27/2012/TT-BYT compliance deadlines:The Ministry of Health's additive management framework is accelerating supplier consolidation as smaller formulators lack capital to meet upgraded testing and documentation requirements.
- Mekong Delta processing cluster concentration:Meat and seafood processors in the southern industrial corridor are absorbing record additive volumes per ton of finished product, driven by export contract specifications for shelf-stable protein products.
Market Restraints
- Cold-chain infrastructure gaps:Tropical climate conditions and limited refrigerated logistics force heavy reliance on chemical preservatives, constraining clean-label migration timelines for cost-sensitive domestic brands.
- Import dependency for specialty ingredients:High-performance emulsifiers and natural colorants concentrate in Chinese and Thai supply bases, exposing Vietnamese formulators to cross-border tariff volatility and customs clearance friction.
- Positive-list rigidity:The Vietnam Food Administration's restrictive approved-additive catalog blocks rapid adoption of novel preservation technologies already cleared in EU and Japanese jurisdictions.
Strategic Opportunities
- Central Highlands underpenetration:Da Nang and surrounding provinces host nascent beverage processing capacity with minimal local additive supplier presence, creating first-mover territory for regional distribution networks.
- Clean-label nucleotide substitution:Yeast extract and fermented vegetable-derived umami compounds are gaining technical validation as MSG alternatives, opening reformulation contracts with health-positioned seasoning brands.
- ASEAN harmonization protocols:Mutual recognition agreements under negotiation with Singapore and Thailand standards bodies promise streamlined cross-border certification, reducing time-to-market for imported specialty ingredients.
Industry Challenges
- Food safety auditor scarcity:Qualified third-party certification bodies capable of conducting Circular 27-compliant facility audits operate primarily in Hanoi and Ho Chi Minh City, creating inspection backlogs for provincial manufacturers.
- Legacy ERP integration:Mid-scale processors in the Mekong Delta rely on fragmented inventory systems that cannot trace additive lot codes through multi-step production, complicating recall readiness and regulatory documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Food Additives Market |
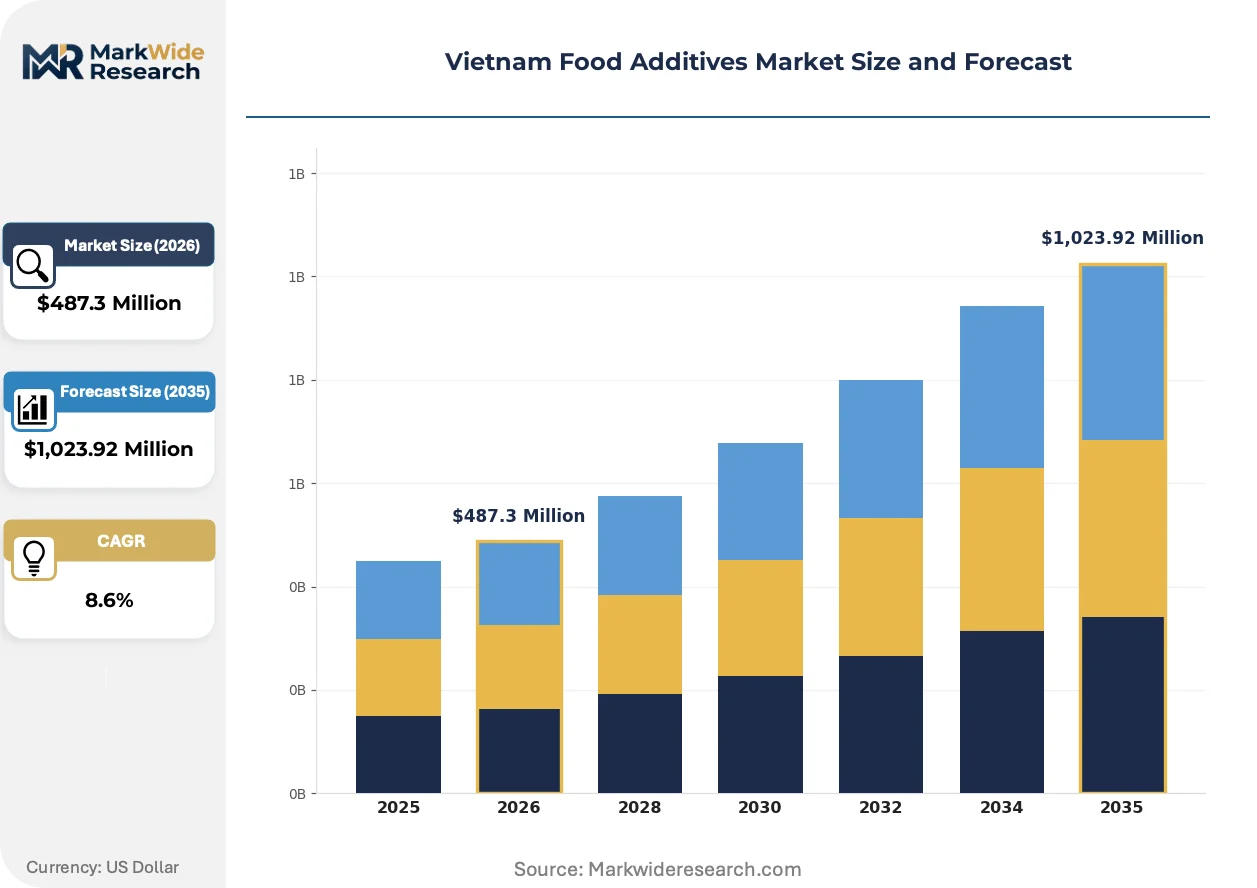
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Flavor Enhancers, Colorants, Emulsifiers Application: Meat Processing, Dairy Products, Bakery, Beverages Form: Powder, Liquid, Granular, Gel End User: Food Manufacturers, Restaurants, Retailers, Catering Services |
| Companies Covered | Tate & Lyle PLC, Kerry Group, Cargill Vietnam, DSM Nutritional Products, Ingredion Vietnam, Ajinomoto Vietnam, Archer Daniels Midland Company, Fufeng Group, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Food Additives Market Trends and Innovations
Digital traceability systems and fermentation-derived ingredient platforms are compressing the traditional gap between synthetic additive performance and clean-label positioning. Vietnamese processors face simultaneous pressure to upgrade documentation infrastructure and reformulate around consumer-perceived natural alternatives.
Blockchain-enabled supply chain verification is digitizing lot-level tracking from raw material receipt through finished goods distribution. Beverage and dairy processors in the southern industrial zone are piloting these platforms to preempt EU import documentation requirements. The technology is digitizing audit preparation workflows, compressing the labor hours previously consumed by paper-based traceability systems.
The Ministry of Health's pending revisions to labeling disclosure rules are mandating quantitative ingredient declarations and allergen callouts in Vietnamese language. Domestic seasoning and sauce manufacturers face the steepest compliance burden, as multi-component formulations require extensive packaging redesign. Smaller processors are responding by simplifying recipes to reduce label complexity and printing costs.
Direct procurement from ingredient manufacturers is displacing traditional distributor intermediaries among large-scale meat processors in Binh Duong and Dong Nai provinces. Volume concentration among the top ten protein processors enables contract negotiations that bypass the 15-20% markups typical of regional chemical traders. This pattern concentrates most visible in export-oriented facilities where price competitiveness determines contract renewal.
Vietnam Food Additives Market Segmentation
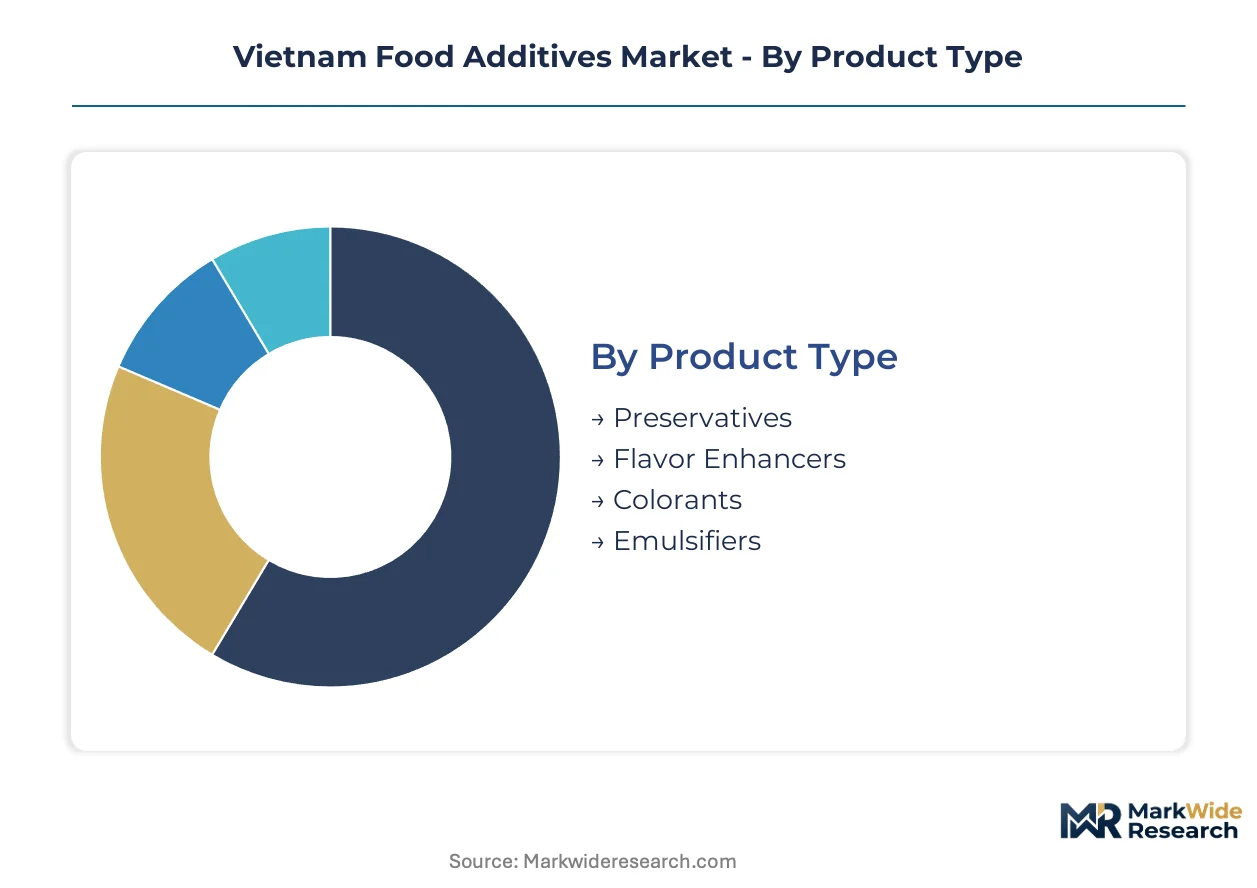
Segmentation in Vietnam's food additives market reveals how tropical climate conditions, export compliance requirements, and urban consumption patterns create divergent demand profiles across product categories. Each dimension exposes distinct procurement behaviors and margin structures that suppliers must navigate.
Product Type:
Maturity varies sharply across this category, with legacy chemistries defending volume positions while fermentation-derived alternatives capture reformulation contracts.
- Preservatives:Sorbates, benzoates, and propionates dominate formulation decks for ambient-stable noodles and sauces. Ho Chi Minh City-based instant food manufacturers absorb the highest volumes per production line due to limited cold-chain penetration across the Mekong Delta.
- Flavor Enhancers:MSG, nucleotides, and yeast-derived compounds intensify umami perception in processed proteins and seasoning blends. Meat processors in Binh Duong province are accelerating nucleotide adoption to meet clean-label export specifications for Japanese retail channels.
- Colorants:Synthetic azo dyes and natural carotenoids stabilize visual appeal in beverages and confectionery.
- Emulsifiers:Lecithin and mono-diglycerides maintain texture in dairy alternatives and baked goods.
Preservatives handle the majority of throughput; flavor enhancers are the fastest mover on share.
Application:
Cost tier differentiation separates commodity-driven segments from specialty formulation opportunities with superior margin retention.
- Meat Processing:Phosphate blends, curing salts, and antioxidant systems extend shelf life in sausages and dried seafood. Export-oriented facilities in Dong Nai province consume the highest additive volumes per ton of finished product to satisfy EU and Japanese microbiological standards.
- Beverages:Acidulants, stabilizers, and clouding agents maintain sensory consistency in tropical-ready drinks. Da Nang's emerging bottling cluster is pulling demand for natural colorants and clean-label emulsifiers as health-positioned brands enter convenience retail.
- Dairy Products:Stabilizers and preservatives support ambient yogurt and condensed milk production.
- Bakery:Emulsifiers and anti-staling agents control crumb structure in packaged bread.
Meat processing absorbs the greatest additive density; beverages are climbing the fastest on premium ingredient penetration.
Form:
Supply concentration in Ho Chi Minh City and Hanoi determines which physical formats dominate procurement patterns.
- Powder:Free-flowing crystalline and spray-dried formats dominate high-volume seasoning and flour fortification. Central Highlands milling operations prefer powder delivery for mechanical dosing compatibility and reduced moisture sensitivity during monsoon storage.
- Liquid:Pumpable concentrates enable precise injection in processed meat and beverage syrup production. Mekong Delta seafood processors favor liquid smoke and acid blends for uniform distribution through brine systems.
- Granular:Coarse particles reduce dust exposure in manual handling environments.
- Gel:Thixotropic systems support specialized confectionery and sauce applications.
Powder handles the majority of throughput; liquid is gaining share fastest in automated processing lines.
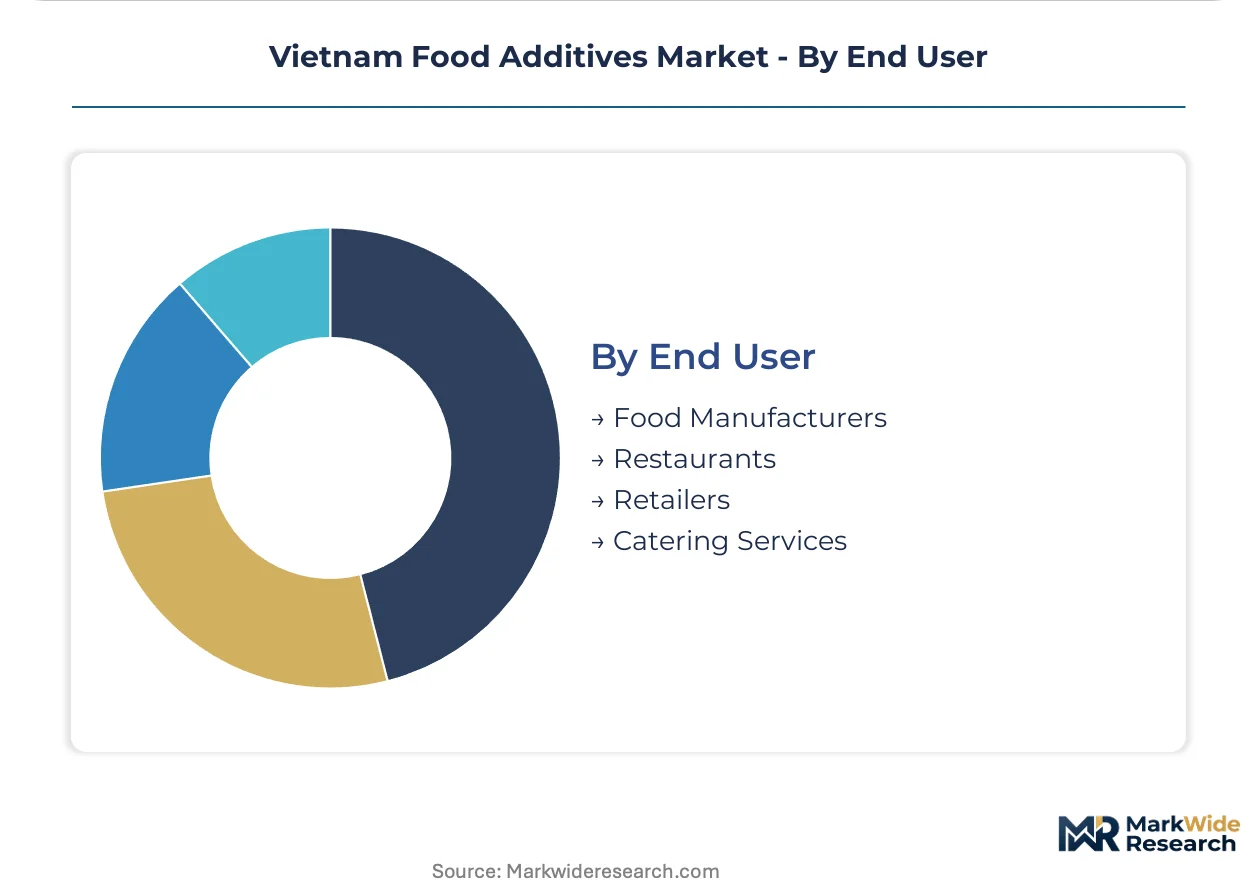
End User:
Customer type dictates packaging scale, technical service intensity, and documentation requirements.
- Food Manufacturers:Industrial-scale bakeries, noodle plants, and protein processors purchase bulk quantities with certificate-of-analysis requirements. The top ten meat and seafood exporters in southern Vietnam concentrate procurement through direct manufacturer contracts, bypassing traditional distributor markups.
- Restaurants:Commercial kitchens and chain operators source blended seasonings and preparation aids. Ho Chi Minh City's quick-service restaurant expansion is pulling demand for pre-mixed flavor systems that reduce kitchen labor and variability.
- Retailers:Supermarket private labels and specialty stores stock consumer-packaged additives.
- Catering Services:Institutional kitchens and event operators purchase mid-scale formats.
Food manufacturers handle the majority of throughput; restaurants are expanding most quickly on foodservice channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Additive supply concentrates in the southern industrial corridor, where Ho Chi Minh City and the Mekong Delta host the bulk of formulation demand. Provincial clusters outside this core remain underpenetrated, creating divergent procurement costs and compliance timelines across Vietnamese territory.
Ho Chi Minh City Metro
Instant noodle and beverage manufacturers drive the highest additive throughput in the southern metro. Circular 27/2012/TT-BYT enforcement has forced facility upgrades among Binh Duong and Dong Nai processors seeking export certification. The Thu Duc industrial zone anchors distribution networks for preservatives and flavor systems serving both domestic retail and ASEAN re-export channels.
Mekong Delta Provinces
Seafood and meat processors in An Giang, Long An, and Tien Giang absorb phosphate blends and curing systems for shelf-stable protein exports. The Vietnam Food Administration maintains regional testing laboratories in Can Tho, reducing certification transit times for delta-based formulators. Cold-chain gaps force heavier preservative loading than northern facilities serving refrigerated distribution networks.
Central Highlands
Da Nang and surrounding provinces host nascent beverage bottling capacity with minimal local additive supplier presence. The Ministry of Health's provincial inspection offices lack the audit capacity of Hanoi and Ho Chi Minh City, stretching compliance timelines for new market entrants. Coffee and tea processors are pulling initial demand for natural colorants and clouding agents as health-positioned brands enter convenience retail.
Hanoi and Northern Delta
Confectionery and dairy manufacturers in Bac Ninh and Hung Yen provinces source emulsifiers and stabilizers through distributor networks rather than direct manufacturer contracts. The northern industrial zone maintains lower additive volumes per ton of finished product due to refrigerated logistics penetration into China-bordering distribution channels. State-owned dairy processors anchor demand for shelf-life extension systems in ambient yogurt production.
Vietnam Food Additives Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in single-ingredient manufacturing. The Vietnamese market structures around three tiers: multinational formulators with regional technical service centers, Asian commodity producers with cost-optimized bulk supply, and domestic distributors bridging specification gaps for mid-scale processors. Competitive moves concentrate on direct procurement displacement of distributor intermediaries and backward integration into fermentation-derived ingredient platforms.
Among multinational ingredient suppliers, Cargill Vietnam and Kerry Group exemplify the integrated platform archetype, combining local starch processing with formulation partnerships. Ajinomoto Vietnam anchors the nucleotide and umami segment through localized production infrastructure. Tate & Lyle PLC and DSM Nutritional Products occupy positions in specialty sweetener and nutritional premix supply, respectively, serving beverage and dairy reformulation contracts.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Kerry Group |
| Cargill Vietnam |
| DSM Nutritional Products |
| Ingredion Vietnam |
| Ajinomoto Vietnam |
| Archer Daniels Midland Company |
| Fufeng Group |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese fermentation-derived ingredient plants is compressing export pricing into Vietnam while simultaneously forcing Ho Chi Minh City distributors to absorb inventory risk through extended stocking commitments. This utilization imbalance rewards bulk purchasers with volume discounts but squeezes margin buffers for mid-scale formulators lacking direct manufacturer relationships.
Pricing Analysis
Circular 27/2012/TT-BYT dictates the pricing tier structure across the Vietnamese food additives market, separating Codex-certified imports from locally tested alternatives. Pricing stratifies across premium certified, standard compliant, and economy unverified tiers based on documentation depth and laboratory validation status. Cost compression in the economy tier is intensifying because provincial processors face working capital constraints for certification upgrades. Food manufacturers with export contracts demonstrate the lowest price sensitivity, while domestic seasoning brands serving cost-conscious retail channels exhibit acute elasticity.
Supply Chain Analysis
Extended payment terms from Chinese and Thai ingredient manufacturers are financing inventory float across Mekong Delta distributor networks. Geographic supply concentration rests on China for high-performance emulsifiers and natural colorants, Thailand for modified starches and acidulants, and domestic fermentation capacity for MSG and nucleotides. Raw material dependencies include corn-derived dextrose, palm-based emulsifier feedstocks, and phosphate rock for meat processing blends. Single-source vulnerability runs through Chinese specialty ingredient channels subject to customs clearance friction. Distribution runs through Ho Chi Minh City chemical traders with satellite stocking points in Can Tho and Da Nang.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's food additives market represents an early-cycle expansion story as clean-label reformulation penetrates export-oriented protein processing faster than domestic retail channels.
For Market Incumbents: Entrench formulation partnerships with Mekong Delta meat processors by embedding technical service teams directly into client R&D facilities. Deepen backward integration into fermentation-derived umami platforms to defend margin position against Chinese MSG price volatility. Prioritize Circular 27/2012/TT-BYT pre-certification investments to capture supplier consolidation tailwinds as smaller formulators exit. For New Entrants and Emerging Players: Build out regional distribution infrastructure targeting Da Nang and Central Highlands beverage processors currently served by Hanoi-based intermediaries with 72-hour delivery cycles. The clean-label nucleotide substitution segment offers the most penetrable white space given technical validation gaps among domestic yeast extract suppliers. Lead with direct procurement models that bypass traditional distributor markups through volume pooling arrangements among mid-scale processors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-based ingredient manufacturing as clean-label capacity expansion requires dedicated bioreactor infrastructure rather than contract tolling. Long-term viability over a five-to-ten year horizon favors platform integrators with backward integration into raw material processing rather than pure-play distributors. Monitor ASEAN mutual recognition agreement negotiations as the critical inflection signal for cross-border certification cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive supply of yeast-derived umami compounds reduces exposure to Chinese MSG price cycles. |
| Direct Procurement Platform Launch | Bypassing Ho Chi Minh City chemical traders captures 15-20% margin compression for meat processors. |
| Circular 27 Pre-Certification Investment | Early compliance with Ministry of Health purity benchmarks locks out undercapitalized domestic competitors. |
| Central Highlands Distribution Network Buildout | First-mover stocking points in Da Nang exploit beverage processing capacity expansion with minimal local supply. |
| Blockchain Traceability System Deployment | Lot-level digitization preempts EU import documentation requirements for seafood exporters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food manufacturing procurement directors, Ministry of Health regulatory inspectors, Mekong Delta distributor principals, and technical R&D managers at seasoning compounders. Secondary validation drew from Vietnam Food Administration circulars, ASEAN harmonization protocol documents, customs import records for additive HS codes, and facility audit reports from certified third-party bodies. Bottom-up volume estimates from individual processor consumption patterns were triangulated against top-down trade flow analysis.
Calibration across the projection horizon applied segment-specific growth assumptions for preservatives, flavor enhancers, colorants, and emulsifiers, with additional granularity by application in meat processing, beverages, dairy, and bakery channels. CAGRs were derived from elasticity-adjusted consumption models incorporating urbanization rates, export contract specifications, and regulatory compliance cost trajectories. Forecast inputs included cold-chain infrastructure development timelines and ASEAN mutual recognition agreement implementation schedules.
Stress conditions across raw material price volatility, customs clearance disruption, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about substitution elasticities and certification cost structures. Macroeconomic contraction, accelerated EU-Japan mutual recognition, or breakthrough clean-label preservation technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
South America Food Additives Market
Food Additives and Ingredients
Global Cereal Ingredients Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Africa Food Emulsifiers Market